

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
The Enterprise Resource Planning Software Market: Strategic Trends and Commercial Opportunities in a Transforming Landscape
Market Snapshot: Scale, Trajectory, and Structural Pressure Points
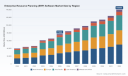
The enterprise resource planning (ERP) software market has transitioned from a mature, incremental-growth category into a structurally expanding ecosystem. Total revenue crossed the 77 billion-dollar threshold in 2025, building on a decade-long expansion that saw the market scale from roughly 40 billion in 2020. The forward trajectory is notably steep, with projected revenue reaching 140 billion by 2032. A compound annual growth rate of 9.5 percent over the 2026 to 2032 period signals that ERP is no longer a back-office utility but a central operating platform where finance, supply chain, human capital, and customer operations converge. The pace of expansion reflects a market that is simultaneously consolidating around cloud delivery, broadening its functional scope, and absorbing new demand from mid-market and cross-industry adopters who previously viewed integrated suites as out of reach.
Beneath the headline growth, three structural challenges are reshaping how buyers evaluate ERP investments and how vendors compete for wallet share. The first is the tension between speed-to-value and implementation complexity. Cloud deployments have lowered the initial capital barrier by removing hardware procurement and shifting costs into subscription and hosting models, but the long-term cost curve depends heavily on configuration discipline, integration maturity, and change management. For smaller enterprises, customization concerns, training requirements, and upgrade costs remain recurring friction points that can erode the promised efficiency gains of a modern platform. The second challenge is regulatory and compliance fluidity. Cloud ERP systems must continuously align with data protection, industry-specific, and financial reporting obligations, while built-in automatic updates create a moving target for internal audit and control teams. Regulatory signals in 2025, including deregulatory proposals aimed at reducing compliance burdens for data and AI obligations in cloud environments, introduce both relief and uncertainty, as the exact scope and timing of obligations continue to evolve. The third challenge is organizational readiness for AI-infused workflows. ERP vendors are embedding intelligent automation, predictive insights, and agent-based capabilities across finance, procurement, and supply chain functions, yet enterprises often lack the data governance, process standardization, and skills infrastructure required to extract measurable value. Without that foundation, AI features risk becoming superficial differentiators rather than operational levers.
For executives and planners, the strategic implication is clear: ERP is becoming a multi-year operating decision rather than a one-time software purchase. The winners will be organizations that treat platform selection as a capabilities investment, align deployment scope with process maturity, and build the governance needed to sustain compliance and continuous improvement.
Core Drivers Reshaping Demand and Vendor Behavior
Several interlocking forces explain why the ERP market is expanding at a pace that outstrips many traditional enterprise software categories. These drivers are not isolated; they reinforce each other and create distinct opportunities for organizations that can position ERP as an enabler of operational resilience and decision velocity.
Technology Innovation and Platform Convergence
The most visible driver is the convergence of cloud architecture, embedded analytics, and AI-enabled automation into a single operational fabric. Cloud ERP has moved from a deployment preference to the dominant delivery model, supported by subscription economics that reduce upfront infrastructure costs while enabling continuous updates. More importantly, the platform layer is increasingly intelligent. Recent product movements show vendors moving beyond dashboards and alerts toward agent-based tooling that can build, connect, and verify AI agents across HR, finance, and IT environments. This shift matters because it reframes ERP from a record-keeping system to an orchestration layer that can coordinate transactions, reconciliations, approvals, and exception handling with less manual intervention.
Accounting Software Market
The commercial impact is twofold. First, buyers can justify ERP investments on the basis of operational agility and reduced cycle times rather than pure cost displacement. Second, vendors are competing on ecosystem breadth, integration depth, and the ability to extend functionality through low-code or partner-built extensions. The practical takeaway is that organizations should evaluate platforms not only on core ledger and reporting strength, but also on how readily the system can absorb new workflows, connect to specialized applications, and support governed automation without creating brittle custom code.
Regulatory and Compliance Dynamics
Policy and regulatory environments are becoming both a constraint and a catalyst. Cloud ERP systems must navigate overlapping obligations related to data protection, financial reporting standards, and industry-specific controls. At the same time, vendors are consolidating compliance capabilities into the platform itself, with automatic updates and configuration controls designed to keep organizations aligned as rules change. This is particularly relevant for multinational enterprises and regulated industries, where manual remediation and fragmented systems can turn compliance into a recurring cost center.
Recent regulatory developments illustrate the direction of travel. In late 2025, European regulators signaled a deregulatory push intended to reduce compliance burdens associated with data and AI obligations in cloud ERP contexts. The implication is nuanced: reducing friction can accelerate adoption and lower the cost of governance, but the exact boundaries of reduced obligations and the timing of implementation remain important variables for procurement and risk teams. For decision-makers, the strategic lesson is to treat compliance not as a static checkbox but as a platform selection criterion, weighing how much regulatory upkeep can be absorbed by the vendor versus how much must remain inside the enterprise.
Demand-Side Shifts in Enterprise Behavior
Buyer behavior is changing as operational complexity rises and expectations for real-time visibility increase. Finance and accounting remain a foundational application area, but demand is broadening across human resources, supply chain management, customer relationship management, and inventory management. This expansion reflects a broader shift in how enterprises organize work: functional silos are increasingly undesirable because they slow decision-making, duplicate data entry, and weaken cross-functional accountability. Integrated suites are therefore attractive not because they eliminate specialized tools, but because they reduce fragmentation and create a shared data backbone for planning, execution, and control.
At the same time, the mid-market is a critical demand engine. Smaller organizations are adopting ERP at increasing rates, yet they encounter familiar implementation concerns around customization, training, and upgrade exposure. That dynamic is reshaping the vendor landscape, with some platforms emphasizing simplicity, rapid deployment, and modular adoption, while others continue to target complex, multi-entity, multi-currency environments. The commercial opportunity lies in matching platform scope to organizational maturity: enterprises that over-customize prematurely or underestimate change management often pay for it later in upgrade costs and adoption friction, while those that standardize first and extend later tend to realize value faster.
Cost Structure and Supply-Side Realities
Cost structure is evolving in ways that influence both adoption timing and vendor strategy. Cloud ERP implementations reduce upfront hardware expenditure, which lowers the barrier to entry and enables faster initial deployment. However, subscription and hosting fees persist over time, and total cost of ownership increasingly depends on integration work, data migration quality, user adoption, and the need for ongoing configuration support. In effect, the cost conversation has shifted from capital avoidance to lifecycle efficiency.
This shift is particularly important for procurement teams and finance leaders. The cheapest entry point is not always the lowest-risk path if the platform requires heavy customization or if internal teams lack the bandwidth to manage upgrades and extensions. Conversely, a platform with stronger out-of-the-box functionality and clearer upgrade paths may deliver better long-term economics, even if initial subscription pricing appears higher. The broader supply-side implication is that vendors are competing on implementation velocity, partner ecosystems, and the predictability of ongoing costs, not merely on feature count.
Competitive Positioning and the Evolving Vendor Landscape
The ERP market remains concentrated, with a relatively small group of large providers commanding a substantial share of total revenue. This concentration reflects the scale required to maintain broad functional coverage, global compliance support, and a mature partner ecosystem. At the same time, the landscape is not static. Consolidation, product divergence, and targeted specialization are all visible at once, creating a more nuanced competitive map than the traditional flagship-versus challenger framing suggests.
Large platform vendors have pursued strategies that emphasize ecosystem integration and cloud-native architectures. SAP continues to anchor its positioning around its S/4HANA and business one offerings, with modules spanning finance, supply chain, and manufacturing. Oracle has reinforced its Fusion Cloud ERP and NetSuite footprint, emphasizing finance, operations, and global supply chain capabilities. Microsoft has leaned into Dynamics 365 with AI-driven integrations across finance and supply chain, while also serving a broad base through Business Central. Workday has expanded its ERP scope around finance, HCM, and enterprise operations, increasingly highlighting AI agent capabilities as part of its differentiation. These players share a common strategic theme: they are positioning ERP as an integrated operating platform rather than a set of isolated modules, and they are investing heavily in cloud delivery, data continuity, and intelligent automation.
Alongside the large platforms, specialized and mid-market vendors continue to compete on industry fit, deployment flexibility, and total cost predictability. Infor focuses on cloud suites for manufacturing, distribution, and industry-specific scenarios. QAD and Epicor target manufacturing, distribution, and service-oriented environments with adaptive or kinetic-oriented ERP formulations. Sage maintains a strong presence in finance, accounting, and small-to-medium enterprise contexts, while Acumatica emphasizes flexible cloud ERP with AI-capable financial and operational management. Odoo offers an approach built around CRM, finance, inventory, and manufacturing with open-source options that appeal to organizations seeking modularity and extensibility. The diversity of these offerings matters because ERP value is highly context-dependent: a platform that excels in a complex multinational manufacturing environment may be overkill for a growing services firm, while a streamlined system may struggle in a heavily regulated multi-entity operation.
Recent market moves underscore how quickly the landscape can shift. In mid-2025, Acumatica reached a definitive agreement to be acquired by Vista Equity Partners, a transaction that signals the continued investor appetite for scalable cloud ERP platforms with clear mid-market positioning and growth potential. In mid-2026, Workday expanded its agent-related tooling with developer agents, agent-ready tools, and agent passport capabilities designed to support building, connecting, and verifying AI agents across HR, finance, and IT environments. These developments are not isolated events; they reflect two broader dynamics. First, capital and M&A activity continues to reshape ownership and go-to-market intensity in the sector. Second, product roadmaps are increasingly oriented around governed AI and orchestration, with vendors racing to make ERP environments more programmable and agent-compatible without sacrificing control.
PW Consulting
The competitive trend that follows from this mix is a market that is simultaneously consolidating at the top and fragmenting by use case. Large platforms are broadening their ecosystems and embedding intelligence, while specialized vendors compete on vertical depth, deployment simplicity, or open extensibility. New entrants and partner-built solutions are also shaping the edges of the market, particularly where organizations want best-of-breed integration around a core ERP backbone. For buyers, the practical implication is that vendor selection should be treated as a fit-and-evolution question: which platform aligns with current process needs, which one can grow with the organization, and which one offers a credible path through compliance, integration, and AI adoption without forcing excessive customization.
Supplier Relationship Management System Market
Forward Outlook: Three Trends to Watch Over the Next Three to Five Years
Looking ahead, the ERP market is likely to be defined by a small number of high-impact trends that will shape both vendor strategies and enterprise buying behavior. These trends are not speculative; they are already visible in product roadmaps, implementation patterns, and regulatory signals, but their full commercial implications will unfold gradually.
Intelligence as a Core ERP Capability, Not a Add-On
The next phase of ERP competition will center on how reliably platforms can support governed automation and agent-based workflows. The move toward developer tools, agent-ready environments, and verification mechanisms indicates that AI will increasingly be treated as an operational layer inside ERP rather than a separate analytics overlay. For enterprises, this creates an opportunity to reduce manual reconciliation, improve exception handling, and accelerate cycle times in finance and supply chain processes. The risk is that organizations adopt agent-enabled features before they have standardized data, cleaned master records, and defined control boundaries. In that scenario, intelligence can amplify process noise rather than reduce it. The strategic opportunity, then, is to pair platform-level intelligence with disciplined data governance and clearly scoped automation use cases.
Compliance and Regulatory Agility Becoming a Buying Criterion
As cloud ERP systems continue to absorb more regulatory upkeep through automatic updates and built-in controls, enterprises will increasingly evaluate vendors on their ability to help them stay aligned without excessive manual intervention. At the same time, regulatory environments will remain fluid, with deregulatory signals and evolving obligations creating periods of both opportunity and uncertainty. Organizations that treat compliance as an ongoing platform capability are better positioned to reduce audit friction and avoid reactive remediation costs. The commercial opportunity is to select platforms and implementation models that make regulatory adaptation part of the operating rhythm rather than a periodic project.
Deployment Economics and Implementation Discipline Driving TCO Outcomes
Cloud adoption will continue to lower upfront barriers, but leadership teams will become more sophisticated about lifecycle economics. Over the next several years, buyers are likely to compare solutions less on initial price and more on implementation risk, upgrade exposure, training burden, and the cost of maintaining custom extensions. This should favor platforms and partners that can deliver predictable deployment timelines, modular adoption, and cleaner upgrade paths. For vendors, the implication is that implementation quality and partner ecosystems will become more important competitive levers, not just product features. For enterprises, it means that the best ERP decision is often the one that balances ambition with implementation realism, especially for organizations that have limited internal bandwidth.
What Decision-Makers Should Do Next
ERP strategy is no longer a procurement exercise; it is an operating model decision. The most effective responses will differ by role, but several priorities apply across the board.
- For manufacturers and operationally complex enterprises, prioritize platforms that can connect finance, supply chain, inventory, and manufacturing workflows without forcing excessive customization. Standardization first, extension second, is usually the most durable path to value, especially when supply chain volatility and compliance demands are high.
- For investors and market observers, focus on the signals that indicate durable competitive advantage: cloud delivery maturity, ecosystem extensibility, agent-ready tooling, and evidence that implementation and upgrade economics are improving rather than worsening. Ownership changes and product launches matter, but they should be evaluated against whether they strengthen or weaken a vendor’s ability to serve complex enterprise needs over time.
- For procurement and finance leaders evaluating ERP purchases, treat total cost of ownership as a lifecycle question. Compare not only subscription pricing, but also implementation complexity, training demands, customization exposure, and the operational burden of maintaining compliance and upgrades. A lower entry cost can be attractive, but it should not come at the expense of long-term maintainability.
Each of these priorities benefits from deeper, segment-level intelligence. Market-wide figures provide direction, but the real decisions happen in the details: which deployment model fits a given operating profile, which functional areas are expanding fastest in a specific industry, how vendor strategies differ by enterprise size, and where implementation risk is most likely to undermine projected value. The ERP market is large, fast-moving, and increasingly defined by platform intelligence, regulatory agility, and deployment discipline. Organizations that make decisions with that context in mind are better positioned to convert ERP from a cost center into a strategic operating asset.
For detailed analysis of this topic, please visit the official page: Enterprise Resource Planning (ERP) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cationic Conditioning Polymers Market: How 6.98% CAGR and Hair Care Demand Reshape Growth Beyond 2032
By pmarketresearch, 2026-09-21
The Cationic Conditioning Polymers Market: Strategic Trends and Commercial Opportunities
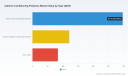
The global market for cationic conditioning polymers has entered a phase of disciplined expansion, driven by fundamental shifts in personal care formulation philosophies and regulatory redefinition of what constitutes acceptable ingredient architecture. Valued at approximately 502.7 million USD in 2025, the market has grown from 358.22 million USD in 2020, reflecting a compound annual growth rate of 6.98 percent through the forecast horizon to 2032. This trajectory signals more than incremental volume growth; it points to a structural transformation in how conditioners, shampoos, and related personal care matrices are engineered for performance, sensorial appeal, and environmental compliance. For executives and investors navigating specialty chemicals and beauty care supply chains, the market presents a landscape where formulation science, regulatory foresight, and supply chain agility now determine competitive positioning more than scale alone.
Market Status and Defining Challenges
From Volume Recovery to Formulation Redesign
The historical 2020–2025 period illustrates a recovery curve that accelerated sharply after the initial disruption of the early 2020s, with market size rising to 419.89 million USD in 2022 and continuing upward to 428.24 million USD in 2023 and 480.94 million USD in 2024. The 2025 valuation of 502.7 million USD represents a market that has absorbed post-pandemic demand normalization, resumed salon and retail channel activity, and begun confronting a more stringent regulatory environment. The forecast period extends this momentum, projecting a climb toward 540.47 million USD in 2026, continuing through 608.61 million USD in 2028, and reaching 802.8 million USD by 2032. This growth path is not uniform across all formulation segments or geographies, and the uneven pace itself reveals where investment logic must be sharpened.
Three structural challenges currently define the operating environment for manufacturers, formulators, and brand owners. First, the regulatory redefinition of polymer-based microplastics in rinse-off personal care products has forced widespread reformulation. Industry tracking shows that more than 28 percent of rinse-off personal care products in 2023 required reformulation across EU nations due to polymer-based microplastic content restrictions, and EU enforcement continues to shape global formulation strategy even beyond European borders. Second, feedstock volatility has introduced margin pressure and supply uncertainty into the production of key intermediates, particularly where CHPTAC pricing fluctuates in response to global supply shocks in epichlorohydrin and trimethylamine. Third, the competitive field remains comparatively fragmented, with a CR3 of 24.6 percent and a CR5 of 26.2 percent, indicating that no small group of players dominates the market and that differentiation depends on technical capability and regulatory navigation rather than scale alone.
These challenges interact in ways that reshape sourcing, R&D prioritization, and portfolio strategy. The market is not simply expanding; it is being redesigned.
PW Consulting
Key Drivers of Market Evolution
Innovation at the Chemistry-Performance Intersection
Technical innovation is propelling the market forward by expanding the performance envelope of cationic conditioning systems. Advanced polymer architectures now deliver stronger substantivity, improved wet and dry hair manageability, and more efficient deposition at lower usage levels. Recent product introductions illustrate this direction. In February 2026, Lubrizol introduced advanced cationic conditioning polymers engineered for enhanced hair manageability, moisture retention, and compatibility in shampoos and conditioners, signaling continued investment in next-generationpersonal care active systems. In December 2025, Inolex highlighted Kerazyne MB polyesteramine as an advanced multifunctional conditioning polymer for hair and skin care, emphasizing multifunctional performance within a single ingredient platform. These developments reflect a broader shift from commodity-style conditioning agents toward actives that solve multiple formulation pain points simultaneously, such as sensory softness, rinsability, and stability in complex surfactant systems.
For formulators and procurement leaders, this shift means that ingredient selection increasingly hinges on functionality breadth and compatibility rather than cost-per-kilogram alone. Polymers that can perform under sulfate-free, mild-surfactant, or low-pH conditions carry disproportionate value in premium and claims-driven product segments, where sensory outcomes and clean-label narratives must coexist with technical reliability.
Regulatory Pressure as a Catalyst for Sustainable Design
Regulatory change is accelerating reformulation cycles and creating a market premium for biodegradable and sulfate-free cationic systems. Between 2022 and 2024, industry data indicates that 38 percent of leading firms launched sulfate-free and biodegradable cationic polymers to address eco-conscious demand, a response that aligns with both consumer sentiment and regulatory tightening. At the same time, EU enforcement of polymer-based microplastic restrictions in rinse-off products continues to influence ingredient choices globally, while China’s REACH MEE Order 12 requires regular or simplified registration for cationic polymers expected to become cationic in natural water environments, adding a compliance layer for manufacturers supplying into or through the Asia-Pacific region.
These regulatory dynamics do not merely constrain; they redirect innovation toward genuinely sustainable chemistries. Companies that can demonstrate environmental compatibility without sacrificing conditioning performance are gaining formulation preference in markets where sustainability claims must be substantiated and where downstream customers face their own compliance obligations.
Consumer and Retailer Demand Reshaping Application Priorities
Demand-side behavior continues to favor hair care segments where conditioning performance is both visible and emotionally salient. Hair conditioners remain the largest application area, embodying the highest share of market value among end-use categories, while shampoos represent a significant secondary application, and other applications account for a smaller but strategically important portion of demand. The broad application footprint means that cationic conditioning polymers are embedded across a range of product formats, from rinse-off masks and treatments to daily-use shampoos and color-protecting systems. Consumer expectations around softness, shine, detangling, and heat protection are intensifying, particularly in premium and salon-grade offerings, pushing manufacturers to adopt actives that can deliver multi-attribute benefits without complicating formulation architecture.
The practical implication is that demand is increasingly performance-specific and claim-sensitive. Ingredients that enable simplified ingredient lists, support sulfate-free positioning, and deliver durable conditioning after rinsing are gaining share in segments where formulation transparency and sensorial consistency directly influence repurchase behavior.
Feedstock Volatility and Supply Chain Realignment
Cost structure and supply chain resilience have emerged as critical strategic variables. The CHPTAC market price volatility driven by global supply shocks in epichlorohydrin and trimethylamine has introduced uncertainty into the cost base for cationic polymer production, compelling manufacturers to revisit sourcing strategies, inventory planning, and pricing architectures. Capacity expansions and production increases are underway to address supply constraints and regional demand growth. In December 2025, Solenis expanded production capabilities for specialty cationic polymers used in personal care and industrial conditioning applications. In January 2026, Nippon Shokubai increased specialty polymer production to meet rising demand from Asia-Pacific personal care and salon-grade segments. These moves reflect a market-wide effort to secure supply, reduce lead-time risk, and align capacity with regional demand intensity.
For buyers and manufacturers, the lesson is that agility in sourcing and the ability to qualify alternative chemistries or regional suppliers are now part of core operational strategy. Reliance on single-source feedstock pathways or rigid formulation routines is becoming a liability in an environment where cost and compliance risks can shift rapidly.
Competitive Landscape and Winning Strategies
Leader Profiles and Differentiation Pathways
The competitive field includes players with distinct technical identities and regional strengths. SKW Quab Chemicals Inc., based in Saddle Brook, New Jersey, focuses on QUAB cationizing reagents and resulting cationic polymers, including cationic guar derivatives, for high-strength conditioning in personal care shampoos and conditioners. This reagent-centric approach positions the company around enabling chemistry that supports strong conditioning performance and formulation flexibility. Samyang KCI Corporation, headquartered in Seoul, South Korea, emphasizes specialty conditioning agents and cationic polymers for premium shampoos, conditioners, and hair care formulations, aligning closely with the Asia-Pacific premium and salon-grade demand trajectory. SNF, based in Andrézieux, France, focuses on water-soluble cationic polymers and film formers for hair care and conditioning in personal care applications, leveraging a broad polymer platform that spans performance and application versatility.
Solenis, headquartered in Charlotte, North Carolina, concentrates on specialty cationic polymers for personal care conditioning applications, and its December 2025 capacity expansion underscores a strategy of scaling specialty supply to meet demand while maintaining application-specific technical support. Inolex, based in Philadelphia, Pennsylvania, focuses on sustainable bio-based cationic conditioning agents and polymers for plant-based hair care and conditioning systems, distinguishing itself through a sustainability narrative anchored in bio-based chemistry and multifunctional performance, as highlighted by its December 2025 Kerazyne MB polyesteramine introduction.
Cationic Starch Market
Strategic Positioning and Differentiation Levers
Across these players, three differentiation levers are becoming decisive. First, application-specific technical support is increasingly valued, particularly where formulators require help optimizing deposition, rinse-off behavior, and compatibility with mild surfactant systems. Second, sustainable sourcing and bio-based or biodegradable positioning create claims advantage in premium and eco-conscious segments, where performance and environmental compatibility must be demonstrated together. Third, supply resilience and regional capacity alignment reduce risk for customers who are sensitive to lead times, feedstock volatility, and regulatory registration requirements across jurisdictions.
The market concentration data, with a CR3 of 24.6 percent and CR5 of 26.2 percent, indicates that scale dominance is not the primary competitive dynamic. Instead, differentiation through chemistry, application expertise, and compliance readiness determines which suppliers gain formulation preference and long-term inclusion in brand owner pipelines.
Market Structure Evolution: Consolidation Pressures and Entry Opportunities
The landscape is likely to evolve through a combination of selective consolidation and continued entry by specialized players. Scale players can capture value by integrating capacity, broadening regional coverage, and offering application breadth that reduces the number of supplier relationships for large brand owners. At the same time, new and niche entrants can compete by solving specific formulation problems, offering sustainable chemistries with verifiable claims, or serving fast-growing regional demand with localized technical support and supply. The regulatory environment also creates entry barriers where registration and compliance costs raise the threshold for new supply, but it simultaneously creates opportunities for suppliers that have already navigated these requirements and can offer ready-to-formulate, compliant solutions.
For incumbents, the strategic priority is to convert technical and compliance capabilities into stickier customer relationships. For new entrants, the entry point is not generic volume but targeted performance, sustainability substantiation, or regional supply advantage.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend One: Sustainability-Linked Performance as a Default Requirement
Over the next three to five years, sustainability-linked performance is likely to become a default expectation rather than a premium differentiator in many priority segments. As regulatory frameworks continue to tighten around polymer-based microplastics and environmental fate, and as consumer and retailer expectations around biodegradability and reduced environmental burden intensify, formulations will increasingly be judged on both function and footprint. This trend creates commercial opportunity for suppliers that can deliver conditioning performance with verifiable environmental compatibility and for brand owners that can translate those attributes into credible claims. The risk is that uncertified or poorly substantiated sustainability narratives face growing scrutiny, making technical validation and documentation essential.
Trend Two: Regional Demand Divergence and Localized Supply Strategies
Regional demand patterns are expected to diverge further, with Asia-Pacific personal care and salon-grade segments continuing to drive volume and premiumization, while North America and Europe remain centers of formulation innovation and regulatory influence. Industry developments already reflect this divergence, with Nippon Shokubai increasing specialty polymer production to meet rising Asia-Pacific demand and Solenis expanding capacity to support both personal care and industrial conditioning applications. The opportunity lies in aligning supply and technical support with regional demand intensity, reducing lead times, and building local formulation partnerships. The risk is that global supply strategies that ignore regional regulatory and demand nuances may face cost, compliance, or service-level disadvantages.
Trend Three: Ingredient Simplification and Multifunctional Actives
Formulation simplification is likely to accelerate as brand owners seek to reduce ingredient counts, improve label clarity, and streamline compliance management while preserving sensory and performance outcomes. Multifunctional conditioning polymers that combine deposition, softness, moisture retention, and compatibility in a single platform are well positioned for this environment. Recent introductions, such as Lubrizol’s advanced cationic conditioning polymers and Inolex’s Kerazyne MB polyesteramine, illustrate the direction of travel toward actives that reduce formulation complexity while expanding benefit sets. The commercial opportunity is for suppliers that can prove multifunctional performance with robust data and for brand owners that can leverage simplified systems to support claims and cost efficiency. The risk is overpromising on multifunctionality without sufficient application-specific validation, which can erode trust in a market where performance is immediately felt by consumers.
Strategic Actions for Decision Makers
For Manufacturers and Formulators
Prioritize application-specific validation of cationic systems under the conditions most relevant to your portfolio, including mild surfactant systems, sulfate-free bases, and rinse-off formats where deposition and substantivity must be balanced with clarity and feel. Build regulatory readiness into ingredient qualification processes, particularly for markets with registration or microplastic-related constraints, so that compliant options are available without last-minute reformulation pressure. Diversify feedstock and supplier pathways where feasible to mitigate CHPTAC-related volatility and reduce exposure to single-source disruptions.
Worldwide Cationic Reagent Market
For Investors and Strategic Buyers
Evaluate suppliers on the basis of technical differentiation, sustainability substantiation, and regional supply resilience rather than price alone. Companies that combine application expertise with verifiable environmental compatibility and the ability to support reformulation under evolving regulatory conditions are likely to capture higher-value positions in the value chain. Pay attention to capacity expansions and regional production moves as indicators of where demand is being served and where supply reliability is improving, since these shifts can alter competitive dynamics and customer loyalty over time.
For Procurement and Product Development Leaders
Treat cationic conditioning polymers as strategic inputs whose selection affects claims, compliance, and consumer perception, not just cost and viscosity. Qualify ingredients that support sulfate-free, biodegradable, or bio-based narratives with documented performance data, and align sourcing decisions with the regulatory and demand profile of your priority markets. Establish early engagement with suppliers that offer technical support for formulation optimization, since collaboration at the development stage can reduce time-to-market and improve the robustness of end-product performance.
The strategic value of this market lies in the intersection of performance, compliance, and supply agility. Detailed segmentation data, regional demand analysis, and tailored sourcing or portfolio recommendations can clarify where to commit resources and how to structure partnerships for the next growth cycle. Access to granular market sizing, application-level demand breakdowns, and company-level competitive assessment enables more precise decision making than aggregate trends alone can provide. For teams seeking to translate these dynamics into product roadmaps, sourcing strategies, or investment theses, comprehensive market intelligence remains a critical input to confident execution.
For detailed analysis of this topic, please visit the official page: Cationic Conditioning Polymers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Embolization Particle Market: Why 9.8% CAGR and the Oncology Shift Redefine Growth to 2032
By pmarketresearch, 2026-09-21
The Embolization Particle Market: Strategic Trends and Commercial Opportunities Through 2032
The embolization particle market has entered a phase of sustained expansion, transitioning from a niche interventional toolkit component to a core growth vector within the broader medical device economy. Between 2020 and 2025, global revenue climbed from approximately 1.83 billion USD to 2.88 billion USD, reflecting consistent year-over-year gains driven by procedural volume growth, product refinement, and expanding clinical indications. The trajectory is expected to continue through 2032, with the market projected to reach roughly 5.51 billion USD. This growth path translates to a compound annual growth rate of 9.8 percent across the 2026–2032 forecast window. Such momentum is not accidental; it reflects converging forces in oncology procedural adoption, interventional radiology workflow optimization, and gradual geographic penetration beyond mature markets. For decision makers evaluating capital allocation, product strategy, or procurement roadmaps, the market now rewards those who understand where innovation is compounding, which segments are maturing, and where regulatory and reimbursement dynamics are shifting the competitive edge.
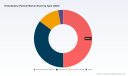
Behind the headline numbers lies a market with notable structural complexity. Revenue distribution is not uniform across procedures or geographies. Oncology applications command the largest share of demand, supported by the increasing use of embolotherapy as a bridge to surgery, a primary treatment in unresectable cases, and a complementary modality in combination regimens. Uterine fibroid embolization and peripheral vascular disease applications continue to anchor steady procedural volumes, while newer indications remain in earlier stages of clinical and commercial validation. Regionally, established markets with mature interventional infrastructure and favorable reimbursement pathways account for the largest revenue pools, while faster-growing regions are expanding capacity through training programs, device localization, and increasing procedural throughput. The overall market concentration also signals that scale, clinical evidence, and regulatory execution remain decisive advantages for leading players, even as specialized entrants find room to compete in differentiated niches.
Key Structural Challenges and Inflection Points
Despite strong growth momentum, the market faces several challenges that can reshape competitive advantage over the next few years. First, clinical evidence requirements are intensifying. Purchasing committees and hospital formulary teams increasingly expect durable outcomes data, not just procedural feasibility. This shifts the basis of competition from device availability alone toward therapeutic performance, reproducibility, and post-market evidence accumulation. Manufacturers that can generate and communicate robust real-world outcomes are better positioned to defend pricing and expand share, while those relying on generic claims face growing scrutiny.
Second, regulatory and reimbursement alignment remains uneven across regions. A product that secures clearance or approval in one jurisdiction may still encounter prolonged adoption timelines elsewhere if reimbursement coding, coverage policy, or procurement rules do not keep pace. The gap between regulatory authorization and economic access can weaken commercial velocity, particularly for products entering smaller or cost-sensitive markets. For this reason, the most effective product strategies now integrate reimbursement planning early, rather than treating it as a downstream activity.
Third, the industry is seeing a shift in supply chain expectations around sterilization, biocompatibility, and consistency. Embolization particles must meet rigorous standards for safe delivery, predictable behavior, and reliable manufacturing quality. Because these products are used in high-stakes vascular procedures, even small inconsistencies can affect procedural confidence and hospital adoption. This elevates the importance of process control, documentation discipline, and regulatory readiness across the manufacturing footprint. Companies that treat these as strategic capabilities rather than operational overhead gain resilience in a market where trust is a core purchasing factor.
A further inflection point lies in the expanding role of embolotherapy in combination treatment pathways. As interventional and oncology teams coordinate care more closely, embolization particles are increasingly evaluated not only as standalone embolic tools but as components within broader treatment strategies. This creates both opportunity and complexity: product selection becomes more procedure- and patient-specific, and competitive differentiation increasingly depends on how well a device supports clinical workflow, imaging compatibility, and procedural flexibility.
Key Growth Drivers Reshaping the Market
Technology Innovation and Product Differentiation
Technology development continues to be one of the most visible drivers of market change. Embolization particles are evolving along several directions at once, including material composition, size distribution precision, delivery characteristics, and functional added value. Spherical embolic microspheres have gained prominence because their consistency can support more predictable occlusion and procedural control compared with irregular particle formats. At the same time, non-spherical polyvinyl alcohol-based options remain relevant where specific embolic behaviors are desired, particularly in arteriovenous malformations and certain hypervascular tumor applications. This diversity of product architecture means the market is not converging on a single format; instead, it is becoming more application-defined.
A second layer of innovation lies in drug-eluting and functionalized platforms. These systems are designed to combine local embolic effect with sustained therapeutic delivery, broadening their relevance in oncology and other targeted indications. Their adoption depends not only on device performance but also on the availability of supporting clinical evidence and procedural protocols. As clinicians gain more experience with these platforms, products that demonstrate reliable delivery, manageable handling, and consistent outcomes are likely to earn stronger preference in complex cases.
Worldwide Intracranial Embolization Coil Market
The third technology trend is the continuous refinement of resorbable and hydrogel-based materials. Fast-resorbable gelatin-based hydrophilic microspheres, for example, reflect an interest in temporary embolic effects for specific procedures such as musculoskeletal pain embolization. Such products illustrate a broader move toward matching material behavior to clinical intent rather than applying one embolic solution across all use cases. For manufacturers, this means product roadmaps increasingly need to balance material science, clinical use cases, and procedural ergonomics.
Policy and Regulatory Dynamics
Regulatory developments are acting as both gatekeepers and enablers. Approvals and clearances can unlock large demand pools quickly when they address high-impact indications. For example, recent authorization activity around Y-90 resin microspheres for unresectable hepatocellular carcinoma has highlighted the commercial importance of strong trial-supported indications in oncology. Similarly, 510(k) clearances for polyvinyl alcohol embolization microspheres used in arteriovenous malformations and hypervascular tumors demonstrate that incremental regulatory progress in conventional embolic categories still matters, particularly when it reinforces procedural versatility and hospital purchasing confidence.
At the same time, compliance expectations around sterilization, packaging, and labeling are increasingly scrutinized across jurisdictions. Products that are packaged dry and designed to meet recognized sterilization standards benefit from manufacturing predictability and regulatory clarity. This may appear technical, but it matters commercially because regulators, procurement teams, and hospital quality departments all rely on consistent documentation when evaluating suppliers for long-term use. In practice, regulatory readiness is becoming a differentiator that affects speed to market, cross-border expansion, and institutional trust.
Reimbursement and market access policies further shape adoption. Even when a device is clinically appropriate, hospitals and interventional centers move faster when reimbursement pathways are clear and aligned with the product’s intended use. Support resources tied to specific product applications can help shorten education and implementation cycles, especially for centers scaling up embolization procedures. As a result, companies that integrate reimbursement support, clinical education, and procedural training into their commercial model tend to achieve more dependable uptake than those that rely on product features alone.
Demand-Side Shifts in Clinical and Institutional Behavior
Demand is being reshaped by changes in how hospitals and procedural teams think about intervention. Interventional radiology and endovascular practices are increasingly focused on minimizing procedural variability, improving turnover, and maintaining consistent outcomes across operators. In that environment, products that provide predictable handling and repeatable performance become more valuable. The emphasis is moving from availability toward reliability and fit-for-purpose performance in specific procedures.
Procurement behavior is also evolving. Hospitals are paying closer attention to total procedural cost, not just device unit price. This includes factors such as preparation time, compatibility with existing delivery systems, waste reduction, and the breadth of procedures a product can support. Where a single product family can serve multiple use cases without compromising performance, it can simplify inventory management and reduce training burden. These operational considerations increasingly influence purchasing decisions alongside clinical factors.
Oncology demand remains a dominant driver, but it is changing in character. Embolization particles are being incorporated into more nuanced treatment pathways, including scenarios where local control is essential and where patient eligibility for surgery or systemic therapy is limited. That shift supports sustained growth in oncology volumes, but it also raises expectations for evidence, safety, and procedural integration. Similarly, uterine fibroid embolization and peripheral vascular disease applications continue to benefit from growing recognition of minimally invasive options, though growth in those areas depends on local clinical adoption patterns and reimbursement conditions.
Supply Chain and Cost Structure Pressures
Cost structure and supply chain resilience are increasingly important as the market expands. Manufacturing consistency, raw material availability, and sterilization logistics directly affect product reliability and commercial continuity. In a market where clinical trust depends on uniformity and quality, supply disruptions can have outsized consequences. This has raised interest in supply models that reduce risk through stable production processes, clear documentation, and well-managed distribution pathways.
Pricing dynamics are also shifting. In mature markets, hospitals are more likely to challenge recurring device spend, especially when multiple products appear clinically similar. In response, manufacturers can defend positions through clinical differentiation, service quality, and procedural support rather than broad price competition. In faster-growing regions, the pricing conversation may be more about access and scalability than about marginal cost reduction. Companies that manage both ends of this spectrum effectively are better positioned to capture regional growth without compromising margin integrity.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Key Players
The competitive field is anchored by a group of established manufacturers with strong product portfolios, regulatory assets, and procedural credibility. These companies compete on more than product features; they compete on evidence base, indication coverage, delivery system compatibility, and commercial support. Their strategies tend to emphasize one or more of the following: breadth across embolic formats, depth in a specialized indication, or capability in drug-eluting and functionalized platforms.
Merit Medical Systems, Inc. maintains a diversified embolization particle portfolio spanning irregularly shaped non-resorbable polyvinyl alcohol particles, sodium acrylate alcohol copolymer microspheres, spherical embolic microspheres positioned as a market leader in that category, and resorbable porcine gelatin for hypervascular tumors and bleeding control. This breadth allows the company to serve a wide procedural range, from arteriovenous malformations to hypervascular tumors, with multiple material options. Their profile suggests a strategy built on format flexibility and cross-application coverage, which can be attractive to centers seeking to standardize on fewer suppliers while still matching products to specific clinical scenarios.
Boston Scientific Corporation competes with a portfolio that includes polyvinyl alcohol embolization particles, hydrogel-based microspheres with Polyzene-F, and Y-90 resin microspheres for radioembolization. This combination supports both conventional embolic applications and specialized oncology radioembolization use cases. A notable advantage lies in combining procedural product lines with reimbursement-related educational resources that can support adoption in peripheral hepatic vascular tumor and uterine fibroid applications. For competitors and customers alike, this illustrates how commercial execution can hinge on pairing device capability with access support and procedural education.
Terumo Corporation emphasizes microspheres and drug-eluting platforms, with offerings that include PEG drug-eluting microspheres and hydrogel-based microspheres cleared in certain regions for hypervascular tumors and uterine fibroids. The strategic logic here is clear: by covering both standard embolic microspheres and drug-eluting options, the company can position for current procedural demand while participating in higher-complexity applications. In markets where clinicians are expanding indications and refining treatment pathways, such product alignment can translate into stronger institutional relationships and repeat usage.
Sirtex Medical Limited focuses strongly on radioembolization, particularly with Y-90 resin microspheres used in unresectable hepatocellular carcinoma. The company’s recent regulatory milestones illustrate the commercial power of indication-specific leadership. A recent FDA approval for unresectable HCC, supported by trial results showing high local tumor control and durable response duration, reinforces the value of evidence-led positioning in oncology. Alongside EU medical device regulation certification for delivery systems, this shows a strategy centered on regulatory and clinical credibility in a high-value therapeutic niche rather than broad product spread.
BTG plc, now integrated with the Boston Scientific portfolio, contributes legacy relevance through sulphonate-modified hydrogel microspheres. The broader trajectory here suggests that portfolio consolidation can strengthen commercialization while preserving specialized technology lines. Integration can streamline distribution, expand customer access, and reinforce clinical messaging, though it also requires careful management of brand continuity and procedural familiarity.
NextBioMedical Co., Ltd. represents a newer competitive presence with fast-resorbable gelatin-based hydrophilic microspheres. Recent Health Canada approval for musculoskeletal pain embolization shows how targeted regulatory success can open commercial entry in specific applications. For smaller or regionally focused players, the strategic play is often to compete where a well-defined clinical niche, clear regulatory pathway, and strong procedural alignment can outweigh the advantages of larger global portfolios.
Market Structure Evolution: Consolidation, Fragmentation, and New Entrants
The market is simultaneously experiencing consolidation benefits and niche fragmentation. Larger portfolios and integrated commercial models can reduce complexity for hospital buyers and improve access to broader procedural support. That favors incumbents with scale and established relationships. At the same time, fragmentation persists because embolization is not a single-use category with one optimal solution. Different applications, anatomical targets, and procedural preferences sustain demand for multiple embolic formats and material types. This creates openings for specialized entrants that can solve a specific clinical problem exceptionally well.
PW Consulting
New entrants are most likely to succeed when they pursue disciplined differentiation rather than broad me-too coverage. The recent approvals and clearances in both conventional PVA microspheres and Y-90 resin microspheres show that incremental innovation can still unlock commercial momentum if it addresses an unmet procedural need or strengthens evidence in a valuable indication. For the overall market, this means competitive intensity will likely remain high, but the winners will be those who combine product performance with regulatory clarity, reimbursement readiness, and credible procedural support.
Forward-Looking Trends and Commercial Implications (2026–2032)
Trend 1: Broader Oncology Integration and Evidence-Led Adoption
Oncology applications are expected to remain the largest demand anchor, but their commercial character will continue to shift. As embolotherapy becomes more embedded in combination treatment pathways, products will be evaluated more closely for local control capability, procedural compatibility, and durability of outcome. This trend favors companies that can support clinicians with evidence, training, and procedural guidance, not just device supply. For investors and manufacturers, it means that oncology growth will increasingly reward those who can translate trial strength and real-world performance into confident purchasing decisions. A risk here is that adoption may advance unevenly across regions if evidence expectations or reimbursement alignment lag.
Trend 2: Expanded Indications in Interventional Pain and Peripheral Applications
Beyond oncology, growth is likely to come from incremental indication expansion in areas such as uterine fibroid embolization, peripheral vascular disease, and musculoskeletal pain embolization. These applications can broaden addressable volume without requiring a complete overhaul of procedural infrastructure. The commercial opportunity lies in product-line extensions and application-specific positioning that match material behavior to clinical intent. For companies, the key is to avoid overextending into indications where clinical evidence or reimbursement support is premature. A realistic expansion strategy should prioritize indications with clear procedural fit and existing institutional demand. The uncertainty is that some newer applications may develop more slowly than anticipated if clinical adoption or payment pathways remain limited.
Trend 3: Regional Expansion with Increasingly Localized Competition
Revenue growth will continue to be supported by regional expansion, especially in markets where interventional capacity is increasing and procedural training is strengthening. However, the pattern of growth is expected to become more localized. As regional players secure approvals, build manufacturing and distribution capability, and tailor commercial support to local procurement realities, competition in emerging markets may intensify beyond the global incumbents. This suggests a future where global portfolio strength and local execution both matter. Manufacturers that can adapt reimbursement engagement, education, and supply strategy to regional conditions will have an advantage. The principal risk is that regional adoption curves may be slower or more policy-dependent than top-line growth projections imply, particularly where purchasing systems prioritize cost containment.
Commercial Opportunity Summary
- Products that align material behavior with clearly defined clinical use cases are likely to gain preference in complex or high-stakes procedures.
- Evidence generation and procedural education will increasingly influence share gains, especially in oncology.
- Reimbursement support and market access readiness will shape commercial velocity as much as regulatory clearance.
- Regional expansion will favor players who can combine global product credibility with localized commercial execution.
- Portfolio breadth can be valuable, but differentiation by application is becoming more important than undifferentiated coverage.
Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
Manufacturers should prioritize product strategy that connects material performance to procedural outcomes. Rather than expanding purely for breadth, companies should evaluate which indications offer the strongest combination of clinical demand, reimbursement feasibility, and differentiation potential. Investment in evidence generation, sterilization and quality documentation, and procedural training can strengthen competitive positions in ways that last longer than short-term promotional activity. For portfolios already spanning multiple embolic formats, the opportunity is to make each product’s clinical rationale explicit and defensible. For newer or narrower portfolios, the opportunity is to win in a specific application with clear regulatory and reimbursement alignment.
For Investors and Corporate Development Teams
Investors should assess both market momentum and competitive defensibility. The projected trajectory suggests continued value creation, but share will likely accrue to businesses that can sustain regulatory confidence, clinical credibility, and commercial support in high-value applications. M&A and partnership opportunities may emerge around specialized technology lines, regional access capabilities, or complementary product formats. Due diligence should focus on indication-level adoption dynamics, evidence readiness, supply resilience, and the extent to which a company’s strategy relies on broad coverage versus focused differentiation. Valuation scenarios should also account for the possibility that regional growth and reimbursement timelines are more variable than aggregate market growth implies.
For Procurement and Clinical Program Leaders
Procurement and clinical leaders should evaluate embolization products through a total-procedure lens. This includes not only unit cost but also consistency of performance, handling characteristics, compatibility with existing delivery workflows, and the breadth of procedures a product can reliably support. Supplier selection should weigh clinical evidence, regulatory status, sterilization and quality documentation, and the availability of procedural support resources. In programs where embolization volume is growing, standardization on products that reduce variability and training burden can improve operational efficiency. At the same time, maintaining flexibility for application-specific needs may be prudent where procedural diversity is high.
Why Detailed Intelligence Matters Now
The embolization particle market is expanding, but the forces shaping that expansion differ significantly by application, region, and product format. Aggregate growth figures provide direction, yet the operational and commercial decisions that determine success depend on more granular insight: which indications are gaining procedural traction fastest, where reimbursement alignment is accelerating adoption, how regulatory milestones are changing competitive positioning, and which product formats are becoming more or less differentiated over time. Decision makers who operate with detailed segmentation data, company-level competitive mapping, and indication-specific outlooks are better equipped to time investments, prioritize portfolios, and manage procurement risk.
Expandable Microspheres Market
For those seeking a more complete view, the full research report provides deeper segmentation detail, company-level competitive profiles, regional and application-level revenue estimates, and tailored strategic scenarios. The additional depth is especially useful for teams that need to evaluate entry timing, portfolio fit, pricing strategy, or regional expansion with more precision than a market overview can support.
For detailed analysis of this topic, please visit the official page: Embolization Particle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
MRAM Market Reaches $45B by 2032: The 38.97% CAGR Trajectory Explained
By pmarketresearch, 2026-09-21
Magneto Resistive RAM (MRAM) Market: Strategic Trends and Commercial Opportunities
The global memory landscape is entering a decisive inflection point. Magnetic Resistive Random Access Memory (MRAM) has moved beyond niche experimentation to become a strategically critical non-volatile memory technology for applications demanding speed, endurance, and retention under harsh conditions. Revenue trajectories over the past half-decade tell a story of accelerating adoption: the market expanded from under one billion dollars in 2020 to approximately 4.49 billion dollars in 2025, and forward projections indicate sustained double-digit expansion through the end of the decade. The compound annual growth rate across the forecast horizon stands at roughly 38.97 percent, a pace that reflects both genuine technological maturation and broadening demand across mission-critical sectors. By 2032, market value is expected to approach 45 billion dollars, signaling a structural shift in how system architects balance performance, power, and reliability.
PW Consulting
Such growth is not merely a function of semiconductor cycle dynamics. MRAM occupies a unique position in the memory hierarchy, bridging gaps left by traditional flash, DRAM, and SRAM in specific use cases. The technology's ability to deliver non-volatility with near-SRAM speeds, combined with exceptional write endurance and temperature tolerance, has made it increasingly attractive for environments where data integrity cannot be compromised. Yet the path from rapid revenue expansion to sustained commercial dominance is neither linear nor guaranteed. Understanding the forces shaping this trajectory requires looking past headline numbers to the underlying technological, regulatory, and competitive dynamics that will determine which players capture value and which segments scale profitably.
Market Context and Structural Challenges
The current market environment reflects a technology transitioning from specialized deployment to broader architectural integration. Historically, MRAM found footholds in industrial, aerospace, and defense applications where radiation hardness, extreme temperature operation, and long-term data retention justified higher unit costs. That foundation remains intact, but the growth profile now reflects incremental penetration into adjacent markets where system designers are re-evaluating memory choices amid increasing performance and power constraints. The revenue curve's steepening over recent years indicates that design wins are compounding, manufacturing yields are improving, and integration pathways with existing semiconductor process flows are becoming more defined.
This momentum coexists with several structural challenges that will shape competitive outcomes over the next five years. First, the tension between density scaling and manufacturing complexity remains acute. MRAM fabrication relies on specialized magnetic materials, additional deposition and patterning steps, and tighter process tolerances than many conventional memory technologies. As manufacturers push toward higher-density arrays, maintaining uniform magnetic tunnel junction characteristics across large wafers becomes increasingly difficult, creating trade-offs between capacity, yield, and cost that cannot be solved through process optimization alone.
Second, qualification and reliability requirements continue to act as both a market enabler and a barrier. High-reliability applications demand documented performance under extreme thermal cycling, long-term retention guarantees, and adherence to automotive-grade qualification frameworks. These standards protect end customers but extend development timelines and raise the cost of market entry. The result is a market where incumbents with established qualification portfolios and application-specific reference designs hold meaningful advantages, while new entrants must navigate a multi-year pathway to prove suitability for safety-critical deployments.
Third, the market's current structure reflects a moderately consolidated landscape. A relatively small group of firms accounts for a substantial share of revenue, while the remainder is distributed across specialized players and emerging participants. This concentration creates both stability and friction: established players benefit from ongoing design wins and customer relationships, but the same dynamic can slow the diffusion of disruptive process innovations if incumbent architectures are optimized for existing product families rather than next-generation scaling pathways.
Key Drivers Shaping the Market Trajectory
The acceleration observed in recent years is not the product of a single catalyst. It emerges from the convergence of technological breakthroughs, evolving demand-side requirements, and shifting supply-side economics that together expand the addressable opportunity for MRAM.
Technical Innovation and Process Maturation form the foundation of current growth. Advances in magnetic tunnel junction design, particularly the transition toward perpendicular MTJ configurations and improvements in spin-transfer torque efficiency, have increased the feasibility of higher-density arrays while preserving the retention and endurance characteristics that define MRAM's value proposition. Incremental improvements in integration compatibility with standard CMOS flows reduce the friction of adoption for system manufacturers who cannot absorb highly customized fabrication requirements. Recent technical milestones illustrate this trajectory: one leading manufacturer achieved a Phase One milestone under a U.S. government-funded program by scaling magnetic cell geometry to enable higher-density space-grade MRAM, demonstrating that process innovation is increasingly oriented toward expanding density envelopes without abandoning reliability requirements.
Policy and Regulatory Environments are reshaping demand patterns in ways that directly favor non-volatile memory technologies with proven reliability profiles. National security priorities, industrial base resilience initiatives, and export control frameworks have heightened interest in domestic or allied supply chains for specialized semiconductor technologies. MRAM's relevance to defense, aerospace, and mission-critical infrastructure aligns with policy directions that emphasize secure, high-reliability components. This is visible in recent contract activity: a major MRAM developer secured a substantial subcontract with a U.S. prime contractor to support Toggle MRAM process technology and engineering services for Defense Industrial Base customers, reflecting how national security initiatives are translating into concrete demand signals for specialized memory capabilities.
Demand-Side Shifts in Application Architecture are expanding the contexts in which MRAM competes. In automotive systems, increasing electrification, advanced driver-assistance functionality, and connectivity requirements are pushing designers toward memory solutions that can operate reliably across wide temperature ranges while maintaining fast read/write performance. Validation activity underscores this momentum: MRAM products have been validated across multiple FPGA families for high-reliability configuration memory in industrial, aerospace, military, and automotive contexts, indicating that MRAM is being positioned not only as a standalone memory component but as an enabling element within broader system architectures. In aerospace and defense, the combination of radiation tolerance, extreme environment performance, and long data retention continues to drive adoption where alternative technologies struggle to meet qualification thresholds.
Supply Chain and Cost Structure Evolution remains a critical shaping force. The specialized materials and additional fabrication steps inherent to MRAM create cost structures that differ from mainstream memory categories. At lower volumes, these costs can limit price competitiveness in cost-sensitive markets. However, as process recipes mature, design wins accumulate, and manufacturing scale improves, the economic balance shifts. The challenge for manufacturers is to manage the intersection of yield, density, and qualification requirements in a way that preserves margin while expanding addressable volume. For customers, the decision increasingly comes down to total cost of ownership over the product lifecycle: MRAM's endurance, reduced risk of data loss, and suitability for harsh environments can offset higher upfront component costs in applications where failure is expensive or dangerous.
Static Random Access Memory (SRAM) Market
Competitive Landscape and Strategic Positioning
The MRAM market's competitive architecture reflects a blend of specialized incumbents, application-focused players, and selective government-driven demand that rewards proven reliability. Rather than competing solely on density or price, leading firms have built differentiation around process expertise, qualification track records, and deep integration with specific end-market requirements.
Everspin Technologies has established a prominent position as a developer and manufacturer of both discrete and embedded MRAM products, with a portfolio spanning Toggle MRAM, STT-MRAM, and advanced perpendicular MTJ-based variants. Its strategic emphasis on industrial IoT, data centers, automotive, aerospace, and mission-critical applications reflects a deliberate focus on markets where reliability and endurance justify the technology's adoption. The company's recent validation of its MRAM across FPGA families for high-reliability configuration memory, alongside a significant subcontract supporting U.S. Defense Industrial Base customers, illustrates how incumbents translate technical capability into commercial and programmatic momentum. The combination of design-in relationships, qualification documentation, and alignment with defense and industrial priorities gives such players a defensible position in segments where certification and trust matter as much as raw performance.
NVE Corporation occupies a more specialized niche, developing and licensing MRAM technology with emphasis on anti-tamper applications and spintronics-based solutions for low-bit-density, tamper-prevention use cases. This positioning reflects a different competitive logic: rather than competing in high-volume mainstream memory, the company focuses on specialized security-oriented applications where its technology's characteristics align with narrow but valuable requirements. In a market where many players chase density and volume, specialized security applications represent a reminder that differentiation can arise from application specificity as much as from process scale.
Avalanche Technology has focused on high-density STT-MRAM with spin-programmable perpendicular MTJ technology, targeting space-grade and industrial products for aerospace and defense. Its recent achievement of a Phase One milestone in a government-funded program, scaling magnetic cell geometry for higher-density space-grade MRAM, highlights a strategy centered on expanding density capability within stringent reliability envelopes. For customers in aerospace and defense, this type of progress signals a pathway toward more capacious memory solutions that still meet the qualification and environmental demands of mission-critical deployment.
The broader competitive trajectory is likely to be shaped by three overlapping dynamics. Integration will continue as system manufacturers seek memory solutions that reduce architectural complexity, particularly where non-volatility, speed, and endurance can be combined in a single element. At the same time, differentiation will persist: the market is not uniform, and the requirements of automotive, aerospace, industrial, and enterprise applications differ enough that specialized expertise, qualification portfolios, and application-specific reference designs will remain valuable. New entry will be selective rather than broad-based, given the barriers posed by fabrication complexity, qualification timelines, and the need for customer trust in high-reliability contexts. Incumbents with established design wins and process knowledge will have an advantage, but targeted entrants addressing narrow, high-value niches may find room to build sustainable positions.
Future Trends and Commercial Implications
Looking ahead across the next three to five years, the MRAM market's evolution will be defined by how effectively the industry resolves the tension between scaling ambition and manufacturing reality, how broadly qualification frameworks expand beyond traditional high-reliability niches, and how policy and supply chain dynamics shape demand concentration.
One clear trend is the continued push toward higher-density MRAM within reliability-constrained environments. As magnetic cell geometry and MTJ stack designs advance, the feasibility of denser arrays for aerospace, defense, and industrial applications improves. The commercial implication is straightforward: customers in these segments will gain access to memory solutions with greater capacity without sacrificing the environmental and retention characteristics that drove initial adoption. This creates opportunities for system architects to consolidate memory functions, reduce component count, and simplify designs in contexts where reliability is non-negotiable. The associated risk is that density gains may lag expectations if process uniformity challenges prove harder to overcome at scale, creating uneven product ramps and potential disappointment in roadmaps that assume linear scaling.
Giant Magneto Resistive (GMR) Sensors Market
A second trend is the broadening of qualification and integration pathways beyond the most demanding defense and aerospace niches. Validation activity across FPGA ecosystems and growing attention to automotive-grade qualification indicate that MRAM is being positioned for design wins in adjacent markets where reliability requirements are significant but not necessarily at the extreme end of the spectrum. The commercial opportunity lies in capturing design-in momentum early in product lifecycles, building reference architectures, and establishing supply confidence before competitors lock in alternative memory choices. The uncertainty here is regulatory and standards-driven: qualification frameworks are rigorous by design, and any shift in requirement interpretation, testing expectations, or supply chain scrutiny can alter timing and cost for both manufacturers and end customers.
A third trend is the growing intersection of memory technology strategy with national security and supply chain resilience priorities. Demand signals tied to defense industrial base initiatives, secure component sourcing, and allied supply chain preferences are likely to remain relevant, particularly for manufacturers positioned to support government and prime-contractor programs. For commercial players, this creates opportunities to align product roadmaps with policy-relevant applications and to build relationships that extend beyond traditional commercial cycles. The risk is concentration: reliance on policy-driven demand can be rewarding but also exposes manufacturers to shifts in program funding, procurement priorities, and export control environments. Diversification across industrial, automotive, and commercial high-reliability segments remains a prudent hedge.
Strategic Considerations for Decision-Makers
For manufacturers and technology developers, the near-term priority is to manage the density-versus-yield tension with explicit roadmaps that account for qualification requirements and customer qualification timelines. Investments in process control, magnetic material optimization, and integration compatibility with standard CMOS flows will determine whether higher-density products can reach volume without eroding margins. Equally important is the development of application-specific reference designs and qualification documentation that shorten customer evaluation cycles. In markets where reliability is paramount, the ability to demonstrate tested performance under representative conditions often matters more than headline specifications. Manufacturers should also consider how to balance defense-adjacent demand with broader industrial and automotive opportunities, ensuring that roadmaps are not overly dependent on any single demand stream.
For investors, the market presents a profile of high growth potential paired with technology execution risk and qualification-driven adoption timelines. The headline growth rate and forward market size trajectory reflect genuine expansion, but returns will depend on which companies can translate technical milestones into volume production, secure recurring design wins, and maintain cost discipline as densities increase. Evaluation should focus on process maturity indicators, qualification progress in target end markets, the durability of customer relationships in high-reliability segments, and the extent to which revenue is tied to policy-sensitive programs versus commercially diversified demand. The specialized nature of MRAM means that leadership in a narrow application area can be more valuable than broad but shallow market presence.
For procurement teams and system architects, MRAM should be evaluated as part of a total cost of ownership framework rather than solely on unit price. In applications where data retention, endurance, temperature tolerance, and fast non-volatile operation reduce downstream risk, MRAM's value can outweigh higher initial component costs. Early engagement with suppliers during the design-in phase, clear alignment on qualification expectations, and review of validation evidence across relevant FPGA or system ecosystems can reduce integration risk. Procurement strategies should also account for supply continuity in high-reliability contexts, where qualification lead times and specialized manufacturing requirements make supply chain resilience a meaningful consideration.
The strategic picture is clear: MRAM is moving from a specialized memory technology to a more broadly relevant element in system architectures where reliability, endurance, and non-volatility intersect with performance requirements. The growth trajectory is strong, but the market's future shape will be determined by how effectively participants navigate manufacturing complexity, qualification rigor, and the selective but meaningful influence of policy-driven demand. Detailed segmentation data, company-level competitive positioning, and application-specific adoption pathways can sharpen these strategic choices further. For decision-makers seeking a fuller picture of market size by segment, regional dynamics, and forward scenario analysis, the complete PW Consulting market report provides the granular intelligence needed to translate high-level trends into concrete commercial action.
For detailed analysis of this topic, please visit the official page: Magneto Resistive RAM (MRAM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Quick Service Restaurant IT Market: Strategic Shifts and Commercial Opportunities in a High-Growth Landscape
The Quick Service Restaurant (QSR) IT market has evolved from a back-office support function into a central growth engine. Between 2020 and 2025, the segment expanded from a 25.94 billion valuation to approximately 39.91 billion, reflecting a compound annual growth rate of 9.0 percent through the 2026–2032 forecast horizon. By 2032, the market is projected to surpass 72.96 billion, signaling sustained momentum rather than a cyclical peak. This trajectory is not driven by uniform expansion across all players. Instead, it reflects a structural realignment where technology, operational efficiency, and consumer expectations converge to redefine how QSR brands operate, compete, and scale.
At its core, the market sits at a transition point. Legacy point-of-sale systems are giving way to cloud-native architectures, fragmented toolchains are being consolidated into integrated platforms, and data is shifting from a reporting artifact to a real-time decision utility. The growth rate itself tells a story: it is fast enough to attract serious capital and competitor attention, but nuanced enough that success depends on execution quality, not merely market timing. For executives and investors, the imperative is to understand where the value is being created, who is capturing it, and what forces will shape the next phase of expansion.
The current landscape is characterized by a relatively open competitive field. Concentration metrics indicate that the top three players account for roughly 20.0 percent of total revenue, while the top five represent approximately 25.0 percent. This suggests a market that is still diversifying rather than ossified around a few dominant incumbents. The implication is straightforward: scale advantages exist, but they are not insurmountable. Companies that can deliver differentiated functionality, reliable integration, and clear total cost of ownership are finding room to grow. The question for decision-makers is no longer whether to invest in QSR IT, but how to align investments with the operational realities of high-volume, speed-driven environments.
Market Snapshot: Scale, Trajectory, and What the Numbers Mean
Macro Growth and Structural Momentum
The market’s expansion from 2020 through 2025 was not a straight line. Growth accelerated during periods of digital adoption pressure and moderated when operational budgets tightened. The 9.0 percent compound annual growth rate projected through 2032 reflects a market that has internalized technology adoption as a baseline expectation rather than a discretionary upgrade. This pace is meaningful because it compresses planning cycles. Manufacturers, software vendors, and service providers must anticipate demand shifts faster, while operators face shorter windows to evaluate, deploy, and derive value from new systems before the next wave of innovation arrives.
Revenue composition across hardware, software, and services indicates that no single component dominates the value pool. Hardware remains a substantial portion of the market, reflecting the continued need for terminals, kiosks, and display infrastructure. Software represents a comparably large share, underscoring the shift toward licensing, analytics, and integrated management capabilities. Services, while smaller in relative terms, play a critical role in implementation, customization, and ongoing optimization. The balance among these categories matters because it signals where margin profiles, renewal dynamics, and customer retention pressures differ. Hardware deployments often anchor long-term relationships, software introduces recurring revenue and upgrade cycles, and services tie value to operational outcomes rather than transactional sales.
Fast-casual Dining Market
Application-level demand also reveals a bifurcated but balanced base. Large-scale consumers represent a significant share of market activity, reflecting the needs of multi-unit brands that prioritize standardization, centralized reporting, and cross-location scalability. Smaller consumers account for a substantial portion as well, driven by independent operators and emerging chains that seek affordable, modular solutions without sacrificing core functionality. This split is strategically important. It means the market is not a single use case waiting for a uniform solution. Instead, it demands flexible architectures that can serve enterprise standardization and small-operator agility without forcing either segment into an ill-fitting model.
Core Challenges and Inflection Points
Integration Complexity and Operational Friction
One of the most persistent challenges in the QSR IT market is integration complexity. Many operators still rely on a patchwork of systems for ordering, payments, kitchen display, inventory, labor scheduling, and analytics. The promise of a unified platform is compelling, but the reality of deployment often introduces friction: data reconciliation between legacy and new systems, workflow redesign for staff, and change management across locations with varying levels of digital maturity. The operational risk is not just technical downtime. It is degraded throughput during transition periods, inconsistent customer experiences, and uncertainty about whether new tools will actually reduce labor intensity or simply add administrative overhead.
This challenge creates a clear inflection point. Vendors that can reduce deployment risk, provide proven migration paths, and demonstrate measurable improvements in throughput and error rates are positioned to win more decisive adoption. Conversely, solutions that overpromise on seamless unification without accounting for real-world operational variability face higher resistance from operators who cannot afford prolonged disruption. For decision-makers, the practical question is how to balance ambition with execution certainty: which capabilities can be standardized immediately, which require phased rollout, and how to measure success beyond go-live dates.
Cost Pressure and Margin Discipline
Operational cost pressure is another defining constraint. Labor availability, wage dynamics, and throughput expectations continue to shape how QSR brands think about technology investments. At the same time, upstream cost dynamics can affect suppliers and ultimately influence menu pricing and margin structures. Industry commentary has highlighted that tariff exposure on imported goods could raise input costs for QSR suppliers, prompting supply-chain adaptations and, in some cases, potential price adjustments passed through to customers. These pressures do not diminish the case for technology. They sharpen it. When margins are tight, the value of technology shifts from convenience to efficiency: reducing waste, improving order accuracy, optimizing labor allocation, and enabling faster decision cycles.
The inflection here is subtle but important. Technology is increasingly evaluated not as a separate line item but as a lever within a broader cost and throughput strategy. Solutions that can tie directly to labor productivity, inventory accuracy, or order velocity are more defensible in budget conversations than abstract digital transformation narratives. For investors and operators alike, this means the most durable demand is likely to come from tools that demonstrate measurable operational impact rather than incremental feature enhancement.
Skill Gaps and Change Management
A third challenge is the human dimension of technology adoption. Even well-designed systems depend on staff proficiency, manager oversight, and consistent usage patterns. QSR environments are high-pressure, turnover-prone, and operationally intense. Systems that require extensive training, complex manual steps, or frequent troubleshooting can underperform in practice regardless of their technical sophistication. This reality places a premium on usability, role-based design, and support models that extend beyond initial installation.
The strategic implication is that vendors and operators must treat change management as part of the product experience. Deployment success increasingly depends on how well a solution fits frontline workflows, how quickly staff can reach competence, and how effectively managers can interpret system outputs without adding administrative burden. In this sense, the market is rewarding solutions that reduce cognitive load and operational ambiguity, not just those that add capability.
Key Drivers Shaping the Market
Technological Innovation and AI-Enabled Operations
Technology innovation remains the most visible driver of market growth, with artificial intelligence emerging as a central theme. AI adoption in the QSR segment is expected to accelerate, driven by needs around order accuracy, voice-based ordering, demand forecasting, and operational automation. The appeal is straightforward: in high-volume environments, small improvements in order handling and throughput compound quickly into meaningful gains in revenue protection and labor efficiency. AI voice ordering, for example, can help manage demand spikes, reduce missed or misheard orders, and free staff to focus on fulfillment and service quality. Analytics and operational intelligence can improve inventory planning, labor scheduling, and menu performance tracking, giving managers more precise inputs for day-to-day decisions.
A concrete example of this trajectory is the recent launch by Toast of a unified enterprise drive-thru platform that integrates POS, kitchen display, digital menu boards, and AI voice ordering with the aim of optimizing QSR throughput. This type of release matters because it reflects a shift from isolated tools to coordinated workflows. The strategic value is not simply the presence of AI. It is the integration of AI into a system where order capture, kitchen execution, and customer-facing display operate as one flow. For operators, this reduces handoff friction. For vendors, it raises the bar on platform coherence and real-world performance.
Demand-Side Changes and Consumer Expectations
Consumer expectations continue to reshape QSR operations. Speed, convenience, and consistency are baseline demands, but they are increasingly supplemented by expectations around personalization, mobile engagement, and frictionless payment. Digital ordering, curbside pickup, and self-service options are no longer niche offerings. They are part of the service architecture that determines perceived value and repeat behavior. As these channels expand, the IT stack must support order routing, inventory visibility, payment flexibility, and loyalty integration without creating inconsistency across channels.
This demand-side shift also influences how brands think about data. When ordering happens across multiple touchpoints, the opportunity is not just to process transactions but to connect them into a coherent view of customer behavior and operational performance. That connection enables better promotion targeting, more accurate demand signals, and tighter alignment between sales channels and kitchen capacity. The commercial implication is that QSR IT is becoming a differentiation layer, not just a transaction layer. Brands that can orchestrate channels efficiently while maintaining speed and consistency are better positioned to defend share in competitive corridors.
Supply Chain, Cost Structure, and Regulatory Context
Supply chain and cost structure dynamics are increasingly intertwined with technology decisions. Tariff-related pressures on imported goods have been noted as a factor that could increase operational costs for QSR suppliers and contribute to broader input cost challenges. While the direct impact varies by supplier and product category, the broader signal is that cost volatility is a persistent consideration. In that environment, technology investments are evaluated for their ability to offset pressure through efficiency, waste reduction, and more precise inventory and labor management.
Regulatory and industry context also contributes to the pace of change. Expert commentary from the restaurant sector indicates that AI adoption in QSR is expected to accelerate, reflecting both competitive pressure and operational necessity. At the same time, the environment is not static. Cost inputs, labor conditions, and consumer behavior all create uncertainty that makes flexibility and scalability important purchase criteria. This reinforces a broader trend: the market is rewarding solutions that are adaptable across locations and resilient to changing cost and demand conditions, rather than solutions optimized for a single idealized operating model.
Competitive Landscape and Leading Strategies
Positioning Among Core Participants
The competitive field includes a mix of platform-focused vendors, hardware specialists, and enterprise-oriented providers. Toast stands out for its all-in-one cloud-based POS and restaurant management orientation, with capabilities that span drive-thru, AI voice ordering, and analytics tailored to high-volume QSR operations. Its recent enterprise drive-thru launch highlights a strategy centered on throughput optimization and integrated order flow. Square approaches the market with a cloud-native restaurant POS built around mobile ordering, inventory management, and curbside solutions, emphasizing speed and multi-location scalability. This positions Square around flexibility and growth-oriented deployment, particularly for operators that value rapid expansion and modular functionality.
Elo Touch Solutions takes a hardware-focused angle, offering customizable QSR POS systems, kiosks, and digital menu boards that connect order processing with inventory integration. Its relevance lies in the physical interaction layer: terminals, kiosks, and displays remain essential in many QSR environments, and hardware differentiation can influence throughput, durability, and customer experience. PAR Technology Corporation operates with an enterprise hospitality orientation, bringing together POS, scheduling, and operational intelligence for multi-unit QSR brands. Its value proposition centers on unification across locations and operational oversight, which appeals to brands managing complex field operations. Oracle brings a broader hospitality and food-and-beverage footprint, with POS capabilities that include mobile order and pay, analytics, and back-office integration. Its positioning reflects the ability to serve QSR and wider hospitality needs within a more extensive technology ecosystem. NCR Voyix focuses on unified-commerce POS for restaurants, including self-checkout and payments, with an emphasis on QSR efficiency and growth. Its strategy aligns with the broader movement toward combined ordering, payment, and service flows that reduce friction at the point of interaction.
Differentiation and Strategic Themes
Across these participants, several strategic themes emerge. One is integration depth. The most compelling offerings are those that reduce the number of disconnected systems an operator must manage and make data flow more naturally between front-of-house, back-of-house, and management functions. Another is scalability. Multi-unit brands need solutions that can standardize operations without eliminating local flexibility, and they need reporting and control mechanisms that work across locations without excessive customization. A third theme is operational intelligence. Analytics and management insights are increasingly expected to be part of the platform rather than a separate add-on, because they connect technology investment to measurable performance outcomes.
Differentiation also comes from deployment and support models. In a market where integration complexity and change management are real risks, vendors that provide smoother onboarding, clearer operational fit, and reliable ongoing support can create meaningful distance from competitors with similar feature sets. This is especially true for high-volume QSR environments, where even small usability issues can affect throughput and staff adoption. The strategic lesson is that functionality alone does not determine winner status. Execution quality, integration reliability, and total cost of ownership often matter more in sustained adoption.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market structure suggests continued evolution rather than early consolidation. With top-three and top-five concentration levels still moderate, there is room for both consolidation and specialization. Larger platforms may pursue breadth by adding capabilities across ordering, payments, kitchen operations, and analytics. Smaller or niche players may pursue depth in specific workflows, hardware categories, or regional deployment models. New entrants can still gain traction by addressing underserved needs, such as particular hardware configurations, vertical-specific workflows, or more affordable entry points for smaller operators.
At the same time, the risk of fragmentation is real. If operators accumulate overlapping tools in pursuit of best-of-breed functionality, they may face higher integration costs and weaker data coherence. This creates pressure for platforms that can balance breadth with usability. The likely outcome is a competitive environment where success depends on the ability to deliver a coherent experience across the stack, while still allowing flexibility for local operational needs. For executives evaluating vendors, the key is to assess not only what a platform can do in isolation, but how well it reduces complexity across the broader system of operations.
Future Outlook: Trends and Commercial Implications
Trend One: Unified, Throughput-Oriented Platforms
Over the next three to five years, one of the clearest trends is likely to be the continued shift toward unified platforms designed around throughput and order flow. In QSR, speed and accuracy are not marginal improvements; they are core to revenue protection and customer satisfaction. Platforms that coordinate ordering, kitchen execution, display, payments, and basic analytics within a connected workflow will have a structural advantage because they reduce handoffs and operational ambiguity. The commercial opportunity here is for vendors that can prove end-to-end impact rather than isolated feature value, and for operators that can standardize high-impact workflows without over-customizing to the point of fragility.
PW Consulting
The associated risk is over-engineering. Not every location needs the same level of automation or the same integration depth. If platforms become too rigid, they may struggle with diverse store formats, varying labor models, and local market differences. The winners will likely be those that offer strong core workflows while allowing controlled adaptation at the edges.
Trend Two: AI and Operational Intelligence as Standard Capabilities
AI and operational intelligence are likely to become standard expectations rather than differentiators in every category. Voice ordering, demand forecasting, labor optimization, and anomaly detection can improve throughput and reduce costly errors when applied well. As adoption accelerates, the differentiator will shift from whether a system includes AI to how reliably it performs in live conditions and how usable its outputs are for managers and staff. The commercial implication is that vendors will need to demonstrate robustness, transparency, and practical value, while operators will need to build internal capability to act on system-generated insights.
A key uncertainty is the pace and shape of AI value realization. Adoption may outpace the ability to integrate AI outputs into daily workflows, leading to underutilization or skepticism if results are inconsistent. In that scenario, the market may reward pragmatic deployments that solve specific operational problems over broad promises of intelligence. Decision-makers should therefore treat AI as an operational tool with measurable endpoints, not as a blanket upgrade.
Trend Three: Cost-Efficiency-Led Adoption and Flexible Architectures
Cost pressure and input volatility are likely to reinforce efficiency-led adoption. Technology purchases will increasingly be justified through labor productivity, waste reduction, order accuracy, and inventory control. This trend favors flexible architectures that can be deployed in phases, scaled across locations, and aligned with operational priorities instead of requiring full transformation upfront. The commercial opportunity is for solutions that can show a clear path from installation to measurable efficiency gains, and for buyers who structure deployments around high-return workflows first.
The related risk is that cost pressure may also delay adoption if returns are unclear or if implementation disruption is perceived as too high. In that environment, vendor credibility, referenceable outcomes, and low-friction rollout become critical. The market may divided between players who can evidence value quickly and those who rely on longer, less certain transformation narratives.
Strategic Implications for Decision-Makers
For Manufacturers and Technology Providers
Focus on workflow coherence and deployment confidence. In a market where integration complexity and change management are persistent barriers, the most defensible position is a solution that fits frontline operations, supports smooth migration, and delivers measurable throughput or efficiency gains. Product roadmaps should prioritize integration depth, role-based usability, and support models that reduce post-deployment friction. Where AI is involved, emphasize reliability, clear use cases, and manager-friendly outputs rather than broad claims of intelligence. Pricing and packaging should reflect the reality that operators evaluate total cost of ownership, not just upfront capability.
Worldwide Information Technology Market
For Investors
Evaluate market positions through the lens of scale, repeatability, and operational proof. The moderate concentration structure suggests room for differentiation, but durable advantage will likely come from platforms that can standardize across locations while maintaining flexibility, and from vendors that can evidence efficiency outcomes in high-volume environments. Pay attention to recurring revenue quality, renewal dynamics, and the ability to expand within existing accounts through additional modules or locations. Also consider exposure to cost and supply-chain volatility, since margin pressure can influence both adoption timing and vendor selection. The strongest investment theses are likely to be tied to platforms that reduce operational risk and demonstrate clear payback paths.
For Procurement and Operator Decision-Makers
Prioritize solutions that align with the highest-impact operational constraints in your environment. Start with workflows where technology can directly improve speed, accuracy, labor utilization, or inventory control, and sequence rollouts to limit disruption. Evaluate vendors on integration reliability, support responsiveness, and the usability of their systems for frontline staff and managers, not just on feature count. Where possible, structure deployments to generate visible operational improvements early, because early wins build internal confidence and support broader adoption. Given the pace of change and the range of vendor strategies, timely access to detailed segmentation data, vendor comparisons, and deployment benchmarks can materially improve decision quality. Detailed research that breaks down sub-segment dynamics and tailored implementation considerations can help ensure that procurement choices match both immediate operational needs and longer-term scalability goals.
The QSR IT market is expanding at a pace that rewards focused strategy. The winners in the next phase will likely be those who treat technology as an integrated operating capability, align investments with measurable efficiency outcomes, and build for flexibility in a cost-conscious, speed-driven environment. For organizations navigating this landscape, the most valuable next step is to ground decisions in detailed, segment-specific intelligence that connects market dynamics to concrete operational choices.
For detailed analysis of this topic, please visit the official page: Quick Service Restaurant (QSR) IT Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Power Liftgate Market: Why 7.6% CAGR Reshapes Competition by 2032
By pmarketresearch, 2026-09-21
Strategic Trends & Commercial Opportunities in the Automotive Power Liftgate Market
Market Trajectory: Growth, Structure, and Inflection Points
The automotive power liftgate market has entered a sustained expansion phase, transitioning from a premium convenience feature to a mainstream closure solution across multiple vehicle segments. Between 2020 and 2025, global market revenue climbed from approximately $163.15 million to $215.0 million, reflecting a compound annual growth rate (CAGR) of 7.6% projected through 2032. By the end of the forecast window, revenue is expected to surpass $344.8 million, signaling that power liftgate adoption is no longer confined to high-end SUV or crossover trims. The growth trajectory underscores a structural shift in how automakers approach rear and tailgate closure architectures: electrification of actuation, tighter integration with body electronics, and a growing emphasis on weight reduction and packaging efficiency.
Despite the positive trajectory, the market faces several critical challenges that will shape competitive outcomes over the next three to five years. First, supply chain volatility for critical raw materials introduces cost and production risk. Rare-earth magnet supply concentration in China affects permanent-magnet motor production used in power liftgate actuators, while copper price volatility directly impacts motor winding costs in brushless DC motor-driven spindle actuators. These input cost pressures compress margins for suppliers who lack multi-source strategies or material substitution capabilities. Second, regulatory and safety expectations are tightening. Safety regulations for power liftgate systems emphasize anti-pinch protection and integrated sensors for reliable operation across temperature ranges, and EU and global vehicle safety standards drive demand for energy-efficient electric actuation compatible with 48V/12V platforms. Compliance is no longer a baseline checkbox; it is becoming a differentiator that influences OEM platform decisions. Third, the market remains moderately fragmented, with a CR3 of 24.6% and CR5 of 26.2%, indicating that scale alone does not guarantee leadership. Suppliers that win are those offering validated system-level integration, not just discrete components.
PW Consulting
Key Drivers Reshaping the Power Liftgate Market
Electrification and actuator efficiency. The shift toward electrified closure systems is a primary growth engine. Brushless DC motor designs with high torque-density and position-controlled architectures are replacing simpler DC solutions in premium and high-volume applications. These designs improve reliability, reduce noise, and enable finer control over closing speed and pinch mitigation. At the same time, the market is seeing a move toward lightweight thermoplastic and composite solutions that reduce mass relative to conventional metal architectures. For EV programs, even modest weight savings at the rear closure contribute to range and packaging objectives, making liftgate design part of a broader vehicle efficiency equation rather than an isolated convenience feature.
Automotive Power Window Motor Market
Safety regulation and functional integration. Regulatory pressure is accelerating the convergence of actuation, sensing, and body electronics. Anti-pinch protection, occupant detection, and reliable operation across temperature extremes are increasingly expected as standard capabilities. This creates a demand pull for suppliers that can deliver integrated control electronics, proximity sensing, and fail-safe motor control within a single validated module. The practical effect is a move away from decentralized, component-level sourcing toward system-level partnerships where the supplier takes greater responsibility for functional safety, diagnostics, and calibration.
Consumer expectations and commercial use cases. On the demand side, power liftgates have become a decisive purchase attribute for passenger cars, particularly in segments where cargo utility and hands-free operation matter. In commercial vehicles, the value proposition shifts toward durability, repeated cycle reliability, and integration with fleet telematics or access control. The combined effect is broader demand across both passenger cars and commercial vehicles, with passenger car applications driving volume growth and commercial applications reinforcing the need for ruggedized designs and higher duty-cycle validation.
Supply chain reconfiguration and cost structure. Cost and resilience are increasingly intertwined. Suppliers are responding to raw material exposure by diversifying magnet sourcing, optimizing winding designs, and increasing the share of applications using composite or thermoplastic structures that reduce reliance on heavier metal stampings. At the same time, regional manufacturing footprints and local content expectations are reshaping sourcing strategies. The companies best positioned to protect margins are those that combine design flexibility with disciplined procurement and the ability to offer platform-sharing architectures across multiple OEM programs.
Competitive Landscape: Differentiation, Positioning, and Evolution
The competitive environment is defined by specialists and system integrators operating at different levels of the value chain. Brose Fahrzeugteile SE & Co. KG has reinforced its system-level positioning through concepts that combine ultra-wideband positioning and radar for automatic tailgate activation and occupant detection, illustrating a move toward contactless, context-aware closure experiences. Aisin Corporation continues to emphasize actuator and control electronics optimized for body closure in Asian OEM programs, where proximity sensors and integrated control strategies support high-volume, cost-sensitive applications. Magna International Inc. is advancing lightweight thermoplastic liftgate solutions that are materially lighter than conventional steel components, directly addressing EV efficiency and packaging constraints while offering a broader system module including electric actuators, hands-free detection, and integrated ECU.
Continental AG focuses on power closure systems, actuators, and anti-pinch motor control integrated with body electronics, aligning with the regulatory and functional safety trend. Huf Hulsbeck & Fürst GmbH & Co. KG brings strength in tailgate latches, actuators, and strikers with integrated closing functions and external actuator variants for reliable operation, which is especially relevant where latch integrity and serviceability are priorities. Stabilus GmbH differentiates through electric liftgate drive systems that combine gas-spring assistance with electromechanical actuation and position control, a hybrid approach that can balance force, stroke, and packaging demands. HI-LEX Corporation contributes power liftgate actuators and related electromechanical components for vehicle tailgates, often supporting suppliers and OEMs that require component-level flexibility. Strattec Security Corporation extends into power access systems including actuators, latches, and security modules integrated with vehicle access, opening adjacency opportunities where closure and access control converge. Johnson Electric Holdings Limited offers brushless DC motor and actuator assemblies with high torque-density and position-controlled designs, reinforcing the broader industry shift toward efficient, controllable actuation.
The market is evolving along two simultaneous paths: consolidation at the system level and specialization at the component level. Larger suppliers are expanding from actuation into full closure modules that span mechanics, electronics, sensing, and software integration. At the same time, smaller entrants and component specialists remain relevant where OEMs seek cost-optimized elements, regional supply support, or alternative architectural approaches. The strategic implication is that positioning matters more than scale alone. Suppliers that can articulate a clear system architecture, demonstrate validation rigor, and reduce integration risk for OEMs are gaining disproportionate influence in platform decisions.
Forward-Looking Trends and Commercial Implications
Trend 1: From liftgate actuation to intelligent closure experiences. Over the next three to five years, power liftgates will increasingly be evaluated as part of a broader closure and access experience rather than as a standalone motorized mechanism. Contactless activation, occupant detection, adaptive closing behavior, and integration with vehicle access ecosystems will move from premium niches toward broader deployment. The commercial opportunity lies in suppliers and OEMs that can bundle actuation with sensing, control software, and validation support, reducing the integration burden for vehicle programs. The main risk is that feature creep raises cost and complexity faster than consumers are willing to pay, especially in price-sensitive segments.
Trend 2: Lightweighting as a strategic necessity, not an option. Weight reduction will continue to gain priority as EV range, packaging, and platform sharing become more central to vehicle economics. Thermoplastic and composite liftgate solutions, along with refined metal architectures, will compete on a program-by-program basis. Suppliers that can deliver repeatable weight savings without compromising durability, safety, or repairability will find expanded relevance across both passenger and commercial platforms. The uncertainty here is material cost and long-term durability validation, particularly where novel structures interact with crash, latch, and environmental requirements.
Trend 3: Supply resilience and material strategy as competitive levers. Input cost exposure will remain a central management challenge. Rare-earth magnet concentration and copper volatility will continue to influence actuator cost structures, making material strategy, multi-source procurement, and design flexibility critical capabilities. Companies that can offer design variants, alternative magnet strategies, or architectures that reduce sensitivity to a single commodity will enjoy stronger negotiating position and more stable margin profiles. The risk is that supply disruptions or trade dynamics compress available options and lengthen qualification cycles for alternative materials.
Strategic Implications for Decision Makers
For component and system suppliers. Positioning should emphasize validated integration rather than discrete component performance alone. The most defensible value proposition combines actuator efficiency, anti-pinch and sensor integration, lightweight material options, and platform-sharing architectures that reduce OEM engineering burden. Suppliers should also treat raw material exposure as a design problem, not only a procurement problem, by developing actuator and latch variants that can adapt to magnet and copper cost dynamics without sacrificing functional performance.
Electric Tailgate Radar Market
For investors. The market’s 7.6% CAGR through 2032 suggests durable growth, but returns will likely accrue to companies with differentiated system capabilities, cost-resilient supply chains, and exposure to both passenger and commercial demand. Investment theses should weigh not only revenue momentum but also the ability to capture value from lightweighting, functional integration, and access-control adjacencies. Companies that remain dependent on a single commodity-intensive actuator architecture or a narrow OEM base carry higher sensitivity to input costs and program concentration.
For procurement and OEM strategy teams. Sourcing decisions should balance short-term cost against integration risk and compliance readiness. As safety expectations around anti-pinch protection, sensor reliability across temperature ranges, and energy-efficient actuation increase, qualification speed and documentation rigor become as important as unit pricing. Multi-source strategies, where feasible, and clear material substitution pathways can reduce exposure to magnet and copper volatility while preserving program timing.
The broader opportunity is to treat the power liftgate not as a late-stage convenience add-on, but as an integrated closure system that contributes to vehicle efficiency, safety compliance, and user experience. Achieving that shift requires timely insight into where material strategies, regulatory expectations, and OEM platform priorities are converging. For leaders who need deeper segment-level data, regional demand patterns, and customized scenario planning, PW Consulting’s full Automotive Power Liftgate Market research report provides the granular breakdowns and strategic frameworks needed to translate market momentum into concrete program and investment decisions.
For detailed analysis of this topic, please visit the official page: Automotive Power Liftgate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Steel Roofing Market Set to Hit $27B by 2032: 5 Key Drivers Behind the 6.5% CAGR Surge
By pmarketresearch, 2026-09-21
Steel Roofing Market: Navigating Growth, Resilience, and Strategic Opportunities Through 2032
The global steel roofing market has entered a period of sustained expansion, underpinned by durable construction demand, evolving material performance standards, and shifting sustainability expectations. Revenue reached approximately $17.3 billion in 2025, reflecting a broader trajectory that has seen the sector climb from roughly $12.7 billion in 2020. Over the full forecast window extending to 2032, the market is projected to advance at a compound annual growth rate of 6.5 percent, reaching a valuation near $27 billion by the close of the decade. This growth is not merely a function of incremental volume; it reflects structural repositioning in how steel roofing is specified, manufactured, installed, and repurposed across residential, commercial, and industrial applications. For decision-makers, the scale of expansion masks beneath the surface a set of nuanced transitions in product design, regional demand intensity, raw material exposure, and competitive positioning. Understanding these dynamics is essential for aligning capital allocation, product portfolios, and go-to-market strategies with the market's next phase of evolution.
市场现状与核心挑战
Steel roofing has matured from a utilitarian building component into a differentiated product category where longevity, weather performance, and recyclability increasingly factor into procurement decisions. The transition is visible in the steady upward revision of revenue estimates and in the way buyers are evaluating upfront costs against multi-decade service life. At a market concentration that leaves a substantial share of activity outside the top tier, the competitive space remains heterogeneous, with large-scale manufacturers, specialized formulators, and regional fabricators competing across different price and performance bands. This fragmentation is simultaneously a hallmark of resilience and a source of strategic friction, because buyers can choose from a wide spectrum of solutions, but vendors must navigate uneven margin structures and highly localized specification habits.
Three interconnected challenges define the current inflection point. The first is cost volatility tied to base material inputs. Market participants are operating in an environment where steel coil pricing has shifted sharply over recent periods, creating margin uncertainty for manufacturers and pricing complexity for distributors and end-users. The second challenge is the alignment of product standards with increasingly stringent performance expectations. Buyers and regulatory bodies are paying closer attention to structural integrity, water penetration resistance, and long-term durability, which elevates the importance of testing, certification, and engineering documentation in winning specification decisions. The third challenge is converting environmental advantages into commercial preference at scale. The category's recyclability and long service life are compelling claims, yet translating them into consistent demand requires more than technical merit; it depends on customer education, procurement frameworks, and the ability to demonstrate whole-life value in comparison with alternative materials.
These challenges are not obstacles that simply need to be survived. They are signals of where value is migrating. Manufacturers that can stabilize input exposure, demonstrate verifiable performance, and articulate lifecycle economics are positioned to capture share from competitors that continue to compete primarily on initial price. For investors and strategic planners, the implication is clear: the market's growth story is increasingly tied to capabilities in cost management, compliance readiness, and value communication rather than capacity expansion alone.
关键驱动因素分析
The expansion of steel roofing is being propelled by a set of reinforcing drivers that cut across technology, policy, demand behavior, and supply-side economics. Taken together, they are reshaping what buyers expect and what producers must deliver.
技术创新与产品性能演进
Product design innovation is moving steel roofing beyond conventional profiles toward systems that combine structural efficiency, installation practicality, and architectural versatility. Recent introductions such as new metal roofing panel designs reflect a broader push to improve compatibility with different substrates, climatic conditions, and aesthetic requirements. Parallel advances in accessory systems, including fall protection anchor solutions tailored to snap-lock panel installations, indicate that the differentiation frontier is expanding beyond the panel itself to the ecosystem of installation and worker safety. These developments matter because they lower adoption friction: when a roofing system is easier to specify, install, and maintain, specification cycles shorten and buyer confidence improves. For manufacturers, the strategic question is whether to compete through incremental design refinement or to lead with platform-level innovation that can serve multiple end-use segments without fragmenting production complexity.
政策、标准与监管环境
Regulatory and standardization activity is sharpening the performance baseline for steel roofing systems. Updated structural standards for standing seam roof panel systems and water penetration testing protocols are pushing the market toward more rigorous verification of durability and weathertightness. Rather than merely constraining the market, these standards are shaping a competitive environment in which documented compliance becomes a commercial asset. Specifiers in commercial and institutional projects, in particular, are increasingly relying on certified performance criteria to reduce project risk. In this context, manufacturers that maintain robust testing programs and clear alignment with recognized standards gain credibility that can translate into repeat specification and stronger positioning in tenders and design-led projects. The broader implication is that compliance is not a cost center to be minimized; it is a differentiator that can create defensible demand in segments where long-term performance is heavily weighted.
需求侧变化与行为迁移
On the demand side, procurement behavior is increasingly influenced by the combination of lifespan expectations and end-of-life recyclability. Steel roofing's long average service life and full recyclability at end of use resonate with buyers who are evaluating whole-project economics rather than first-cost alone. This shift is especially relevant in markets where replacement cycles, maintenance exposure, and disposal considerations are receiving greater attention. Residential applications continue to play a major role in volume, supported by replacement demand and aesthetic upgrading, while commercial and industrial users are prioritizing reliability, standardized performance, and ease of integration with broader building systems. The trend is not uniform across segments, but the directional signal is consistent: buyers are more receptive to durable solutions when the value case can be framed in terms of lifecycle cost, reduced maintenance exposure, and material circularity.
供应链与成本结构的调整
Supply-side dynamics are exerting both pressure and opportunity. Elevated hot rolled coil steel prices relative to prior-year levels illustrate how raw material cost movements can compress margins and trigger price adjustments downstream. At the same time, cost pressure is encouraging operational discipline, including improved yield management, product mix optimization, and closer coordination between fabrication capacity and demand geography. The market's response to input volatility is revealing which players have invested in flexible production arrangements, inventory strategy, and contracting models that can absorb price fluctuations without sacrificing competitiveness. For the sector as a whole, cost structure is becoming a strategic variable as important as product features, because the ability to manage cost pass-through, protect margin integrity, and maintain service continuity will influence both share stability and customer retention.
These four drivers are not independent. Technology improvements influence specification under stricter standards; performance credibility strengthens demand-side adoption; and cost discipline determines whether innovation and compliance investments can be scaled profitably. The market is rewarding participants that treat these elements as an integrated system rather than as separate workstreams.
竞争格局与领先策略
The competitive landscape is populated by manufacturers with distinct reputations across residential, commercial, and industrial end-use markets. Several large U.S.-based producers have established positions through broad product line breadth, established distribution relationships, and strong brand familiarity among contractors and specifiers. Their scale allows them to serve multiple application types, which is valuable in a market where project types vary widely and where the ability to offer related panels, accessories, and system-level components can reduce procurement complexity for buyers. Alongside these broader specialists, other manufacturers have built identities around particular product strengths, such as stone-coated aesthetics, architectural detailing, or commercial panel solutions. This mix of scale players and specialized producers creates a layered competitive environment in which differentiation often comes from the fit between product attributes and project requirements rather than from price alone.
Leading strategies in this environment tend to converge around a few recognizable approaches. One is portfolio breadth that enables cross-application coverage, allowing a manufacturer to capture demand from a single customer or specification source across multiple project types. Another is product-line specialization, where a narrower range is developed to a higher level of performance or visual refinement, supporting premium positioning and repeated specification in targeted segments. A third approach is ecosystem development, including accessories and installation-support solutions that make a roofing system more practical to deploy and maintain. The recent introduction of new panel series and fall protection anchor systems illustrates this ecosystem-oriented thinking: companies are increasingly aware that winning in steel roofing is not only about the panel, but also about the installation context and the safety, speed, and reliability of the overall system.
Worldwide Roofing Market
The competitive trajectory is likely to involve both consolidation and continued segmentation. Consolidation can create advantages in procurement leverage, manufacturing efficiency, and geographic coverage, particularly for players seeking to scale their position against volatile input costs and rising compliance expectations. At the same time, segmentation is expected to persist because project-specific requirements, regional specification habits, and design preferences continue to reward targeted solutions. New entrants and smaller manufacturers can still find room by focusing on underserved niches, specialized coatings or finishes, or regionally concentrated customer relationships. The more durable competitive threat may come not from sheer capacity, but from organizations that combine credible performance documentation, stable cost management, and clear installation value into a repeatable commercial proposition.
A useful way to read the competitive field is to ask where each player is most difficult to displace. For some, it is breadth and supply reliability; for others, it is a particular performance profile or design language; for still others, it is the strength of contractor and distributor relationships. The companies that are expanding their strategic options are generally those that are reducing customer switching costs in positive ways, by offering integrated system solutions, clearer performance evidence, or more predictable commercial terms.
未来趋势预测
Looking across the next three to five years, three trends are likely to shape how the steel roofing market evolves and where profitable opportunities emerge.
PW Consulting
性能验证与标准契合度将成为获胜因素
As specification practices become more risk-aware and performance expectations tighten, verifiable durability and water penetration performance will increasingly influence procurement decisions. The trend favors companies that can provide clear documentation, repeatable testing alignment, and engineering support that simplifies specification. The commercial opportunity lies in turning standards compliance into a reliable source of preference, particularly in commercial and institutional segments where project risk reduction carries substantial weight. The associated uncertainty is that compliance expectations may continue to rise, requiring sustained investment in testing infrastructure and technical sales capability.
循环经济与寿命优势的商业化将加速
The combination of long service life and full recyclability is well suited to growing interest in material efficiency and end-of-life responsibility. Over the forecast period, more buyers are likely to frame roofing decisions around lifecycle value, maintenance exposure, and material recovery, especially where procurement mandates or corporate sustainability objectives are in play. The opportunity is to build value narratives that connect technical performance with circularity in a way that procurement teams can act upon. The risk is that environmental attributes may be overstated or undervalued depending on local market maturity, meaning that claims must be matched with clear proof points and credible comparison frameworks.
成本韧性将区分领导者与追随者
Raw material price sensitivity is expected to remain a persistent feature of the operating environment. Companies that can manage input exposure through mix strategy, production discipline, and transparent commercial terms will be better positioned to preserve margin integrity while sustaining volume growth. This creates a strategic opportunity for manufacturers and supply partners that can offer predictability, whether through product configurations that optimize yield, contracting structures that share risk responsibly, or regional production footprints that reduce freight and inventory burden. The uncertainty is that cost volatility can reshape comparative advantage quickly, and players that depend on narrow margin buffers may face pressure if input trends shift materially.
These trends point toward a market in which growth is increasingly earned through credibility, efficiency, and integration rather than through volume alone. For businesses evaluating their next moves, the most valuable question is not whether the market will expand, but which capabilities will determine who captures the higher-value portions of that expansion.
决策者行动建议
Different participant types will derive value from different strategic priorities, but several practical actions apply across the board.
Metal Roofing Market
-
For manufacturers, invest in the intersection of product performance, installation practicality, and cost discipline. That means maintaining rigorous testing and standards alignment, expanding system-level accessories that reduce installation friction, and improving production flexibility to respond to input volatility without eroding margin. Companies that can present steel roofing as a coherent, low-friction solution rather than a commodity panel are better positioned to defend price and win repeat specification.
-
For investors, evaluate exposure to the segments and capabilities most likely to benefit from durability-driven demand and lifecycle value framing. Look for operators with credible compliance documentation, diversified end-use reach, and operational strategies that can withstand raw material swings. The opportunity is strongest where growth is supported by structural demand and where differentiation is built on verifiable performance and efficient cost management rather than on temporary input advantages.
-
For procurement and specifier teams, broaden the evaluation framework beyond first cost. Give appropriate weight to service life, maintenance exposure, water penetration and structural performance evidence, and material recyclability. Where possible, standardize on solutions that reduce project risk and installation complexity, and request documentation that supports whole-life comparisons. This approach can improve project outcomes and reduce downstream exposure to performance-related issues.
In a market expanding at a steady multi-year pace, the practical edge comes from access to granular insight: which product segments are expanding fastest, how regional demand intensity is shifting, where price and margin pressure is concentrated, and how leading competitors are positioning their portfolios. Detailed segmentation, scenario modeling, and competitor-level benchmarking can sharpen those decisions and reduce the risk of acting on averages rather than on the segments that matter most. For teams that want to move from high-level awareness to targeted action, a deeper review of the full research can provide the segmented detail and customized context needed to prioritize investments, pricing strategy, specification support, and regional expansion with greater precision.
For detailed analysis of this topic, please visit the official page: Steel Roofing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Low Pressure Molding Polyamides Market 2026: Beyond the 7.5% CAGR Story
By pmarketresearch, 2026-09-21
The Strategic Evolution of Low Pressure Molding with Polyamides: Market Outlook and Commercial Opportunities
The low pressure molding (LPM) with polyamides sector has transitioned from a niche encapsulation technique to a strategic manufacturing capability across multiple high-value industries. Between 2020 and 2025, the global market expanded from approximately 118 million USD to 192 million USD, establishing a base for sustained growth. Forward-looking projections through 2032 indicate a compound annual growth rate of 7.5 percent, positioning the total addressable market to exceed 320 million USD within the forecast horizon. This trajectory reflects a structural shift in how engineers approach component protection, miniaturization, and sustainability compliance rather than a temporary production cycle fluctuation. For executives and investors evaluating advanced manufacturing materials, the numbers themselves tell only part of the story. The underlying value lies in understanding how formulation chemistry, equipment engineering, regulatory pressure, and end-use demand are converging to reshape commercial positioning.
Despite the clear growth momentum, the industry operates at a critical inflection point. Three structural challenges demand strategic attention. First, raw material supply volatility continues to create margin pressure, as specialty polyamide feedstocks and performance additives experience periodic shortages and pricing swings that complicate long-term planning. Second, regulatory tightening around volatile organic compound emissions, particularly across Europe and China, is forcing material suppliers to redesign formulations without sacrificing thermal stability, adhesion reliability, or processing speed. Third, the high initial capital outlay for compatible LPM equipment, combined with the premium cost of engineered polyamide compounds, remains a barrier for mid-tier manufacturers who recognize the performance benefits but struggle to justify the investment against legacy potting or traditional molding alternatives. These pressures are not transient obstacles; they are forcing a market recalibration where operational efficiency, material sustainability, and total cost of ownership will determine which participants capture durable share.
Key Drivers Reshaping the Market Trajectory
Several interconnected forces are accelerating adoption and redefining how value is created in the low pressure molding with polyamides ecosystem. Understanding these drivers is essential for anticipating where capital, capability, and competitive advantage will concentrate over the next several years.
PW Consulting
Technical Innovation in Materials and Processing Systems
Material science and equipment engineering are advancing in tandem, creating compounding productivity gains. Polyamide-based hot melt compounds are being optimized for lower processing temperatures, faster cycle times, and enhanced mechanical resilience, while LPM machinery platforms are being upgraded to deliver tighter process control and reduced energy consumption. Recent system upgrades in the industry have demonstrated efficiency improvements approaching 28 percent alongside energy reductions near 20 percent, illustrating how hardware and chemistry improvements reinforce one another. Equally significant is the expansion into specialized performance grades. New polyamide formulations designed for medical device encapsulation have shown durability increases around 24 percent and equipment failure rate reductions near 16 percent, opening doors to higher-margin regulated applications. In automotive contexts, high-strength molding compounds introduced in late 2024 have boosted demand by roughly 25 percent while cutting defect rates by 15 percent, signaling that material performance gains can directly translate into production yield improvements and lower warranty exposure.
Regulatory and Sustainability Pressures as Catalysts
Environmental regulation is no longer a compliance footnote; it is becoming a primary procurement driver. The European Chemicals Strategy for Sustainability and China's Green Manufacturing Standards are reshaping acceptable formulation parameters for polyamide hot melts used in low pressure molding. Compliance now requires meaningful reductions in VOC emissions and, increasingly, measurable progress toward circularity. This regulatory trajectory is pushing suppliers toward bio-sourced feedstocks and recyclable compound architectures. One notable industry example demonstrated a bio-based polyamide launch that reduced emissions by 20 percent and improved recycling rates by 18 percent within electronics applications, establishing a benchmark for what sustainability-compliant processing can achieve. For manufacturers and specifiers, these regulatory shifts create a dual imperative: investments in cleaner formulations protect market access, while proactive sustainability positioning can become a competitive differentiator in tenders where environmental criteria carry increasing weight.
Demand-Side Shifts Across End-Use Markets
The demand landscape is being restructured by electrification, miniaturization, and reliability expectations across discrete industries. Electronics remains the largest application segment, driven by the ongoing need to protect densely packed PCBs, sensors, and connectors from moisture, thermal stress, and mechanical shock. Automotive demand is intensifying as vehicle architectures incorporate more power electronics, battery-adjacent components, and advanced driver-assistance systems that require robust encapsulation without adding significant mass or thermal resistance. Appliance and industrial automation applications are expanding more gradually, but they are benefiting from the same overarching themes: tighter space constraints, higher operating temperatures, and a preference for process methods that minimize post-mold finishing. The common thread across these sectors is that LPM with polyamides is increasingly viewed as a solution that combines protection, automation compatibility, and material efficiency in a single step, reducing downstream assembly complexity.
Supply Chain and Cost Structure Dynamics
Cost structures are evolving as the industry matures. While the upfront expense of polyamide compounds and compatible molding equipment remains a consideration, the total cost calculus is shifting when yield improvement, rework reduction, and energy efficiency are factored in. At the same time, feedstock volatility and additive availability continue to introduce uncertainty into production scheduling and pricing strategies. Companies that are building more resilient supplier relationships, standardizing compound specifications across product families, and investing in process control are better positioned to absorb input cost fluctuations without eroding margins. The strategic lesson is clear: procurement and manufacturing strategy can no longer be treated separately. In this market, material sourcing decisions directly influence process stability, quality consistency, and ultimately, the economic justification for adopting LPM at scale.
Competitive Landscape and Strategic Positioning
The competitive environment in low pressure molding with polyamides is characterized by a mix of established adhesive and materials giants, specialized compound developers, and equipment-focused system providers. Market concentration indicates that a relatively small group of participants commands a significant share of revenue, with the top three firms accounting for approximately 46 percent and the top five reaching around 68 percent. This concentration reflects the technical barriers to entry, the importance of validated performance in demanding applications, and the value of integrated offerings that span materials, equipment know-how, and application support.
Leading players are differentiating through distinct strategic vectors. One major global materials company has built its position around recognized hot melt adhesive platforms for electronics, medical, industrial automation, HVAC, and lighting encapsulation, leveraging brand trust and broad application coverage. Another key competitor has leaned into sustainability and vertical application strength, offering polyamide hot melt adhesives based on substantial bio-sourced content and expanding into high-strength automotive molding compounds that directly address yield and defect performance. Regional and specialized players are carving out space through equipment compatibility, localized service, and targeted compound development. Several suppliers focus on polyamide hot melt compounds engineered specifically for LPM systems, while equipment-oriented firms emphasize machine design, process optimization, and integration support that reduce the learning curve for manufacturers transitioning from traditional methods.
Recent industry developments highlight how quickly competitive advantage can shift when technical execution aligns with market needs. System upgrades have improved throughput and energy efficiency, bio-based launches have advanced sustainability credentials in electronics, product line expansions have strengthened automotive demand and quality outcomes, and specialized medical-grade polyamides have enhanced durability and reliability. These moves demonstrate that the market rewards participants who can simultaneously deliver material performance, processing efficiency, and application-specific validation. Looking ahead, the landscape is likely to evolve through a combination of consolidation among materials and adhesive players seeking broader portfolios, continued differentiation by equipment and compound specialists capturing regional or vertical niches, and potential new entry from organizations that can bridge formulation chemistry with automated encapsulation systems. The companies that will lead are those that treat LPM not merely as a material sell, but as an integrated process solution with measurable operational and sustainability returns.
Forward-Looking Trends and Commercial Implications
The next three to five years will likely be defined by a small number of high-impact trends that connect technical progress with commercial opportunity. Anticipating these trends allows decision-makers to prioritize investments, shape procurement strategies, and identify where new value can be captured.
- Sustainability-driven formulation leadership will become a market access requirement and a sales advantage. As regulatory expectations around emissions and circularity tighten, polyamide compounds that demonstrate lower VOC profiles, bio-sourced content, and improved recyclability will be preferred in regulated electronics, automotive, and medical applications. Suppliers and manufacturers that standardize sustainable grades early will reduce reformulation risk and position themselves favorably in procurement evaluations where environmental criteria are increasingly quantified.
- Process integration and smart manufacturing will deepen the value proposition of LPM systems. Equipment upgrades that improve yield, cut energy use, and enable tighter process control are already delivering measurable efficiency gains. Over the forecast period, the integration of real-time monitoring, predictive maintenance, and closed-loop process adjustments is expected to further reduce variability and support higher-volume production. Manufacturers that invest in compatible equipment and data-driven process control can convert material performance into repeatably lower cost per protected unit, strengthening the economic case for LPM adoption.
- Application expansion into higher-margin regulated segments will accelerate. Medical device encapsulation and advanced automotive electronics represent areas where durability, failure reduction, and compliance documentation carry substantial commercial weight. Materials and systems that can prove enhanced reliability and meet sector-specific standards will command premium positioning. The opportunity here is not simply incremental volume growth but a shift toward applications where performance validation and regulatory readiness create higher barriers to competition and more resilient pricing power.
These trends carry inherent uncertainties. Feedstock volatility can disrupt cost planning and production continuity, particularly when specialty additives or specific polyamide variants face constrained availability. Regulatory evolution may outpace formulation development in some regions, creating temporary compliance gaps that affect time-to-market. In addition, the capital intensity of equipment and engineered compounds may slow adoption among cost-sensitive manufacturers unless the total cost benefits are clearly demonstrated through pilot programs and lifecycle economics. Organizations that monitor these variables closely and build flexibility into their sourcing, formulation, and equipment strategies will be better equipped to navigate shifts without losing competitive momentum.
Polyamide Hot Melt Adhesives Market
Strategic Actions for Decision-Makers
Translating market dynamics into concrete decisions requires a clear view of where to allocate attention and resources. The following recommendations are tailored to the primary audiences evaluating low pressure molding with polyamides.
For Manufacturers and Process Engineers
Prioritize pilot-scale validation that measures total cost of ownership rather than material price alone. Quantify yield improvements, rework reduction, energy consumption, and cycle-time changes when evaluating polyamide compounds and LPM equipment. Where possible, standardize compound specifications across product families to simplify procurement and reduce exposure to feedstock volatility. Invest in operator training and process control capabilities early, as the performance advantage of LPM is often realized through repeatable process execution rather than material selection in isolation. For manufacturers serving regulated sectors, establish documentation and compliance pathways for sustainable formulations to protect future market access.
Thermoplastic Polyamide Market
For Investors and Strategists
Focus on participants that combine material innovation with equipment compatibility and application-specific validation, as integrated solutions are earning share in a concentrated market. Pay attention to companies expanding into bio-based or high-strength grades that address automotive and medical demand, since these segments offer stronger margin resilience and clearer differentiation. Monitor consolidation signals and regional expansion patterns, particularly where localized compound development or equipment support can reduce lead times and improve customer retention. When evaluating opportunities, weigh feedstock supply resilience and regulatory readiness as much as current revenue, because these factors will increasingly determine long-term competitiveness.
For Procurement and Supply Chain Leaders
Treat material sourcing as a strategic lever rather than a transactional function. Develop dual or multi-source strategies for critical polyamide feedstocks and additives to mitigate volatility, and work with suppliers to lock in quality specifications that align with downstream process requirements. Where sustainability criteria are entering tender evaluations, require transparent formulation data and recycling or emissions performance indicators, not just price benchmarks. Collaborate with R&D and manufacturing teams to align procurement decisions with process goals, ensuring that material choices support cycle-time targets, defect reduction, and compliance obligations simultaneously.
The market for low pressure molding with polyamides is moving beyond a phase of basic adoption into one where formulation sophistication, process efficiency, sustainability compliance, and application-specific validation determine commercial outcomes. Executing effectively in this environment requires access to granular segmentation data, competitive benchmarking, and scenario-based planning that go beyond headline market size and growth rates. For decision-makers seeking to refine entry timing, portfolio focus, or supply strategy, a detailed research report can provide the segmented revenue breakdowns, company-level positioning maps, and forward indicators needed to convert these strategic themes into precise, executable plans.
For detailed analysis of this topic, please visit the official page: Low Pressure Molding with Polyamides Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vehicle Routing and Scheduling Market: How 4.03% CAGR Planning Redefines Logistics Strategy
By pmarketresearch, 2026-09-21
Vehicle Routing and Scheduling Market: Strategic Trends and Commercial Opportunities in the Age of Intelligent Logistics
The global vehicle routing and scheduling market has entered a phase of structural transformation where route planning is no longer a back-office optimization problem but a core operational driver of margin protection, service reliability, and carbon accountability. Valued at approximately USD 12.01 billion in 2025, the market is projected to reach USD 15.83 billion by 2032, expanding at a compound annual growth rate of roughly 4.03% over the 2026–2032 forecast window. This trajectory reflects a market that is maturing in terms of software adoption, yet simultaneously becoming more complex as operational, regulatory, and technological pressures converge. For executives, investors, and procurement leaders, the strategic implication is clear: routing and scheduling capabilities are increasingly intertwined with broader freight visibility, workforce management, and sustainability commitments. The companies and fleets that treat route intelligence as a standalone tool will find diminishing returns; those that embed it into real-time operational workflows will gain measurable advantages in cost per mile, asset utilization, and service consistency.
The market expansion is not uniform across time or activity. Growth has been shaped by a combination of post-pandemic logistics normalization, rising last-mile complexity, and the gradual shift from static planning models toward more adaptive, data-driven scheduling. Historical demand between 2020 and 2025 illustrates this arc: modest recovery in the early years gave way to stronger operational investment as organizations attempted to absorb volatility in labor availability, freight volumes, and customer expectations. The forecast period onward suggests continued expansion, though not without intermittent adjustments as enterprises recalibrate spending, vendors refine product-market fit, and buyers weigh the total cost of ownership against promised efficiency gains. In this context, the market is best understood as a space where incremental efficiency improvements can compound into meaningful competitive differentiation, especially for operators managing large fleets, multi-stop delivery networks, or time-sensitive service schedules.
Market Landscape and Core Challenges
Where the Market Stands Today
Today’s vehicle routing and scheduling market is defined by a broad shift from fixed, pre-planned routes to systems that can respond to changing conditions throughout the day. Enterprises are no longer satisfied with tools that optimize once at the start of a shift; they increasingly expect platforms that can incorporate live traffic patterns, service-window constraints, driver availability, and real-time exceptions. That expectation is pushing vendors to integrate routing logic more tightly with telematics, transportation management, and field service workflows, rather than offering routing as an isolated module.
At the same time, the market remains meaningfully concentrated. A relatively small group of established providers accounts for a substantial share of enterprise adoption, while a wider field of specialist and emerging players competes on usability, vertical-specific features, or deployment speed. This split matters because it shapes how quickly innovation reaches different buyer segments. Large platforms tend to emphasize integration depth, security, and enterprise governance, while smaller or more focused vendors often move faster on user experience, specialized optimization logic, or rapid onboarding for particular use cases. The result is a market where the value proposition increasingly depends on context: the right solution for a global freight operation may differ substantially from the right solution for a regional field-service organization or a high-density urban delivery network.
Key Challenges and Decision Points
Several intersecting challenges are shaping the market’s near-term direction.
-
Operational variability versus planning stability. Route optimization becomes harder as conditions grow less predictable. Traffic disruptions, weather events, shifting delivery windows, and vehicle availability issues all create exceptions that can quickly erode the value of a theoretically optimal plan. The challenge for buyers is not simply to buy an optimizer, but to choose systems that can re-plan quickly without destabilizing the day’s operations or overwhelming dispatchers with constant changes.
PW Consulting -
Regulatory and compliance complexity. Route scheduling does not operate in a vacuum. Driving-hour restrictions, emission-sensitive zones, load limits, toll structures, and vehicle-type restrictions differ across regions and can materially affect feasible routing choices. As regulatory expectations tighten in various markets, route planning tools must account for compliance constraints while still supporting efficiency goals. This creates a tension that many operators are still learning to manage: optimizing for cost or speed in a way that does not inadvertently create compliance exposure or operational friction.
-
Labor cost pressures and workforce constraints. Labor remains one of the largest cost categories for fleet operators when routes are planned manually or managed through fragmented tools. At the same time, driver availability and retention have become strategic concerns in many markets. This combination is pushing organizations to seek routing and scheduling systems that can reduce unnecessary miles, balance workload more effectively, and support Hours of Service and driver-availability considerations. The operational prize is twofold: lower direct cost and a more sustainable workflow for drivers, which can matter just as much in a tight labor environment.
-
Data security, privacy, and system trustworthiness. Routing platforms increasingly touch sensitive operational, customer, and location data. As a result, security and privacy concerns have become a more visible part of the buying decision. Enterprises are paying closer attention to breach risk, governance, and regulatory compliance, particularly where routing data is integrated with broader logistics or customer-facing systems. Trust and reliability are no longer secondary considerations; they are part of the platform’s commercial viability.
Key Demand Drivers Shaping the Market
Technology Innovation and Optimization Maturity
A central driver of market growth is the continued maturation of optimization technology itself. Route planning has evolved from relatively static, rules-based approaches toward systems that can absorb more variables, adapt more quickly, and support more granular operational decisions. Dynamic re-optimization, in particular, has moved from a differentiating feature to an expectation in many use cases. When a dispatcher can adjust routes in response to a delayed vehicle, a new order, or a service-window change without rebuilding the entire day’s plan, the operational value is considerable.
The practical impact of this shift is visible in how vendors are packaging routing capabilities. Some are embedding route optimization inside broader logistics and transportation platforms, making it part of a continuous operational flow rather than a separate planning step. Others are pairing optimization engines with telematics and field-data capture so that scheduled plans can be compared against actual execution, creating feedback loops that improve future planning. This convergence is important because it moves routing from a static efficiency exercise toward a more measurable, iterative capability.
Policy, Regulation, and Compliance Pressure
Policy and regulatory environments are influencing both the demand for routing software and the functionality that buyers require. Driving-hour rules, regional load and vehicle restrictions, emission zones, and toll regimes can all affect which routes are viable and how schedules should be structured. In markets where these constraints are especially varied or evolving, routing tools that can encode compliance logic directly into scheduling decisions have a stronger value proposition. This is not only about avoiding penalties; it is also about reducing the operational burden of managing complex rule sets manually.
For multinational operators and cross-border logistics providers, the regulatory dimension adds another layer of importance. Different jurisdictions can impose different constraints on heavy vehicles, urban access, driver working time, and environmental performance. In such environments, routing and scheduling software becomes a mechanism for standardizing operational decision-making across regions while still respecting local constraints. That capability is increasingly relevant as supply chains and service networks become more geographically diversified.
Demand-Side Changes in Customer and Enterprise Behavior
Demand-side behavior is also reshaping the market. Customers across both consumer and business segments increasingly expect more accurate delivery or service-time predictions, faster response to exceptions, and greater transparency in logistics operations. Those expectations raise the stakes for routing and scheduling because they connect operational planning directly to customer experience. A plan that is mathematically efficient but fragile in execution may not satisfy service expectations once real-world disruptions occur.
In parallel, many enterprises are under pressure to improve not just service levels but also asset productivity and environmental performance. Route optimization supports both objectives by reducing empty miles, tightening stop sequencing, and helping organizations make better use of existing vehicles and drivers. In that sense, routing and scheduling is becoming part of a broader operational narrative around doing more with constrained assets while improving consistency and reliability.
Supply Chain and Cost Structure Pressures
Cost structure dynamics continue to influence adoption. When labor, fuel, maintenance, and compliance costs rise or become more volatile, the value of better routing becomes more visible. Even modest reductions in unnecessary miles or unproductive downtime can translate into meaningful operational savings across a large fleet or high-frequency delivery operation. This is why routing optimization is often evaluated not as a discretionary software purchase but as a lever for protecting margins in an environment where many cost inputs are difficult to control.
The same pressure is encouraging integration with broader cost and performance management. Organizations are increasingly interested in solutions that can link route decisions with fuel consumption, driver scheduling, vehicle maintenance windows, and service-level outcomes. The more routing is connected to these surrounding processes, the more it can contribute to total operating efficiency rather than isolated route improvements.
Competitive Landscape and Leading Strategies
How the Market Is Structured
The competitive landscape reflects a mix of large enterprise platforms, specialized optimization vendors, telematics-rich fleet solutions, and regional or vertically oriented providers. This diversity is one of the market’s defining features. Large platforms typically compete on breadth: integration with broader ERP, transportation, or supply chain systems, enterprise governance, security posture, and the ability to support complex global operations. Specialist and mid-tier vendors often compete on speed, usability, targeted optimization logic, and the clarity of their solution for a specific operational context.
Several organizations stand out for the way they position routing and scheduling within their broader portfolios. Descartes Systems Group emphasizes routing and dispatch capabilities oriented around logistics and distribution workflows. Oracle and SAP embed vehicle routing and scheduling within broader transportation management and fleet scheduling environments, appealing to enterprises that want routing to operate as part of a unified operational backbone. IBM supports routing and scheduling through supply chain and logistics platforms, targeting organizations that value integrated intelligence across planning and execution. Manhattan Associates has expanded route optimization within its broader logistics software ecosystem, reflecting a strategy of connecting routing more tightly to warehouse, order, and delivery execution.
There is also a notable presence of telematics-oriented and fleet-focused providers. Samsara, Verizon Connect, Fleet Complete, and Geotab integrate route optimization with telematics and fleet-management capabilities, which can be especially compelling for operators that want scheduling decisions linked to vehicle location, driver behavior, and real-time operational data. Locus highlights multi-fleet planning and real-time dynamic re-optimization for enterprise use cases, while Routific, Route4Me, and OptimoRoute are commonly associated with delivery-oriented route planning and optimization. e2open and Trimble round out the landscape with solutions that connect routing and scheduling to broader transportation, last-mile, and logistics workflows.
Differentiation and Strategic Positioning
The market’s competitive dynamics are increasingly shaped by differentiation in a few key areas.
-
Integration depth. Providers that connect routing to other operational systems have an advantage in environments where plans must flow directly into execution. Integration with transportation management, telematics, order management, or field-service platforms reduces the friction between planning and doing, which is often where the greatest operational value is realized.
-
Real-time adaptability. The ability to re-optimize quickly, without disrupting the entire schedule, is becoming a critical differentiator. Vendors that can handle live exceptions, reorder stops, and rebalance routes as conditions change are better positioned for complex, high-variability operations.
-
Vertical and use-case fit. Routing and scheduling needs differ substantially by application. Public transportation, freight and logistics, field service management, emergency services, and healthcare transportation all impose different constraints and priorities. Providers that tune their optimization logic, user experience, and integrations to specific use cases can stand out even in a crowded market.
Carpooling Market -
Compliance and operational governance. Solutions that make it easier to manage driving-hour rules, regional restrictions, and other compliance considerations are gaining relevance, particularly where regulatory variation is high. This is not just a legal matter; it is an operational design issue that affects how workable a schedule is in practice.
-
Deployment and usability. In many buyer segments, implementation speed and dispatcher usability matter as much as algorithmic sophistication. Tools that are easier to adopt and train can deliver value sooner, which is especially important for organizations that need to improve operations quickly without large transformation programs.
How the Landscape Is Evolving
The market is evolving along multiple axes at once. One trend is convergence, as routing capabilities become more embedded in larger logistics, telematics, and transportation platforms. This makes sense operationally, because route planning is most powerful when it is connected to real-time execution data and broader business processes. Another trend is fragmentation at the specialist level, where smaller or more focused providers continue to emerge around specific delivery models, regional markets, or vertical needs. Finally, there is ongoing consolidation pressure among enterprise buyers, who increasingly prefer fewer, better-integrated systems over a patchwork of point solutions.
Together, these dynamics suggest that competition will not be decided by optimization quality alone. The winners in different segments will likely be those that combine sound routing logic with strong integration, practical usability, compliance awareness, and credible security and data governance. In market terms, that means some providers will grow by extending into broader operational platforms, while others will compete by dominating a specific use case or deployment profile with exceptional fit and speed.
Future Outlook: Strategic Trends for the Next 3–5 Years
Trend 1: Routing as a Real-Time Operational Capability
Over the next several years, routing and scheduling is likely to become less about planning a day in advance and more about continuously managing a living operation. Dynamic re-optimization, exception handling, and live feedback from telematics and execution systems will increasingly define the value of a platform. For commercial operators, this means routing will matter not only at the start of a shift, but throughout the day as conditions change. The opportunity is to reduce operational drag: fewer cascading delays, better recovery from disruptions, and higher percentages of stops or services completed within intended windows.
The associated risk is that real-time capabilities can create complexity if they are not designed well. Constant replanning can overwhelm dispatchers and drivers if the system lacks clear priorities, thresholds, and human-in-the-loop controls. The most successful deployments will likely be those that balance automation with operational governance, so that optimization improves stability rather than creating noise.
Trend 2: Compliance-Aware, Sustainability-Linked Scheduling
Regulatory and sustainability pressures are expected to keep rising as planning constraints. Emissions considerations, urban access rules, driving-hour compliance, and vehicle restrictions will not remain niche concerns; they will become embedded in how feasible routes are defined and evaluated. This creates an opportunity for routing and scheduling tools to serve as a dual-purpose asset: improving efficiency while also supporting compliance and environmental objectives. In many operations, that combination is becoming more valuable than pure cost minimization.
At the same time, there is uncertainty in how regulations will evolve across regions and how consistently organizations can operationalize sustainability goals alongside service and cost targets. Market participants should expect continued variation in the pace and shape of requirements, which will favor flexible platforms over rigid ones.
Trend 3: Smarter Integration With Workforce, Telematics, and Execution Data
A third major trend is the deepening connection between routing and the systems that surround it. Telematics, driver scheduling, order or service data, and execution analytics will be more tightly linked to route decisions. This matters because routing outcomes are only as useful as the operational feedback loop that follows. When planned routes are compared with actual performance, organizations can refine constraints, identify recurring exceptions, and improve future schedules. Over time, this turns routing into a continuously improving capability rather than a one-time optimization exercise.
The opportunity here extends beyond technology. Organizations that invest in data quality, operational discipline, and clear performance metrics will benefit more from advanced routing than those that simply install a better optimizer. The technology amplifies operational intent; it does not replace it.
Strategic Implications for Decision Makers
For Fleet Operators and Logistics Providers
Operators should evaluate routing and scheduling as part of a broader operational architecture rather than as a standalone efficiency tool. The highest returns typically come when route optimization is connected to real-time execution data, dispatcher workflows, and compliance requirements. A practical approach is to prioritize solutions that can handle dynamic exceptions, support driver and vehicle constraints, and integrate with existing telematics or transportation systems without creating new data silos.
Ride Sharing Market
Equally important is realistic scoping. Different operations need different levels of sophistication. A high-density urban delivery network may benefit most from frequent re-optimization and tight time-window control, while a field-service organization may need stronger scheduling integration around technician availability and service priorities. Matching the tool to the operational model is often more important than selecting the most feature-rich platform.
For Technology and Software Investors
Investors should look for differentiation that is defensible in practice, not just in product descriptions. The most durable opportunities tend to sit where routing is tightly integrated with surrounding workflows, where compliance and security requirements create meaningful barriers, and where execution feedback improves outcomes over time. Niche fit can be valuable, but scaling often depends on the ability to connect routing to broader platforms or to serve a clearly defined vertical with strong adoption economics.
It is also worth monitoring consolidation patterns. As enterprises favor fewer, more integrated systems, providers that can either expand into adjacent operational capabilities or maintain a strong specialist position with clear customer value will be better placed than those competing primarily on commoditized planning features.
For Procurement and Enterprise Buyers
Procurement teams should evaluate total operating impact rather than software features in isolation. That means assessing how a solution affects dispatcher workload, driver experience, exception handling, compliance management, and integration with existing systems. Security, data governance, and implementation effort should be treated as core commercial criteria, not secondary checkboxes. Where possible, pilot programs should test not just plan quality but operational resilience under realistic disruption scenarios.
A useful lens is to ask whether the platform can make the operation more stable, not simply more optimized on paper. Stability under pressure, clarity of workflow, and measurable integration with execution often matter more in day-to-day operations than marginal gains in theoretical route efficiency.
Conclusion
The vehicle routing and scheduling market is moving from incremental tooling improvement toward a more central role in operational performance. Growth to roughly USD 15.83 billion by 2032, at a CAGR of about 4.03%, reflects a market where efficiency, compliance, customer expectations, and data integration are converging. The strategic question for organizations is no longer whether routing matters, but how routing is embedded into real-time operations, regulatory response, and workforce management. Those that treat it as a connected operational capability will be better positioned to control cost, protect service levels, and adapt as conditions change. For decision makers seeking a more detailed view of segment dynamics, regional variation, and vendor-specific positioning, a fuller market study can provide the depth needed to translate these trends into targeted investment and procurement decisions.
For detailed analysis of this topic, please visit the official page: Vehicle Routing and Scheduling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Corn Starch Market: Beyond 8.1% CAGR, What's Driving $41.4B Growth by 2032
By pmarketresearch, 2026-09-21
The Corn Starch Market: Strategic Trends and Commercial Opportunities Through 2032
The global corn starch market has entered a phase of accelerated expansion, driven by converging forces across food innovation, pharmaceutical formulation, and industrial substitution. With total market revenue reaching USD 24.0 billion in 2025 and a projected compound annual growth rate of 8.1 percent through 2032, the sector is evolving from a commoditized feedstock into a specialized functional ingredient landscape. This shift demands that executives, planners, and investors recalibrate their strategic assumptions. The following analysis maps the market's structural dynamics, identifies the forces reshaping competitive positioning, and outlines actionable implications for decision-makers.
Market Landscape and Structural Challenges
Historical trajectory underscores the market's momentum. Revenue climbed from USD 12.0 billion in 2020 to USD 15.49 billion in 2023, then accelerated sharply to USD 20.08 billion in 2024 and USD 24.0 billion in 2025. Forecasts project continued growth to USD 25.31 billion in 2026, USD 28.53 billion in 2027, and a terminal value of USD 41.4 billion by 2032. This trajectory reflects both volume expansion and value migration toward higher-margin specialty grades. The market remains moderately concentrated, with the top three players capturing 45.2 percent of revenue and the top five holding 58.6 percent, indicating room for regional challengers and niche specialists to compete on formulation expertise, certification portfolios, and supply reliability.
Despite the favorable macro trajectory, the industry faces several structural inflection points that will separate resilient operators from those caught off-guard.
- Feedstock volatility and margin asymmetry. Corn starch economics are tightly coupled to agricultural commodity cycles. While recent U.S. corn futures for the July 2026 contract traded between USD 4.11 and USD 4.73 per bushel in early 2026, below the 2022 peaks and hovering near the 2015-2019 average of USD 3.50 per bushel, the structural risk remains. Feedstock cost advantages can compress quickly, forcing producers to rely on operational efficiency, long-term supply agreements, and formulation differentiation rather than raw material arbitrage alone.
- Regulatory divergence across pharmaceuticals and foods. The excipient and functional ingredient landscape is being reshaped by region-specific mandates. In India, draft guidance from the Central Drugs Standard Control Organisation issued in March 2025 requires domestic tablet manufacturers to source at least 30 percent of excipients from plant-based or mineral origins by 2028, favoring suppliers with ISO 9001 and Good Manufacturing Practice certifications. In China, the National Medical Products Administration mandated in August 2025 that new generic applications justify the use of synthetic excipients over natural alternatives, accelerating the transition to pregelatinized corn starch in Asian pharmaceutical manufacturing. These divergent requirements elevate compliance complexity and reward suppliers with robust quality systems and regional regulatory fluency.
- Substitution pressure and functional performance thresholds. End-use industries are increasingly demanding ingredients that deliver specific rheological, textural, or health-related properties without compromising cost or label cleanliness. The European Commission's Farm to Fork Strategy update in May 2025 targets a 15 percent reduction in average per-capita saturated-fat intake by 2030, driving substitution of butter or cream with enzymatically modified waxy corn starch. Meeting these performance benchmarks requires continuous R&D investment and close co-development with downstream customers, raising the barrier for commoditized entrants.
Core Demand Drivers Reshaping the Market
The market's growth is not a single-factor story. It emerges from the intersection of technical capability, policy direction, consumer and industrial behavior, and shifting cost structures. Understanding how these forces interact clarifies where value will accumulate over the next several years.
Technological Innovation and Formulation Breakthroughs
The most consequential advances are occurring in modification science and application-specific engineering. Enzymatic modification, pregelatinization, and resistant starch development are expanding the functional envelope of corn starch beyond traditional thickening and binding roles. In pharmaceuticals, pregelatinized grades are improving tablet compression characteristics and disintegration profiles, directly supporting generic manufacturing efficiency. In food and beverage, enzymatically modified waxy corn starch is enabling fat reduction while preserving mouthfeel, aligning with clean-label and health-forward product pipelines. These capabilities are not incremental; they redefine the ingredient's role from a bulk commodity to a performance enabler, which in turn supports premium pricing and longer-term customer lock-in.
Policy and Regulatory Tailwinds
Regulation is acting as both a filter and an accelerant. The U.S. Department of Agriculture's BioPreferred Program, reauthorized in the 2024 Farm Bill with a 40 percent budget increase, requires federal agencies to prioritize products containing at least 25 percent bio-based carbon. Since 100 percent plant-derived corn starch qualifies automatically, this policy creates a structural procurement advantage for bio-based formulations in government-adjacent and institutional supply chains. Meanwhile, pharmaceutical regulatory shifts in India and China are pulling demand toward plant-based excipients with verifiable quality certifications. The net effect is a policy environment that rewards certified, traceable, and bio-based corn starch offerings while penalizing opaque or synthetic-heavy supply chains.
Demand-Side Shifts in Consumer and Industrial Behavior
Downstream demand is being reshaped by three interrelated trends. First, food and beverage formulators are prioritizing texture modification, fat replacement, and clean-label positioning, which elevates the role of modified and specialty starches. Second, pharmaceutical manufacturers are optimizing excipient selection to meet regional mandates and improve process reliability, particularly in generic drug production where cost and compliance are tightly coupled. Third, industrial applications such as paper, corrugated, and technical coatings continue to rely on starch-based solutions for binding, sizing, and surface strength, but with growing expectations for consistency and supply security. These demand signals favor suppliers that can pair technical service with robust logistics and certification documentation.
Supply Chain and Cost Structure Dynamics
Cost structures are improving in the near term, but the long-term advantage will belong to operators who build resilience. The recent moderation in U.S. corn futures has lowered feedstock costs for corn starch production, providing margin relief and enabling reinvestment in capacity and quality systems. Yet the more strategic opportunity lies in supply chain design. Regional capacity expansions are reducing logistics friction and improving service levels for local markets. Certifications and quality management systems are becoming differentiators in regulated segments. Producers that integrate feedstock procurement, modification capability, and application support into a coherent value proposition will capture more of the margin pool than those competing solely on volume.
Potato Starch Market
Competitive Landscape and Strategic Positioning
The corn starch market is shaped by a mix of global agribusiness integrators, specialty starch specialists, and regional capacity builders. Their strategies reveal how value is being captured and where gaps remain for new entrants or focused challengers.
Large, diversified players are leveraging scale, integrated supply chains, and broad application portfolios to anchor their positions. Their advantage lies in the ability to serve multiple downstream industries simultaneously, smoothing cyclicality and cross-selling functional ingredients across food, beverage, industrial, and pharmaceutical channels. These firms are increasingly emphasizing modification technology and certification readiness to compete in higher-value segments rather than relying on commodity throughput alone.
PW Consulting
Specialty and regional operators are differentiating through formulation depth, pharma-grade quality systems, and localized service. Companies with strong positions in modified starches, resistant starches, and pharmaceutical excipients are capturing demand from tablet manufacturers, infant formula producers, and dairy formulators seeking reliable, certified inputs. Their strategic edge often comes from technical collaboration, rapid customization, and the ability to meet region-specific regulatory requirements without the overhead of a fully integrated global network.
Capacity expansion is a visible signal of where demand is heading. In October 2025, Al Ghurair Foods announced the phased completion of the UAE's first corn starch plant in the Khalifa Economic Zones Abu Dhabi, targeting processing capacity of up to 1,000 tons per day for food, pharmaceutical, paper, and chemical industries, with completion expected by the first quarter of 2026. This move reflects a broader pattern of regional supply 구축 to reduce logistics dependency and serve Middle East and Africa demand with shorter lead times and localized certification support. In May 2025, Cargill inaugurated a new corn milling plant in Gwalior, India, operated through Saatvik Agro Processors, to support increasing demand from confectionery, infant formula, and dairy sectors. The expansion underscores the strategic importance of India as a growth node for food-grade and specialty starches. In August 2025, Ingredion expanded its Cardinal plant in Ontario, Canada with a CAD 28 million investment to meet domestic and export demand for tablet manufacturers and specialty starches, highlighting the continued relevance of North American capacity for pharmaceutical and technical grades.
The competitive landscape is evolving along two axes. On one hand, consolidation pressure persists among the largest players as they seek to widen application coverage and secure feedstock and logistics advantages. On the other hand, differentiation is intensifying in specialty segments where certification, modification expertise, and regional compliance matter more than sheer scale. New entrants and regional challengers can succeed by targeting underserved application-grade combinations, building strong quality and regulatory profiles, and forming strategic partnerships with downstream formulators. The market is therefore not converging into a pure commodity oligopoly; it is fragmenting into performance tiers where technical service, certification, and supply reliability command measurable premiums.
Forward-Looking Trends and Commercial Implications
Looking ahead to the mid-2020s and toward 2032, several trends are likely to define the market's trajectory and create distinct commercial opportunities.
Bio-based procurement standards will become a structural advantage
As public procurement and institutional supply chains increasingly prioritize bio-based content, 100 percent plant-derived corn starch is well positioned to benefit from automatic qualification under programs like the USDA BioPreferred reauthorization. This trend favors suppliers that can document bio-based content, maintain consistent quality, and serve government-adjacent and institutional customers with reliable logistics. Commercial opportunity lies in aligning product portfolios with bio-based procurement criteria and building the certification and traceability infrastructure to capture these contracts early.
Pharmaceutical excipient substitution will accelerate in Asia and beyond
Regulatory guidance in India and China is nudging generic manufacturers toward plant-based excipients, with pregelatinized corn starch emerging as a preferred option for tablet compression and disintegration. As these mandates take effect, demand for pharma-grade, certified corn starch is likely to grow, particularly where suppliers can demonstrate GMP compliance and consistent batch-to-batch quality. The opportunity extends beyond Asia, as multinational generic producers align their excipient sourcing with the most stringent regional requirements to simplify compliance across markets.
Functional modification will drive value migration in food and beverage
The drive to reduce saturated fat, improve texture, and maintain clean labels is expanding the role of enzymatically modified waxy corn starch and other specialty grades. As formulators seek ingredients that deliver specific sensory and functional outcomes, the market will increasingly reward modification capability and co-development expertise. Commercial advantage will accrue to suppliers that can translate technical performance into measurable product benefits, support customer innovation pipelines, and secure long-term formulation partnerships rather than one-off transactions.
These trends carry inherent uncertainties. Feedstock prices could reverse course if weather patterns, trade policy, or energy costs disrupt agricultural markets, compressing margins for producers without hedging strategies or cost flexibility. Regulatory requirements may diverge further across regions, increasing compliance costs and complicating global supply strategies. Substitution risk also remains, as alternative starches, fibers, and synthetic excipients could capture share in specific applications if they offer better cost or performance profiles. Operators should therefore treat these trends as directional signals rather than guaranteed outcomes, and build optionality into capacity, certification, and customer engagement plans.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align capacity and capability with the segments where performance and compliance command premiums. This means investing in modification technology, pharma-grade quality systems, and bio-based documentation where demand is growing, while maintaining cost discipline in commoditized segments. Close technical collaboration with downstream formulators can shorten development cycles and lock in specification preferences early. Where regional demand is strong, localized capacity or partnership models can reduce logistics risk and improve service levels, as illustrated by recent expansions in the Middle East, India, and North America.
For investors, the market offers a differentiated risk-return profile across tiers. Commodity-scale operations provide volume and cash flow but face margin sensitivity to feedstock cycles and substitution pressure. Specialty and pharma-grade positions offer higher margins and regulatory-driven demand, but require sustained investment in quality systems, certifications, and technical service. Regional capacity plays can capture growth in underserved markets, though they carry execution and regulatory risk. A balanced view should weigh feedstock exposure, certification readiness, application mix, and the ability to serve regulated segments when evaluating potential investments or partnerships.
Modified Starch Market
For procurement and supply chain leaders, the strategic imperative is to diversify toward certified, bio-based, and functionally appropriate inputs while preserving supply security. Building relationships with suppliers that can demonstrate GMP compliance, ISO quality systems, and consistent bio-based content will reduce regulatory and reputational risk, particularly in pharmaceutical and institutional procurement. Qualifying multiple grades and regions can mitigate disruption risk, while co-development with suppliers can unlock formulation improvements that reduce total cost of ownership. In a market where performance and compliance increasingly determine supplier selection, procurement strategy should be treated as a value-creation function rather than a cost-minimization exercise.
The corn starch market is transitioning from a volume-driven commodity landscape to a performance-and-compliance-led specialty market. Capturing the available opportunities requires timely access to granular segmentation data, regional regulatory mapping, and supplier-level capability assessments. Decision-makers who integrate these inputs into capacity planning, investment selection, and procurement strategy will be better positioned to navigate feedstock volatility, regulatory divergence, and functional substitution while participating in the market's projected growth trajectory through 2032.
For detailed analysis of this topic, please visit the official page: Corn Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com