

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Cationic Conditioning Polymers Market: How 6.98% CAGR and Hair Care Demand Reshape Growth Beyond 2032

The Cationic Conditioning Polymers Market: Strategic Trends and Commercial Opportunities
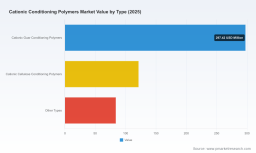
The global market for cationic conditioning polymers has entered a phase of disciplined expansion, driven by fundamental shifts in personal care formulation philosophies and regulatory redefinition of what constitutes acceptable ingredient architecture. Valued at approximately 502.7 million USD in 2025, the market has grown from 358.22 million USD in 2020, reflecting a compound annual growth rate of 6.98 percent through the forecast horizon to 2032. This trajectory signals more than incremental volume growth; it points to a structural transformation in how conditioners, shampoos, and related personal care matrices are engineered for performance, sensorial appeal, and environmental compliance. For executives and investors navigating specialty chemicals and beauty care supply chains, the market presents a landscape where formulation science, regulatory foresight, and supply chain agility now determine competitive positioning more than scale alone.
Market Status and Defining Challenges
From Volume Recovery to Formulation Redesign
The historical 2020–2025 period illustrates a recovery curve that accelerated sharply after the initial disruption of the early 2020s, with market size rising to 419.89 million USD in 2022 and continuing upward to 428.24 million USD in 2023 and 480.94 million USD in 2024. The 2025 valuation of 502.7 million USD represents a market that has absorbed post-pandemic demand normalization, resumed salon and retail channel activity, and begun confronting a more stringent regulatory environment. The forecast period extends this momentum, projecting a climb toward 540.47 million USD in 2026, continuing through 608.61 million USD in 2028, and reaching 802.8 million USD by 2032. This growth path is not uniform across all formulation segments or geographies, and the uneven pace itself reveals where investment logic must be sharpened.
Three structural challenges currently define the operating environment for manufacturers, formulators, and brand owners. First, the regulatory redefinition of polymer-based microplastics in rinse-off personal care products has forced widespread reformulation. Industry tracking shows that more than 28 percent of rinse-off personal care products in 2023 required reformulation across EU nations due to polymer-based microplastic content restrictions, and EU enforcement continues to shape global formulation strategy even beyond European borders. Second, feedstock volatility has introduced margin pressure and supply uncertainty into the production of key intermediates, particularly where CHPTAC pricing fluctuates in response to global supply shocks in epichlorohydrin and trimethylamine. Third, the competitive field remains comparatively fragmented, with a CR3 of 24.6 percent and a CR5 of 26.2 percent, indicating that no small group of players dominates the market and that differentiation depends on technical capability and regulatory navigation rather than scale alone.
These challenges interact in ways that reshape sourcing, R&D prioritization, and portfolio strategy. The market is not simply expanding; it is being redesigned.
PW Consulting
Key Drivers of Market Evolution
Innovation at the Chemistry-Performance Intersection
Technical innovation is propelling the market forward by expanding the performance envelope of cationic conditioning systems. Advanced polymer architectures now deliver stronger substantivity, improved wet and dry hair manageability, and more efficient deposition at lower usage levels. Recent product introductions illustrate this direction. In February 2026, Lubrizol introduced advanced cationic conditioning polymers engineered for enhanced hair manageability, moisture retention, and compatibility in shampoos and conditioners, signaling continued investment in next-generationpersonal care active systems. In December 2025, Inolex highlighted Kerazyne MB polyesteramine as an advanced multifunctional conditioning polymer for hair and skin care, emphasizing multifunctional performance within a single ingredient platform. These developments reflect a broader shift from commodity-style conditioning agents toward actives that solve multiple formulation pain points simultaneously, such as sensory softness, rinsability, and stability in complex surfactant systems.
For formulators and procurement leaders, this shift means that ingredient selection increasingly hinges on functionality breadth and compatibility rather than cost-per-kilogram alone. Polymers that can perform under sulfate-free, mild-surfactant, or low-pH conditions carry disproportionate value in premium and claims-driven product segments, where sensory outcomes and clean-label narratives must coexist with technical reliability.
Regulatory Pressure as a Catalyst for Sustainable Design
Regulatory change is accelerating reformulation cycles and creating a market premium for biodegradable and sulfate-free cationic systems. Between 2022 and 2024, industry data indicates that 38 percent of leading firms launched sulfate-free and biodegradable cationic polymers to address eco-conscious demand, a response that aligns with both consumer sentiment and regulatory tightening. At the same time, EU enforcement of polymer-based microplastic restrictions in rinse-off products continues to influence ingredient choices globally, while China’s REACH MEE Order 12 requires regular or simplified registration for cationic polymers expected to become cationic in natural water environments, adding a compliance layer for manufacturers supplying into or through the Asia-Pacific region.
These regulatory dynamics do not merely constrain; they redirect innovation toward genuinely sustainable chemistries. Companies that can demonstrate environmental compatibility without sacrificing conditioning performance are gaining formulation preference in markets where sustainability claims must be substantiated and where downstream customers face their own compliance obligations.
Consumer and Retailer Demand Reshaping Application Priorities
Demand-side behavior continues to favor hair care segments where conditioning performance is both visible and emotionally salient. Hair conditioners remain the largest application area, embodying the highest share of market value among end-use categories, while shampoos represent a significant secondary application, and other applications account for a smaller but strategically important portion of demand. The broad application footprint means that cationic conditioning polymers are embedded across a range of product formats, from rinse-off masks and treatments to daily-use shampoos and color-protecting systems. Consumer expectations around softness, shine, detangling, and heat protection are intensifying, particularly in premium and salon-grade offerings, pushing manufacturers to adopt actives that can deliver multi-attribute benefits without complicating formulation architecture.
The practical implication is that demand is increasingly performance-specific and claim-sensitive. Ingredients that enable simplified ingredient lists, support sulfate-free positioning, and deliver durable conditioning after rinsing are gaining share in segments where formulation transparency and sensorial consistency directly influence repurchase behavior.
Feedstock Volatility and Supply Chain Realignment
Cost structure and supply chain resilience have emerged as critical strategic variables. The CHPTAC market price volatility driven by global supply shocks in epichlorohydrin and trimethylamine has introduced uncertainty into the cost base for cationic polymer production, compelling manufacturers to revisit sourcing strategies, inventory planning, and pricing architectures. Capacity expansions and production increases are underway to address supply constraints and regional demand growth. In December 2025, Solenis expanded production capabilities for specialty cationic polymers used in personal care and industrial conditioning applications. In January 2026, Nippon Shokubai increased specialty polymer production to meet rising demand from Asia-Pacific personal care and salon-grade segments. These moves reflect a market-wide effort to secure supply, reduce lead-time risk, and align capacity with regional demand intensity.
For buyers and manufacturers, the lesson is that agility in sourcing and the ability to qualify alternative chemistries or regional suppliers are now part of core operational strategy. Reliance on single-source feedstock pathways or rigid formulation routines is becoming a liability in an environment where cost and compliance risks can shift rapidly.
Competitive Landscape and Winning Strategies
Leader Profiles and Differentiation Pathways
The competitive field includes players with distinct technical identities and regional strengths. SKW Quab Chemicals Inc., based in Saddle Brook, New Jersey, focuses on QUAB cationizing reagents and resulting cationic polymers, including cationic guar derivatives, for high-strength conditioning in personal care shampoos and conditioners. This reagent-centric approach positions the company around enabling chemistry that supports strong conditioning performance and formulation flexibility. Samyang KCI Corporation, headquartered in Seoul, South Korea, emphasizes specialty conditioning agents and cationic polymers for premium shampoos, conditioners, and hair care formulations, aligning closely with the Asia-Pacific premium and salon-grade demand trajectory. SNF, based in Andrézieux, France, focuses on water-soluble cationic polymers and film formers for hair care and conditioning in personal care applications, leveraging a broad polymer platform that spans performance and application versatility.
Solenis, headquartered in Charlotte, North Carolina, concentrates on specialty cationic polymers for personal care conditioning applications, and its December 2025 capacity expansion underscores a strategy of scaling specialty supply to meet demand while maintaining application-specific technical support. Inolex, based in Philadelphia, Pennsylvania, focuses on sustainable bio-based cationic conditioning agents and polymers for plant-based hair care and conditioning systems, distinguishing itself through a sustainability narrative anchored in bio-based chemistry and multifunctional performance, as highlighted by its December 2025 Kerazyne MB polyesteramine introduction.
Cationic Starch Market
Strategic Positioning and Differentiation Levers
Across these players, three differentiation levers are becoming decisive. First, application-specific technical support is increasingly valued, particularly where formulators require help optimizing deposition, rinse-off behavior, and compatibility with mild surfactant systems. Second, sustainable sourcing and bio-based or biodegradable positioning create claims advantage in premium and eco-conscious segments, where performance and environmental compatibility must be demonstrated together. Third, supply resilience and regional capacity alignment reduce risk for customers who are sensitive to lead times, feedstock volatility, and regulatory registration requirements across jurisdictions.
The market concentration data, with a CR3 of 24.6 percent and CR5 of 26.2 percent, indicates that scale dominance is not the primary competitive dynamic. Instead, differentiation through chemistry, application expertise, and compliance readiness determines which suppliers gain formulation preference and long-term inclusion in brand owner pipelines.
Market Structure Evolution: Consolidation Pressures and Entry Opportunities
The landscape is likely to evolve through a combination of selective consolidation and continued entry by specialized players. Scale players can capture value by integrating capacity, broadening regional coverage, and offering application breadth that reduces the number of supplier relationships for large brand owners. At the same time, new and niche entrants can compete by solving specific formulation problems, offering sustainable chemistries with verifiable claims, or serving fast-growing regional demand with localized technical support and supply. The regulatory environment also creates entry barriers where registration and compliance costs raise the threshold for new supply, but it simultaneously creates opportunities for suppliers that have already navigated these requirements and can offer ready-to-formulate, compliant solutions.
For incumbents, the strategic priority is to convert technical and compliance capabilities into stickier customer relationships. For new entrants, the entry point is not generic volume but targeted performance, sustainability substantiation, or regional supply advantage.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend One: Sustainability-Linked Performance as a Default Requirement
Over the next three to five years, sustainability-linked performance is likely to become a default expectation rather than a premium differentiator in many priority segments. As regulatory frameworks continue to tighten around polymer-based microplastics and environmental fate, and as consumer and retailer expectations around biodegradability and reduced environmental burden intensify, formulations will increasingly be judged on both function and footprint. This trend creates commercial opportunity for suppliers that can deliver conditioning performance with verifiable environmental compatibility and for brand owners that can translate those attributes into credible claims. The risk is that uncertified or poorly substantiated sustainability narratives face growing scrutiny, making technical validation and documentation essential.
Trend Two: Regional Demand Divergence and Localized Supply Strategies
Regional demand patterns are expected to diverge further, with Asia-Pacific personal care and salon-grade segments continuing to drive volume and premiumization, while North America and Europe remain centers of formulation innovation and regulatory influence. Industry developments already reflect this divergence, with Nippon Shokubai increasing specialty polymer production to meet rising Asia-Pacific demand and Solenis expanding capacity to support both personal care and industrial conditioning applications. The opportunity lies in aligning supply and technical support with regional demand intensity, reducing lead times, and building local formulation partnerships. The risk is that global supply strategies that ignore regional regulatory and demand nuances may face cost, compliance, or service-level disadvantages.
Trend Three: Ingredient Simplification and Multifunctional Actives
Formulation simplification is likely to accelerate as brand owners seek to reduce ingredient counts, improve label clarity, and streamline compliance management while preserving sensory and performance outcomes. Multifunctional conditioning polymers that combine deposition, softness, moisture retention, and compatibility in a single platform are well positioned for this environment. Recent introductions, such as Lubrizol’s advanced cationic conditioning polymers and Inolex’s Kerazyne MB polyesteramine, illustrate the direction of travel toward actives that reduce formulation complexity while expanding benefit sets. The commercial opportunity is for suppliers that can prove multifunctional performance with robust data and for brand owners that can leverage simplified systems to support claims and cost efficiency. The risk is overpromising on multifunctionality without sufficient application-specific validation, which can erode trust in a market where performance is immediately felt by consumers.
Strategic Actions for Decision Makers
For Manufacturers and Formulators
Prioritize application-specific validation of cationic systems under the conditions most relevant to your portfolio, including mild surfactant systems, sulfate-free bases, and rinse-off formats where deposition and substantivity must be balanced with clarity and feel. Build regulatory readiness into ingredient qualification processes, particularly for markets with registration or microplastic-related constraints, so that compliant options are available without last-minute reformulation pressure. Diversify feedstock and supplier pathways where feasible to mitigate CHPTAC-related volatility and reduce exposure to single-source disruptions.
Worldwide Cationic Reagent Market
For Investors and Strategic Buyers
Evaluate suppliers on the basis of technical differentiation, sustainability substantiation, and regional supply resilience rather than price alone. Companies that combine application expertise with verifiable environmental compatibility and the ability to support reformulation under evolving regulatory conditions are likely to capture higher-value positions in the value chain. Pay attention to capacity expansions and regional production moves as indicators of where demand is being served and where supply reliability is improving, since these shifts can alter competitive dynamics and customer loyalty over time.
For Procurement and Product Development Leaders
Treat cationic conditioning polymers as strategic inputs whose selection affects claims, compliance, and consumer perception, not just cost and viscosity. Qualify ingredients that support sulfate-free, biodegradable, or bio-based narratives with documented performance data, and align sourcing decisions with the regulatory and demand profile of your priority markets. Establish early engagement with suppliers that offer technical support for formulation optimization, since collaboration at the development stage can reduce time-to-market and improve the robustness of end-product performance.
The strategic value of this market lies in the intersection of performance, compliance, and supply agility. Detailed segmentation data, regional demand analysis, and tailored sourcing or portfolio recommendations can clarify where to commit resources and how to structure partnerships for the next growth cycle. Access to granular market sizing, application-level demand breakdowns, and company-level competitive assessment enables more precise decision making than aggregate trends alone can provide. For teams seeking to translate these dynamics into product roadmaps, sourcing strategies, or investment theses, comprehensive market intelligence remains a critical input to confident execution.
For detailed analysis of this topic, please visit the official page: Cationic Conditioning Polymers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com