

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
ERP Software Market Hits $140B by 2032: The 9.5% CAGR Reality>

The Enterprise Resource Planning Software Market: Strategic Trends and Commercial Opportunities in a Transforming Landscape
Market Snapshot: Scale, Trajectory, and Structural Pressure Points
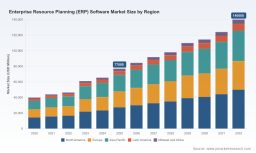
The enterprise resource planning (ERP) software market has transitioned from a mature, incremental-growth category into a structurally expanding ecosystem. Total revenue crossed the 77 billion-dollar threshold in 2025, building on a decade-long expansion that saw the market scale from roughly 40 billion in 2020. The forward trajectory is notably steep, with projected revenue reaching 140 billion by 2032. A compound annual growth rate of 9.5 percent over the 2026 to 2032 period signals that ERP is no longer a back-office utility but a central operating platform where finance, supply chain, human capital, and customer operations converge. The pace of expansion reflects a market that is simultaneously consolidating around cloud delivery, broadening its functional scope, and absorbing new demand from mid-market and cross-industry adopters who previously viewed integrated suites as out of reach.
Beneath the headline growth, three structural challenges are reshaping how buyers evaluate ERP investments and how vendors compete for wallet share. The first is the tension between speed-to-value and implementation complexity. Cloud deployments have lowered the initial capital barrier by removing hardware procurement and shifting costs into subscription and hosting models, but the long-term cost curve depends heavily on configuration discipline, integration maturity, and change management. For smaller enterprises, customization concerns, training requirements, and upgrade costs remain recurring friction points that can erode the promised efficiency gains of a modern platform. The second challenge is regulatory and compliance fluidity. Cloud ERP systems must continuously align with data protection, industry-specific, and financial reporting obligations, while built-in automatic updates create a moving target for internal audit and control teams. Regulatory signals in 2025, including deregulatory proposals aimed at reducing compliance burdens for data and AI obligations in cloud environments, introduce both relief and uncertainty, as the exact scope and timing of obligations continue to evolve. The third challenge is organizational readiness for AI-infused workflows. ERP vendors are embedding intelligent automation, predictive insights, and agent-based capabilities across finance, procurement, and supply chain functions, yet enterprises often lack the data governance, process standardization, and skills infrastructure required to extract measurable value. Without that foundation, AI features risk becoming superficial differentiators rather than operational levers.
For executives and planners, the strategic implication is clear: ERP is becoming a multi-year operating decision rather than a one-time software purchase. The winners will be organizations that treat platform selection as a capabilities investment, align deployment scope with process maturity, and build the governance needed to sustain compliance and continuous improvement.
Core Drivers Reshaping Demand and Vendor Behavior
Several interlocking forces explain why the ERP market is expanding at a pace that outstrips many traditional enterprise software categories. These drivers are not isolated; they reinforce each other and create distinct opportunities for organizations that can position ERP as an enabler of operational resilience and decision velocity.
Technology Innovation and Platform Convergence
The most visible driver is the convergence of cloud architecture, embedded analytics, and AI-enabled automation into a single operational fabric. Cloud ERP has moved from a deployment preference to the dominant delivery model, supported by subscription economics that reduce upfront infrastructure costs while enabling continuous updates. More importantly, the platform layer is increasingly intelligent. Recent product movements show vendors moving beyond dashboards and alerts toward agent-based tooling that can build, connect, and verify AI agents across HR, finance, and IT environments. This shift matters because it reframes ERP from a record-keeping system to an orchestration layer that can coordinate transactions, reconciliations, approvals, and exception handling with less manual intervention.
Accounting Software Market
The commercial impact is twofold. First, buyers can justify ERP investments on the basis of operational agility and reduced cycle times rather than pure cost displacement. Second, vendors are competing on ecosystem breadth, integration depth, and the ability to extend functionality through low-code or partner-built extensions. The practical takeaway is that organizations should evaluate platforms not only on core ledger and reporting strength, but also on how readily the system can absorb new workflows, connect to specialized applications, and support governed automation without creating brittle custom code.
Regulatory and Compliance Dynamics
Policy and regulatory environments are becoming both a constraint and a catalyst. Cloud ERP systems must navigate overlapping obligations related to data protection, financial reporting standards, and industry-specific controls. At the same time, vendors are consolidating compliance capabilities into the platform itself, with automatic updates and configuration controls designed to keep organizations aligned as rules change. This is particularly relevant for multinational enterprises and regulated industries, where manual remediation and fragmented systems can turn compliance into a recurring cost center.
Recent regulatory developments illustrate the direction of travel. In late 2025, European regulators signaled a deregulatory push intended to reduce compliance burdens associated with data and AI obligations in cloud ERP contexts. The implication is nuanced: reducing friction can accelerate adoption and lower the cost of governance, but the exact boundaries of reduced obligations and the timing of implementation remain important variables for procurement and risk teams. For decision-makers, the strategic lesson is to treat compliance not as a static checkbox but as a platform selection criterion, weighing how much regulatory upkeep can be absorbed by the vendor versus how much must remain inside the enterprise.
Demand-Side Shifts in Enterprise Behavior
Buyer behavior is changing as operational complexity rises and expectations for real-time visibility increase. Finance and accounting remain a foundational application area, but demand is broadening across human resources, supply chain management, customer relationship management, and inventory management. This expansion reflects a broader shift in how enterprises organize work: functional silos are increasingly undesirable because they slow decision-making, duplicate data entry, and weaken cross-functional accountability. Integrated suites are therefore attractive not because they eliminate specialized tools, but because they reduce fragmentation and create a shared data backbone for planning, execution, and control.
At the same time, the mid-market is a critical demand engine. Smaller organizations are adopting ERP at increasing rates, yet they encounter familiar implementation concerns around customization, training, and upgrade exposure. That dynamic is reshaping the vendor landscape, with some platforms emphasizing simplicity, rapid deployment, and modular adoption, while others continue to target complex, multi-entity, multi-currency environments. The commercial opportunity lies in matching platform scope to organizational maturity: enterprises that over-customize prematurely or underestimate change management often pay for it later in upgrade costs and adoption friction, while those that standardize first and extend later tend to realize value faster.
Cost Structure and Supply-Side Realities
Cost structure is evolving in ways that influence both adoption timing and vendor strategy. Cloud ERP implementations reduce upfront hardware expenditure, which lowers the barrier to entry and enables faster initial deployment. However, subscription and hosting fees persist over time, and total cost of ownership increasingly depends on integration work, data migration quality, user adoption, and the need for ongoing configuration support. In effect, the cost conversation has shifted from capital avoidance to lifecycle efficiency.
This shift is particularly important for procurement teams and finance leaders. The cheapest entry point is not always the lowest-risk path if the platform requires heavy customization or if internal teams lack the bandwidth to manage upgrades and extensions. Conversely, a platform with stronger out-of-the-box functionality and clearer upgrade paths may deliver better long-term economics, even if initial subscription pricing appears higher. The broader supply-side implication is that vendors are competing on implementation velocity, partner ecosystems, and the predictability of ongoing costs, not merely on feature count.
Competitive Positioning and the Evolving Vendor Landscape
The ERP market remains concentrated, with a relatively small group of large providers commanding a substantial share of total revenue. This concentration reflects the scale required to maintain broad functional coverage, global compliance support, and a mature partner ecosystem. At the same time, the landscape is not static. Consolidation, product divergence, and targeted specialization are all visible at once, creating a more nuanced competitive map than the traditional flagship-versus challenger framing suggests.
Large platform vendors have pursued strategies that emphasize ecosystem integration and cloud-native architectures. SAP continues to anchor its positioning around its S/4HANA and business one offerings, with modules spanning finance, supply chain, and manufacturing. Oracle has reinforced its Fusion Cloud ERP and NetSuite footprint, emphasizing finance, operations, and global supply chain capabilities. Microsoft has leaned into Dynamics 365 with AI-driven integrations across finance and supply chain, while also serving a broad base through Business Central. Workday has expanded its ERP scope around finance, HCM, and enterprise operations, increasingly highlighting AI agent capabilities as part of its differentiation. These players share a common strategic theme: they are positioning ERP as an integrated operating platform rather than a set of isolated modules, and they are investing heavily in cloud delivery, data continuity, and intelligent automation.
Alongside the large platforms, specialized and mid-market vendors continue to compete on industry fit, deployment flexibility, and total cost predictability. Infor focuses on cloud suites for manufacturing, distribution, and industry-specific scenarios. QAD and Epicor target manufacturing, distribution, and service-oriented environments with adaptive or kinetic-oriented ERP formulations. Sage maintains a strong presence in finance, accounting, and small-to-medium enterprise contexts, while Acumatica emphasizes flexible cloud ERP with AI-capable financial and operational management. Odoo offers an approach built around CRM, finance, inventory, and manufacturing with open-source options that appeal to organizations seeking modularity and extensibility. The diversity of these offerings matters because ERP value is highly context-dependent: a platform that excels in a complex multinational manufacturing environment may be overkill for a growing services firm, while a streamlined system may struggle in a heavily regulated multi-entity operation.
Recent market moves underscore how quickly the landscape can shift. In mid-2025, Acumatica reached a definitive agreement to be acquired by Vista Equity Partners, a transaction that signals the continued investor appetite for scalable cloud ERP platforms with clear mid-market positioning and growth potential. In mid-2026, Workday expanded its agent-related tooling with developer agents, agent-ready tools, and agent passport capabilities designed to support building, connecting, and verifying AI agents across HR, finance, and IT environments. These developments are not isolated events; they reflect two broader dynamics. First, capital and M&A activity continues to reshape ownership and go-to-market intensity in the sector. Second, product roadmaps are increasingly oriented around governed AI and orchestration, with vendors racing to make ERP environments more programmable and agent-compatible without sacrificing control.
PW Consulting
The competitive trend that follows from this mix is a market that is simultaneously consolidating at the top and fragmenting by use case. Large platforms are broadening their ecosystems and embedding intelligence, while specialized vendors compete on vertical depth, deployment simplicity, or open extensibility. New entrants and partner-built solutions are also shaping the edges of the market, particularly where organizations want best-of-breed integration around a core ERP backbone. For buyers, the practical implication is that vendor selection should be treated as a fit-and-evolution question: which platform aligns with current process needs, which one can grow with the organization, and which one offers a credible path through compliance, integration, and AI adoption without forcing excessive customization.
Supplier Relationship Management System Market
Forward Outlook: Three Trends to Watch Over the Next Three to Five Years
Looking ahead, the ERP market is likely to be defined by a small number of high-impact trends that will shape both vendor strategies and enterprise buying behavior. These trends are not speculative; they are already visible in product roadmaps, implementation patterns, and regulatory signals, but their full commercial implications will unfold gradually.
Intelligence as a Core ERP Capability, Not a Add-On
The next phase of ERP competition will center on how reliably platforms can support governed automation and agent-based workflows. The move toward developer tools, agent-ready environments, and verification mechanisms indicates that AI will increasingly be treated as an operational layer inside ERP rather than a separate analytics overlay. For enterprises, this creates an opportunity to reduce manual reconciliation, improve exception handling, and accelerate cycle times in finance and supply chain processes. The risk is that organizations adopt agent-enabled features before they have standardized data, cleaned master records, and defined control boundaries. In that scenario, intelligence can amplify process noise rather than reduce it. The strategic opportunity, then, is to pair platform-level intelligence with disciplined data governance and clearly scoped automation use cases.
Compliance and Regulatory Agility Becoming a Buying Criterion
As cloud ERP systems continue to absorb more regulatory upkeep through automatic updates and built-in controls, enterprises will increasingly evaluate vendors on their ability to help them stay aligned without excessive manual intervention. At the same time, regulatory environments will remain fluid, with deregulatory signals and evolving obligations creating periods of both opportunity and uncertainty. Organizations that treat compliance as an ongoing platform capability are better positioned to reduce audit friction and avoid reactive remediation costs. The commercial opportunity is to select platforms and implementation models that make regulatory adaptation part of the operating rhythm rather than a periodic project.
Deployment Economics and Implementation Discipline Driving TCO Outcomes
Cloud adoption will continue to lower upfront barriers, but leadership teams will become more sophisticated about lifecycle economics. Over the next several years, buyers are likely to compare solutions less on initial price and more on implementation risk, upgrade exposure, training burden, and the cost of maintaining custom extensions. This should favor platforms and partners that can deliver predictable deployment timelines, modular adoption, and cleaner upgrade paths. For vendors, the implication is that implementation quality and partner ecosystems will become more important competitive levers, not just product features. For enterprises, it means that the best ERP decision is often the one that balances ambition with implementation realism, especially for organizations that have limited internal bandwidth.
What Decision-Makers Should Do Next
ERP strategy is no longer a procurement exercise; it is an operating model decision. The most effective responses will differ by role, but several priorities apply across the board.
- For manufacturers and operationally complex enterprises, prioritize platforms that can connect finance, supply chain, inventory, and manufacturing workflows without forcing excessive customization. Standardization first, extension second, is usually the most durable path to value, especially when supply chain volatility and compliance demands are high.
- For investors and market observers, focus on the signals that indicate durable competitive advantage: cloud delivery maturity, ecosystem extensibility, agent-ready tooling, and evidence that implementation and upgrade economics are improving rather than worsening. Ownership changes and product launches matter, but they should be evaluated against whether they strengthen or weaken a vendor’s ability to serve complex enterprise needs over time.
- For procurement and finance leaders evaluating ERP purchases, treat total cost of ownership as a lifecycle question. Compare not only subscription pricing, but also implementation complexity, training demands, customization exposure, and the operational burden of maintaining compliance and upgrades. A lower entry cost can be attractive, but it should not come at the expense of long-term maintainability.
Each of these priorities benefits from deeper, segment-level intelligence. Market-wide figures provide direction, but the real decisions happen in the details: which deployment model fits a given operating profile, which functional areas are expanding fastest in a specific industry, how vendor strategies differ by enterprise size, and where implementation risk is most likely to undermine projected value. The ERP market is large, fast-moving, and increasingly defined by platform intelligence, regulatory agility, and deployment discipline. Organizations that make decisions with that context in mind are better positioned to convert ERP from a cost center into a strategic operating asset.
For detailed analysis of this topic, please visit the official page: Enterprise Resource Planning (ERP) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com