

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Vehicle Routing and Scheduling Market: How 4.03% CAGR Planning Redefines Logistics Strategy

Vehicle Routing and Scheduling Market: Strategic Trends and Commercial Opportunities in the Age of Intelligent Logistics
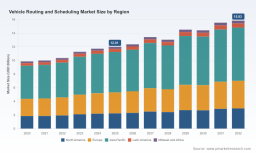
The global vehicle routing and scheduling market has entered a phase of structural transformation where route planning is no longer a back-office optimization problem but a core operational driver of margin protection, service reliability, and carbon accountability. Valued at approximately USD 12.01 billion in 2025, the market is projected to reach USD 15.83 billion by 2032, expanding at a compound annual growth rate of roughly 4.03% over the 2026–2032 forecast window. This trajectory reflects a market that is maturing in terms of software adoption, yet simultaneously becoming more complex as operational, regulatory, and technological pressures converge. For executives, investors, and procurement leaders, the strategic implication is clear: routing and scheduling capabilities are increasingly intertwined with broader freight visibility, workforce management, and sustainability commitments. The companies and fleets that treat route intelligence as a standalone tool will find diminishing returns; those that embed it into real-time operational workflows will gain measurable advantages in cost per mile, asset utilization, and service consistency.
The market expansion is not uniform across time or activity. Growth has been shaped by a combination of post-pandemic logistics normalization, rising last-mile complexity, and the gradual shift from static planning models toward more adaptive, data-driven scheduling. Historical demand between 2020 and 2025 illustrates this arc: modest recovery in the early years gave way to stronger operational investment as organizations attempted to absorb volatility in labor availability, freight volumes, and customer expectations. The forecast period onward suggests continued expansion, though not without intermittent adjustments as enterprises recalibrate spending, vendors refine product-market fit, and buyers weigh the total cost of ownership against promised efficiency gains. In this context, the market is best understood as a space where incremental efficiency improvements can compound into meaningful competitive differentiation, especially for operators managing large fleets, multi-stop delivery networks, or time-sensitive service schedules.
Market Landscape and Core Challenges
Where the Market Stands Today
Today’s vehicle routing and scheduling market is defined by a broad shift from fixed, pre-planned routes to systems that can respond to changing conditions throughout the day. Enterprises are no longer satisfied with tools that optimize once at the start of a shift; they increasingly expect platforms that can incorporate live traffic patterns, service-window constraints, driver availability, and real-time exceptions. That expectation is pushing vendors to integrate routing logic more tightly with telematics, transportation management, and field service workflows, rather than offering routing as an isolated module.
At the same time, the market remains meaningfully concentrated. A relatively small group of established providers accounts for a substantial share of enterprise adoption, while a wider field of specialist and emerging players competes on usability, vertical-specific features, or deployment speed. This split matters because it shapes how quickly innovation reaches different buyer segments. Large platforms tend to emphasize integration depth, security, and enterprise governance, while smaller or more focused vendors often move faster on user experience, specialized optimization logic, or rapid onboarding for particular use cases. The result is a market where the value proposition increasingly depends on context: the right solution for a global freight operation may differ substantially from the right solution for a regional field-service organization or a high-density urban delivery network.
Key Challenges and Decision Points
Several intersecting challenges are shaping the market’s near-term direction.
-
Operational variability versus planning stability. Route optimization becomes harder as conditions grow less predictable. Traffic disruptions, weather events, shifting delivery windows, and vehicle availability issues all create exceptions that can quickly erode the value of a theoretically optimal plan. The challenge for buyers is not simply to buy an optimizer, but to choose systems that can re-plan quickly without destabilizing the day’s operations or overwhelming dispatchers with constant changes.
PW Consulting -
Regulatory and compliance complexity. Route scheduling does not operate in a vacuum. Driving-hour restrictions, emission-sensitive zones, load limits, toll structures, and vehicle-type restrictions differ across regions and can materially affect feasible routing choices. As regulatory expectations tighten in various markets, route planning tools must account for compliance constraints while still supporting efficiency goals. This creates a tension that many operators are still learning to manage: optimizing for cost or speed in a way that does not inadvertently create compliance exposure or operational friction.
-
Labor cost pressures and workforce constraints. Labor remains one of the largest cost categories for fleet operators when routes are planned manually or managed through fragmented tools. At the same time, driver availability and retention have become strategic concerns in many markets. This combination is pushing organizations to seek routing and scheduling systems that can reduce unnecessary miles, balance workload more effectively, and support Hours of Service and driver-availability considerations. The operational prize is twofold: lower direct cost and a more sustainable workflow for drivers, which can matter just as much in a tight labor environment.
-
Data security, privacy, and system trustworthiness. Routing platforms increasingly touch sensitive operational, customer, and location data. As a result, security and privacy concerns have become a more visible part of the buying decision. Enterprises are paying closer attention to breach risk, governance, and regulatory compliance, particularly where routing data is integrated with broader logistics or customer-facing systems. Trust and reliability are no longer secondary considerations; they are part of the platform’s commercial viability.
Key Demand Drivers Shaping the Market
Technology Innovation and Optimization Maturity
A central driver of market growth is the continued maturation of optimization technology itself. Route planning has evolved from relatively static, rules-based approaches toward systems that can absorb more variables, adapt more quickly, and support more granular operational decisions. Dynamic re-optimization, in particular, has moved from a differentiating feature to an expectation in many use cases. When a dispatcher can adjust routes in response to a delayed vehicle, a new order, or a service-window change without rebuilding the entire day’s plan, the operational value is considerable.
The practical impact of this shift is visible in how vendors are packaging routing capabilities. Some are embedding route optimization inside broader logistics and transportation platforms, making it part of a continuous operational flow rather than a separate planning step. Others are pairing optimization engines with telematics and field-data capture so that scheduled plans can be compared against actual execution, creating feedback loops that improve future planning. This convergence is important because it moves routing from a static efficiency exercise toward a more measurable, iterative capability.
Policy, Regulation, and Compliance Pressure
Policy and regulatory environments are influencing both the demand for routing software and the functionality that buyers require. Driving-hour rules, regional load and vehicle restrictions, emission zones, and toll regimes can all affect which routes are viable and how schedules should be structured. In markets where these constraints are especially varied or evolving, routing tools that can encode compliance logic directly into scheduling decisions have a stronger value proposition. This is not only about avoiding penalties; it is also about reducing the operational burden of managing complex rule sets manually.
For multinational operators and cross-border logistics providers, the regulatory dimension adds another layer of importance. Different jurisdictions can impose different constraints on heavy vehicles, urban access, driver working time, and environmental performance. In such environments, routing and scheduling software becomes a mechanism for standardizing operational decision-making across regions while still respecting local constraints. That capability is increasingly relevant as supply chains and service networks become more geographically diversified.
Demand-Side Changes in Customer and Enterprise Behavior
Demand-side behavior is also reshaping the market. Customers across both consumer and business segments increasingly expect more accurate delivery or service-time predictions, faster response to exceptions, and greater transparency in logistics operations. Those expectations raise the stakes for routing and scheduling because they connect operational planning directly to customer experience. A plan that is mathematically efficient but fragile in execution may not satisfy service expectations once real-world disruptions occur.
In parallel, many enterprises are under pressure to improve not just service levels but also asset productivity and environmental performance. Route optimization supports both objectives by reducing empty miles, tightening stop sequencing, and helping organizations make better use of existing vehicles and drivers. In that sense, routing and scheduling is becoming part of a broader operational narrative around doing more with constrained assets while improving consistency and reliability.
Supply Chain and Cost Structure Pressures
Cost structure dynamics continue to influence adoption. When labor, fuel, maintenance, and compliance costs rise or become more volatile, the value of better routing becomes more visible. Even modest reductions in unnecessary miles or unproductive downtime can translate into meaningful operational savings across a large fleet or high-frequency delivery operation. This is why routing optimization is often evaluated not as a discretionary software purchase but as a lever for protecting margins in an environment where many cost inputs are difficult to control.
The same pressure is encouraging integration with broader cost and performance management. Organizations are increasingly interested in solutions that can link route decisions with fuel consumption, driver scheduling, vehicle maintenance windows, and service-level outcomes. The more routing is connected to these surrounding processes, the more it can contribute to total operating efficiency rather than isolated route improvements.
Competitive Landscape and Leading Strategies
How the Market Is Structured
The competitive landscape reflects a mix of large enterprise platforms, specialized optimization vendors, telematics-rich fleet solutions, and regional or vertically oriented providers. This diversity is one of the market’s defining features. Large platforms typically compete on breadth: integration with broader ERP, transportation, or supply chain systems, enterprise governance, security posture, and the ability to support complex global operations. Specialist and mid-tier vendors often compete on speed, usability, targeted optimization logic, and the clarity of their solution for a specific operational context.
Several organizations stand out for the way they position routing and scheduling within their broader portfolios. Descartes Systems Group emphasizes routing and dispatch capabilities oriented around logistics and distribution workflows. Oracle and SAP embed vehicle routing and scheduling within broader transportation management and fleet scheduling environments, appealing to enterprises that want routing to operate as part of a unified operational backbone. IBM supports routing and scheduling through supply chain and logistics platforms, targeting organizations that value integrated intelligence across planning and execution. Manhattan Associates has expanded route optimization within its broader logistics software ecosystem, reflecting a strategy of connecting routing more tightly to warehouse, order, and delivery execution.
There is also a notable presence of telematics-oriented and fleet-focused providers. Samsara, Verizon Connect, Fleet Complete, and Geotab integrate route optimization with telematics and fleet-management capabilities, which can be especially compelling for operators that want scheduling decisions linked to vehicle location, driver behavior, and real-time operational data. Locus highlights multi-fleet planning and real-time dynamic re-optimization for enterprise use cases, while Routific, Route4Me, and OptimoRoute are commonly associated with delivery-oriented route planning and optimization. e2open and Trimble round out the landscape with solutions that connect routing and scheduling to broader transportation, last-mile, and logistics workflows.
Differentiation and Strategic Positioning
The market’s competitive dynamics are increasingly shaped by differentiation in a few key areas.
-
Integration depth. Providers that connect routing to other operational systems have an advantage in environments where plans must flow directly into execution. Integration with transportation management, telematics, order management, or field-service platforms reduces the friction between planning and doing, which is often where the greatest operational value is realized.
-
Real-time adaptability. The ability to re-optimize quickly, without disrupting the entire schedule, is becoming a critical differentiator. Vendors that can handle live exceptions, reorder stops, and rebalance routes as conditions change are better positioned for complex, high-variability operations.
-
Vertical and use-case fit. Routing and scheduling needs differ substantially by application. Public transportation, freight and logistics, field service management, emergency services, and healthcare transportation all impose different constraints and priorities. Providers that tune their optimization logic, user experience, and integrations to specific use cases can stand out even in a crowded market.
Carpooling Market -
Compliance and operational governance. Solutions that make it easier to manage driving-hour rules, regional restrictions, and other compliance considerations are gaining relevance, particularly where regulatory variation is high. This is not just a legal matter; it is an operational design issue that affects how workable a schedule is in practice.
-
Deployment and usability. In many buyer segments, implementation speed and dispatcher usability matter as much as algorithmic sophistication. Tools that are easier to adopt and train can deliver value sooner, which is especially important for organizations that need to improve operations quickly without large transformation programs.
How the Landscape Is Evolving
The market is evolving along multiple axes at once. One trend is convergence, as routing capabilities become more embedded in larger logistics, telematics, and transportation platforms. This makes sense operationally, because route planning is most powerful when it is connected to real-time execution data and broader business processes. Another trend is fragmentation at the specialist level, where smaller or more focused providers continue to emerge around specific delivery models, regional markets, or vertical needs. Finally, there is ongoing consolidation pressure among enterprise buyers, who increasingly prefer fewer, better-integrated systems over a patchwork of point solutions.
Together, these dynamics suggest that competition will not be decided by optimization quality alone. The winners in different segments will likely be those that combine sound routing logic with strong integration, practical usability, compliance awareness, and credible security and data governance. In market terms, that means some providers will grow by extending into broader operational platforms, while others will compete by dominating a specific use case or deployment profile with exceptional fit and speed.
Future Outlook: Strategic Trends for the Next 3–5 Years
Trend 1: Routing as a Real-Time Operational Capability
Over the next several years, routing and scheduling is likely to become less about planning a day in advance and more about continuously managing a living operation. Dynamic re-optimization, exception handling, and live feedback from telematics and execution systems will increasingly define the value of a platform. For commercial operators, this means routing will matter not only at the start of a shift, but throughout the day as conditions change. The opportunity is to reduce operational drag: fewer cascading delays, better recovery from disruptions, and higher percentages of stops or services completed within intended windows.
The associated risk is that real-time capabilities can create complexity if they are not designed well. Constant replanning can overwhelm dispatchers and drivers if the system lacks clear priorities, thresholds, and human-in-the-loop controls. The most successful deployments will likely be those that balance automation with operational governance, so that optimization improves stability rather than creating noise.
Trend 2: Compliance-Aware, Sustainability-Linked Scheduling
Regulatory and sustainability pressures are expected to keep rising as planning constraints. Emissions considerations, urban access rules, driving-hour compliance, and vehicle restrictions will not remain niche concerns; they will become embedded in how feasible routes are defined and evaluated. This creates an opportunity for routing and scheduling tools to serve as a dual-purpose asset: improving efficiency while also supporting compliance and environmental objectives. In many operations, that combination is becoming more valuable than pure cost minimization.
At the same time, there is uncertainty in how regulations will evolve across regions and how consistently organizations can operationalize sustainability goals alongside service and cost targets. Market participants should expect continued variation in the pace and shape of requirements, which will favor flexible platforms over rigid ones.
Trend 3: Smarter Integration With Workforce, Telematics, and Execution Data
A third major trend is the deepening connection between routing and the systems that surround it. Telematics, driver scheduling, order or service data, and execution analytics will be more tightly linked to route decisions. This matters because routing outcomes are only as useful as the operational feedback loop that follows. When planned routes are compared with actual performance, organizations can refine constraints, identify recurring exceptions, and improve future schedules. Over time, this turns routing into a continuously improving capability rather than a one-time optimization exercise.
The opportunity here extends beyond technology. Organizations that invest in data quality, operational discipline, and clear performance metrics will benefit more from advanced routing than those that simply install a better optimizer. The technology amplifies operational intent; it does not replace it.
Strategic Implications for Decision Makers
For Fleet Operators and Logistics Providers
Operators should evaluate routing and scheduling as part of a broader operational architecture rather than as a standalone efficiency tool. The highest returns typically come when route optimization is connected to real-time execution data, dispatcher workflows, and compliance requirements. A practical approach is to prioritize solutions that can handle dynamic exceptions, support driver and vehicle constraints, and integrate with existing telematics or transportation systems without creating new data silos.
Ride Sharing Market
Equally important is realistic scoping. Different operations need different levels of sophistication. A high-density urban delivery network may benefit most from frequent re-optimization and tight time-window control, while a field-service organization may need stronger scheduling integration around technician availability and service priorities. Matching the tool to the operational model is often more important than selecting the most feature-rich platform.
For Technology and Software Investors
Investors should look for differentiation that is defensible in practice, not just in product descriptions. The most durable opportunities tend to sit where routing is tightly integrated with surrounding workflows, where compliance and security requirements create meaningful barriers, and where execution feedback improves outcomes over time. Niche fit can be valuable, but scaling often depends on the ability to connect routing to broader platforms or to serve a clearly defined vertical with strong adoption economics.
It is also worth monitoring consolidation patterns. As enterprises favor fewer, more integrated systems, providers that can either expand into adjacent operational capabilities or maintain a strong specialist position with clear customer value will be better placed than those competing primarily on commoditized planning features.
For Procurement and Enterprise Buyers
Procurement teams should evaluate total operating impact rather than software features in isolation. That means assessing how a solution affects dispatcher workload, driver experience, exception handling, compliance management, and integration with existing systems. Security, data governance, and implementation effort should be treated as core commercial criteria, not secondary checkboxes. Where possible, pilot programs should test not just plan quality but operational resilience under realistic disruption scenarios.
A useful lens is to ask whether the platform can make the operation more stable, not simply more optimized on paper. Stability under pressure, clarity of workflow, and measurable integration with execution often matter more in day-to-day operations than marginal gains in theoretical route efficiency.
Conclusion
The vehicle routing and scheduling market is moving from incremental tooling improvement toward a more central role in operational performance. Growth to roughly USD 15.83 billion by 2032, at a CAGR of about 4.03%, reflects a market where efficiency, compliance, customer expectations, and data integration are converging. The strategic question for organizations is no longer whether routing matters, but how routing is embedded into real-time operations, regulatory response, and workforce management. Those that treat it as a connected operational capability will be better positioned to control cost, protect service levels, and adapt as conditions change. For decision makers seeking a more detailed view of segment dynamics, regional variation, and vendor-specific positioning, a fuller market study can provide the depth needed to translate these trends into targeted investment and procurement decisions.
For detailed analysis of this topic, please visit the official page: Vehicle Routing and Scheduling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com