

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
Fiber Cement Board Market: Decoding 4.88% CAGR and Regional Shifts to 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Fiber Cement Board Market
The global fiber cement board market has entered a phase of measured but structurally significant expansion. Over the 2020 to 2025 period, total market revenue moved from 105.0 million USD to 133.1 million USD, reflecting a compound trajectory that accelerated notably in the latter half of the decade. The five-year forecast extending to 2032 projects the market will reach 183.8 million USD, underpinned by a CAGR of 4.88 percent. These figures point to more than cyclical recovery or inventory correction; they indicate a maturing replacement cycle where builders, architects, and property owners are steadily shifting toward materials that deliver durability, regulatory compliance, and lifecycle value. The market is not a high-growth commodity story. It is a technology-enabled building materials segment where performance specifications, code alignment, and manufacturing footprint increasingly determine competitive outcomes.
At the same time, the growth path is not uniform across regions, applications, or product densities. The aggregate numbers mask a landscape defined by divergent demand drivers, raw material transitions, and a concentrated competitive field in which a handful of established players account for a disproportionate share of revenue. For executives and investors, the central question is no longer whether fiber cement boards will continue to gain share against alternative cladding and sheathing products. The question is where margin, capacity, and differentiation will be created over the next three to five years, and which structural shifts will separate leaders from laggards.
Market Snapshot and Structural Realities
The current market environment reflects a combination of post-pandemic normalization, project pipeline recovery, and deliberate product substitution. After a contraction in 2024, when revenue dipped relative to 2023, the market rebounded in 2025 with renewed demand across key geographies and applications. This pattern suggests that earlier softness was partly tied to supply chain adjustments, pricing pressure, and project timing rather than a fundamental loss of demand for fiber cement solutions. The forward curve shows steady annual increases in the forecast window, indicating that underlying adoption drivers remain intact.
Two structural realities deserve attention. First, the market exhibits meaningful concentration, with the top three and top five players sharing the same combined market share level. This concentration signals that scale, brand trust, distribution reach, and technical certification are powerful moats. New entrants face a steep climb unless they bring a clearly differentiated value proposition, such as specialized regional compliance, innovative surface treatments, or cost-optimized manufacturing for underserved segments. Second, revenue growth is being shaped by a mix of mature replacement demand and targeted new-construction adoption, particularly where building codes, weather risk, and fire performance increasingly favor dense, non-combustible board products.
Key Challenges Shaping the Next Phase
The first challenge is the tension between performance premiums and cost sensitivity. Fiber cement boards compete against wood-based, vinyl, and traditional masonry-adjacent solutions that can offer lower upfront cost or familiar installation workflows. In price-sensitive segments, bidding pressure can compress margins unless manufacturers can anchor value in durability, reduced maintenance, lower insurance or code-related risk, and consistent aesthetic performance over time. The commercial opportunity lies in translating technical superiority into total cost of ownership narratives that resonate with developers, general contractors, and specifying architects.
The second challenge is regulatory complexity and geographic variability. Building codes, hurricane-zone requirements, fire-resistance certifications, and procurement rules differ across markets and sometimes within regions. Compliance burdens can slow specification if manufacturers cannot present clear, locally recognized certifications and test data. This is not a barrier that disappears with scale alone; it requires continuous investment in product validation, documentation, and market-specific positioning. Companies that treat compliance as a strategic asset rather than a cost center are better positioned to win in high-risk or fast-growing zones.
The third challenge is raw material and supply chain evolution. Shifts in fiber choice, cement sourcing, and production location can alter cost structures and lead-time reliability. Demand for cellulose fiber, for example, has been gaining momentum, supported by sustainability preferences and performance characteristics. This transition creates both opportunity and execution risk. Manufacturers must manage the technical integration of alternative fibers, ensure consistent board quality, and align procurement strategies with changing input availability and pricing dynamics.
Core Drivers of Market Change
Technology, Product Performance, and Specification Multipliers
Innovation in fiber cement is less about radical product reinvention and more about incremental performance gains that compound into specification advantage. Denser board formulations, improved surface finishes, consistent color stability under UV exposure, and enhanced resistance to moisture, impact, and fire conditions all increase the likelihood of repeat specification. When a manufacturer can demonstrate non-combustible behavior, long-term color integrity, and resilience under harsh environmental conditions, the product becomes easier to defend in architect-led selections and code-driven projects. Over time, these attributes function as a specification multiplier, reducing the effort required to justify premium positioning.
Recent market activity underscores the importance of linking product performance with event-driven visibility. At a major architecture and design conference in 2025, a manufacturer highlighted resilient exterior cladding solutions designed for hurricane exposure and fire resistance, with domestically produced fiber cement panels as a central part of the presentation. This type of engagement is strategically meaningful because it places performance claims directly in front of specifiers at the moment when design decisions are being shaped. In a category where trust and repeat use matter, trade presence and demonstration of localized production can reinforce both technical credibility and supply assurance.
Policy, Code Alignment, and Procurement Rules
Regulatory and procurement dynamics are reshaping demand patterns in ways that favor manufacturers with appropriate certifications and domestic production capability. In regions exposed to high-velocity wind events and elevated fire risk, approval for specific building zones and fire safety certifications can substantially improve a product’s eligibility for bids and specifications. Similarly, public and infrastructure-linked projects in North America increasingly emphasize domestic manufacturing eligibility. A manufacturer that achieves such certification gains an advantage in projects where sourcing rules require or strongly prefer locally produced materials. This is not merely a compliance detail; it is a market access lever that can influence project qualification and specification preferences.
The strategic implication is clear. Companies that proactively map code pathways, secure relevant certifications, and communicate compliance status in a credible, product-specific way are better positioned to capture demand in regulated segments. In contrast, manufacturers that treat certifications as passive credentials may find themselves slower to enter high-value projects or vulnerable to displacement by competitors with stronger documentation and local production credentials.
Demand-Side Shifts in Construction and Renovation Behavior
On the demand side, two overlapping trends are influencing adoption. The first is renovation and replacement activity driven by aging building stock and the desire to reduce maintenance frequency. Fiber cement boards appeal in these scenarios because they are associated with long service life, resistance to rot and insect damage, and lower repainting or repair burdens compared with certain alternatives. The second trend is new-construction demand in geographies where durability and risk mitigation carry greater monetary and operational weight. In coastal, high-heat, or wildfire-adjacent environments, specification choices increasingly reward materials that can help manage exposure to weather and fire risk.
Demand is also being shaped by design and finish expectations. Architects and builders are not only asking whether a board performs; they are asking whether it can deliver consistent aesthetics across large façades, support a range of surface treatments, and maintain appearance over time without excessive fading or degradation. Products that combine performance with predictable appearance and ease of integration into broader cladding systems tend to gain stronger repeat use. For commercial decision-makers, this means that the specification conversation is shifting from feature-level claims to long-term reliability and design continuity.
Supply Chain, Manufacturing Footprint, and Cost Structure
Capacity expansion and manufacturing location decisions are becoming central to competitive positioning. One of the most telling signals in recent market activity came from a major manufacturer announcing a substantial global spending program to support fiber cement production growth for the following fiscal year. A capacity investment at this scale signals confidence in sustained demand, a need to protect lead times, and a desire to maintain flexibility across multiple markets. It also reflects the reality that in concentrated categories, supply assurance can be as important as product features, particularly when project timelines are tight and specification windows are narrow.
Fiber Cement Market
At the same time, cost structures are influenced by input transitions and the economics of domestic versus international production. Manufacturers that can balance scale efficiency with localized output may be better positioned to serve procurement rules, reduce freight exposure, and respond faster to regional demand shifts. The broader point is that fiber cement is moving toward a market where manufacturing strategy, input mix, and distribution resilience are inseparable from commercial competitiveness. Businesses that optimize only for unit cost without considering service reliability, certification alignment, and specification support risk underdelivering in high-stakes segments.
Cement Boards Market
Competitive Landscape and Leading Strategies
Concentration as a Signal of Scale and Trust
The market’s concentration structure indicates that scale, established distribution, and recognized brand positioning remain powerful differentiators. The leading companies operate across multiple geographies and product lines, often combining siding, cladding, roofing-adjacent, and interior or partition applications into broader portfolios. This breadth allows them to serve repeat customers across project types and to capture value not just from a single application but from the broader specification ecosystem. It also creates difficulty for smaller competitors that lack similar multi-application reach or the ability to support large regional programs end to end.
Several established manufacturers illustrate distinct strategic approaches. One global leader in fiber cement siding and backer board production operates with a network of plants and continues to invest in capacity expansion to meet anticipated demand. Its commercial logic is rooted in scale, traceability, and the ability to sustain supply across markets while reinforcing brand trust. A Japanese manufacturer produces high-performance siding and panels with domestic manufacturing and resilience certifications, positioning product validation and quality assurance as core equity. A European group offers high-density cladding and boards through a recognized brand identity, relying on international production facilities to serve architectural and façade applications. A Swiss-based panel and cladding producer, incorporating former product lines into its portfolio, focuses on architectural applications where finish consistency and specification support matter.
Regional Specialists and Application-Focused Positioning
Not all competitive advantage is built on global scale. Some manufacturers compete by anchoring their position in specific regions or application verticals. An Indian producer supplies boards for ceilings, walls, and partitions with an emphasis on asbestos-free offerings, aligning product positioning with health, safety, and local building requirements. A U.S.-based company distributes and manufactures high-density compressed panels and siding for North American markets, leveraging proximity to specification channels and regional procurement expectations. A Thailand-based global supplier addresses wall, ceiling, and flooring applications, using a broad application footprint to move across multiple construction use cases.
These regional or application-focused players often succeed by reducing distance to the specifier, tailoring product support to local codes and preferences, and maintaining a clear value story around compliance, indoor safety, or application versatility. Their challenge is to scale that positioning without diluting specialization. Where they can combine local relevance with consistent quality and credible certification, they can establish durable niches even in a concentrated market.
Strategic Moves Shaping the Landscape
Recent developments highlight two recurring strategic themes: performance-led specification support and supply assurance through localized production. At a major design event, a manufacturer showcased domestically produced resilient cladding solutions with hurricane and fire resistance, reinforcing both product capability and local manufacturing credibility. In parallel, a large capacity expansion announcement signaled that one of the market’s leading players expects continued demand and is willing to commit significant capital to support growth. These moves suggest a landscape in which competitive advantage is increasingly tied to visible performance claims, code readiness, and the ability to deliver reliably where projects are awarded.
The market structure appears likely to remain concentrated, but with room for targeted differentiation. Consolidation pressure may continue where scale and compliance portfolios confer strong advantages. At the same time, fragmentation can persist in specialized applications or regions where local certification, application knowledge, and responsive service create meaningful separation. New entrants are unlikely to win on commodity terms. More plausible paths include focused offerings around specific density categories, specialty surface finishes, region-specific compliance, or sustainable fiber integration, provided these are backed by credible testing and market-specific documentation.
Forward Outlook: Trends and Commercial Implications
Trend One: Performance Certification Becomes a Commercial Accelerator
Over the next three to five years, the ability to demonstrate code alignment, fire safety credentials, hurricane-zone suitability, and consistent UV or weather performance will increasingly act as a commercial accelerant rather than a defensive requirement. Specifiers and project teams are likely to favor products that reduce risk in the approval process and simplify the justification for premium materials. This favors manufacturers that can package test results, certification status, and application guidance into clear specification tools. The commercial opportunity is in reducing friction: the easier it is to validate performance and eligibility, the faster a product can become a default choice in relevant projects.
Commercial implication: Companies should invest in product documentation, specifier-facing evidence, and market-specific approval visibility. Where certification opens doors to high-risk or public-sector projects, it should be treated as a growth enabler and communicated with precision.
Trend Two: Capacity, Location, and Supply Assurance Will Separate Leaders
Demand growth combined with procurement expectations around domestic production and reliable delivery is likely to make manufacturing footprint more strategically important. Capacity expansion where demand is durable, supported by credible local sourcing or certification, can strengthen a manufacturer’s ability to win time-sensitive projects and meet specification requirements that favor regional output. This trend may intensify as project pipelines recover and as buyers place greater weight on supply continuity and compliance credentials.
Commercial implication: Businesses should evaluate where capacity investments, input strategy, and regional production can unlock access to preferred procurement channels. In many cases, the value of capacity is not only volume; it is the ability to meet qualification rules and protect lead times in competitive bidding environments.
PW Consulting
Trend Three: Sustainability-Linked Material Shifts Will Reshape Cost and Positioning
The growing role of cellulose fiber in fiber cement board production signals a broader shift toward material choices that align with sustainability preferences and performance needs. With cellulose fiber identified as the fastest-growing raw material input in the category, manufacturers that can integrate it effectively while maintaining board quality and cost discipline may gain a narrative advantage. Sustainability in this context is not only environmental positioning; it can influence procurement decisions, brand perception, and specification preferences, especially when paired with credible claims and consistent product outcomes.
Commercial implication: Material transitions should be managed as product strategy, not just procurement optimization. Where cellulose fiber or other input shifts can be tied to verifiable sustainability benefits and maintained performance, they can support both commercial differentiation and long-term relevance. The risk lies in executing the switch without compromising quality, consistency, or cost competitiveness.
Risk Factors and Uncertainties
Despite constructive fundamentals, several uncertainties remain. Housing and construction cycles can create uneven demand, particularly if interest rates, labor availability, or project financing conditions tighten in key regions. Regulatory environments can also shift, altering which certifications matter most or changing procurement preferences in public projects. Raw material pricing and availability may affect margins, especially if input transitions are not managed carefully. Finally, competitive pressure from alternative materials will persist in segments where upfront cost or installation familiarity remains the dominant decision factor. Leaders will need to manage these risks by maintaining flexible capacity plans, robust compliance portfolios, and clear total-cost narratives.
Actionable Guidance for Decision-Makers
For Manufacturers
- Treat certification and specification support as revenue-enabling assets. Align product claims with regionally relevant codes, fire safety requirements, and resilience standards, and make documentation easy for specifiers to use.
- Evaluate capacity and sourcing strategy against market access, not just unit cost. Where domestic production, procurement eligibility, or localized service improves qualification odds, those factors should carry explicit strategic weight.
- Manage raw material transitions with product integrity in mind. If shifting toward cellulose fiber or other evolving inputs, ensure the change is supported by consistent quality controls and a defensible performance story.
For Investors
- Focus on companies with credible compliance portfolios, visible expansion commitments, and the ability to win in regulated or high-risk applications. In concentrated markets, these capabilities often translate into more durable revenue streams.
- Assess exposure to demand volatility across geographies and applications. Diversified application reach and multi-region manufacturing footprints can reduce dependence on any single project cycle.
- Watch for material strategy as a differentiator. Manufacturers that execute input transitions well may strengthen both cost structures and sustainability positioning, while poor execution can create quality or margin risk.
For Procurement and Specification Teams
- Prioritize products that reduce project risk through clear certification, consistent performance data, and reliable supply. In commission-sensitive or high-exposure environments, easier approval and stronger documentation can outweigh marginal cost differences.
- Evaluate total installed cost and lifecycle implications rather than initial price alone. Products that lower maintenance burden or improve durability may offer better long-term value, especially in demanding climates or code-heavy applications.
- Confirm sourcing eligibility and lead-time reliability early in the specification process. Projects with tight schedules or procurement requirements can be disproportionately affected by supply uncertainty.
Closing Perspective
The fiber cement board market is poised for steady expansion, but the shape of that expansion will be defined by more than volume growth. Competitive outcomes will increasingly depend on performance credibility, code alignment, manufacturing resilience, and the ability to translate technical advantage into specification ease. Businesses that treat compliance, capacity, and material strategy as integrated commercial levers are better positioned to capture durable share in a concentrated and specification-driven market. For decision-makers seeking deeper segmentation detail, cost-structure analysis, and tailored scenario planning across regions and applications, the full PW Consulting research report provides a more granular basis for strategy development and investment decisions.
For detailed analysis of this topic, please visit the official page: Fiber Cement Board Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
High-End Household P1.29 LED Display Market: Why 7.8% CAGR Signals a Strategic Reset
By pmarketresearch, 2026-09-21
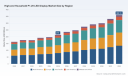
Strategic Trends and Commercial Opportunities in the High-End Household P1.29 LED Display Market
Market Overview: Trajectory and Scale
The high-end household P1.29 LED display sector has entered a phase of sustained expansion, driven by a convergence of premium content consumption, architectural integration, and technological maturation. Between 2020 and 2025, revenue climbed from 163.15 million USD to an estimated 215.0 million USD, reflecting a compound annual growth rate of 7.8 percent over the broader 2020 to 2032 horizon. This trajectory points toward a market surpassing 360 million USD by the end of the decade, as fine-pitch LED panels transition from commercial and institutional deployments into luxury residential and high-performance entertainment environments.
The P1.29 pixel pitch specification occupies a strategic middle ground in the fine-pitch spectrum. It delivers resolution and contrast levels that rival traditional premium display architectures while preserving the modularity, brightness headroom, and longevity associated with LED technology. Growth has been particularly pronounced in the 55 to 65 inch and above 65 inch segments, where consumers and enterprise buyers alike are prioritizing immersive viewing surfaces over compact consumer electronics form factors. Flat panels continue to anchor the display type mix, but curved and transparent variants are gaining traction in premium interiors where design integration and spatial awareness matter as much as picture quality. On the technology front, OLED remains a benchmark for contrast and response, yet quantum dot enhancement, mini LED backlighting architectures, and emerging micro LED approaches are reshaping expectations around color accuracy, HDR performance, and energy efficiency.
Market concentration reflects a mature but still evolving competitive arena. The top three players account for roughly 45 percent of revenue, while the top five reach approximately 60 percent. This distribution suggests a landscape where established display manufacturers and specialized fine-pitch LED specialists coexist, but it also indicates room for asymmetric moves in product ecosystems, channel partnerships, and regional differentiation.
For decision makers, the headline takeaway is that premium home LED is no longer a niche experiment. It is a growing, multi-segment category where value creation depends on aligning pixel architecture, processing capability, ecosystem integration, and cost discipline. The companies that win will be those that treat P1.29 displays not merely as screens, but as integrated components of residential entertainment, ambient media, and premium interior experiences.
Critical Challenges and Inflection Points
Despite favorable momentum, the market faces several structural tensions that will define competitive outcomes over the next few years. The first is component and supply chain timing. High-brightness SMD LEDs used in P1.29 panels rely on precision manufacturing and specialized material inputs. Premium components can experience lead times extending to 12 to 18 weeks, creating planning friction for product launches, channel replenishment, and large residential projects. In an environment where pricing visibility and delivery reliability increasingly influence buyer selection, these timing constraints can erode margin flexibility and constrain responsiveness to demand shifts.
The second challenge revolves around input cost volatility and labor intensity. Advanced surface-mount technology assembly for P1.29 modules commands hourly labor rates significantly above baseline in precision electronics facilities, reflecting the skill requirements and quality controls needed for fine-pitch production. At the same time, critical mineral sourcing for gallium and indium in RGB LED chips has shown quarterly cost fluctuations of up to 15 percent. This combination of specialized labor pricing and raw material volatility creates a cost structure that is difficult to compress purely through scale. Manufacturers must therefore manage cost through design efficiency, yield improvement, supplier diversification, and selective technology substitution rather than relying on commodity-style procurement advantages.
A third inflection point is regulatory and standards-driven safety compliance. LED displays exceeding 1000 nits brightness must meet IEC 62471 photobiological safety requirements for residential installation. As high-brightness P1.29 panels move from controlled commercial settings into living spaces, compliance becomes a gating factor for product acceptance, installer confidence, and liability management. This is not a barrier that eliminates opportunity; rather, it shifts value toward firms that can embed safety, thermal management, and installation guidance into their product and service narratives from the outset.
A fourth pressure point is geopolitical and tariff exposure. Import costs for Chinese-origin fine-pitch LED modules and panels can be impacted by US tariffs ranging from 10 to 25 percent. For P1.29 household displays, where margin structures are already shaped by premium specifications and complex manufacturing, tariff exposure can meaningfully alter landed cost, pricing strategy, and the relative competitiveness of regional sourcing models. Companies that treat trade policy as a static assumption rather than a planning variable risk underpricing, margin compression, or disrupted channel economics.
Together, these challenges point to a central reality: the P1.29 household display market rewards operational resilience and ecosystem maturity at least as much as product specifications. The inflection point is not whether fine-pitch LED belongs in premium homes, but which firms can produce, deliver, and support it reliably under cost and compliance pressure.
Key Demand Drivers
Technology innovation and integration depth are among the strongest demand catalysts. Recent cooperative moves between major consumer display organizations and professional processing specialists illustrate the shift toward integrated home display ecosystems. For example, a 2025 partnership between Samsung Electronics and Barco focused on co-developing high-end LED home display ecosystems, combining Samsung's consumer microLED direction with Barco's processing capabilities for luxury residential applications. This signals a broader industry realization that pixel pitch alone does not win premium households; processing, calibration, content compatibility, and installation reliability are equally decisive. Product-level responses reinforce the same theme. In mid-2025, LG Electronics introduced a 29-inch MicroLED-based home display designed for premium home theater setups, emphasizing advanced sub-pixel drive and enhanced HDR performance. Even at smaller screen sizes, manufacturers are pursuing high-end differentiation through drive engineering and color performance, not just panel size or resolution alone.
Competitor consolidation around driver and interface technology is also reshaping the innovation frontier. Sharp's 2024 acquisition of a microLED driver technology firm was aimed at accelerating compact, high-brightness LED panels for luxury residential displays and improving color accuracy at small pixel pitches. Driver architecture has become a strategic asset because it influences brightness uniformity, thermal behavior, signal integrity, and the ability to scale fine-pitch designs without sacrificing yield. As leading firms absorb or partner for these capabilities, the differentiation gap between pure panel assembly and full-system competence widens.
Small Pitch LED Display Market
Policy and regulatory conditions are shaping adoption patterns in ways that go beyond compliance. Safety standards for high-brightness displays and trade policy on imported modules are creating uneven cost and risk environments across regions. In practice, this encourages regional sourcing strategies, localized assembly where feasible, and product designs that can be certified for multiple regulatory contexts. It also increases the importance of documentation, installer training, and after-sale support, especially for premium residential projects where buyers and integrators expect end-to-end assurance rather than component-level performance claims.
On the demand side, consumer and enterprise behavior is shifting toward experiential and multi-use display environments. Home theater is a core application profile, reflecting the desire for cinematic image quality within private spaces. Gaming is another significant driver, as enthusiasts seek high refresh behavior, low latency, and large immersive surfaces that complement high-performance systems. Corporate presentations and digital signage also contribute to demand, though their role in the household category is more about crossover value: the same fine-pitch technologies used in professional interiors are increasingly influencing premium home expectations for color consistency, brightness stability, and modularity. What ties these applications together is that they reward accuracy, uniformity, and ecosystem readiness more than sheer size increments. Buyers are increasingly comparing fine-pitch LED against alternative premium display technologies on total experience, not just spec sheets.
Supply chain and cost structure changes are a fourth driver, but they operate differently from traditional volume-led cost reduction. P1.29 production depends on precision assembly, tight quality tolerances, and specialized component availability. As a result, competitive advantage is increasingly derived from yield optimization, process consistency, component selection, and supplier relationships that reduce exposure to long lead times and cost swings. Firms that can stabilize throughput while maintaining high-brightness performance and color consistency will be better positioned to offer predictable pricing and dependable delivery, both of which matter for premium residential projects and repeat enterprise deployments.
The strategic implication is that demand is being pulled not only by larger screens, but by better-integrated ones. buyers want displays that fit into residential design, comply with safety expectations, perform consistently under HDR and gaming workloads, and arrive with reliable support. That combination elevates the importance of product architecture, processing partnerships, manufacturing discipline, and regional cost management.
Competitive Landscape and Leading Strategies
The competitive field includes organizations with very different strategic centers of gravity. Samsung Display and LG Display operate from major South Korean electronics ecosystems and emphasize premium high-resolution LED panels and advanced OLED and LED technologies for high-end household video displays. Their advantage is often rooted in scale, system integration, and the ability to connect display hardware with broader consumer electronics and content ecosystems. Panasonic Corporation contributes a distinct angle through professional and household LED display solutions, including all-in-one systems that reduce integration complexity for end users and installers. Sharp Corporation brings attention to microLED driver technology and compact high-brightness LED panels for luxury residential applications, with a focus on precision and color behavior at small pixel pitches. Barco, based in Belgium, stands out for its emphasis on X1.2 series LED video walls with 1.29 mm pixel pitch for high-performance indoor installations, positioning around processing, installation reliability, and professional-grade performance characteristics.
A second cluster includes specialized fine-pitch LED manufacturers based in Shenzhen, Beijing, and other technology hubs. AOTO Electronics focuses on premium fine-pitch COB LED displays for high-end residential and cinema applications. Liantronics emphasizes fine-pitch and high-resolution LED screens for premium indoor household use. Absen targets small-pitch LED displays, including P1.29 mm series options for high-end residential installations. Leyard concentrates on fine-pitch LED video walls and residential display solutions. Unilumin focuses on professional LED displays with small-pitch options for household high-end applications. AVMS, in Germany, contributes high-resolution 1.29 mm GOB LED modules and indoor display systems for premium household installations. These firms often compete on modularity, pitch precision, customization, regional serviceability, and the ability to tailor products to specific interior and installation requirements.
The differentiating question is not simply who makes the smallest pitch or the brightest panel. It is who can manage the full stack most effectively. Leading strategies tend to fall into several patterns. One is ecosystem integration: combining panel hardware with processing, calibration, and installation support so that the display arrives as a usable premium solution rather than a component. Another is technology specialization: building advantage around driver architecture, GOB or COB module design, sub-pixel drive, or compact high-brightness implementations that improve color accuracy and uniformity at fine pitches. A third is regional and channel positioning: aligning manufacturing footprint, certification readiness, and distribution relationships to reduce tariff exposure, shorten delivery paths, and strengthen installer trust. A fourth is application targeting: designing product lines for specific use cases such as home theater, luxury interiors, or high-performance indoor installations where brightness, HDR behavior, and viewing distance requirements differ.
The market landscape is evolving through both consolidation and differentiation. Recent partnerships and acquisitions indicate that firms are seeking capabilities that extend beyond panel fabrication. The trend toward co-developed ecosystems, driver technology absorption, and specialized module design suggests that vertical depth is becoming a competitive necessity in the premium segment. At the same time, the presence of multiple specialists indicates that differentiation by application, region, and installation model remains viable. New entrants can still compete if they bring a credible combination of fine-pitch precision, ecosystem readiness, and dependable delivery, but head-to-head competition on price alone is increasingly difficult given labor intensity, component lead times, and compliance costs.
For buyers and investors, the practical conclusion is that market leadership is increasingly defined by reliability and integration rather than headline specifications. A strong P1.29 strategy now involves a clear answer to how the product will be manufactured consistently, certified for residential use, supported through installation, and positioned against tariff and sourcing risks.
Future Outlook: Three Strategic Trends
One major trend over the next three to five years is the deepening of integrated home display ecosystems. As premium residential deployments grow, the value of standalone panels will increasingly be judged against full solution quality: processing, calibration, compatibility, installer support, and long-term serviceability. This favors organizations that can coordinate hardware, software-adjacent processing, and installation workflows into a coherent offering. The opportunity lies in owning a more complete experience pathway, especially in high-value residential projects where buyers and integrators prioritize dependable outcomes over isolated performance claims. The risk is that integration expands scope and cost, requiring disciplined execution and strong partnership models where internal capability is incomplete.
A second trend is continued coexistence and selective convergence between fine-pitch LED and alternative premium display technologies. OLED, quantum dot, mini LED, and micro LED approaches will continue to compete for attention in the premium household category, each with strengths in contrast, color volume, brightness headroom, or form factor. Rather than a single winner, the market is likely to segment by use case and buyer priorities. Some environments will favor LED for brightness robustness and modular scalability, while others will lean toward competing technologies for specific visual characteristics. The commercial opportunity here is in positioning P1.29 products with a clear, defensible advantage for particular applications and design requirements rather than attempting to win every premium use case with a single architecture. The uncertainty is that technological progress in competing categories could shift purchase criteria faster than product cycles can adapt, especially if HDR, color accuracy, and energy performance continue to improve across technologies.
A third trend is the growing importance of regional cost and compliance strategy. Tariff exposure, raw material volatility, labor intensity, and safety standards will continue to shape where and how P1.29 products are sourced, assembled, certified, and delivered. Companies that design regional flexibility into their supply and distribution models are more likely to maintain pricing stability and market access across jurisdictions. The opportunity is to build repeatable compliance and sourcing frameworks that reduce surprise costs and accelerate project execution. The risk is that trade and input cost conditions may shift in ways that disrupt assumptions built into pricing, margin planning, and regional roadmaps, especially for firms with concentrated sourcing exposure.
LED Display Market
These trends point to a market where durable advantage will come from consistency, integration, and adaptive sourcing rather than from short-lived specification leadership alone.
Actionable Guidance for Decision Makers
For manufacturers, the strategic priority is to strengthen the full product and delivery chain behind the P1.29 specification. That means investing in yield, process consistency, driver and module design, safety and compliance readiness, and supply relationships that reduce exposure to long lead times and cost volatility. Product differentiation should be tied to application outcomes, whether that is superior HDR behavior for home theater, reliable brightness uniformity for luxury interiors, or modular installation advantages for premium indoor projects. Firms that can demonstrate dependable production performance and installation confidence will be better positioned to defend pricing and win premium projects even when competition intensifies.
For investors, the emphasis should be on capability depth rather than headline unit growth alone. Organizations with strong integration strategies, credible compliance management, resilient sourcing, and clear differentiation in targeted applications are more likely to sustain margins and market access. It is equally important to assess exposure to tariff-gated cost structures and raw material volatility, since these factors can influence not only profitability but also the competitiveness of specific geographies and channel models. The most attractive opportunities are likely to be found where technology positioning, service reliability, and regional strategy reinforce one another.
For procurement and channel decision makers, the priority is to evaluate P1.29 offerings on total project value rather than panel-level specifications alone. This includes assessing certification and safety readiness for residential use, installation support, component availability, delivery reliability, and the expected lifecycle of processing and driver performance. Preference should tilt toward suppliers that can reduce integration risk and provide predictable outcomes, particularly in high-value residential projects where installation quality and long-term performance are as important as initial image quality. Clear visibility into sourcing, compliance, and support expectations will help reduce downstream disruption.
PW Consulting
The premium household P1.29 LED display market is moving from early adoption to structured competition, and the pace of change in integration, cost exposure, and application targeting makes detailed intelligence increasingly valuable. For decision makers who need granular segment data, regional cost modeling, competitive benchmarking, and scenario analysis across the 2026 to 2032 horizon, the full PW Consulting research report provides deeper segmentation detail, company-level context, and tailored strategic recommendations to support board-level planning and investment decisions.
For detailed analysis of this topic, please visit the official page: High-end Household P1.29 LED Display Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Paint Remover Market: Strategic Shifts, Regulatory Headwinds, and the Bio-Based Transition
The global paint remover market has moved past a period of incremental growth and entered a phase of structural transformation. Valued at approximately $1.56 billion in 2025 and projected to reach $2.29 billion by 2032, the market is expanding at a compound annual growth rate of 5.6 percent from 2020 through 2032. This trajectory reflects more than steady demand for surface preparation solutions. It signals a fundamental recalibration of product chemistry, regulatory compliance requirements, and end-user expectations across residential, commercial, industrial, and automotive refinishing channels. For executives and investors evaluating chemical specialties and maintenance markets, the paint remover segment offers a clear case study in how environmental regulation and innovation intersect to reshape competitive advantage.
The market remains moderately concentrated, with the top three firms accounting for roughly 42.5 percent of revenue and the top five capturing approximately 52.1 percent. This concentration suggests that established names retain significant shelf presence and distribution leverage, yet it also leaves meaningful room for differentiated entrants that can solve persistent performance and compliance pain points. The growth profile from 2026 onward indicates that demand will not be evenly distributed across product categories or end-use segments. Instead, value will accrue to formulations that reconcile removal effectiveness with worker safety, environmental stewardship, and application convenience.
Current Market Conditions and Critical Inflection Points
The paint remover industry is operating at the intersection of three converging pressures. First, legacy solvent chemistries face mounting regulatory and reputational constraints, forcing both consumer and industrial buyers to rethink procurement standards. Second, reformulation costs and supply-chain complexity are raising per-unit economics for compliant alternatives, which compresses margins for firms slow to adapt their manufacturing footprints. Third, end-users increasingly expect products that perform reliably on vertical surfaces, detailed trim, and mixed substrates without sacrificing usability or indoor air quality. These forces are not separate issues; they reinforce one another and define the strategic agenda for the next cycle.
A clear inflection point is the post-ban operating environment for methylene chloride and related restricted solvents. The U.S. Environmental Protection Agency finalized a ban on most uses of methylene chloride in April 2024, with consumer sales already prohibited since 2019 and remaining industrial uses subject to strict workplace protections. In Europe, REACH restrictions have limited dichloromethane concentrations in consumer paint strippers across member states since 2010, with full implementation completed in 2012. California has gone further by classifying paint strippers containing methylene chloride as a Priority Product, requiring evaluation of safer alternatives for both consumer and commercial channels. These measures have shifted the center of gravity in product design from performance-only optimization to performance-plus-compliance.
A second inflection point lies in the economics of reformulation. Moving away from methylene chloride and N-methyl-2-pyrrolidone is accelerating adoption of acetone, dimethyl carbonate, and water-based systems that trade off higher per-gallon costs for regulatory certainty and safer handling profiles. For manufacturers, this means that compliance is no longer a checkbox but a cost-structure decision with direct implications for pricing, channel strategy, and margin defense. For buyers, it means that total cost of use now includes exposure management, disposal considerations, and training burden, not just purchase price.
Core Drivers Reshaping Demand and Competitive Advantage
Technology and formulation innovation are the most visible drivers of change. The market is seeing a steady shift toward bio-based and lower-toxicity solvent systems that maintain stripping efficacy while reducing environmental and occupational risk. Recent product launches illustrate how companies are translating regulatory pressure into commercial opportunity. In March 2026, Cortec Corporation introduced EcoLine Surface Reveal with 77 percent USDA-certified biobased content and biodegradable ingredients, formulated without methylene chloride or NMP for metal surface cleaning. In the same month, Rust-Oleum Corporation released a gel-based paint remover designed for vertical surfaces and intricate detailing in home renovations. By April 2026, 3M Company launched a next-generation solvent-based paint remover with a low-odor, biodegradable formula. These launches are not isolated product updates; they reflect a broader pattern in which formulators are building differentiation on biobased content, application geometry, and odor and disposal profiles.
PW Consulting
Policy and regulatory environment is the second core driver. Beyond the bans and concentration limits already in force, the direction of travel is toward tighter workplace protections, greater ingredient disclosure, and increased scrutiny of safer alternative assessment. The EU’s earlier REACH framework set a long-standing precedent for limiting hazardous solvents in consumer products, while U.S. federal and state actions have added friction to legacy chemistries and incentivized reformulation. For global suppliers, regulatory divergence between regions creates both complexity and opportunity: products that satisfy stringent U.S. and European standards can command premium positioning in channels where compliance is a purchasing criterion, while also future-proofing portfolios against further restrictions.
Demand-side behavior is changing in ways that reward usability and transparency. In residential renovation, buyers and professional contractors alike prefer gel and targeted formulations that cling to vertical surfaces, control runoff, and simplify cleanup. In industrial and maintenance contexts, surface preparation teams are increasingly weighing total application time, safety training requirements, and waste handling against raw removal speed. Rising demand for biobased alternatives is also increasing supply-chain transparency expectations among home-improvement buyers, who want clearer information about ingredient origins and environmental claims. This shift in procurement mindset is pushing manufacturers to communicate performance and sustainability attributes with greater precision.
Supply-chain and cost-structure changes form the fourth driver. Reformulation away from restricted solvents is raising per-gallon costs by an estimated 20 to 30 percent for certain alternative systems, which reshapes the economics of production and distribution. At the same time, rising interest in biobased inputs is pressuring suppliers to improve traceability, certify content claims, and manage feedstock variability. Firms that can secure reliable access to alternative solvents, optimize process efficiency, and align packaging and application design with end-user workflows are better positioned to absorb cost increases without losing competitiveness. Those that treat reformulation as a one-time compliance exercise risk ceding ground to rivals who embed safer chemistry into a broader value proposition.
Competitive Landscape and Strategic Positioning
The competitive set spans established chemical and coatings players, specialty formulators, and regional suppliers serving professional and consumer channels. Cortecx Corporation and 3M Company illustrate how large innovators are leveraging R&D capacity to introduce biodegradable and low-odor solvent systems that align with shifting regulatory and user expectations. The Sherwin-Williams Company and Rust-Oleum Corporation continue to strengthen retail-facing gel products tailored to vertical surfaces and detailed renovation work, where ease of application directly influences purchase decisions. Henkel AG & Co. KGaA has doubled down on sustainable, non-toxic stripping technologies, including an R&D facility expansion in Germany in March 2025 aimed at developing solutions compliant with EU chemical safety directives. PPG Industries, WM Barr & Co., Dumond Chemicals, Sunnyside Corporation, and Twin Specialties, Inc. each occupy distinct niches, from consumer-friendly citrus and fast-acting options to professional-grade stripping for maintenance and repair markets.
The strategic positioning that separates leaders from followers is increasingly built on three elements. The first is chemistry differentiation that does more than remove paint. Biobased content, absence of methylene chloride and NMP, low odor, and biodegradable profiles are becoming selling points in channels where safety and environmental claims influence repeat purchase. The second is application engineering. Gel formulations, controlled viscosity, and surface-specific guides reduce misuse, improve outcomes on vertical and detailed surfaces, and lower the perceived effort of the job. The third is compliance storytelling and transparency. Suppliers that can demonstrate ingredient safety, certification where relevant, and practical handling benefits are better equipped to navigate regulated procurement and to justify price premiums in a market where reformulation costs are rising.
Market structure is evolving along two parallel paths. Consolidation pressure exists where scale in distribution, brand recognition, and R&D budgets create barriers for smaller generic players. At the same time, differentiation and fragmentation are evident in the number of niche launches targeting specific substrates, surface geometries, and compliance requirements. New entrants and smaller specialists can still win by solving a narrow but valuable problem well: a gel for vertical renovation work, a biobased metal-cleaning stripper, or a fast-acting consumer option with a clear safety narrative. The broader trend is toward a market where incumbents defend share through portfolio breadth and compliance leadership, while challengers gain traction with focused formulation and application advantages.
Worldwide Oil Stain Remover Market
Strategic Outlook: Three Trends to Watch Over the Next Three to Five Years
The first trend is accelerating adoption of bio-based and low-toxicity chemistries as the default expectation in consumer and many professional channels. As regulatory restrictions on legacy solvents continue to bite and buyers become more familiar with safer alternatives, products that combine effective removal with biobased content, low odor, and biodegradable attributes will capture a growing share of new adoption. The commercial opportunity lies in designing complete value propositions around these attributes, including packaging, instructional support, and claims that withstand scrutiny. The risk is overclaiming or inconsistent performance, which can erode trust quickly in a category where results are immediately visible to the end-user.
The second trend is application-specific innovation becoming a central battleground. Vertical surfaces, intricate detailing, mixed substrates, and metal cleaning each impose different requirements on viscosity, dwell time, rinsing, and waste handling. Companies that tailor formulations and application guides to these scenarios can command stronger loyalty and reduce the likelihood of product substitution. For industrial and maintenance buyers, the opportunity is to reduce total cycle time and exposure risk; for consumer channels, the opportunity is to simplify the job and improve perceived ease of use. The uncertainty here is that over-specialization can fragment production and inflate inventory complexity, so firms need to balance segment focus with manufacturing efficiency.
The third trend is the widening gap between firms that treat compliance as a cost center and those that treat it as a design parameter. Reformulation cost pressure, estimated at 20 to 30 percent higher per gallon for certain alternative systems, will not disappear. The winners will be those that integrate safer chemistry into product architecture, supply-chain planning, and channel messaging from the outset, rather than retrofitting after regulatory events. There is real upside in using compliance leadership to access regulated procurement and to build brand trust, but there is also exposure if ingredient claims, supply continuity, or performance consistency do not hold up under real-world use. Additionally, regional regulatory divergence means that global portfolios must be designed with modularity and local adaptation in mind, not just a single global formula.
Actionable Recommendations for Decision-Makers
For manufacturers and formulators, the priority is to align product development with the dual demands of performance and compliance. Investment should focus on biobased and low-toxicity solvent systems that can demonstrate reliable removal on target substrates, along with application formats such as gels and targeted formulas that reduce misuse and improve outcomes on vertical and detailed surfaces. Equally important is supply-chain readiness: securing feedstock for alternative solvents, validating ingredient claims, and building manufacturing flexibility to manage cost variability. Firms should also strengthen instructional content and safety resources, because in a category where handling and disposal matter, guidance is part of the product experience.
Worldwide Photoresist Remover Market
For investors, the appeal of the paint remover market lies in its shift from commodity-like competition to value-driven differentiation. Due diligence should weigh formulation capability, regulatory responsiveness, and the credibility of sustainability claims more heavily than historical revenue alone. Companies with credible biobased or low-toxicity portfolios, clear application advantages, and disciplined cost management are better positioned to defend margins in a higher-cost reformulation environment. At the same time, investors should monitor exposure to regional regulatory divergence and the risk that overconcentration in any single chemistry could become a liability if standards tighten further.
For procurement and channel leaders, the strategic task is to evaluate total cost of use rather than list price. Safer, application-specific formulations may carry higher unit costs but can reduce training burden, exposure management, and waste handling, while improving consistency on difficult surfaces. Procurement criteria should include ingredient safety, compatibility with target substrates, and the quality of application guidance and support resources. Building relationships with suppliers that can demonstrate compliance leadership and transparent ingredient information will reduce downstream risk and improve purchasing confidence in regulated environments.
Understanding where the market is heading requires more than headline growth figures. The interplay of formulation innovation, regulatory pressure, application specificity, and cost structure is reshaping how value is created and captured in this category. For teams that need granular segmentation data, regional demand patterns, competitive share estimates, and tailored commercial scenarios, the full PW Consulting study provides the detailed breakdown and working assumptions behind these trends. It is designed to support product roadmap decisions, investment screening, and procurement strategy with the level of specificity that general market narratives cannot provide.
For detailed analysis of this topic, please visit the official page: Paint Remover Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Realities of the Laptop Bag Market: Navigating Growth, Fragmentation, and Technology-Driven Value
The laptop bag market has evolved far beyond a simple accessory category into a strategic intersection of mobility, security, and professional identity. With a global market valuation approaching $223 million in 2025 and a projected compound annual growth rate of 5.9 percent through 2032, the sector demonstrates consistent expansion, yet that headline growth masks significant structural shifts beneath the surface. Revenue dispersion across backpacks, messenger bags, briefcases, and other formats reveals a category in transition. The backpack segment commands the largest share of revenue, while briefcases and messenger bags continue to serve niche professional and hybrid work use cases. At the application level, business professionals and students represent the dominant demand pools, each pulling the market in different directions when it comes to durability, organization, and aesthetic expectations.
Understanding this market requires moving past aggregate numbers and examining the tension between steady demand growth and a landscape that is becoming more fragmented, more technologically demanding, and more sensitive to procurement dynamics. For executives, investors, and category managers, the laptop bag category is no longer just about carrying a device. It is about signaling competence, reducing risk, and integrating into broader workplace mobility strategies.
Market Landscape and Core Challenges
The laptop bag market's growth trajectory is built on a strong foundation of device proliferation and the enduring need for organized, protected mobility. From 2020 to 2025, revenue expanded steadily, reflecting a recovery from earlier pandemic-era discontinuities and a subsequent normalization of device-carrying habits across work, education, and travel. The forecast period through 2032 extends that momentum, though growth will not be uniform across segments or geographies. The top-line trajectory depends on how well manufacturers adapt to shifting form factors, sustainability expectations, and procurement rules that increasingly shape what gets bought and why.
Several structural challenges define the current market environment.
-
Category saturation and differentiation fatigue. As demand grows, the market has attracted a wide range of players, from global luggage and mobility brands to specialized accessory manufacturers and private-label suppliers. That breadth creates noise. Consumers and procurement teams are confronted with comparable-looking products that vary mostly in stitching, zipper quality, and minor padding differences. Without meaningful differentiation, price competition intensifies and margin structures compress.
-
Device format evolution and protection uncertainty. Laptop sizes and form factors are not static. Thinner chassis, heavier premium builds, and the continued co-existence of 13-inch to 17-inch screen sizes complicate compartment design. A bag that performs well for one generation of devices may feel misaligned with the next. This pushes manufacturers to design for flexibility rather than fixed dimensions, adding engineering complexity and testing costs.
-
Procurement rules and specification-driven purchasing. Institutional buying has become more specific. Public-sector and enterprise purchasing frameworks increasingly define acceptable materials, water resistance, and certification requirements, which narrows the pool of eligible products. This dynamic raises the barrier for generic offerings and rewards suppliers that can demonstrate compliance, traceability, and reliable product documentation.
These challenges do not negate growth, but they change the conditions under which growth is captured. The market rewards suppliers that can convert protection, compliance, and organization into defensible value rather than competing solely on appearance or brand recognition.
Key Demand Drivers Reshaping the Category
Several intersecting forces are shaping how the laptop bag market expands and where value is concentrated.
Technology Innovation and Protection Engineering
Protection has become a more sophisticated value proposition. The market is moving beyond generic padding toward engineered cushioning, impact distribution, and integrated organization systems that reduce movement and friction. RFID-blocking features, anti-theft design elements, and smarter compartment layouts are increasingly viewed as essential rather than premium extras, especially for business users who carry devices alongside credentials, payment cards, and sensitive documents.
This shift matters because protection is not just about preventing damage. It is about reducing anxiety during daily commuting, travel, and public-space use. The most relevant innovations are those that make protection feel seamless. A bag that protects effectively while remaining light, accessible, and professional in appearance can command stronger positioning than one that relies on bulky armor-like construction.
Demand-Side Behavior and Hybrid Work Realities
Work patterns continue to reshape product expectations. Hybrid and flexible work arrangements have made the laptop bag a daily transitional object, moving between home, office, co-working spaces, and client sites. That usage pattern increases the importance of versatility. Users want bags that support quick access, clean organization, and a professional look without sacrificing comfort during longer carry periods. Students, meanwhile, prioritize durability, storage flexibility, and affordability, which puts pressure on manufacturers to balance feature richness with accessible price points.
The result is a more demanding buyer profile. Consumers and institutions are not simply asking for a bag that fits a laptop. They are asking for a carry system that supports workflow, lowers risk, and remains appropriate across multiple settings. This behavioral shift is one of the strongest drivers behind continued category expansion, but it also raises the stakes for product design and messaging.
Sustainability, Certification, and Procurement Alignment
Sustainability has moved from a marketing dimension to a procurement and design consideration. Certifications, material transparency, and durable construction are increasingly relevant in commercial buying decisions. Some procurement frameworks explicitly factor in product attributes such as water-resistant nylon models or ENERGY STAR-related considerations where applicable. That does not mean every buyer demands the same credentials, but it does mean that documentation, compliance, and verifiable product claims are becoming part of the commercial conversation.
For manufacturers, the implication is clear. Sustainability is not just a narrative; it is a specification. Suppliers that can align materials, manufacturing practices, and product testing with purchasing requirements will have an advantage in institutional channels, particularly where volume purchasing and standardization matter.
PW Consulting
Supply Chain Pressures and Cost Structure Realignment
The broader cost environment continues to influence category economics. Raw materials, manufacturing processes, logistics, and compliance testing all contribute to the final cost structure. As buyers become more attuned to specifications and durability, there is less room to compete through aggressive cost-cutting that compromises quality. At the same time, efficient sourcing, modular component design, and consistent quality control can protect margins without eroding trust.
This driver is especially important because the laptop bag market is not growing through a single high-volume breakthrough. It is growing through cumulative improvements in usability, reliability, and alignment with institutional and professional buying behavior. Cost discipline, therefore, has to be balanced against the risk of weakening the very attributes that justify premium positioning.
Competitive Landscape and Leading Strategies
The competitive environment reflects a blend of established mobility brands and specialized accessory players, each pursuing a different interpretation of value. The market is not dominated by a single category standard. Instead, it is shaped by competing philosophies: professional security, urban lifestyle integration, rugged protection, and lightweight portability.
Differentiation Strategies Among Key Players
Global players such as Samsonite have built their laptop bag positioning around professional and business-oriented backpacks and briefcases with RFID blocking and anti-theft features. Their strength lies in translating trust and professional image into structured protection and organized carry. Thule approaches the category from an urban and active lifestyle angle, emphasizing padded protection and sustainability credentials that appeal to users who value both durability and responsible product design. Targus focuses on premium executive and work backpacks with innovative protection systems, reinforcing a professional identity while upgrading organization and device security. Kensington addresses rugged protection needs through cases, sleeves, and carrying bags that serve users looking for stronger device safeguards. DICOTA contributes a more lightweight and cushion-protection-oriented approach, targeting users who prioritize portability without sacrificing protection.
What these strategies share is a focus on reducing uncertainty. Whether through anti-theft features, certified protection, rugged construction, or sustainability positioning, the leading players are trying to make the laptop bag feel less like a commodity and more like a functional part of a professional or lifestyle ecosystem.
Strategic Positioning Patterns
A few patterns are emerging across the competitive field.
-
Protection as a product system, not a feature. Leading designs increasingly treat protection as an integrated outcome of compartment structure, padding distribution, closure design, and material choice. This makes it harder for followers to copy a product by imitating a single attribute.
-
Professional identity and aesthetic discipline. Business users still expect products that look appropriate in formal and semi-formal environments. That does not mean conservative design only, but it does mean restraint, clean lines, and coherent material choices often outperform visually noisy products.
-
Compliance and documentation as commercial leverage. Brands that can provide clear product information, relevant certifications, and procurement-friendly specifications gain traction in institutional channels where purchasing decisions are more structured.
Market Structure Evolution
The market is not consolidating into a single dominant model, nor is it fully fragmenting into unrelated niches. Instead, it is becoming more layered. At one level, global players maintain visibility through brand trust and broad distribution. At another level, specialized brands compete with highly focused product architectures that address a narrower set of use cases more intensely. New entrants can still find room, particularly if they target underserved intersections such as hybrid-use bags that combine professional appearance with light weight, or products designed explicitly for procurement specifications.
One notable dynamic is that recent product activity has centered on refinement rather than radical reinvention. Launches have emphasized premium protection, improved organization, convertible formats, and broader professional collections. That suggests a market that is maturing in its core expectations while still searching for better ways to combine protection, mobility, and style. Instructional and institutional buying dynamics further reinforce the importance of meeting defined product requirements rather than relying on brand appeal alone.
Future Trends and Commercial Implications
Looking ahead three to five years, several trends are likely to shape where growth and profitability concentrate.
Trend One: Protection Becomes Smarter and More Integrated
The next phase of product development will likely treat protection and organization as a unified system. Expect more designs that combine impact mitigation with smarter storage architecture, quick-access zones, and security-oriented features that do not add bulk. The commercial opportunity lies in packaging these attributes into products that are still comfortable to carry and coherent in appearance. Risk arises if protection features become overdesign-heavy, making bags feel cumbersome or visually off-putting for everyday professional use.
Trend Two: Procurement-Ready Products Gain Share in Institutional Channels
Demand from structured buying environments is likely to become more influential. As purchasing frameworks specify attributes such as material performance, water resistance, and certification alignment, suppliers with compliant, well-documented products will be better positioned to win volume business. The opportunity is to build procurement-ready portfolios that can scale across organizational buyers without sacrificing brand consistency. The uncertainty is that procurement requirements can vary widely by region and institution, making it harder to rely on a single standardized offering.
Trend Three: Hybrid-Use Design Expands the Addressable Use Case
As users continue to move between settings, hybrid-use bags are likely to become more important. Products that perform well for commuting, office use, and light travel can widen the value proposition and reduce the need for multiple specialized bags. This creates an opportunity to design for flexibility, modularity, and professional credibility at the same time. The challenge is maintaining a clear identity. A hybrid product that tries to serve too many audiences can lose coherence and weaken perceived value.
Underlying Risks and Uncertainties
A few cautionary signals should not be ignored. Device form factors will continue to evolve, and bags that are too tightly optimized for current sizes may lose relevance if sizes, weights, or carrying preferences change. Sustainability expectations may intensify, increasing the compliance burden for manufacturers that lack robust documentation or material strategies. Competition may also push the category toward incrementalism, where features accumulate without delivering a clearly superior user experience. If that happens, the market may grow but margins and brand loyalty could erode.
Strategic Action Points for Decision Makers
For Manufacturers and Brand Leaders
-
Design for system-level protection and organization rather than isolated features. Products that feel engineered, not assembled from separate add-ons, are better positioned to defend price and trust.
-
Build procurement-ready documentation and specification clarity into product development early. The ability to demonstrate compliance and performance consistency can open institutional channels that are otherwise difficult to access.
-
Balance hybrid-use versatility with a clear point of view. Versatility should expand relevance, not blur identity.
For Investors and Strategic Capital
-
Prioritize brands with defensible differentiation in protection, organization, or procurement alignment. Growth alone is not enough; the quality of growth determines whether a player can sustain margins.
-
Watch for product refinement cycles that strengthen core value propositions rather than dilute them through feature overload. Investment theses should favor companies that can convert product credibility into repeat professional demand.
-
Monitor how sustainability and specification requirements reshape sourcing and marketing costs, since those factors will increasingly influence profitability in commercial channels.
For Procurement and Enterprise Buyers
-
Evaluate laptop bags as part of a broader device-carrying and security strategy, not merely as accessories. Specifications related to protection, water resistance, and organization can directly affect daily operational reliability.
-
Prefer suppliers that can provide clear product documentation, repeatable quality, and compatibility with institutional purchasing requirements. This reduces the risk of mismatched procurement and user dissatisfaction.
-
Balance professional appearance expectations with real-world carry needs. The best choice is often the product that supports workflow across multiple environments without requiring users to compromise on protection or usability.
Conclusion
The laptop bag market is expanding on the back of device mobility, hybrid work habits, and rising expectations for protection and organization. Yet the more important story is not the growth rate itself, but the changing criteria that determine who captures value within that growth. Differentiation is increasingly tied to how well a product integrates protection, professional identity, compliance readiness, and everyday usability. Brands that treat the category as a functional system rather than a cosmetic accessory are better positioned for the next phase of expansion.
Backpack Travel Bag Market
For leaders operating in this space, the strategic question is not whether demand will continue, but whether product strategy and commercial positioning are aligned with the specifications, behaviors, and purchasing dynamics that now shape the market. More granular segmentation data, regional dynamics, and tailored strategic scenarios can help narrow the gap between market-level trends and actionable business decisions.
Luggage Market
For detailed analysis of this topic, please visit the official page: Laptop Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Blood and Fluid Warmer Market: How 7.85% CAGR and Critical Care Demand Are Redefining Growth
By pmarketresearch, 2026-09-21
Market Intelligence Brief: Strategic Trends and Commercial Opportunities in the Blood and Fluid Warmer Market
The blood and fluid warmer market has moved from a niche clinical niche to a strategically important segment within broader patient temperature management and infusion therapies. Driven by rising surgical volumes, stricter perioperative thermal management standards, and a shift toward portable, high-flow warming solutions, the sector is entering a phase of disciplined growth rather than speculative expansion. Market size reached approximately USD 1.29 billion in the base year before progressing to an estimated USD 2.17 billion by the end of the forecast horizon, with a compound annual growth rate of 7.85 percent. This trajectory reflects steady demand expansion, but it also masks structural shifts in how devices are engineered, regulated, reimbursed, and positioned across care settings. For executives, investors, and procurement leaders, the opportunity lies not in assuming uniform growth, but in understanding where differentiation, compliance readiness, and real-world clinical adoption will separate winners from the rest.
Market Profile and Defining Challenges
The overall market has expanded consistently from 2020 through the base year, with acceleration evident in the most recent periods. Growth is not evenly distributed across product types, clinical applications, or geographies, even though high-level splits point to clear concentration patterns. Intravenous warming systems remain the largest product category, reflecting the long-standing clinical imperative to warm fluids during transfusions, massive resuscitation, and high-volume infusion. Patient and surface warming systems also contribute meaningfully, underscoring how fluid warming is increasingly evaluated within a broader thermoregulation strategy rather than as a standalone device class. By care setting, surgical environments continue to anchor demand, while newborn care and acute care represent substantial and growing use cases. Regional dynamics show a mature, high-volume base in North America, followed by a sizable European footprint, with Asia-Pacific, Latin America, and the Middle East and Africa collectively representing a smaller but strategically important growth pool. Concentration metrics indicate a moderately consolidated environment, with the top three players holding roughly 42.5 percent of revenue and the top five approaching 58.2 percent, leaving room for specialized entrants and regional champions to compete on niche performance, portability, and workflow integration.
Against this backdrop, three challenges define the current market inflection point.
- Clinical precision and safety are now central purchase criteria, not secondary features. Fluid warming devices must deliver consistent temperature control across variable flow rates while minimizing risks such as air emboli, under-warming, or overheating. Regulatory scrutiny around labeling, performance specifications, and air-in-line risks has raised the compliance bar, making verification, documentation, and post-market monitoring essential parts of commercial viability.
- Workflow integration and portability are reshaping purchasing logic. Hospitals and emergency teams increasingly prefer solutions that can be deployed quickly, fit within limited clinical space, and integrate with existing infusion and fluid management workflows. This shifts competition away from basic heating capability toward usability, battery performance, flow range, and compatibility with high-acuity scenarios.
- Reimbursement clarity and procurement efficiency influence adoption velocity. Changes in coding status and hospital outpatient payment mechanics can alter the financial calculus for facilities evaluating warming systems, particularly in outpatient, emergency, and high-throughput surgical environments. Commercial teams therefore need to understand not only clinical evidence but also the administrative and reimbursement pathways that determine how quickly a device can be justified and deployed.
Core Demand Drivers Shaping the Market
The market’s direction is being pulled by interacting forces across technology, regulation, demand behavior, and cost structure. Each driver has practical implications for product strategy and commercial planning.
Technology Innovation and Performance Gaps
Innovation is moving beyond basic heating elements toward systems that combine flow adaptability, air detection, portability, and material safety. Recent developments illustrate how device makers are responding to performance requirements in specific use cases. One notable example is the clearance of a moderate-to-high flow blood and fluid warmer with automatic air detection, signaling that air-in-line protection and flow range are becoming baseline expectations rather than differentiators only in premium products. Another clearance focused on pediatric use, highlighting how smaller patient populations and lower flow requirements create distinct engineering challenges and open targeted commercial pathways. At the same time, device materials and manufacturing quality remain under scrutiny, with attention to components such as coated heating chambers and testing protocols aligned to recognized standards. These details matter because clinicians and procurement teams increasingly evaluate the entire system, not just the warming function in isolation.
Regulatory and Guideline Environment
Guideline updates and safety communications are reshaping how facilities think about active warming. Updated perioperative guidance has reinforced the importance of active temperature management, including fluid warming, which supports more consistent adoption in surgical and acute care pathways. Equally important, ongoing safety communications related to air-in-line and embolism risks with infusion pumps, fluid warmers, and rapid infusers continue to influence device design expectations and hospital vigilance. Rather than slowing the market, these dynamics tend to reward manufacturers that can demonstrate robust risk mitigation, clear labeling, and credible post-market documentation. For commercial leaders, regulatory readiness is becoming a market access advantage because it reduces adoption friction in risk-averse procurement environments.
Worldwide Peritoneal Dialysis Bag Warmer Market
Demand-Side Behavior and Care Setting Evolution
Clinical demand is expanding beyond traditional operating room settings. Emergency, trauma, newborn, and acute care teams are increasingly seeking warming options that can be mobilized quickly and used across variable flow conditions. Portable and battery-capable systems are particularly relevant where immediate access matters and where reliance on fixed infrastructure may limit responsiveness. This shift changes the purchasing conversation: it is less about buying a warming device for a single department and more about equipping multiple care points with solutions that fit fast-paced workflows. The practical effect is greater interest in devices that can support both high-flow resuscitation and lower-flow maintenance scenarios without forcing clinicians to switch between disconnected systems.
Supply Chain, Cost Structure, and Commercial Execution
Cost pressures and supply chain reliability remain important but are now intertwined with product complexity. Devices with more advanced sensing, air detection, and portability requirements require disciplined component sourcing and quality assurance. At the same time, procurement groups are under pressure to reduce total cost of ownership, standardize wherever possible, and avoid device proliferation that complicates training and maintenance. The result is a market where value is increasingly defined by the combination of clinical performance, training burden, service reliability, and compliance support. Manufacturers that can present a complete operational case, not just a hardware specification, are better positioned to win recurring adoption and repeat purchases.
Competitive Landscape and Strategic Positioning
The competitive field includes large diversified healthcare companies, specialized device manufacturers, and regional players with focused product lines. Profiles span companies offering integrated fluid warming within broader portfolios, portable systems designed for emergency and transport use, and engineered solutions emphasizing battery operation, flow range, or compact design. This mix creates a multi-layered market in which some competitors compete on scale, distribution, and cross-product integration, while others compete on portability, specialized clinical scenarios, and rapid deployment.
Differentiation Paths Among Leading Players
Several strategic positions are visible across the field.
- Portfolio integration plays: Some companies embed blood and fluid warming within wider fluid management, infusion, or critical care offerings. The advantage is cross-selling leverage, existing clinical relationships, and the ability to present a coordinated solution rather than a standalone device. The challenge is maintaining product-level excellence and responsiveness when warming is one component among many priorities.
- Specialized portable and high-flow solutions: Other players focus on compact, battery-powered, or high-flow devices built for emergency, trauma, and transport contexts. Their edge comes from mobility, quick setup, and performance in scenarios where fixed systems are impractical. These offerings can win strong loyalty in specific departments but must demonstrate durable reliability and regulatory compliance to scale.
- Niche engineering and targeted clearances: A subset of manufacturers builds differentiation around specific use cases, such as pediatric applications, air detection, or moderate-to-high flow performance. Targeted clearances can open distinct customer segments and provide a clearer value proposition to clinicians who need validated performance for a defined population or workflow.
Market Evolution: Consolidation, Fragmentation, and Entry Dynamics
The market appears likely to evolve along parallel tracks. Incumbent positions are supported by installed bases, regulatory histories, and distribution reach, which creates some resilience at the top of the market. At the same time, the breadth of clinical needs and the importance of specialized features prevent full commoditization. New entrants and smaller specialists can gain traction by solving concrete workflow problems, particularly where portability, air-in-line safety, and flow versatility matter most. M&A or partnership activity may increase as larger players seek to fill capability gaps in portability, digital integration, or specific clinical indications. For investors and strategic planners, the key question is not whether the market is consolidating in a simple sense, but where value is being created: in scale, in engineering specificity, or in the operational compatibility of the device with real clinical environments.
Forward-Looking Trends and Associated Opportunities
Looking across the current data and recent developments, three trends are likely to shape the next three to five years.
Infant Radiant Warmer Market
Trend 1: Performance Standardization Will Raise the Entry Bar
Air detection, flow adaptability, temperature consistency, and labeling clarity are becoming more central to purchasing decisions. As these capabilities become expected rather than exceptional, the practical barriers to entry rise. Devices that cannot demonstrate reliable performance across stated flow ranges, or that carry unresolved labeling or specification issues, face heightened scrutiny. The commercial opportunity lies in building compelling, verifiable performance narratives that reduce adoption risk for hospital teams and procurement groups. Manufacturers that treat compliance and performance documentation as part of the product story, not a back-office task, will likely see faster evaluation cycles and stronger trust from clinical buyers.
Trend 2: Portable, Multi-Scenario Warming Will Expand Beyond Traditional Settings
Demand is broadening into emergency, trauma, newborn, and acute care workflows where rapid deployment and flexibility matter. This creates opportunities for systems that can serve more than one clinical scenario without sacrificing safety or usability. Battery operation, compact form factors, and compatibility with varied infusion setups are likely to become increasingly important in procurement evaluations. Companies that design for these scenarios with clinically credible performance and clear practical advantages can capture share in segments where conventional warming solutions are less convenient. The risk is that portability claims outpace real-world reliability, so field validation and service support will be decisive.
Trend 3: Reimbursement and Guideline Alignment Will Influence Adoption Speed
Changes in coding status and payment mechanics, alongside stronger guideline emphasis on active warming, are likely to affect how quickly facilities adopt or expand warming programs. While these factors do not determine clinical value, they influence purchasing timelines, budget justification, and the administrative burden of adopting new devices. Commercial strategies that account for reimbursement pathways and guideline alignment can reduce friction and improve forecasting accuracy. At the same time, uncertainty remains because payment policy and institutional procurement behavior can shift, and any delay in reimbursement clarity can slow adoption even when clinical interest is strong.
Across these trends, the most durable commercial opportunities belong to organizations that can connect technical performance with operational fit. That means designing for the realities of busy clinical environments, providing evidence and documentation that support procurement decisions, and preparing for a market where safety, portability, and workflow compatibility are evaluated together rather than in isolation.
Strategic Actions for Decision Makers
Different audiences will extract value from the market in different ways. The following actions are most relevant for manufacturers, investors, and procurement or clinical leadership teams.
PW Consulting
For Manufacturers and Product Strategy Teams
- Prioritize verifiable differentiation. Build product narratives around flow range, air detection, portability, and material and labeling integrity, backed by clear documentation that procurement and clinical teams can evaluate quickly.
- Design for multi-scenario use where possible. Devices that can serve both higher-flow and lower-flow needs, or that fit emergency and inpatient contexts alike, reduce the need for multiple product acquisitions and simplify training.
- Treat regulatory and reimbursement readiness as commercial infrastructure. Maintain robust post-market processes, clear labeling, and an understanding of payment and coding developments so that market access is not delayed by avoidable administrative friction.
For Investors and Corporate Development Teams
- Focus on adoption readiness rather than headline growth alone. Assess whether a company’s technology fits real workflows, whether it has credible safety and compliance posture, and whether its distribution and service model can sustain repeat business.
- Watch for capability gaps that larger portfolios may want to fill. Solutions with strong portability, specialized flow performance, or validated pediatric or emergency use cases may attract interest from broader healthcare portfolios seeking to strengthen temperature management offerings.
- Factor reimbursement and guideline dynamics into valuation assumptions. Adoption speed can be influenced by coding status, payment updates, and institutional procurement cycles, so these elements should be part of scenario planning.
For Procurement, Clinical, and Hospital Leadership
- Evaluate total operational fit, not just warming capability. Consider setup time, staff training burden, compatibility with existing infusion workflows, service reliability, and how well the device supports both routine and high-acuity scenarios.
- Align device selection with guideline expectations and internal safety protocols. Preference for solutions that support active temperature management and address known risks such as air-in-line concerns can simplify internal justification and reduce clinical risk.
- Use evidence and post-market documentation as part of the evaluation process. Clear specifications, reliable labeling, and transparent performance claims help reduce uncertainty and support consistent adoption across departments.
The blood and fluid warmer market is moving toward a more disciplined, performance-driven phase in which growth is real but increasingly dependent on compliance readiness, workflow fit, and credible differentiation. For leaders evaluating entry, expansion, or procurement decisions, the most valuable intelligence is the kind that connects market size and trend direction to the specific operational realities of each purchase environment. Detailed segmentation data, company-level profiles, regulatory timelines, reimbursement mechanics, and region- and application-specific demand patterns can sharpen those decisions significantly. For teams that need that level of granularity, the full research report provides deeper breakdowns and tailored guidance to support planning with more precision.
For detailed analysis of this topic, please visit the official page: Blood and Fluid Warmer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the HFC Refrigerant Market
The hydrofluorocarbon (HFC) refrigerant market is entering a period of complex transformation, driven by tightening regulatory frameworks, evolving technological standards, and shifts in global demand patterns. As of 2025, the market operates with a revenue baseline of approximately USD 5.65 billion, having grown from around USD 3.8 billion in 2020 at a compound annual growth rate of 6.25 percent through the forecast horizon extending to 2032. This trajectory reflects a sector that continues to expand in absolute terms, even as it faces structural pressures that will reshape how refrigerants are produced, allocated, and consumed. The market is not shrinking; it is recalibrating. Understanding the mechanics of that recalibration is essential for executives, investors, and procurement leaders who must align their operations with the next phase of industry evolution.
PW Consulting
The concentration of market activity among a small group of established players underscores the capital-intensive and technically specialized nature of refrigerant production. The top three participants command roughly 78.5 percent of market revenue, while the top five collectively account for approximately 95 percent. This level of concentration suggests that access to compliant production capacity, regulatory expertise, and established distribution channels remains a significant barrier. It also indicates that pricing power, product diversification, and strategic partnerships will likely play an outsized role in determining which organizations can sustain growth as the regulatory landscape tightens and raw material dynamics fluctuate.
Market Sizing and Trajectory Context
From a macroeconomic perspective, the HFC refrigerant market has demonstrated consistent expansion over the past half-decade, with revenue moving from 3.8 billion in 2020 to 5.65 billion in 2025. Projections for the coming years indicate continued growth, with revenue expected to reach 6.26 billion in 2026, 6.55 billion in 2027, and 6.76 billion in 2028. The trajectory accelerates modestly through the end of the decade, reaching 7.23 billion in 2029, 7.57 billion in 2030, 7.95 billion in 2031, and 8.45 billion in 2032. A 6.25 percent compound annual growth rate across the 2026 to 2032 forecast period signals that demand will remain resilient, particularly in cooling-intensive applications, even as regulatory mechanisms systematically reduce the availability of high-global-warming-potential compounds.
Worldwide Freon Refrigerant Market
This growth pattern should not be interpreted as a simple continuation of past trends. The composition of demand is shifting, the cost structure of production is becoming more volatile, and regulatory compliance is adding new layers of operational complexity. Organizations that treat the market as a static volume play risk misallocating capital and missing the strategic inflection points that will define competitive positioning over the next several years.
Core Challenges and Inflection Points
Three structural challenges are converging to create a pivotal moment for the HFC refrigerant sector. The first is the regulatory mandate to reduce production and consumption of high-GWP HFCs. Under the AIM Act framework, an 85 percent reduction in production and consumption is required by 2036, with application-specific allowances renewed through 2030 and reporting requirements for 2025 data due by March 31, 2026. This phasedown schedule forces manufacturers, equipment builders, and end users to plan around a shrinking pool of conventional refrigerants, while simultaneously managing transition timelines for alternative formulations.
The second challenge lies in the tightening of operational compliance at the equipment level. Effective January 1, 2026, EPA Subsection H rules require leak inspection and repair protocols for HFC systems containing 15 pounds or more of refrigerant, with GWP limits of 300 for systems over 200 pounds. The EPA HFC Leak Repair and Management Rule (Subsection H) came into effect in January 2026, imposing leak detection and repair requirements on HFC-containing appliances meeting the threshold. This rule changes the economics of refrigerant use by increasing maintenance obligations, raising the cost of compliance, and making leak prevention a material factor in total cost of ownership.
The third challenge is the volatility and upward pressure in raw material costs. Chinese hydrofluoric acid prices rose with an annual average increase of 12.52 percent in 2025, supported by stable costs and peak-season refrigerant demand. HFC refrigerant spot market prices remained firm at elevated levels in April 2026 amid subdued trading activity. These cost dynamics compress margins for producers and increase procurement risk for buyers, particularly when combined with supply chain strains that have already triggered significant price adjustments in specific product lines. A notable example occurred in April 2025, when a leading manufacturer announced a 42 percent price increase on R-454B refrigerant cylinders due to supply chain strains and regulatory transitions. This type of pricing movement illustrates how regulatory transition pressure and logistics constraints can combine to create abrupt cost shocks for end users.
Key Drivers of Market Change
The trajectory of the HFC refrigerant market is being shaped by a tightly interconnected set of drivers that span technology, regulation, demand behavior, and supply chain economics. Understanding these drivers in isolation is insufficient; their interaction is what determines where value will be created and where risk will accumulate.
Technological Innovation and Formulation Shifts
The push toward lower-GWP formulations has accelerated the development and commercialization of refrigerant blends and alternative chemistries that can operate within existing or slightly modified equipment architectures. Manufacturers are increasingly focused on HFC-32 blends, R-454B, and other intermediate-GWP options that offer a pragmatic balance between performance, safety, and regulatory compliance. One recent example of this dynamic is the May 2025 commercial arrangement between Arkema and Honeywell, which strengthened Arkema’s range of lower-GWP refrigerants through expanded access to HFO blends for HVACR applications while supporting the HFC phasedown. This type of portfolio expansion allows equipment manufacturers and service providers to access compliant alternatives without waiting for entirely new production ecosystems to mature.
From a strategic standpoint, the innovation frontier is not solely about replacing one molecule with another. It is about building product portfolios that can adapt to regional regulatory variation, application-specific performance requirements, and evolving safety classifications. Companies that can offer a graduated pathway—from current HFCs to lower-GWP blends and ultimately to next-generation alternatives—will be better positioned to retain customer relationships across multiple transition cycles.
Policy and Regulatory Environment
Regulatory pressure is the single most consequential driver in the current market cycle. The combination of an 85 percent phasedown target by 2036, application-specific allowance renewals through 2030, and the new leak detection and repair obligations creates a multi-layered compliance environment. The EPA’s proposed rule to address stranded high-GWP HFC inventory extends compliance deadlines, with effects on food retail refrigeration equipment use extended to 2032. This extension provides temporary relief for certain end-use sectors, but it also prolongs the coexistence of legacy and transitional refrigerants, complicating procurement planning and inventory management.
For industry participants, regulation is no longer a distant compliance issue. It is an active determinant of pricing, availability, and product design. Reporting obligations for 2025 data due by March 31, 2026 add a transparency layer that increases visibility into production and consumption patterns, which in turn can influence allowance allocation and market expectations. Organizations that integrate regulatory tracking into their strategic planning will be better equipped to anticipate allowance constraints, adjust product roadmaps, and avoid reactive procurement decisions.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand for cooling and refrigeration continues to grow, driven by rising ambient temperatures, expanded cold-chain requirements, and the electrification of heating and cooling in both residential and commercial segments. Air conditioning remains the largest application category, followed by refrigeration and a smaller share of other applications. This demand base provides a structural floor for refrigerant consumption, even as the mix of refrigerants used shifts toward lower-GWP options.
At the same time, end users are becoming more sensitive to total cost of ownership, including maintenance, leak management, and regulatory compliance. The new leak inspection and repair protocols for systems with 15 pounds or more of refrigerant make it more expensive to operate high-GWP systems without rigorous maintenance discipline. As a result, equipment buyers and facility operators are increasingly weighing refrigerant choice against serviceability, downtime risk, and long-term compliance exposure. This behavioral shift favors suppliers and equipment manufacturers that can demonstrate reliable performance, clear compliance pathways, and lower-risk operating profiles.
Supply Chain and Cost Structure Dynamics
Cost pressures are being amplified by raw material movements and logistics constraints. The 12.52 percent annual average increase in Chinese hydrofluoric acid prices in 2025 reflects a broader environment where key inputs are subject to seasonal demand spikes and cost stability on the upstream side, while downstream demand remains strong. At the same time, HFC refrigerant spot market prices held firm at elevated levels in April 2026 despite subdued trading activity, indicating that pricing is being supported by structural factors rather than short-term speculation.
Supply chain strains have also manifested in sharp price increases for specific transitional refrigerants. The 42 percent price increase on R-454B cylinders announced in April 2025 highlights how regulatory transition demand, combined with constrained supply and logistics friction, can produce rapid cost escalation. For procurement teams, this underscores the importance of forward visibility into allowance allocations, production capacity, and regional price dynamics. For producers, it reinforces the value of diversified feedstock strategies, flexible manufacturing footprints, and stronger customer contracting approaches that can buffer against short-term volatility.
Competitive Landscape and Leading Strategies
The HFC refrigerant market is dominated by a concentrated group of global chemical and industrial companies, complemented by a set of equipment-focused and specialty producers that play important roles in specific channels. The strategic positioning of these players reveals a landscape where portfolio breadth, regulatory agility, and partnership networks are becoming as important as raw production capacity.
Worldwide Refrigerant Cylinder Market
Strategic Positioning of Core Players
Honeywell International Inc., based in Charlotte, North Carolina, is a leading producer of HFC refrigerants through its Solstice line and HFC-32 blends for HVAC and refrigeration systems. Its strategic emphasis on lower-GWP formulations and blend technology positions it as a bridge supplier during the transition from legacy HFCs to next-generation options. The company’s April 2025 price adjustment on R-454B cylinders reflects both the realities of supply chain strain and the pricing leverage that can emerge when compliant transitional products are in high demand.
The Chemours Company, headquartered in Wilmington, Delaware, is a major supplier of HFC refrigerants under its Freon and Opteon brands, with a clear focus on R-410A alternatives and blends. Chemours’ brand heritage and broad distribution relationships give it significant visibility across multiple end markets, while its blend-oriented portfolio supports customers seeking compliance pathways that can be implemented with relatively modest equipment modifications.
Arkema S.A., based in Colombes, France, provides HFC-32 and low-GWP HFC refrigerants for commercial and industrial refrigeration applications. Its May 2025 commercial arrangement with Honeywell demonstrates a strategy of expanding access to HFO blends and lower-GWP options without requiring full vertical integration of every technology pathway. This partnership model allows Arkema to widen its offering while participating in the broader phasedown trajectory.
Daikin Industries Ltd., headquartered in Osaka, Japan, is both a manufacturer and supplier of HFC refrigerants, including R-32 and R-454B for air conditioning and heat pump systems. Daikin’s vertical integration across equipment and refrigerant supply gives it a distinctive ability to align refrigerant development with system design, which can reduce transition friction for customers and create a more controlled path to compliance.
Carrier Corporation, based in Palm Beach Gardens, Florida, produces and distributes HFC refrigerants and refrigerant-containing HVAC equipment systems. Its equipment-centric orientation means that refrigerant strategy is tightly linked to product roadmaps, service networks, and customer migration plans. Trane Technologies plc, located in Davidson, North Carolina, supplies HFC refrigerants for commercial refrigeration and HVAC systems, with a similar emphasis on application-specific solutions and service compatibility.
Iofina Chemical, based in Maryland, remains an active producer of HFC refrigerants under EPA production for export allowances, reflecting the continued importance of trade dynamics and regulatory allowances in shaping global supply. Linde plc, headquartered in Wicklow, Ireland, supplies HFC refrigerants and related industrial gases for refrigeration and HVAC applications, leveraging its broader industrial gas infrastructure to support integrated supply and logistics across multiple end-use channels.
Market Structure Evolution
The market is likely to continue evolving along three tracks. First, consolidation pressure will persist among producers with undifferentiated assets or limited access to compliant portfolios, while companies with strong blend technology, regulatory expertise, and global distribution will be better positioned to capture share. Second, differentiation will increasingly center on transition readiness: the ability to supply intermediate-GWP blends, support leak management compliance, and provide application-specific guidance will become more valuable than commodity volume alone. Third, new entry will remain challenging due to concentration, capital intensity, and regulatory complexity, but selective partnerships, licensing arrangements, and regional niche plays can still create meaningful footholds.
In this environment, competitive advantage will depend less on asserting scale for its own sake and more on demonstrating the ability to navigate phasedown schedules, manage input cost volatility, and deliver reliable compliance pathways. The companies that can combine product flexibility with regulatory foresight and supply chain resilience will be the ones that shape the next phase of market development.
Future Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to define the market’s evolution and create distinct commercial opportunities for organizations that respond proactively.
Trend 1: Accelerated Migration to Intermediate and Lower-GWP Blends
The combination of phasedown targets, allowance constraints, and leak management requirements will drive a faster shift toward intermediate-GWP blends and lower-GWP alternatives in both air conditioning and refrigeration. This migration will create opportunities for suppliers that can offer clear formulation pathways, consistent quality, and application-specific support. It will also create opportunities for equipment manufacturers that align product lines with compliant refrigerants and simplify the transition for end users. The commercial value here lies in reducing transition risk: customers will pay a premium for clarity, reliability, and a credible path through the regulatory timeline.
Trend 2: Compliance-Driven Service and Lifecycle Value
The EPA Subsection H leak detection and repair requirements, together with GWP limits for larger systems, will make maintenance and leak prevention central to the economics of refrigerant use. This shifts the competitive focus from initial product price to lifecycle performance, service quality, and compliance assurance. Providers that integrate refrigerant supply with leak management guidance, inspection protocols, and repair support can capture additional value while helping customers avoid regulatory exposure. Over time, this may lead to more bundled offerings that combine refrigerant, equipment, and service components into a single compliance-oriented solution.
Trend 3: Regional Divergence and Strategic Sourcing
Regulatory timelines, allowance structures, and raw material dynamics will not move uniformly across regions. Asia Pacific is expected to continue representing a substantial share of market revenue, while North America and Europe will be shaped by their own phasedown schedules and compliance frameworks. Latin America and the Middle East and Africa will remain smaller but potentially fast-moving in specific application segments. This regional divergence will reward organizations that can tailor sourcing, product mix, and compliance strategy to local conditions rather than applying a single global template. Strategic sourcing relationships, allowance-aware procurement, and region-specific product planning will become important differentiators.
Risks and Uncertainties
Several uncertainties could alter this trajectory. If regulatory timelines are adjusted further, or if allowance allocation mechanisms create unexpected shortages, price volatility could intensify and disrupt procurement plans. If raw material costs continue to rise, margins may be squeezed and end-user adoption of transitional products could slow in price-sensitive segments. If leak management compliance proves more costly or operationally complex than anticipated, some customers may delay transitions or seek alternative solutions that reduce exposure. Finally, the coexistence of legacy, transitional, and next-generation refrigerants could create fragmentation in service practices and supply chains, increasing complexity for multi-site operators and distributors.
Strategic Recommendations for Decision Makers
For manufacturers, the priority should be to build transition-ready portfolios that span current HFCs, intermediate blends, and lower-GWP options, while investing in regulatory tracking and compliance support capabilities. Product roadmaps should be aligned not just with technology development but with phasedown schedules, application-specific rules, and leak management obligations. Supply chain resilience should be strengthened through feedstock diversification, flexible production planning, and forward visibility into allowance and export dynamics.
For investors, the market offers exposure to a sector that is growing in absolute terms but undergoing significant structural change. The most compelling opportunities are likely to be found in companies with differentiated blend technology, strong compliance orientation, and the ability to serve high-value applications with lower transition risk. Due diligence should focus on regulatory exposure, allowance dependency, raw material sensitivity, and the strength of customer relationships in segments where compliance and service quality matter most.
For procurement and supply chain leaders, the most important action is to move from reactive purchasing to forward-looking planning. This means mapping refrigerant needs against phasedown timelines, understanding leak management obligations for relevant systems, and building sourcing strategies that account for regional price divergence and supply constraints. Long-term agreements, diversified supplier bases, and early engagement with compliance requirements can reduce exposure to sudden price shocks and availability gaps.
As the HFC refrigerant market continues to evolve, the organizations that succeed will be those that treat regulatory change, cost dynamics, and technology transition as interconnected strategic variables rather than isolated operational issues. For decision makers seeking a more granular view of segmentation dynamics, regional variations, and customized scenario planning, the full research report provides deeper data and tailored analysis to support implementation.
For detailed analysis of this topic, please visit the official page: HFC Refrigerant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PMSM Market to Hit $28.81B by 2032: Why 7.7% CAGR Signals a Strategic Shift
By pmarketresearch, 2026-09-21
The PMSM Market at a Strategic Inflection Point: Trends, Challenges, and Where Value Is Created
The global landscape for Permanent Magnet Synchronous Motors (PMSM) has shifted from a niche technology segment to a foundational power transmission architecture across multiple industries. Over the 2020–2025 cycle, the market expanded from approximately $12.5 billion to $17.18 billion, reflecting a steady compound annual growth trajectory that analysts project to continue through 2032. At a 7.7 percent CAGR, the segment is expected to reach roughly $28.81 billion by the end of the forecast period, signaling a structural expansion rather than a temporary cyclical surge. This growth is not distributed uniformly across regions, motor configurations, or end-use sectors, and that unevenness is where competitive advantage is being forged. Executives evaluating capacity allocation, portfolio strategy, or capital deployment should recognize that the PMSM market is entering a phase where efficiency mandates, raw material dynamics, and application-specific performance requirements are converging to reshape demand patterns.
Dc Permanent Magnet Motor Market
Market Scale, Concentration, and the Shape of the Opportunity
The headline figures point to a market that has more than doubled its baseline in just over a decade, but the strategic story lies in the composition of that growth. Asia Pacific continues to anchor the largest share of revenue, reflecting the concentration of manufacturing capacity, electrification investment, and industrial modernization in the region. North America and Europe follow, each drawing strength from distinct demand engines: North America benefits from industrial automation modernization and a rapidly scaling electric mobility ecosystem, while Europe's growth is tightly coupled to energy efficiency directives and advanced manufacturing reshoring. Latin America and the Middle East and Africa represent smaller but strategically relevant footprints, often tied to infrastructure modernization, emerging industrial bases, and selective mobility programs. Across motor types, interior permanent magnet designs command the largest revenue share, a reflection of their dominance in applications demanding high power density, precise control, and compact packaging. Surface-mounted variants and other specialized configurations maintain meaningful positions in segments where thermal management, cost structure, or manufacturability favor alternative layouts. In terms of applications, electric vehicles represent the most visible growth vector, but industrial automation, robotics, conveyors, compressors, and precision motion control systems collectively account for a substantial and steadier portion of demand. The market is moderately concentrated, with the top three players capturing roughly 45 percent of revenue and the top five approaching 60 percent, a structure that suggests scale advantages, technology portfolios, and service ecosystems matter, but there remains meaningful space for differentiated specialists and regional champions.
Key Challenges and Strategic Inflection Points
Three challenges define the current operating environment for PMSM suppliers and downstream buyers. First, the economics of rare earth permanent magnets create a persistent cost and supply risk. Neodymium-iron-boron (NdFeB) magnets constitute over 90 percent of material costs in production for many PMSM designs, and the manufacturing capacity for sintered NdFeB magnets is heavily concentrated in a single geography. This concentration introduces exposure to export controls, pricing volatility, and logistics disruptions, making magnet sourcing a strategic variable rather than a routine procurement activity. Second, the market is navigating a mismatch between standardized motor offerings and the growing demand for application-specific optimization. As vehicles, industrial equipment, and precision machinery demand higher efficiency at partial loads, faster dynamic response, and tighter integration with power electronics and control software, generic motor configurations are losing relevance in premium segments. Third, the industry is facing a regulatory and standards environment that is accelerating adoption but also raising the bar for validation, lifecycle efficiency, and traceability. Energy and resource-saving PMSM and synchronous reluctance motor systems are entering commercial mass production, and efficiency mandates across industrial and automotive applications are reinforcing the shift toward high-performance synchronous architectures. The inflection point is clear: the companies that can decouple performance from raw material intensity, align product roadmaps with regulatory trajectories, and deliver integrated solutions rather than isolated motor units will capture disproportionate value.
Key Drivers Reshaping the PMSM Market
Technology Innovation and the Push for Higher Efficiency at Lower Material Intensity
Innovation in PMSM design is increasingly focused on achieving competitive power density and efficiency without proportionally increasing rare earth content. Advances in rotor topology, magnetization patterns, thermal management, and winding architecture are enabling manufacturers to optimize torque ripple, reduce losses at partial load, and improve controllability. These improvements matter because many real-world applications do not operate at peak load; they cycle through variable speeds, frequent starts and stops, and partial-load conditions where efficiency and responsiveness determine total cost of ownership. At the same time, the integration of motors with inverters, sensors, and control firmware is becoming a differentiator. A motor that performs well in isolation may underdeliver in a system where torque control, thermal limits, and communication latency intersect. As a result, engineering leadership is shifting from component-level specifications to system-level performance, and suppliers that can co-design motors with power electronics and control strategies are gaining an edge in high-value applications. The recent push toward energy- and resource-saving PMSM and synchronous reluctance motor systems entering commercial mass production illustrates this direction: performance is being redesigned to align with both efficiency mandates and material constraints.
Policy and Regulatory Tailwinds Reinforcing Adoption Across Sectors
Regulation is acting as both a demand catalyst and a design constraint. In industrial contexts, efficiency standards and corporate sustainability targets are driving retrofits and new equipment purchases toward motor systems that reduce energy consumption across duty cycles. In mobility, electrification mandates and emissions frameworks are accelerating the replacement of legacy drivetrain architectures with permanent magnet synchronous solutions that offer precise torque control and compact packaging. Compliance is no longer a checkpoint at the end of development; it is increasingly embedded in product architecture decisions, from material selection to thermal design to lifecycle documentation. This regulatory environment rewards companies that can demonstrate measurable efficiency gains, maintain consistent quality across batches, and provide evidence of performance under real operating conditions. It also raises the stakes for suppliers that rely on fragmented design approaches or inconsistent validation, because the cost of non-compliance or underperformance is rising across both industrial and automotive pipelines.
PW Consulting
Demand-Side Shifts in Mobility and Industrial Automation
On the demand side, two broad behavioral shifts are reshaping the market. Electric vehicle platforms are moving from early adoption to mainstream scaling, but the motor requirements within that segment are diversifying. Different vehicle classes, duty profiles, and packaging constraints are creating a need for motors that balance power density, cost, thermal robustness, and manufacturability. Meanwhile, industrial buyers are prioritizing automation that reduces labor dependency, improves throughput consistency, and supports energy-conscious operation. Robotics, precision motion control, conveyors, compressors, and machine tools are all seeing renewed investment in motor systems that can deliver accurate positioning, rapid acceleration, and efficient operation across variable loads. The common thread is a preference for motors that are not only efficient at peak performance but also dependable and controllable in dynamic operating conditions. This is shifting purchasing criteria from price-per-unit toward total system value, including integration ease, lifecycle serviceability, and compatibility with control and automation architectures.
Supply Chain Realities and Cost Structure Pressures
The cost structure of PMSM production is increasingly defined by magnet availability, processing capacity, and the ability to manage volatility without eroding margins. Because rare earth magnets account for such a large share of material cost, procurement strategy has become a core competitive lever. Suppliers are exploring multiple routes to resilience: diversifying magnet sources where possible, designing for reduced rare earth intensity, improving recycling and recovery pathways, and standardizing components to reduce variability. At the same time, manufacturing footprint decisions are being influenced by the location of downstream demand, the cost of energy and labor, and the need to be close to customers for customization and service. The practical effect is that scale alone is no longer the sole determinant of advantage. Companies that can combine disciplined material management with flexible manufacturing and strong supplier relationships are better positioned to protect margins through cycles of demand growth and input volatility.
Competition Landscape: Positioning, Differentiation, and the Evolution of Advantage
How Leading Players Are Building Defensible Positions
The competitive field in the PMSM market includes established industrial conglomerates, specialized motion control manufacturers, automotive-adjacent suppliers, and regional players with strong local execution. A defining feature of the leaders is the breadth of their portfolios paired with the depth of their application expertise. Large multinational suppliers typically compete by offering integrated solutions that span motors, drives, control software, and service support, which reduces integration risk for customers and creates switching costs that protect recurring revenue. Their advantage often lies in the ability to standardize core motor architectures while tailoring performance through control strategies, packaging, and optional features. This approach allows them to serve multiple verticals without fragmenting their engineering base too thinly.
Specialized and regional players compete in a different way. Rather than pursuing breadth, they focus on specific performance niches, hygiene-sensitive environments, compact applications, or regional service requirements where responsiveness and customization matter more than scale. Their differentiation often comes from mastering a narrow set of requirements exceptionally well, whether that is high-precision motion, harsh-environment reliability, cost-efficient manufacturability for a particular motor form factor, or close collaboration with local system integrators. The recent product activity in the sector reflects these divergent strategies. For example, Yaskawa Electric Corporation launched the MOTOMAN-HD7 and HD8 servo systems designed for hygienic environments, an indication that application-specific robustness and compliance with stringent cleanliness requirements are becoming valued differentiators in selected industrial and life sciences contexts. In mobility, Nidec Corporation signaled its intent to unveil next-generation mobility technologies, including advanced motors, at a major industry exhibition, reinforcing the continued focus on drivetrain performance, packaging, and integration as competitive battlegrounds. Mitsubishi Electric Corporation also received recognition for its railcar motor system, an example of how synchronous motor solutions are being validated in demanding transportation applications where reliability, efficiency, and lifecycle performance are closely scrutinized.
Strategic Positioning and the Role of Integration
The most resilient positions in this market are built on integration and system-level value creation. Suppliers that can deliver not only a motor but also the accompanying control logic, thermal strategy, and service model reduce the complexity burden for end users and increase the likelihood that their products become embedded in long-lived deployments. This is especially relevant in industrial automation, where downtime costs and retrofit complexity influence purchasing decisions, and in mobility, where packaging constraints and performance consistency shape platform choices. In contrast, companies that compete primarily on component price without differentiation in control, reliability, or service face greater exposure to margin pressure and substitution risk. As efficiency mandates tighten and application demands become more specific, the premium on integration capability is likely to increase, favoring players that can orchestrate the interaction between motor, drive, and control layers.
Consolidation, Fragmentation, and the Role of New Entrants
The market's moderate concentration suggests room for both consolidation and fragmentation depending on the segment. In high-volume, standardized applications, scale advantages in manufacturing, procurement, and distribution can drive consolidation, as larger players capture efficiencies and downstream customers prefer fewer, more capable suppliers. In specialized segments, fragmentation can persist or even intensify, because the value lies in solving distinct technical challenges rather than in pure volume. New entrants are most likely to succeed when they address a clearly defined performance gap, such as lower rare earth dependence, improved thermal behavior in a specific duty cycle, or a control architecture that simplifies integration for a particular customer segment. The strategic implication is that market share movements will not be uniform. Growth will be redistributed toward firms that align their capabilities with the most valuable application requirements, while undifferentiated offerings face increasing pressure from both incumbents and targeted newcomers.
Forward Outlook: Trends to Watch and Where the Opportunities Lie
Trend 1: Efficiency as a System Property, Not Just a Motor Specification
Over the next three to five years, PMSM value will increasingly be defined by system-level efficiency across real operating profiles rather than peak-rated performance alone. Buyers in industrial and mobility applications will continue to prioritize motors that maintain strong efficiency at partial loads, respond quickly to control inputs, and integrate cleanly with power electronics and automation software. This trend creates opportunities for suppliers that can offer configurable performance, application-tuned control strategies, and documentation that supports compliance and lifecycle planning. It also raises the importance of validation under representative conditions, because efficiency claims that look strong on paper but underperform in the field will erode trust and purchasing preference.
Trend 2: Material Strategy Becomes a Competitive Capability
The rare earth dependency embedded in many PMSM designs will keep material strategy in the foreground. Companies that can reduce magnet intensity without sacrificing critical performance attributes, manage supply relationships intelligently, and explore recovery or substitution pathways where technically and economically feasible will gain resilience. This is not solely a cost issue; it is also a risk management and continuity issue. In periods of pricing volatility or policy change, the ability to maintain consistent output and margin can distinguish winners from laggards. Opportunities here include design optimization that preserves torque and efficiency with smarter magnet placement, improved recycling loops, and procurement models that reduce exposure to single-source bottlenecks.
Trend 3: Application-Specific Solutions Gain Premium Positioning
As the market matures, the most attractive margins are likely to shift toward applications where motors must meet specialized requirements. Hygiene-sensitive industrial environments, high-precision motion control, demanding transportation duty cycles, and compact mobility architectures are all examples where tailored engineering can command premium positioning. The commercial launch of servo systems designed for hygienic environments and continued activity in mobility technology exhibitions point to this direction. Suppliers that invest in understanding the operating context, regulatory constraints, and lifecycle needs of specific segments can build defensible niches, while those that rely on broad, undifferentiated portfolios may find themselves competing primarily on price in more commoditized parts of the market.
Portable Permanent Magnet Pump Market
Risks and Uncertainties to Monitor
Several uncertainties could shape the trajectory of the market. Input availability and pricing for rare earth materials remain volatile, and any disruption can affect cost structures and time-to-market for new designs. Regulatory timelines and efficiency standards may accelerate adoption in some regions while creating compliance complexity in others, especially where validation requirements differ across jurisdictions. Competitive intensity may increase as incumbents deepen integration capabilities and new entrants target specific niches, which could pressure margins in segments that fail to differentiate. Finally, demand growth in electric vehicles and industrial automation is subject to broader macroeconomic conditions, investment cycles, and the pace of electrification adoption in different geographies. Executives should treat these variables as integral to planning rather than peripheral risks, because they affect sourcing, product roadmaps, and the timing of capacity decisions.
Actionable Implications for Decision-Makers
For Manufacturers and Product Leaders
Align engineering roadmaps with system-level value rather than motor-only specifications. Prioritize designs that perform well across variable duty cycles, integrate readily with control and power electronics, and offer flexibility for application-specific customization. Strengthen material strategy by evaluating magnet intensity, sourcing diversification, and recovery pathways as core design parameters. Where possible, build modular architectures that allow performance to be tuned through control and packaging instead of relying solely on changes in magnet content. This approach can improve resilience while preserving the ability to serve both standardized and specialized segments.
For Investors and Capital Allocators
Focus on companies that demonstrate a credible path to combining efficiency, integration, and material resilience. Scale matters, but in this market it is most valuable when paired with application expertise and the ability to deliver total system performance. Differentiated niches in hygiene-sensitive environments, precision motion, mobility packaging constraints, and other high-specification applications can offer stronger margin potential than undifferentiated volume plays. Pay attention to how suppliers manage rare earth exposure and whether they have clear strategies for continuity, cost control, and product evolution. The winners are likely to be those that can convert technical capability into embedded, long-lived deployments.
For Procurement and Operations Leaders
Shift evaluation criteria toward total cost of ownership, integration effort, and lifecycle reliability. A lower upfront price can be offset by higher integration cost, poorer partial-load efficiency, or greater service complexity. Where critical applications are concerned, prioritize suppliers that can provide consistent validation, predictable service support, and clear documentation of performance under representative conditions. Diversify sourcing where feasible to reduce exposure to single-point material or manufacturing risks, and consider long-term collaboration with suppliers that demonstrate a strong plan for managing magnet-related volatility. Procurement decisions made with system value in mind tend to reduce downstream risk and improve operational predictability.
The strategic picture for the PMSM market is one of durable growth shaped by efficiency mandates, material constraints, and application diversification. The companies that will capture the most value are those that treat the motor as part of a broader system, build resilience into material and supply decisions, and tailor performance to the real operating conditions their customers face. For decision-makers looking to move from high-level trends to segment-level detail, the full research report provides a deeper breakdown of subsegments, regional demand patterns, competitive positioning, and scenario-based implications that can inform capacity, sourcing, and portfolio choices.
For detailed analysis of this topic, please visit the official page: Permanent Magnet Synchronous Motor (PMSM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Laminated Tubes Market Beyond the 6.5% CAGR: Key Drivers Shaping 2032 Growth
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Laminated Tubes Market
The global laminated tubes market has demonstrated steady, compounding growth over the past five years, with revenue expanding from $1,345.0 million in 2020 to $1,810.0 million in 2025. Forward projections indicate this trajectory will continue through the forecast period of 2026-2032, reaching $2,800.0 million by the end of the decade. The implied compound annual growth rate of 6.5% reflects more than baseline demographic expansion; it signals a structural transition where laminated tubes are increasingly evaluated not merely as dispensing packages, but as functional components within product performance, regulatory compliance, and sustainability narratives.
Leadership teams across personal care, oral care, pharmaceuticals, and food and beverage sectors are navigating a landscape where packaging decisions directly influence formulation integrity, brand positioning, and supply chain risk exposure. The market's expansion is not uniform. It is concentrated around innovation cycles, regulatory inflection points, and geographic rebalancing that reward manufacturers and brand owners who align capacity investments with material science breakthroughs. Understanding where growth concentrates, what constraints will harden, and which competitive moves are gaining traction is essential for strategic planning in the near to medium term.
Market Landscape and Emerging Pressure Points
The laminated tubes market operates with moderate concentration, where the top three players capture approximately 26.8% of revenue and the top five reach about 32.6%. This structure indicates a competitive environment with a stable core of established manufacturers and sufficient space for regional specialists and technology-driven entrants to differentiate. Growth has been consistent year over year, with 2024 revenue reaching $1,701.4 million and 2025 closing at $1,810.0 million. The momentum continues into 2026 at $1,955.44 million, reflecting sustained demand across core application categories and incremental gains from higher-value barrier solutions.
Several structural tensions are defining the current phase of market development. First, the cost architecture of laminated tubes remains inherently higher than conventional single-material alternatives. Multilayer construction, specialty adhesives, and barrier films such as aluminum foil or engineered resins create a production cost premium typically 15-20% above standard polyethylene tubes. When resin prices experienced 30-40% spikes between 2021 and 2023 due to supply chain bottlenecks, the margin pressure on laminated tube manufacturers intensified, forcing a sharper focus on value engineering, procurement discipline, and pricing strategies that justify premium positioning through performance and compliance.
Second, regulatory momentum is reshaping design assumptions. Packaging legislation in major markets is moving from voluntary guidelines toward enforceable standards that link material composition, recyclability, and recycled content to market access. This shift places laminated tube manufacturers and brand owners under pressure to reconcile barrier performance with end-of-life compatibility, particularly in regions where existing recycling infrastructure is calibrated for simpler polymer streams.
Third, the market is encountering a capability gap between high-volume standard production and the growing demand for customized, high-resolution printed, and functionally specialized tubes. As brands seek packaging that supports premium positioning, tamper evidence, anti-counterfeiting, and differentiated dispensing experiences, manufacturers that can deliver consistent quality at scale while accommodating shorter runs and tailored specifications are gaining strategic relevance.
Drivers Reshaping Market Trajectory
Material Innovation and Barrier Performance
Technology advancement remains the most direct engine of market growth. Laminated tube value is increasingly derived from the ability to combine barrier protection, lightweighting, and recyclability in a single structure. High-barrier aluminum-based laminate tubes continue to command significant share because they protect oxygen-sensitive and moisture-sensitive formulations, but innovation is expanding the functional envelope of plastic barrier solutions as well. Recent product launches demonstrate that barrier performance is no longer treated as a fixed attribute; it is being re-engineered for compatibility with recycling streams while retaining the protective characteristics demanded by oral care, cosmetics, and pharmaceutical applications.
Examples include the introduction of recyclable high-barrier laminate tubes designed for oral care and cosmetics, the debut of mono-material recyclable barrier tubes with sensory and aesthetic differentiation, and the integration of anti-counterfeiting features directly into multilayer tube structures through holographic films. These developments matter commercially because they allow brand owners to defend formulation quality and consumer trust without defaulting to conventional aluminum structures that may face recyclability friction in certain jurisdictions. For manufacturers, the ability to offer differentiated barrier solutions is increasingly a revenue driver rather than a compliance checkbox.
Regulatory and Policy Dynamics
Policy environments are accelerating design transitions. In Europe, packaging regulation is moving toward enforceable recycled content thresholds and harmonized recyclability grading. Flexible packaging is subject to mandates requiring at least 35% recycled plastic content by 2030, which compels laminated tube producers and their customers to adapt structures for recyclability in existing polyethylene streams. Enforcement of single-use plastics requirements since mid-2024 has reinforced expectations around tethered closures and mono-material orientation, further accelerating the shift away from complex multi-layer laminates where recycling compatibility is limited.
Laminate Tube Packaging Market
By 2026, technical implementing acts are expected to impose harmonized recyclability grades, creating a more predictable but stricter evaluation framework. Manufacturers that rely on laminated films incompatible with existing recycling systems face increased redesign exposure, while those with mono-material or certified recyclable platforms gain a compliance advantage. This regulatory trajectory is not solely a European phenomenon; it influences global supply chains as multinational brand owners standardize packaging architectures across regions to reduce complexity and risk. The strategic implication is clear: regulatory readiness is becoming a market entry and retention factor, especially in premium personal care and pharmaceutical segments.
Demand-Side Evolution in Consumer and B2B Behavior
Consumer and enterprise demand is pulling laminated tube markets in two complementary directions. On the consumer side, expectations around sustainability, authenticity, and premium experience are influencing purchasing decisions in oral care and cosmetics. Tubes are no longer invisible carriers; they communicate brand values through finish, dispensing feel, and perceived environmental responsibility. On the B2B side, pharmaceutical and personal care manufacturers are seeking packaging that supports product integrity, regulatory documentation, and supply reliability. High-barrier laminated tubes serve these needs by protecting active ingredients, enabling stable shelf life, and providing a platform for controlled dispensing.
This dual demand pattern is expanding the commercial relevance of specialized tube formats. Oral care remains a particularly strong application category, benefiting from high usage frequency, brand loyalty, and format familiarity. Cosmetics and personal care continue to drive demand for customizable prints, premium tactile qualities, and functional closures. Pharmaceuticals and healthcare-related applications contribute steady demand where barrier protection and compliance documentation are critical. The underlying trend is that laminated tubes are being selected for a wider set of performance criteria, which raises the stakes for manufacturers that cannot deliver consistent quality, traceability, and specialized features.
Supply Chain Economics and Cost Structure Realignment
Cost dynamics are a persistent determinant of competitive positioning. Laminated tube economics are shaped by resin pricing, aluminum foil costs, adhesives, and multilayer processing complexity. The resin price volatility experienced during 2021-2023 illustrated how quickly input cost swings can compress margins, particularly for producers with limited ability to pass through costs or re-engineer structures for efficiency. As markets stabilize, the strategic focus is shifting toward cost resilience rather than short-term price hedging alone.
Capacity expansion is one response. Investments in automated production lines in key manufacturing hubs are increasing throughput and reducing per-unit labor intensity, which helps offset structural cost premiums. At the same time, manufacturers are pursuing lightweighting, material optimization, and hybrid technologies that preserve barrier performance while reducing overall material usage. These moves are not only about margin protection; they are increasingly tied to sustainability messaging and recyclability performance, creating a link between cost efficiency and market acceptance.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a mix of global manufacturers with broad application coverage and regional specialists with strong customization or cost advantages. A handful of scaled players set the pace on innovation and capacity, while a wider field competes through regional service, printing quality, pharmaceutical compliance capabilities, and application-specific expertise. Strategic differentiation is increasingly tied to three dimensions: recyclable barrier technology, capacity scale with automation, and the ability to support premium branding through high-resolution graphics and custom formats.
Several leaders illustrate how these dimensions are being pursued. Essel Propack Limited has built a broad manufacturing footprint with facilities across multiple countries and a focus on high-volume aluminum and plastic barrier tubes spanning oral care, cosmetics, food, and pharmaceutical products. Its recent investment of approximately $35 million in automated production lines reflects a strategy centered on capacity growth and operational efficiency in a major manufacturing region. Albea S.A. has positioned itself around recyclable tube platforms with advanced barrier technologies, including high-barrier recyclable laminate solutions intended for oral care and cosmetics. This emphasis on recyclability and barrier performance aligns with the regulatory and consumer pressures shaping European and global markets.
Amcor Limited has emphasized ultra-lightweight and post-consumer resin-based laminated tubes for personal care and pharmaceutical use, with a stronger narrative around circular packaging models and targeted market launches in Europe. Huhtamaki Oyj has moved into paper-based bio-barrier laminated tubes for personal care and cosmetics, supported by recyclability certifications, signaling a bet on alternative material pathways that reduce dependence on conventional plastics and aluminum in specific applications. Berry Global Group, Inc. has invested in patented hybrid technology designed to support high-resolution, premium graphic laminated tubes for cosmetic and pharmaceutical applications, reinforcing a premiumization and visual differentiation angle. Hoffmann Neopac AG has focused on recyclable mono-material barrier tubes with pharmaceutical-grade manufacturing standards, expanding capacity in North America and introducing sensory-oriented recyclable barrier options for cosmetics.
Beyond these global players, regional manufacturers play an important role in the market's architecture. Asian producers frequently serve cosmetics, skincare, and personal care demand with custom aluminum and plastic barrier tubes and strong printing capabilities, while North American and European specialists often compete on pharmaceutical compliance, documentation support, and premium healthcare-oriented formats. This diversity means that competitive advantage is not simply a function of scale. It is increasingly determined by the ability to match the right material platform, regulatory posture, and service model to the application.
The market structure suggests continued differentiation rather than rapid consolidation. The top firms maintain a meaningful but not dominant share, enabling niche leaders to thrive where they offer clear functional or compliance advantages. At the same time, the pace of technology introduction and regulatory change is raising the bar for new entrants and smaller players. Manufacturers without recyclable platforms, reliable barrier performance, or scaling automation may find it harder to compete in premium segments, while those able to deliver specialized print quality, anti-counterfeiting features, or pharmaceutical documentation may capture value in higher-margin niches.
Forward Outlook: Trends Shaping the Next Three to Five Years
The next phase of laminated tube market development is likely to be shaped by the interaction of recyclability mandates, premiumization, and manufacturing efficiency. Three trends stand out.
Recyclable barrier architectures will become a baseline expectation in key markets. As harmonized recyclability grading and recycled content requirements take hold, the market will increasingly reward tube structures that balance protection with compatibility in existing recycling streams. This will intensify redesign activity for multi-layer laminates and create durable demand for mono-material and certified recyclable solutions. The commercial opportunity is not limited to compliance; recyclable barrier tubes can support brand narratives and procurement requirements that are becoming standard in multinational purchasing decisions.
Laminated Steel Market
Premium differentiation will expand through graphics, sensory design, and security features. High-resolution printing, hybrid graphic technologies, and integrated anti-counterfeiting features are moving from specialty projects to broader commercial relevance. Brands in cosmetics and oral care are using packaging to reinforce premium positioning and consumer trust, while pharmaceutical and personal care buyers are looking for solutions that reduce risk and support product authenticity. Manufacturers that can deliver these features consistently at scale will capture higher-value demand.
Capacity growth will concentrate where automation and material access align. Investments in automated lines and regional production expansion are likely to continue, particularly in markets that combine cost efficiency with strong application demand. This will improve throughput and cost resilience but will also raise the operational standard for competitiveness. Suppliers that remain dependent on labor-intensive processes or lack material and printing specialization may face margin compression and reduced access to premium programs.
These trends carry uncertainty. Regulatory timelines and enforcement intensity may vary by region, affecting how quickly recyclable structures become commercially mandatory. Resin and aluminum pricing can still disrupt margins if supply constraints re-emerge. In addition, alternative packaging formats and refill systems may influence demand patterns in certain categories, particularly where brand owners pursue circularity through reusable or reduced-packaging models. The net effect is that growth will persist, but the allocation of that growth will increasingly favor players who can integrate material science, regulatory readiness, and premium execution.
Strategic Actions for Decision Makers
For manufacturers and packaging suppliers: Prioritize recyclable barrier platforms and mono-material pathways that align with regulated markets and multinational buyer expectations. Invest in automation and line flexibility to reduce unit costs while accommodating custom formats, high-resolution graphics, and shorter runs. Strengthen capabilities in anti-counterfeiting, sensory differentiation, and documentation support for pharmaceutical and healthcare applications, where compliance and traceability command premium value.
PW Consulting
For investors evaluating exposure to laminated tube value chains: Focus on companies with credible recyclable technology roadmaps, diversified application coverage, and capacity expansion tied to automation rather than purely incremental volume. Monitor regulatory milestones that affect recyclability grading and recycled content thresholds, since these will influence which product architectures gain or lose market access. Assess regional manufacturing footprints for cost resilience, material access, and proximity to high-growth application demand.
For brand owners, procurement teams, and R&D leaders: Treat laminated tube selection as a strategic variable rather than a procurement commodity. Align packaging architecture with formulation sensitivity, shelf-life requirements, brand positioning, and regional compliance obligations. Engage suppliers that can demonstrate recyclable design compatibility, consistent barrier performance, and the ability to support premium graphics or security features where relevant. Build sourcing strategies that balance cost, compliance, and differentiation, recognizing that premium packaging value is increasingly tied to sustainability credibility and product protection.
Detailed segment-level data, regional demand patterns, and company-specific capability comparisons can materially sharpen these decisions. Access to comprehensive research and customized insights helps leadership teams validate assumptions, size opportunities more precisely, and anticipate regulatory or competitive shifts before they affect sourcing or investment choices. For organizations seeking a fuller picture of the laminated tubes market, deeper analysis and tailored recommendations are available through the complete research report.
For detailed analysis of this topic, please visit the official page: Laminated Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Zinc Sulfate Market: How the 6.8% CAGR and Asia Pacific Growth Redefine Strategy
By pmarketresearch, 2026-09-21
The Zinc Sulfate Market at a Crossroads: Strategic Trends and Commercial Opportunities
The global zinc sulfate market is entering a phase of structural expansion, driven by converging demand across agriculture, life sciences, and industrial applications. With revenues reaching approximately 1,780 million in 2025 and a projected compound annual growth rate of 6.8 percent through 2032, the sector is moving beyond cyclical commodity fluctuations into a period defined by geographic rebalancing, product specialization, and regulatory tightening. Asia Pacific now anchors the majority of volume, while Europe and North America maintain higher value-share positions tied to pharmaceutical-grade and food-safety specifications. The market is not uniformly expanding; growth is concentrating in segments where purity, traceability, and supply reliability command premium pricing. For executives and investors, the opportunity lies in understanding where value is shifting and which operational capabilities will separate winners from commoditized suppliers.
The market structure reflects moderate concentration, with the top three players capturing just over forty percent of revenue and the top five approaching fifty-three percent. This leaves meaningful room for regional specialists, contract manufacturers, and new entrants that can align product grades with regulatory pathways and end-user certification requirements. The balance between scale and specialization will define competitive outcomes over the next several years. Companies that treat zinc sulfate as a single commodity are increasingly exposed to margin compression, while those that segment by application, hydration state, and quality assurance are building defensible positions in higher-margin channels.
Market Landscape and Core Challenges
A Market Defined by Volume Growth and Specification Differentiation
The revenue trajectory from 2020 through 2025 shows steady expansion, with a notable acceleration in 2024 before stabilizing at a higher base in 2025. The forward curve suggests continued growth, but the path is uneven across hydration states and end-use channels. Monohydrate forms the largest share of revenue, reflecting its broad industrial and specialty use, while anhydrous and hydrated variants serve more application-specific roles. The agrochemical channel remains the largest demand pool, drawing on zinc sulfate as a micronutrient supplement and soil amendment, while pharmaceuticals, water treatment, and animal nutrition contribute smaller but strategically important revenue streams that often carry stricter quality and documentation requirements.
This mix matters because growth in one channel does not automatically translate into margin expansion. Agrochemical volume can be price-sensitive and logistics-driven, while pharmaceutical and food-adjacent applications reward consistency, certification, and testing capability. The market’s center of gravity is therefore shifting not only by geography but by the economic value attached to specification control. Suppliers that can reliably bridge bulk demand and high-purity demand are positioned to capture more of the value chain.
Key Challenges and Turning Points
Three structural challenges are reshaping strategic planning across the sector.
-
Raw material and energy cost volatility. Sulfuric acid is a core input for zinc sulfate production, and regional disruptions have periodically pushed input costs higher for sulfate-based trace minerals and related chemical lines. When feedstock costs rise faster than contractual pass-through mechanisms, producers face margin pressure unless they have secured long-term agreements, optimized process efficiency, or shifted toward higher-specification grades that better absorb cost increases. This dynamic is especially relevant for producers operating in regions exposed to Middle East supply instability and for manufacturers that rely on imported acid or upstream zinc intermediates.
-
Regulatory compliance as a barrier and a differentiator. Matched to evolving safety data sheet requirements, registration dossier maintenance, and food-safety database inclusion, compliance is no longer a back-office function. It is increasingly a commercial prerequisite. Producers serving export markets must navigate REACH-related documentation, quality-assurance databases, and testing protocols that differ by destination. A company’s ability to maintain current documentation and demonstrate traceability can determine whether it wins or loses regulated tenders. In practical terms, regulatory readiness is becoming a source of competitive advantage rather than a baseline cost.
-
Supply continuity and operational resilience. Force majeure events, plant maintenance, and logistics bottlenecks can interrupt supply faster than demand adjusts. Recent operational restarts at major European sites illustrate how quickly availability can be restored after disruptions, but they also underline the importance of contingency planning for customers that depend on steady grades and reliable delivery. For buyers, this creates a premium on dual sourcing, inventory strategy, and supplier transparency. For producers, it reinforces the need for robust maintenance planning, clear communication during outages, and alternative routing for key customers.
Together, these challenges push the market toward a more differentiated operating environment. The winners will be those who convert compliance, continuity, and cost discipline into trust-based customer relationships rather than treating them as isolated risk management tasks.
Core Drivers Shaping the Market
Technology and Process Innovation
Innovation in zinc sulfate production is less about radical chemistry and more about precision, efficiency, and grade control. Higher-purity monohydrate and heptahydrate offerings depend on tighter processing controls, consistent crystallization, and reliable analytical verification. In a market where end-users increasingly compare suppliers on documented purity and batch-to-batch consistency, testing capability becomes a strategic asset. Laboratories that achieve recognized accreditation for chemical testing strengthen their ability to support pharmaceutical, food-safety, and high-purity industrial applications. This is not simply a quality function; it is a market-access enabler.
Process improvements that reduce variability, lower energy intensity, and improve yield also matter because they directly affect cost structure and the ability to compete in regulated segments. Where producers can demonstrate both consistent output and credible test documentation, they can defend pricing in channels where specification risk is costly to the buyer. In effect, technology is becoming a commercial signal as much as an operational one.
Policy and Regulatory Environment
Regulatory dynamics are tightening the practical definition of market participation. Safety data sheet updates aligned with REACH obligations, active registration dossier monitoring, and food-safety database registrations all contribute to a landscape where documentation is part of the product. For exporters and multinational buyers, this means that compliance maturity varies by supplier and by region, and those variations influence sourcing decisions.
The regulatory environment also shapes the pace at which new capacity can be commercialized and how easily suppliers can enter specific channels. Registration, notification, and certification pathways differ across pharmaceutical, food, and industrial applications, and the cost of navigating them can be substantial. Companies that invest early in maintaining current filings and transparent documentation can shorten sales cycles in regulated markets and reduce the risk of disqualification during procurement reviews.
Demand-Side Shifts in Agriculture and Life Sciences
Demand is being shaped by two distinct but important dynamics. In agriculture, zinc deficiency management and crop nutrition strategies continue to support demand for zinc sulfate as a micronutrient source, but purchasing behavior is increasingly informed by formulation compatibility, solubility, and application reliability. In life sciences and animal nutrition, demand is growing more slowly in volume terms but more decisively in value terms, because these channels require higher-grade material and stronger documentation. The rise of certified API-oriented supply chains and specialized pharmaceutical-grade sourcing has created a separate demand layer in which compliance and traceability matter as much as price.
This divergence means that aggregate demand growth can mask very different commercial realities. Volume-led buyers may focus on logistics and cost, while specification-led buyers focus on certification, purity, and supply continuity. Suppliers that understand this split can avoid the trap of competing on a single metric and instead design product lines, service models, and commercial terms around the needs of each channel.
Supply Chain and Cost Structure Evolution
The cost structure of zinc sulfate is sensitive to sulfuric acid prices, zinc feedstock availability, energy costs, and freight dynamics. Regional instability in the Middle East has periodically lifted sulfuric acid prices, raising production costs for zinc sulfate and related sulfate-based trace minerals. This is not a temporary inconvenience; it is a reminder that sulfate chemistry remains exposed to upstream volatility. Companies with diversified sourcing, long-term feedstock contracts, or integrated operations have a structural edge when input markets tighten.
At the same time, the supply chain is becoming more regionalized in practice. While Asia Pacific remains a major volume center, buyers in Europe and North America often prioritize proximity, reduced transit risk, and established regulatory documentation. That creates opportunities for producers with manufacturing footprints in or near key markets, as well as for exporters that can demonstrate reliable logistics and full regulatory alignment. Supply chain strategy is increasingly a market-access strategy.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The market features a mix of large-scale European producers, specialized U.S. suppliers, and India-based manufacturers serving pharmaceutical, industrial, and export channels. This diversity matters because each group competes on a different set of strengths.
-
Europe’s scale producers emphasize large-volume capability, broad application coverage, and food-safety and quality-assurance positioning. Their strategic advantage lies in scale, established customer relationships, and the ability to supply multiple hydration states and industrial grades. Recent operational restarts at major sites show how quickly scale producers can recover supply and reaffirm market position after disruptions, reinforcing their role as reliability anchors for industrial and specialty buyers.
-
U.S.-based specialty suppliers compete through grade specificity and application alignment. High-purity testing accreditation and product forms suited to pharmaceuticals, food, and high-purity industrial use allow these players to serve channels where specification matters more than bulk price. Their value proposition is increasingly tied to documented quality, responsive service, and the ability to support regulated procurement requirements.
-
Middle East and export-oriented suppliers combine manufacturing access with export reach, often bridging European or other production bases with distribution into international markets. Their strategic relevance comes from logistics flexibility and the ability to serve buyers seeking geographic diversification or alternative sourcing pathways.
-
India-based pharmaceutical and API-linked manufacturers are positioned around regulatory filings, international certifications, and export-ready compliance documentation. Their differentiation often rests on certifications that support pharmaceutical and regulated industrial sales, enabling them to participate in channels where documentation and audit readiness are essential.
The common thread across these groups is that scale alone is no longer enough. The most resilient players combine capacity with specification control, regulatory readiness, and the ability to maintain supply during disruptions. Where those capabilities align, suppliers can move up the value chain into channels that reward reliability and documentation.
PW Consulting
Market Structure Evolution: Consolidation, Fragmentation, and New Entry
The market is not consolidating in a simple, uniform way. Concentration is moderate, which means a few major players hold meaningful share, but the long tail of regional and specialized suppliers remains commercially relevant. Over time, the structure is likely to evolve along two tracks. In bulk and price-sensitive channels, scale, logistics efficiency, and feedstock cost management will push toward consolidation among the most efficient producers. In regulated and high-purity channels, fragmentation may persist or even deepen, because access depends on certification, testing, and documentation rather than volume alone.
Sodium Sulfate Market
New entry will be most viable where suppliers can bring a clear regulatory or specification advantage, a regional logistics benefit, or a process advantage that reduces variability and cost. Pure commodity entry without differentiation is harder to sustain, especially when input costs fluctuate and buyers increasingly screen suppliers on compliance and continuity. The more interesting opportunities lie in targeted entry into pharmaceutical-grade, food-adjacent, or specialty industrial niches where the purchase decision is shaped by risk reduction rather than lowest unit price.
Future Trends and Commercial Implications
Trend One: Specification and Compliance as Market Moats
Over the next three to five years, the practical cost of entering regulated channels will remain high, and the value of proven documentation will increase. Suppliers that maintain current safety data sheet alignment, keep registration dossiers active, and hold recognized test accreditation will find it easier to secure contracts in pharmaceutical, food-safety, and specialty industrial applications. The commercial implication is clear: documentation and testing capability will increasingly function as a market moat. Companies that treat these capabilities as strategic assets can expect stronger customer retention, better pricing resilience, and broader access to higher-margin demand.
Trend Two: Regional Rebalancing and Supply-Side Diversification
Demand will continue to grow, but the geography of value capture will shift as buyers prioritize supply continuity, regulatory alignment, and freight reliability. Asia Pacific will remain a volume anchor, but European and North American demand may increasingly favor suppliers with regional production, strong logistics, and established regulatory standing. For manufacturers, this creates pressure to decide whether to compete primarily on volume, on proximity, or on specification. For buyers, it creates an incentive to diversify sourcing rather than depend on a single region or a single supplier profile. The broader implication is that resilience will be priced into sourcing decisions more explicitly than in the past.
Trend Three: Input Volatility Will Reward Integrated and Contract-Secured Producers
Sulfuric acid and upstream zinc economics will continue to influence margins, especially when geopolitical instability affects feedstock prices. Producers with long-term sourcing, integrated operations, or flexible cost-pass-through structures will be better positioned to maintain profitability during input shocks. The commercial opportunity here is not simply cost reduction; it is the ability to offer reliable pricing and consistent availability when competitors are distracted by cost volatility. In uncertain input markets, predictability becomes a selling point.
Risks and Uncertainties to Watch
Several uncertainties could alter the trajectory. Regulatory requirements may tighten further in specific end-use channels, raising the compliance burden for exporters and smaller producers. Input cost swings could compress margins for suppliers without contract protection or process efficiency. Demand in agriculture may be sensitive to crop economics, weather patterns, and fertilizer price cycles, introducing volatility into the largest volume channel. Finally, operational disruptions at major sites can temporarily reshape regional availability, rewarding suppliers with backup capacity and transparent communication. These risks are manageable, but they require proactive planning rather than reactive adjustment.
Actionable Guidance for Decision Makers
For Manufacturers and Producers
-
Align product portfolios with the economic logic of each channel. Maintain bulk-grade capability for volume demand, but invest in the documentation, testing, and grade control needed to serve pharmaceutical, food-safety, and specialty industrial buyers. The highest-margin growth is often in segments where specification reduces customer risk.
-
Treat regulatory readiness as a commercial function. Keep safety data sheets, registration filings, and quality-assurance records current and accessible. Buyers increasingly screen for compliance during sourcing decisions, and documentation gaps can become lost sales even when price and capacity look attractive.
-
Build input resilience into operations and commercial terms. Where possible, secure feedstock arrangements, improve process efficiency, and design pricing mechanisms that can withstand periodic sulfuric acid volatility without eroding customer trust.
For Investors and Strategic Buyers
-
Assess suppliers on more than capacity. The most durable value often sits with companies that combine reliable output with recognized testing, regulatory alignment, and the ability to maintain supply through disruptions. In regulated channels, these attributes can matter more than headline volume.
-
Look for structural advantages in specification control and certification. Producers with strong documentation and accreditation are better positioned to expand into higher-margin demand and to retain customers when input costs or supply conditions become turbulent.
-
Monitor regional diversification as a sourcing signal. In a market where availability can shift quickly, suppliers with multiple production bases, export flexibility, or strong logistics footprints offer more predictable access than single-point dependencies.
For Procurement and Supply Chain Leaders
-
Diversify by specification and region, not only by supplier name. Separate bulk-grade sourcing from high-purity or regulated-grade sourcing so that supply strategy matches end-use risk. A single sourcing model rarely fits both agrochemical volume and pharmaceutical-grade requirements.
-
Incorporate compliance and continuity into supplier evaluation. Review documentation currency, testing accreditation, and operational resilience alongside price. In practice, the cheapest option can become expensive if it fails a regulatory check or disrupts production.
-
Plan for input-driven price variability. Use contract structures, inventory buffers, or dual sourcing to reduce exposure to sulfuric acid volatility and regional logistics shocks. Predictable availability can be worth a premium when production continuity is at stake.
Why Deeper Intelligence Matters Now
The zinc sulfate market is growing, but growth is not uniform, and the value of that growth depends on where a company sits in the value chain. The most important decisions in the next few years will concern specification strategy, regulatory readiness, feedstock resilience, and sourcing diversification. Aggregate market size and CAGR tell part of the story, but they do not reveal which hydration states, applications, regions, or compliance pathways will generate the strongest returns for a particular business model.
For decision makers who need to move from broad market direction to actionable targeting, the next step is to examine the segmentation detail, competitive benchmarking, and scenario-based supply analysis that sit beneath the headline trends. A more granular view of regional demand patterns, product-grade economics, and supplier capability gaps can clarify where to invest, where to source, and where to defend position. Access to the full research report enables that level of precision, providing the detailed breakdowns and customization needed to translate strategic insight into operational decisions.
Magnesium Sulfate Market
For detailed analysis of this topic, please visit the official page: Zinc Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Steam Dryer Market 2026: How Asia Pacific's 5.9% CAGR Reshapes Global Growth
By pmarketresearch, 2026-09-21
Steam Dryer Market: Strategic Trends and Commercial Opportunities Through 2032
The steam dryer market has entered a phase of measured expansion, with global revenue projected to grow from approximately $5.28 billion in 2025 to $7.19 billion by 2032, reflecting a compound annual growth rate of 5.9 percent. This trajectory is neither explosive nor stagnant; it signals a maturing industrial ecosystem where capital discipline, energy economics, and process innovation intersect. For executives and investors evaluating exposure to thermal processing equipment, the market offers steady returns but demands sharper segmentation, regional nuance, and a clear view of where competitive advantage is being rebuilt.
Underlying the headline numbers is a sector shaped by continuous drying demands across food, chemical, pharmaceutical, and bulk material applications. The revenue base has expanded consistently over the past five years, yet growth rates vary by geography, equipment type, and end-use segment. What matters now is not simply that the market is growing, but how the growth is being distributed and what structural forces are reallocating value among participants.
PW Consulting
Market Landscape and Core Challenges
At a macro level, the steam dryer market is characterized by moderate consolidation and a wide dispersion of equipment formats. The top three players account for roughly 47 percent of revenue, while the top five capture just over half. This concentration indicates a competitive environment where scale, application coverage, and service integration matter, but it also leaves substantial room for specialized suppliers and regional challengers to compete on customization, lead times, and local support.
One of the most pressing challenges is the tension between operational efficiency and input cost volatility. Industrial dryer manufacturing relies heavily on steel-intensive components, and hot rolled coil prices for dryer components hovered in the $904 to $940 per ton range in March 2025, with upward pressure linked to demand and raw material costs. Even as operators seek energy-efficient drying solutions, OEMs face margin compression if they cannot pass through material costs without sacrificing order momentum. This dynamic is reshaping pricing strategies, contract structures, and the economics of customization versus standardization.
Food Dryer Market
A second challenge lies in the skilled labor constraint affecting specialized engineering and assembly roles. Complex steam drying systems require precision fabrication, integrated controls, and commissioning expertise. Persistent shortages in these functions extend lead times and raise execution risk, particularly for large-scale or custom installations. For buyers, this translates into longer project cycles and greater dependency on supplier capacity; for manufacturers, it raises the stakes around workforce planning, modular design, and remote support capabilities.
A third inflection point is arriving through regulatory and standards-driven change. In the United States, federal energy efficiency standards for consumer clothes dryers now incorporate performance measures under Appendix D1, with updates effective after 2024. While this change primarily affects consumer equipment, it reflects a broader policy momentum around energy performance, lifecycle efficiency, and verifiable process outcomes. Industrial steam dryer buyers are increasingly exposed to similar expectations through corporate sustainability targets, utility incentives, and procurement standards that reward demonstrable energy recovery and lower thermal waste.
The practical implication is that market growth alone does not guarantee profitable growth. Companies that succeed will be those that can align equipment design with total cost of ownership, manage input cost exposure, and navigate a landscape where efficiency expectations are rising faster than in prior cycles.
Key Drivers Reshaping the Market
Technology Innovation and Breakthroughs
The most strategically important driver is the shift toward higher-efficiency steam drying architectures. Leading OEMs are investing in next-generation steam dryer platforms featuring advanced heat exchanger geometries and self-cleaning tube bundles. These improvements are not incremental cosmetics; they directly affect throughput, maintenance frequency, and energy utilization in continuous drying processes. Self-cleaning designs reduce fouling-related downtime, while refined heat exchange surfaces improve heat transfer consistency across varying load conditions.
Superheated steam drying is another area gaining traction, particularly where moisture removal, product quality, and sterilization must be managed together. The interest in this approach is reinforced by collaborative research efforts, including Valmet Corporation’s participation in the SteamDry research project for superheated steam drying technology in the paper industry. Such initiatives signal a transition from standalone equipment sales toward system-level solutions where drying, heat recovery, and condensate management are integrated.
Perhaps the most visible endorsement of scale and engineering maturity is Tsukishima Kikai Co., Ltd.’s delivery of the largest steam tube dryer to date in November 2025. Large-format units matter because they expand the feasible envelope for high-throughput applications and can improve unit economics in volume-intensive processes. At the same time, they raise the bar for installation logistics, structural support, and after-sales service, reinforcing the differentiation between suppliers that can execute complex projects and those positioned for smaller, more standardized orders.
For decision-makers, the message is clear: technology competition is moving from basic drying capability to integrated performance, reliability, and energy recovery. Procurement teams should evaluate not only drying capacity but also downtime sensitivity, cleaning cycles, and the extent to which steam condensate and waste heat can be recovered within the broader plantutility system.
Policy and Regulatory Environment
Policy dynamics are becoming a more explicit factor in demand patterns and vendor selection. Energy-related standards and efficiency expectations are no longer confined to consumer appliances; they are increasingly shaping procurement criteria in industrial contexts as well. In practical terms, buyers are looking for equipment that supports measurable efficiency gains, whether through reduced steam consumption, improved heat recovery, or process designs that lower the carbon intensity of drying operations.
At the same time, regulatory scrutiny can create both compliance burdens and differentiation opportunities. Suppliers that can document performance, provide transparent energy metrics, and align with regional standards are better positioned in tenders where efficiency is a scoring criterion. This is especially relevant in sectors such as food and pharmaceuticals, where process integrity and hygiene add further layers of specification. The regulatory environment is therefore not simply a constraint; it is a filter that rewards suppliers with robust technical documentation, application-specific validation, and lifecycle thinking.
Demand-Side Shifts in Consumer and Business Behavior
Demand is being shaped by broader industrial priorities rather than by a single sectoral surge. Food processing continues to be a major application area, driven by the need for consistent drying, shelf-life management, and scale. Chemical applications remain significant where thermal separation and moisture control are core to product specifications. Pharmaceutical and related sterile-processing environments contribute demand where drying must align with contamination control and process asepsis.
What ties these segments together is a growing emphasis on reliability and operating cost over pure purchase price. In many industrial settings, the economic case for a steam dryer is increasingly evaluated across energy consumption, maintenance intervals, cleaning requirements, and integration with existing steam and condensate systems. This is pushing buyers toward suppliers that can offer application engineering, commissioning support, and measurable performance guarantees.
Demand is also being influenced by regional industrialization patterns and the location of processing capacity. As production footprints adjust in response to logistics, labor, and market access, new drying capacity is being planned in diverse geographies. This does not automatically translate into uniform growth, but it does suggest that local service capability, parts availability, and application knowledge are becoming more valuable than in an era when equipment purchases were more centralized.
Supply Chain and Cost Structure Dynamics
The cost structure of steam dryer manufacturing is being tested by material price movement and labor availability. Steel-based components remain a core cost driver, and the recent range in hot rolled coil prices points to continued exposure for fabrication-intensive equipment. In response, some manufacturers are exploring more standardized module designs, improved procurement hedging, and design choices that reduce weight or material intensity without compromising performance.
Steam Water Heater Market
Labor shortages in specialized engineering and assembly roles add another layer of complexity. Where skilled capacity is constrained, projects can face scheduling risk, and the value of repeatable designs and remote diagnostics increases. A supply chain that can deliver consistent quality, predictable lead times, and responsive field support is becoming a competitive asset in its own right. This is particularly important for large installations and for customers operating in regions where local technical support is limited.
For commercial strategy, these dynamics suggest that cost leadership alone is increasingly difficult to sustain unless it is paired with process efficiency and service reliability. Suppliers that can manage material exposure, streamline assembly, and reduce dependency on scarce specialized labor are better placed to protect margins while maintaining competitive pricing.
Competitive Landscape and Leading Strategies
The competitive field blends global engineering groups, application-focused specialists, and regional manufacturers with strong local presence. The strategic question is not simply who is largest, but where each participant derives defensible advantage and how that advantage is likely to translate into share over the next several years.
Andritz AG operates from a position of broad process integration, offering rotary steam tube dryers, fluidized bed systems, and superheated steam dryers for pulp, paper, food processing, biomass, and bulk chemicals. Its emphasis on high-throughput continuous drying and energy recovery positions it as a solution provider for large industrial flows rather than a narrow equipment vendor. The strategic advantage here is the ability to connect drying performance with upstream and downstream process needs, which can be compelling in complex installations where overall plant efficiency matters.
GEA Group AG brings strength in spray drying and heat recovery, including aseptic-oriented systems for pharmaceutical and food applications. Its focus on aseptic sterilization and energy efficiency in steam-based processes aligns well with demand in sectors where hygiene and process control carry high value. In competitive terms, this creates a clear niche where reliability, validation, and specialized servicing can support premium positioning.
Valmet Corporation specializes in pulp drying machines, airborne dryers, and steam recovery systems with high-capacity designs and integrated steam-condensate management. Its participation in research on superheated steam drying indicates a willingness to shape emerging process directions rather than merely respond to them. For paper and adjacent industrial drying contexts, that combination of capacity leadership and technology exploration can be a durable source of relevance.
Alfa Laval AB focuses on heat transfer and condensation through plate heat exchangers and vacuum dryers for food, dairy, and industrial applications. Its orientation toward energy-efficient steam recovery and condensation gives it a distinct angle in markets where thermal efficiency and compactness are priorities. Rather than competing purely on dryer size or throughput, Alfa Laval’s value proposition often centers on how effectively steam energy is managed within the system.
In the United States, Louisville Dryer Company and Williams, White & Company illustrate the continued importance of custom and application-tailored engineering. Louisville Dryer Company manufactures custom rotary steam tube dryers and ASME Division I certified systems for bulk materials and high-volume thermal processing. Williams, White & Company provides Davenport Dryers rotary steam tube dryers and water tube coolers for ethanol, biomass, food processing, and industrial bulk materials, with a long-term efficiency focus. These firms compete by serving specialized requirements, often where standard packages are insufficient and where engineering flexibility, certification, and service continuity matter.
Tsukishima Kikai Co., Ltd. stands out for large-scale steam tube dryer capability, including the largest units manufactured and supplied globally. Recent delivery of the largest steam tube dryer to date underscores its position in high-capacity applications and its ability to execute demanding projects. This scale advantage is most relevant where volume processing justifies large equipment footprints and where supplier execution capability is a decisive factor.
In parallel, region-specific players such as Jiangsu Chuandao Washing Machinery Technology Co., Ltd. in China and Ace Industries in India illustrate how local manufacturing and application focus can support growth in laundry, commercial processing, and batch-oriented pharmaceutical, food, and chemical applications. Their relevance often lies in responsiveness, cost-appropriate engineering, and proximity to local end-users, rather than in competing directly on global scale.
The broader pattern is one of differentiation rather than uniform convergence. Some suppliers compete on integration and large continuous processes, others on hygiene-sensitive applications, and others on customization and regional service. Market evolution is likely to remain fragmented at the application level while consolidating where scale, engineering intensity, and service networks create clear cost and performance advantages. New entry will probably be most viable where a supplier can address a specific application gap, offer a compelling efficiency story, or serve an underserved geography with credible local support.
Forward Outlook: Trends and Commercial Opportunities
Over the next three to five years, three trends are likely to shape the market's commercial center of gravity.
The first is the widening premium on efficiency-enabled drying systems. As energy costs, sustainability commitments, and procurement standards become more demanding, equipment that delivers better heat recovery, lower steam intensity, and reduced maintenance burden will gain preference. The opportunity lies not only in selling dryers, but in positioning drying as part of an integrated thermal management solution. Suppliers and buyers alike will benefit from clearer comparisons of total operating cost rather than upfront price alone.
The second trend is continued segmentation by application intensity. High-throughput continuous drying, hygiene-critical batch processing, and specialized bulk material handling will not compete on identical criteria. This creates room for targeted strategies: large-scale engineering for volume applications, aseptic and validated solutions for pharmaceutical and food uses, and flexible customized systems for niche industrial needs. Companies that align their product portfolios and service models to these distinct demand profiles are more likely to defend margins than those pursuing a one-size approach.
The third trend is the growing importance of execution capability. Large-scale equipment deliveries, complex installations, and specialized labor constraints will reward suppliers that can manage project risk, standardize where possible, and provide dependable field support. For buyers, this means that vendor selection should incorporate installation logistics, commissioning support, spare parts availability, and response time alongside technical specifications.
These trends also carry uncertainty. Material cost volatility can compress margins if pricing power is limited. Labor constraints may slow project execution and increase reliance on modular or more standardized designs. Regulatory expectations may shift faster in some regions than others, altering the relative attractiveness of efficiency-led investments. And while superheated steam and advanced heat exchange designs show promise, their adoption will depend on real-world validation, maintenance requirements, and the willingness of end-users to commit to new process configurations.
Even with these caveats, the commercial opportunity is tangible for players who treat efficiency, application fit, and service reliability as core competitive variables rather than supporting features.
Strategic Implications for Decision-Makers
The following actions are most relevant depending on the reader's role in the market.
For Manufacturers and Equipment Suppliers
Design strategies should increasingly balance customization with modular repeatability. Where specialized engineering is required, the cost of bespoke execution is rising, and suppliers that can standardize core subassemblies while retaining application flexibility will be better positioned to manage labor constraints and material exposure. Efficiency claims should be supported by verifiable performance metrics and integrated into the broader value proposition, including steam recovery, cleaning intervals, and downtime sensitivity.
Service and project execution are becoming strategic differentiators. The ability to deliver large or complex installations on schedule, provide local technical support, and maintain spare parts availability can matter as much as hardware specifications in competitive bids. Suppliers should also evaluate where partnerships, channel models, or regional assembly can reduce lead times and improve responsiveness.
For Investors and Corporate Development Teams
Investment judgment should focus on business models that can convert efficiency trends into recurring value. This may include suppliers with strong application engineering, service-intensive revenue streams, or exposure to sectors where hygiene, validation, and continuous processing command higher willingness to pay. Scale leaders with integration capabilities and specialized providers with defensible niches can both be attractive, but for different reasons and with different risk profiles.
It is also important to monitor where consolidation is likely to be driven by service networks and project execution rather than by product overlap alone. In a market where the top three hold roughly 47 percent and the top five just over half, there is still meaningful fragmentation, but share shifts will probably come from differentiation in application coverage, regional reach, and reliability rather than from price competition in commoditized segments.
For Procurement and Operations Leaders
Buying decisions should weigh total cost of ownership more heavily than initial equipment price. Key evaluation areas include steam consumption patterns, heat recovery potential, cleaning and fouling behavior, commissioning complexity, and the supplier's capacity to support the installation over time. For large or specialized projects, the execution track record of the supplier is especially important given ongoing labor and supply chain constraints.
Procurement teams should also consider how drying equipment interacts with plant-level steam and condensate systems. A dryer that performs well in isolation may underdeliver if it is not aligned with site utility infrastructure or if energy recovery opportunities are overlooked. In that sense, the most valuable purchases are those that reduce operating risk and improve integration, not merely those that meet a nominal capacity requirement.
Closing Perspective
The steam dryer market through 2032 is best understood as a steadily expanding but increasingly discriminating arena. Growth is real, but value creation will depend on how well participants navigate material costs, skilled labor limits, efficiency expectations, and application-specific demand. The leaders who stand out will be those that combine technical credibility with execution discipline and a clear view of where efficiency, reliability, and integration matter most to end-users.
For organizations that need a more granular view of segmentation dynamics, regional revenue distribution, and competitive positioning across specific end-use categories, the full PW Consulting report provides detailed breakdowns and tailored scenario analysis to support planning decisions.
For detailed analysis of this topic, please visit the official page: Steam Dryer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com