

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Laminated Tubes Market Beyond the 6.5% CAGR: Key Drivers Shaping 2032 Growth

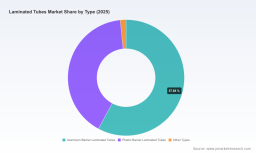
Strategic Shifts and Commercial Opportunities in the Laminated Tubes Market
The global laminated tubes market has demonstrated steady, compounding growth over the past five years, with revenue expanding from $1,345.0 million in 2020 to $1,810.0 million in 2025. Forward projections indicate this trajectory will continue through the forecast period of 2026-2032, reaching $2,800.0 million by the end of the decade. The implied compound annual growth rate of 6.5% reflects more than baseline demographic expansion; it signals a structural transition where laminated tubes are increasingly evaluated not merely as dispensing packages, but as functional components within product performance, regulatory compliance, and sustainability narratives.
Leadership teams across personal care, oral care, pharmaceuticals, and food and beverage sectors are navigating a landscape where packaging decisions directly influence formulation integrity, brand positioning, and supply chain risk exposure. The market's expansion is not uniform. It is concentrated around innovation cycles, regulatory inflection points, and geographic rebalancing that reward manufacturers and brand owners who align capacity investments with material science breakthroughs. Understanding where growth concentrates, what constraints will harden, and which competitive moves are gaining traction is essential for strategic planning in the near to medium term.
Market Landscape and Emerging Pressure Points
The laminated tubes market operates with moderate concentration, where the top three players capture approximately 26.8% of revenue and the top five reach about 32.6%. This structure indicates a competitive environment with a stable core of established manufacturers and sufficient space for regional specialists and technology-driven entrants to differentiate. Growth has been consistent year over year, with 2024 revenue reaching $1,701.4 million and 2025 closing at $1,810.0 million. The momentum continues into 2026 at $1,955.44 million, reflecting sustained demand across core application categories and incremental gains from higher-value barrier solutions.
Several structural tensions are defining the current phase of market development. First, the cost architecture of laminated tubes remains inherently higher than conventional single-material alternatives. Multilayer construction, specialty adhesives, and barrier films such as aluminum foil or engineered resins create a production cost premium typically 15-20% above standard polyethylene tubes. When resin prices experienced 30-40% spikes between 2021 and 2023 due to supply chain bottlenecks, the margin pressure on laminated tube manufacturers intensified, forcing a sharper focus on value engineering, procurement discipline, and pricing strategies that justify premium positioning through performance and compliance.
Second, regulatory momentum is reshaping design assumptions. Packaging legislation in major markets is moving from voluntary guidelines toward enforceable standards that link material composition, recyclability, and recycled content to market access. This shift places laminated tube manufacturers and brand owners under pressure to reconcile barrier performance with end-of-life compatibility, particularly in regions where existing recycling infrastructure is calibrated for simpler polymer streams.
Third, the market is encountering a capability gap between high-volume standard production and the growing demand for customized, high-resolution printed, and functionally specialized tubes. As brands seek packaging that supports premium positioning, tamper evidence, anti-counterfeiting, and differentiated dispensing experiences, manufacturers that can deliver consistent quality at scale while accommodating shorter runs and tailored specifications are gaining strategic relevance.
Drivers Reshaping Market Trajectory
Material Innovation and Barrier Performance
Technology advancement remains the most direct engine of market growth. Laminated tube value is increasingly derived from the ability to combine barrier protection, lightweighting, and recyclability in a single structure. High-barrier aluminum-based laminate tubes continue to command significant share because they protect oxygen-sensitive and moisture-sensitive formulations, but innovation is expanding the functional envelope of plastic barrier solutions as well. Recent product launches demonstrate that barrier performance is no longer treated as a fixed attribute; it is being re-engineered for compatibility with recycling streams while retaining the protective characteristics demanded by oral care, cosmetics, and pharmaceutical applications.
Examples include the introduction of recyclable high-barrier laminate tubes designed for oral care and cosmetics, the debut of mono-material recyclable barrier tubes with sensory and aesthetic differentiation, and the integration of anti-counterfeiting features directly into multilayer tube structures through holographic films. These developments matter commercially because they allow brand owners to defend formulation quality and consumer trust without defaulting to conventional aluminum structures that may face recyclability friction in certain jurisdictions. For manufacturers, the ability to offer differentiated barrier solutions is increasingly a revenue driver rather than a compliance checkbox.
Regulatory and Policy Dynamics
Policy environments are accelerating design transitions. In Europe, packaging regulation is moving toward enforceable recycled content thresholds and harmonized recyclability grading. Flexible packaging is subject to mandates requiring at least 35% recycled plastic content by 2030, which compels laminated tube producers and their customers to adapt structures for recyclability in existing polyethylene streams. Enforcement of single-use plastics requirements since mid-2024 has reinforced expectations around tethered closures and mono-material orientation, further accelerating the shift away from complex multi-layer laminates where recycling compatibility is limited.
Laminate Tube Packaging Market
By 2026, technical implementing acts are expected to impose harmonized recyclability grades, creating a more predictable but stricter evaluation framework. Manufacturers that rely on laminated films incompatible with existing recycling systems face increased redesign exposure, while those with mono-material or certified recyclable platforms gain a compliance advantage. This regulatory trajectory is not solely a European phenomenon; it influences global supply chains as multinational brand owners standardize packaging architectures across regions to reduce complexity and risk. The strategic implication is clear: regulatory readiness is becoming a market entry and retention factor, especially in premium personal care and pharmaceutical segments.
Demand-Side Evolution in Consumer and B2B Behavior
Consumer and enterprise demand is pulling laminated tube markets in two complementary directions. On the consumer side, expectations around sustainability, authenticity, and premium experience are influencing purchasing decisions in oral care and cosmetics. Tubes are no longer invisible carriers; they communicate brand values through finish, dispensing feel, and perceived environmental responsibility. On the B2B side, pharmaceutical and personal care manufacturers are seeking packaging that supports product integrity, regulatory documentation, and supply reliability. High-barrier laminated tubes serve these needs by protecting active ingredients, enabling stable shelf life, and providing a platform for controlled dispensing.
This dual demand pattern is expanding the commercial relevance of specialized tube formats. Oral care remains a particularly strong application category, benefiting from high usage frequency, brand loyalty, and format familiarity. Cosmetics and personal care continue to drive demand for customizable prints, premium tactile qualities, and functional closures. Pharmaceuticals and healthcare-related applications contribute steady demand where barrier protection and compliance documentation are critical. The underlying trend is that laminated tubes are being selected for a wider set of performance criteria, which raises the stakes for manufacturers that cannot deliver consistent quality, traceability, and specialized features.
Supply Chain Economics and Cost Structure Realignment
Cost dynamics are a persistent determinant of competitive positioning. Laminated tube economics are shaped by resin pricing, aluminum foil costs, adhesives, and multilayer processing complexity. The resin price volatility experienced during 2021-2023 illustrated how quickly input cost swings can compress margins, particularly for producers with limited ability to pass through costs or re-engineer structures for efficiency. As markets stabilize, the strategic focus is shifting toward cost resilience rather than short-term price hedging alone.
Capacity expansion is one response. Investments in automated production lines in key manufacturing hubs are increasing throughput and reducing per-unit labor intensity, which helps offset structural cost premiums. At the same time, manufacturers are pursuing lightweighting, material optimization, and hybrid technologies that preserve barrier performance while reducing overall material usage. These moves are not only about margin protection; they are increasingly tied to sustainability messaging and recyclability performance, creating a link between cost efficiency and market acceptance.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a mix of global manufacturers with broad application coverage and regional specialists with strong customization or cost advantages. A handful of scaled players set the pace on innovation and capacity, while a wider field competes through regional service, printing quality, pharmaceutical compliance capabilities, and application-specific expertise. Strategic differentiation is increasingly tied to three dimensions: recyclable barrier technology, capacity scale with automation, and the ability to support premium branding through high-resolution graphics and custom formats.
Several leaders illustrate how these dimensions are being pursued. Essel Propack Limited has built a broad manufacturing footprint with facilities across multiple countries and a focus on high-volume aluminum and plastic barrier tubes spanning oral care, cosmetics, food, and pharmaceutical products. Its recent investment of approximately $35 million in automated production lines reflects a strategy centered on capacity growth and operational efficiency in a major manufacturing region. Albea S.A. has positioned itself around recyclable tube platforms with advanced barrier technologies, including high-barrier recyclable laminate solutions intended for oral care and cosmetics. This emphasis on recyclability and barrier performance aligns with the regulatory and consumer pressures shaping European and global markets.
Amcor Limited has emphasized ultra-lightweight and post-consumer resin-based laminated tubes for personal care and pharmaceutical use, with a stronger narrative around circular packaging models and targeted market launches in Europe. Huhtamaki Oyj has moved into paper-based bio-barrier laminated tubes for personal care and cosmetics, supported by recyclability certifications, signaling a bet on alternative material pathways that reduce dependence on conventional plastics and aluminum in specific applications. Berry Global Group, Inc. has invested in patented hybrid technology designed to support high-resolution, premium graphic laminated tubes for cosmetic and pharmaceutical applications, reinforcing a premiumization and visual differentiation angle. Hoffmann Neopac AG has focused on recyclable mono-material barrier tubes with pharmaceutical-grade manufacturing standards, expanding capacity in North America and introducing sensory-oriented recyclable barrier options for cosmetics.
Beyond these global players, regional manufacturers play an important role in the market's architecture. Asian producers frequently serve cosmetics, skincare, and personal care demand with custom aluminum and plastic barrier tubes and strong printing capabilities, while North American and European specialists often compete on pharmaceutical compliance, documentation support, and premium healthcare-oriented formats. This diversity means that competitive advantage is not simply a function of scale. It is increasingly determined by the ability to match the right material platform, regulatory posture, and service model to the application.
The market structure suggests continued differentiation rather than rapid consolidation. The top firms maintain a meaningful but not dominant share, enabling niche leaders to thrive where they offer clear functional or compliance advantages. At the same time, the pace of technology introduction and regulatory change is raising the bar for new entrants and smaller players. Manufacturers without recyclable platforms, reliable barrier performance, or scaling automation may find it harder to compete in premium segments, while those able to deliver specialized print quality, anti-counterfeiting features, or pharmaceutical documentation may capture value in higher-margin niches.
Forward Outlook: Trends Shaping the Next Three to Five Years
The next phase of laminated tube market development is likely to be shaped by the interaction of recyclability mandates, premiumization, and manufacturing efficiency. Three trends stand out.
Recyclable barrier architectures will become a baseline expectation in key markets. As harmonized recyclability grading and recycled content requirements take hold, the market will increasingly reward tube structures that balance protection with compatibility in existing recycling streams. This will intensify redesign activity for multi-layer laminates and create durable demand for mono-material and certified recyclable solutions. The commercial opportunity is not limited to compliance; recyclable barrier tubes can support brand narratives and procurement requirements that are becoming standard in multinational purchasing decisions.
Laminated Steel Market
Premium differentiation will expand through graphics, sensory design, and security features. High-resolution printing, hybrid graphic technologies, and integrated anti-counterfeiting features are moving from specialty projects to broader commercial relevance. Brands in cosmetics and oral care are using packaging to reinforce premium positioning and consumer trust, while pharmaceutical and personal care buyers are looking for solutions that reduce risk and support product authenticity. Manufacturers that can deliver these features consistently at scale will capture higher-value demand.
Capacity growth will concentrate where automation and material access align. Investments in automated lines and regional production expansion are likely to continue, particularly in markets that combine cost efficiency with strong application demand. This will improve throughput and cost resilience but will also raise the operational standard for competitiveness. Suppliers that remain dependent on labor-intensive processes or lack material and printing specialization may face margin compression and reduced access to premium programs.
These trends carry uncertainty. Regulatory timelines and enforcement intensity may vary by region, affecting how quickly recyclable structures become commercially mandatory. Resin and aluminum pricing can still disrupt margins if supply constraints re-emerge. In addition, alternative packaging formats and refill systems may influence demand patterns in certain categories, particularly where brand owners pursue circularity through reusable or reduced-packaging models. The net effect is that growth will persist, but the allocation of that growth will increasingly favor players who can integrate material science, regulatory readiness, and premium execution.
Strategic Actions for Decision Makers
For manufacturers and packaging suppliers: Prioritize recyclable barrier platforms and mono-material pathways that align with regulated markets and multinational buyer expectations. Invest in automation and line flexibility to reduce unit costs while accommodating custom formats, high-resolution graphics, and shorter runs. Strengthen capabilities in anti-counterfeiting, sensory differentiation, and documentation support for pharmaceutical and healthcare applications, where compliance and traceability command premium value.
PW Consulting
For investors evaluating exposure to laminated tube value chains: Focus on companies with credible recyclable technology roadmaps, diversified application coverage, and capacity expansion tied to automation rather than purely incremental volume. Monitor regulatory milestones that affect recyclability grading and recycled content thresholds, since these will influence which product architectures gain or lose market access. Assess regional manufacturing footprints for cost resilience, material access, and proximity to high-growth application demand.
For brand owners, procurement teams, and R&D leaders: Treat laminated tube selection as a strategic variable rather than a procurement commodity. Align packaging architecture with formulation sensitivity, shelf-life requirements, brand positioning, and regional compliance obligations. Engage suppliers that can demonstrate recyclable design compatibility, consistent barrier performance, and the ability to support premium graphics or security features where relevant. Build sourcing strategies that balance cost, compliance, and differentiation, recognizing that premium packaging value is increasingly tied to sustainability credibility and product protection.
Detailed segment-level data, regional demand patterns, and company-specific capability comparisons can materially sharpen these decisions. Access to comprehensive research and customized insights helps leadership teams validate assumptions, size opportunities more precisely, and anticipate regulatory or competitive shifts before they affect sourcing or investment choices. For organizations seeking a fuller picture of the laminated tubes market, deeper analysis and tailored recommendations are available through the complete research report.
For detailed analysis of this topic, please visit the official page: Laminated Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com