

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Zinc Sulfate Market: How the 6.8% CAGR and Asia Pacific Growth Redefine Strategy

The Zinc Sulfate Market at a Crossroads: Strategic Trends and Commercial Opportunities
The global zinc sulfate market is entering a phase of structural expansion, driven by converging demand across agriculture, life sciences, and industrial applications. With revenues reaching approximately 1,780 million in 2025 and a projected compound annual growth rate of 6.8 percent through 2032, the sector is moving beyond cyclical commodity fluctuations into a period defined by geographic rebalancing, product specialization, and regulatory tightening. Asia Pacific now anchors the majority of volume, while Europe and North America maintain higher value-share positions tied to pharmaceutical-grade and food-safety specifications. The market is not uniformly expanding; growth is concentrating in segments where purity, traceability, and supply reliability command premium pricing. For executives and investors, the opportunity lies in understanding where value is shifting and which operational capabilities will separate winners from commoditized suppliers.
The market structure reflects moderate concentration, with the top three players capturing just over forty percent of revenue and the top five approaching fifty-three percent. This leaves meaningful room for regional specialists, contract manufacturers, and new entrants that can align product grades with regulatory pathways and end-user certification requirements. The balance between scale and specialization will define competitive outcomes over the next several years. Companies that treat zinc sulfate as a single commodity are increasingly exposed to margin compression, while those that segment by application, hydration state, and quality assurance are building defensible positions in higher-margin channels.
Market Landscape and Core Challenges
A Market Defined by Volume Growth and Specification Differentiation
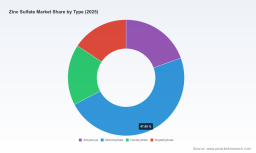
The revenue trajectory from 2020 through 2025 shows steady expansion, with a notable acceleration in 2024 before stabilizing at a higher base in 2025. The forward curve suggests continued growth, but the path is uneven across hydration states and end-use channels. Monohydrate forms the largest share of revenue, reflecting its broad industrial and specialty use, while anhydrous and hydrated variants serve more application-specific roles. The agrochemical channel remains the largest demand pool, drawing on zinc sulfate as a micronutrient supplement and soil amendment, while pharmaceuticals, water treatment, and animal nutrition contribute smaller but strategically important revenue streams that often carry stricter quality and documentation requirements.
This mix matters because growth in one channel does not automatically translate into margin expansion. Agrochemical volume can be price-sensitive and logistics-driven, while pharmaceutical and food-adjacent applications reward consistency, certification, and testing capability. The market’s center of gravity is therefore shifting not only by geography but by the economic value attached to specification control. Suppliers that can reliably bridge bulk demand and high-purity demand are positioned to capture more of the value chain.
Key Challenges and Turning Points
Three structural challenges are reshaping strategic planning across the sector.
-
Raw material and energy cost volatility. Sulfuric acid is a core input for zinc sulfate production, and regional disruptions have periodically pushed input costs higher for sulfate-based trace minerals and related chemical lines. When feedstock costs rise faster than contractual pass-through mechanisms, producers face margin pressure unless they have secured long-term agreements, optimized process efficiency, or shifted toward higher-specification grades that better absorb cost increases. This dynamic is especially relevant for producers operating in regions exposed to Middle East supply instability and for manufacturers that rely on imported acid or upstream zinc intermediates.
-
Regulatory compliance as a barrier and a differentiator. Matched to evolving safety data sheet requirements, registration dossier maintenance, and food-safety database inclusion, compliance is no longer a back-office function. It is increasingly a commercial prerequisite. Producers serving export markets must navigate REACH-related documentation, quality-assurance databases, and testing protocols that differ by destination. A company’s ability to maintain current documentation and demonstrate traceability can determine whether it wins or loses regulated tenders. In practical terms, regulatory readiness is becoming a source of competitive advantage rather than a baseline cost.
-
Supply continuity and operational resilience. Force majeure events, plant maintenance, and logistics bottlenecks can interrupt supply faster than demand adjusts. Recent operational restarts at major European sites illustrate how quickly availability can be restored after disruptions, but they also underline the importance of contingency planning for customers that depend on steady grades and reliable delivery. For buyers, this creates a premium on dual sourcing, inventory strategy, and supplier transparency. For producers, it reinforces the need for robust maintenance planning, clear communication during outages, and alternative routing for key customers.
Together, these challenges push the market toward a more differentiated operating environment. The winners will be those who convert compliance, continuity, and cost discipline into trust-based customer relationships rather than treating them as isolated risk management tasks.
Core Drivers Shaping the Market
Technology and Process Innovation
Innovation in zinc sulfate production is less about radical chemistry and more about precision, efficiency, and grade control. Higher-purity monohydrate and heptahydrate offerings depend on tighter processing controls, consistent crystallization, and reliable analytical verification. In a market where end-users increasingly compare suppliers on documented purity and batch-to-batch consistency, testing capability becomes a strategic asset. Laboratories that achieve recognized accreditation for chemical testing strengthen their ability to support pharmaceutical, food-safety, and high-purity industrial applications. This is not simply a quality function; it is a market-access enabler.
Process improvements that reduce variability, lower energy intensity, and improve yield also matter because they directly affect cost structure and the ability to compete in regulated segments. Where producers can demonstrate both consistent output and credible test documentation, they can defend pricing in channels where specification risk is costly to the buyer. In effect, technology is becoming a commercial signal as much as an operational one.
Policy and Regulatory Environment
Regulatory dynamics are tightening the practical definition of market participation. Safety data sheet updates aligned with REACH obligations, active registration dossier monitoring, and food-safety database registrations all contribute to a landscape where documentation is part of the product. For exporters and multinational buyers, this means that compliance maturity varies by supplier and by region, and those variations influence sourcing decisions.
The regulatory environment also shapes the pace at which new capacity can be commercialized and how easily suppliers can enter specific channels. Registration, notification, and certification pathways differ across pharmaceutical, food, and industrial applications, and the cost of navigating them can be substantial. Companies that invest early in maintaining current filings and transparent documentation can shorten sales cycles in regulated markets and reduce the risk of disqualification during procurement reviews.
Demand-Side Shifts in Agriculture and Life Sciences
Demand is being shaped by two distinct but important dynamics. In agriculture, zinc deficiency management and crop nutrition strategies continue to support demand for zinc sulfate as a micronutrient source, but purchasing behavior is increasingly informed by formulation compatibility, solubility, and application reliability. In life sciences and animal nutrition, demand is growing more slowly in volume terms but more decisively in value terms, because these channels require higher-grade material and stronger documentation. The rise of certified API-oriented supply chains and specialized pharmaceutical-grade sourcing has created a separate demand layer in which compliance and traceability matter as much as price.
This divergence means that aggregate demand growth can mask very different commercial realities. Volume-led buyers may focus on logistics and cost, while specification-led buyers focus on certification, purity, and supply continuity. Suppliers that understand this split can avoid the trap of competing on a single metric and instead design product lines, service models, and commercial terms around the needs of each channel.
Supply Chain and Cost Structure Evolution
The cost structure of zinc sulfate is sensitive to sulfuric acid prices, zinc feedstock availability, energy costs, and freight dynamics. Regional instability in the Middle East has periodically lifted sulfuric acid prices, raising production costs for zinc sulfate and related sulfate-based trace minerals. This is not a temporary inconvenience; it is a reminder that sulfate chemistry remains exposed to upstream volatility. Companies with diversified sourcing, long-term feedstock contracts, or integrated operations have a structural edge when input markets tighten.
At the same time, the supply chain is becoming more regionalized in practice. While Asia Pacific remains a major volume center, buyers in Europe and North America often prioritize proximity, reduced transit risk, and established regulatory documentation. That creates opportunities for producers with manufacturing footprints in or near key markets, as well as for exporters that can demonstrate reliable logistics and full regulatory alignment. Supply chain strategy is increasingly a market-access strategy.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The market features a mix of large-scale European producers, specialized U.S. suppliers, and India-based manufacturers serving pharmaceutical, industrial, and export channels. This diversity matters because each group competes on a different set of strengths.
-
Europe’s scale producers emphasize large-volume capability, broad application coverage, and food-safety and quality-assurance positioning. Their strategic advantage lies in scale, established customer relationships, and the ability to supply multiple hydration states and industrial grades. Recent operational restarts at major sites show how quickly scale producers can recover supply and reaffirm market position after disruptions, reinforcing their role as reliability anchors for industrial and specialty buyers.
-
U.S.-based specialty suppliers compete through grade specificity and application alignment. High-purity testing accreditation and product forms suited to pharmaceuticals, food, and high-purity industrial use allow these players to serve channels where specification matters more than bulk price. Their value proposition is increasingly tied to documented quality, responsive service, and the ability to support regulated procurement requirements.
-
Middle East and export-oriented suppliers combine manufacturing access with export reach, often bridging European or other production bases with distribution into international markets. Their strategic relevance comes from logistics flexibility and the ability to serve buyers seeking geographic diversification or alternative sourcing pathways.
-
India-based pharmaceutical and API-linked manufacturers are positioned around regulatory filings, international certifications, and export-ready compliance documentation. Their differentiation often rests on certifications that support pharmaceutical and regulated industrial sales, enabling them to participate in channels where documentation and audit readiness are essential.
The common thread across these groups is that scale alone is no longer enough. The most resilient players combine capacity with specification control, regulatory readiness, and the ability to maintain supply during disruptions. Where those capabilities align, suppliers can move up the value chain into channels that reward reliability and documentation.
PW Consulting
Market Structure Evolution: Consolidation, Fragmentation, and New Entry
The market is not consolidating in a simple, uniform way. Concentration is moderate, which means a few major players hold meaningful share, but the long tail of regional and specialized suppliers remains commercially relevant. Over time, the structure is likely to evolve along two tracks. In bulk and price-sensitive channels, scale, logistics efficiency, and feedstock cost management will push toward consolidation among the most efficient producers. In regulated and high-purity channels, fragmentation may persist or even deepen, because access depends on certification, testing, and documentation rather than volume alone.
Sodium Sulfate Market
New entry will be most viable where suppliers can bring a clear regulatory or specification advantage, a regional logistics benefit, or a process advantage that reduces variability and cost. Pure commodity entry without differentiation is harder to sustain, especially when input costs fluctuate and buyers increasingly screen suppliers on compliance and continuity. The more interesting opportunities lie in targeted entry into pharmaceutical-grade, food-adjacent, or specialty industrial niches where the purchase decision is shaped by risk reduction rather than lowest unit price.
Future Trends and Commercial Implications
Trend One: Specification and Compliance as Market Moats
Over the next three to five years, the practical cost of entering regulated channels will remain high, and the value of proven documentation will increase. Suppliers that maintain current safety data sheet alignment, keep registration dossiers active, and hold recognized test accreditation will find it easier to secure contracts in pharmaceutical, food-safety, and specialty industrial applications. The commercial implication is clear: documentation and testing capability will increasingly function as a market moat. Companies that treat these capabilities as strategic assets can expect stronger customer retention, better pricing resilience, and broader access to higher-margin demand.
Trend Two: Regional Rebalancing and Supply-Side Diversification
Demand will continue to grow, but the geography of value capture will shift as buyers prioritize supply continuity, regulatory alignment, and freight reliability. Asia Pacific will remain a volume anchor, but European and North American demand may increasingly favor suppliers with regional production, strong logistics, and established regulatory standing. For manufacturers, this creates pressure to decide whether to compete primarily on volume, on proximity, or on specification. For buyers, it creates an incentive to diversify sourcing rather than depend on a single region or a single supplier profile. The broader implication is that resilience will be priced into sourcing decisions more explicitly than in the past.
Trend Three: Input Volatility Will Reward Integrated and Contract-Secured Producers
Sulfuric acid and upstream zinc economics will continue to influence margins, especially when geopolitical instability affects feedstock prices. Producers with long-term sourcing, integrated operations, or flexible cost-pass-through structures will be better positioned to maintain profitability during input shocks. The commercial opportunity here is not simply cost reduction; it is the ability to offer reliable pricing and consistent availability when competitors are distracted by cost volatility. In uncertain input markets, predictability becomes a selling point.
Risks and Uncertainties to Watch
Several uncertainties could alter the trajectory. Regulatory requirements may tighten further in specific end-use channels, raising the compliance burden for exporters and smaller producers. Input cost swings could compress margins for suppliers without contract protection or process efficiency. Demand in agriculture may be sensitive to crop economics, weather patterns, and fertilizer price cycles, introducing volatility into the largest volume channel. Finally, operational disruptions at major sites can temporarily reshape regional availability, rewarding suppliers with backup capacity and transparent communication. These risks are manageable, but they require proactive planning rather than reactive adjustment.
Actionable Guidance for Decision Makers
For Manufacturers and Producers
-
Align product portfolios with the economic logic of each channel. Maintain bulk-grade capability for volume demand, but invest in the documentation, testing, and grade control needed to serve pharmaceutical, food-safety, and specialty industrial buyers. The highest-margin growth is often in segments where specification reduces customer risk.
-
Treat regulatory readiness as a commercial function. Keep safety data sheets, registration filings, and quality-assurance records current and accessible. Buyers increasingly screen for compliance during sourcing decisions, and documentation gaps can become lost sales even when price and capacity look attractive.
-
Build input resilience into operations and commercial terms. Where possible, secure feedstock arrangements, improve process efficiency, and design pricing mechanisms that can withstand periodic sulfuric acid volatility without eroding customer trust.
For Investors and Strategic Buyers
-
Assess suppliers on more than capacity. The most durable value often sits with companies that combine reliable output with recognized testing, regulatory alignment, and the ability to maintain supply through disruptions. In regulated channels, these attributes can matter more than headline volume.
-
Look for structural advantages in specification control and certification. Producers with strong documentation and accreditation are better positioned to expand into higher-margin demand and to retain customers when input costs or supply conditions become turbulent.
-
Monitor regional diversification as a sourcing signal. In a market where availability can shift quickly, suppliers with multiple production bases, export flexibility, or strong logistics footprints offer more predictable access than single-point dependencies.
For Procurement and Supply Chain Leaders
-
Diversify by specification and region, not only by supplier name. Separate bulk-grade sourcing from high-purity or regulated-grade sourcing so that supply strategy matches end-use risk. A single sourcing model rarely fits both agrochemical volume and pharmaceutical-grade requirements.
-
Incorporate compliance and continuity into supplier evaluation. Review documentation currency, testing accreditation, and operational resilience alongside price. In practice, the cheapest option can become expensive if it fails a regulatory check or disrupts production.
-
Plan for input-driven price variability. Use contract structures, inventory buffers, or dual sourcing to reduce exposure to sulfuric acid volatility and regional logistics shocks. Predictable availability can be worth a premium when production continuity is at stake.
Why Deeper Intelligence Matters Now
The zinc sulfate market is growing, but growth is not uniform, and the value of that growth depends on where a company sits in the value chain. The most important decisions in the next few years will concern specification strategy, regulatory readiness, feedstock resilience, and sourcing diversification. Aggregate market size and CAGR tell part of the story, but they do not reveal which hydration states, applications, regions, or compliance pathways will generate the strongest returns for a particular business model.
For decision makers who need to move from broad market direction to actionable targeting, the next step is to examine the segmentation detail, competitive benchmarking, and scenario-based supply analysis that sit beneath the headline trends. A more granular view of regional demand patterns, product-grade economics, and supplier capability gaps can clarify where to invest, where to source, and where to defend position. Access to the full research report enables that level of precision, providing the detailed breakdowns and customization needed to translate strategic insight into operational decisions.
Magnesium Sulfate Market
For detailed analysis of this topic, please visit the official page: Zinc Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com