

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
High-End Household P1.29 LED Display Market: Why 7.8% CAGR Signals a Strategic Reset

Strategic Trends and Commercial Opportunities in the High-End Household P1.29 LED Display Market
Market Overview: Trajectory and Scale
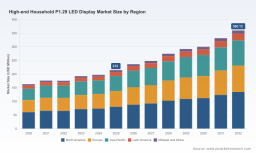
The high-end household P1.29 LED display sector has entered a phase of sustained expansion, driven by a convergence of premium content consumption, architectural integration, and technological maturation. Between 2020 and 2025, revenue climbed from 163.15 million USD to an estimated 215.0 million USD, reflecting a compound annual growth rate of 7.8 percent over the broader 2020 to 2032 horizon. This trajectory points toward a market surpassing 360 million USD by the end of the decade, as fine-pitch LED panels transition from commercial and institutional deployments into luxury residential and high-performance entertainment environments.
The P1.29 pixel pitch specification occupies a strategic middle ground in the fine-pitch spectrum. It delivers resolution and contrast levels that rival traditional premium display architectures while preserving the modularity, brightness headroom, and longevity associated with LED technology. Growth has been particularly pronounced in the 55 to 65 inch and above 65 inch segments, where consumers and enterprise buyers alike are prioritizing immersive viewing surfaces over compact consumer electronics form factors. Flat panels continue to anchor the display type mix, but curved and transparent variants are gaining traction in premium interiors where design integration and spatial awareness matter as much as picture quality. On the technology front, OLED remains a benchmark for contrast and response, yet quantum dot enhancement, mini LED backlighting architectures, and emerging micro LED approaches are reshaping expectations around color accuracy, HDR performance, and energy efficiency.
Market concentration reflects a mature but still evolving competitive arena. The top three players account for roughly 45 percent of revenue, while the top five reach approximately 60 percent. This distribution suggests a landscape where established display manufacturers and specialized fine-pitch LED specialists coexist, but it also indicates room for asymmetric moves in product ecosystems, channel partnerships, and regional differentiation.
For decision makers, the headline takeaway is that premium home LED is no longer a niche experiment. It is a growing, multi-segment category where value creation depends on aligning pixel architecture, processing capability, ecosystem integration, and cost discipline. The companies that win will be those that treat P1.29 displays not merely as screens, but as integrated components of residential entertainment, ambient media, and premium interior experiences.
Critical Challenges and Inflection Points
Despite favorable momentum, the market faces several structural tensions that will define competitive outcomes over the next few years. The first is component and supply chain timing. High-brightness SMD LEDs used in P1.29 panels rely on precision manufacturing and specialized material inputs. Premium components can experience lead times extending to 12 to 18 weeks, creating planning friction for product launches, channel replenishment, and large residential projects. In an environment where pricing visibility and delivery reliability increasingly influence buyer selection, these timing constraints can erode margin flexibility and constrain responsiveness to demand shifts.
The second challenge revolves around input cost volatility and labor intensity. Advanced surface-mount technology assembly for P1.29 modules commands hourly labor rates significantly above baseline in precision electronics facilities, reflecting the skill requirements and quality controls needed for fine-pitch production. At the same time, critical mineral sourcing for gallium and indium in RGB LED chips has shown quarterly cost fluctuations of up to 15 percent. This combination of specialized labor pricing and raw material volatility creates a cost structure that is difficult to compress purely through scale. Manufacturers must therefore manage cost through design efficiency, yield improvement, supplier diversification, and selective technology substitution rather than relying on commodity-style procurement advantages.
A third inflection point is regulatory and standards-driven safety compliance. LED displays exceeding 1000 nits brightness must meet IEC 62471 photobiological safety requirements for residential installation. As high-brightness P1.29 panels move from controlled commercial settings into living spaces, compliance becomes a gating factor for product acceptance, installer confidence, and liability management. This is not a barrier that eliminates opportunity; rather, it shifts value toward firms that can embed safety, thermal management, and installation guidance into their product and service narratives from the outset.
A fourth pressure point is geopolitical and tariff exposure. Import costs for Chinese-origin fine-pitch LED modules and panels can be impacted by US tariffs ranging from 10 to 25 percent. For P1.29 household displays, where margin structures are already shaped by premium specifications and complex manufacturing, tariff exposure can meaningfully alter landed cost, pricing strategy, and the relative competitiveness of regional sourcing models. Companies that treat trade policy as a static assumption rather than a planning variable risk underpricing, margin compression, or disrupted channel economics.
Together, these challenges point to a central reality: the P1.29 household display market rewards operational resilience and ecosystem maturity at least as much as product specifications. The inflection point is not whether fine-pitch LED belongs in premium homes, but which firms can produce, deliver, and support it reliably under cost and compliance pressure.
Key Demand Drivers
Technology innovation and integration depth are among the strongest demand catalysts. Recent cooperative moves between major consumer display organizations and professional processing specialists illustrate the shift toward integrated home display ecosystems. For example, a 2025 partnership between Samsung Electronics and Barco focused on co-developing high-end LED home display ecosystems, combining Samsung's consumer microLED direction with Barco's processing capabilities for luxury residential applications. This signals a broader industry realization that pixel pitch alone does not win premium households; processing, calibration, content compatibility, and installation reliability are equally decisive. Product-level responses reinforce the same theme. In mid-2025, LG Electronics introduced a 29-inch MicroLED-based home display designed for premium home theater setups, emphasizing advanced sub-pixel drive and enhanced HDR performance. Even at smaller screen sizes, manufacturers are pursuing high-end differentiation through drive engineering and color performance, not just panel size or resolution alone.
Competitor consolidation around driver and interface technology is also reshaping the innovation frontier. Sharp's 2024 acquisition of a microLED driver technology firm was aimed at accelerating compact, high-brightness LED panels for luxury residential displays and improving color accuracy at small pixel pitches. Driver architecture has become a strategic asset because it influences brightness uniformity, thermal behavior, signal integrity, and the ability to scale fine-pitch designs without sacrificing yield. As leading firms absorb or partner for these capabilities, the differentiation gap between pure panel assembly and full-system competence widens.
Small Pitch LED Display Market
Policy and regulatory conditions are shaping adoption patterns in ways that go beyond compliance. Safety standards for high-brightness displays and trade policy on imported modules are creating uneven cost and risk environments across regions. In practice, this encourages regional sourcing strategies, localized assembly where feasible, and product designs that can be certified for multiple regulatory contexts. It also increases the importance of documentation, installer training, and after-sale support, especially for premium residential projects where buyers and integrators expect end-to-end assurance rather than component-level performance claims.
On the demand side, consumer and enterprise behavior is shifting toward experiential and multi-use display environments. Home theater is a core application profile, reflecting the desire for cinematic image quality within private spaces. Gaming is another significant driver, as enthusiasts seek high refresh behavior, low latency, and large immersive surfaces that complement high-performance systems. Corporate presentations and digital signage also contribute to demand, though their role in the household category is more about crossover value: the same fine-pitch technologies used in professional interiors are increasingly influencing premium home expectations for color consistency, brightness stability, and modularity. What ties these applications together is that they reward accuracy, uniformity, and ecosystem readiness more than sheer size increments. Buyers are increasingly comparing fine-pitch LED against alternative premium display technologies on total experience, not just spec sheets.
Supply chain and cost structure changes are a fourth driver, but they operate differently from traditional volume-led cost reduction. P1.29 production depends on precision assembly, tight quality tolerances, and specialized component availability. As a result, competitive advantage is increasingly derived from yield optimization, process consistency, component selection, and supplier relationships that reduce exposure to long lead times and cost swings. Firms that can stabilize throughput while maintaining high-brightness performance and color consistency will be better positioned to offer predictable pricing and dependable delivery, both of which matter for premium residential projects and repeat enterprise deployments.
The strategic implication is that demand is being pulled not only by larger screens, but by better-integrated ones. buyers want displays that fit into residential design, comply with safety expectations, perform consistently under HDR and gaming workloads, and arrive with reliable support. That combination elevates the importance of product architecture, processing partnerships, manufacturing discipline, and regional cost management.
Competitive Landscape and Leading Strategies
The competitive field includes organizations with very different strategic centers of gravity. Samsung Display and LG Display operate from major South Korean electronics ecosystems and emphasize premium high-resolution LED panels and advanced OLED and LED technologies for high-end household video displays. Their advantage is often rooted in scale, system integration, and the ability to connect display hardware with broader consumer electronics and content ecosystems. Panasonic Corporation contributes a distinct angle through professional and household LED display solutions, including all-in-one systems that reduce integration complexity for end users and installers. Sharp Corporation brings attention to microLED driver technology and compact high-brightness LED panels for luxury residential applications, with a focus on precision and color behavior at small pixel pitches. Barco, based in Belgium, stands out for its emphasis on X1.2 series LED video walls with 1.29 mm pixel pitch for high-performance indoor installations, positioning around processing, installation reliability, and professional-grade performance characteristics.
A second cluster includes specialized fine-pitch LED manufacturers based in Shenzhen, Beijing, and other technology hubs. AOTO Electronics focuses on premium fine-pitch COB LED displays for high-end residential and cinema applications. Liantronics emphasizes fine-pitch and high-resolution LED screens for premium indoor household use. Absen targets small-pitch LED displays, including P1.29 mm series options for high-end residential installations. Leyard concentrates on fine-pitch LED video walls and residential display solutions. Unilumin focuses on professional LED displays with small-pitch options for household high-end applications. AVMS, in Germany, contributes high-resolution 1.29 mm GOB LED modules and indoor display systems for premium household installations. These firms often compete on modularity, pitch precision, customization, regional serviceability, and the ability to tailor products to specific interior and installation requirements.
The differentiating question is not simply who makes the smallest pitch or the brightest panel. It is who can manage the full stack most effectively. Leading strategies tend to fall into several patterns. One is ecosystem integration: combining panel hardware with processing, calibration, and installation support so that the display arrives as a usable premium solution rather than a component. Another is technology specialization: building advantage around driver architecture, GOB or COB module design, sub-pixel drive, or compact high-brightness implementations that improve color accuracy and uniformity at fine pitches. A third is regional and channel positioning: aligning manufacturing footprint, certification readiness, and distribution relationships to reduce tariff exposure, shorten delivery paths, and strengthen installer trust. A fourth is application targeting: designing product lines for specific use cases such as home theater, luxury interiors, or high-performance indoor installations where brightness, HDR behavior, and viewing distance requirements differ.
The market landscape is evolving through both consolidation and differentiation. Recent partnerships and acquisitions indicate that firms are seeking capabilities that extend beyond panel fabrication. The trend toward co-developed ecosystems, driver technology absorption, and specialized module design suggests that vertical depth is becoming a competitive necessity in the premium segment. At the same time, the presence of multiple specialists indicates that differentiation by application, region, and installation model remains viable. New entrants can still compete if they bring a credible combination of fine-pitch precision, ecosystem readiness, and dependable delivery, but head-to-head competition on price alone is increasingly difficult given labor intensity, component lead times, and compliance costs.
For buyers and investors, the practical conclusion is that market leadership is increasingly defined by reliability and integration rather than headline specifications. A strong P1.29 strategy now involves a clear answer to how the product will be manufactured consistently, certified for residential use, supported through installation, and positioned against tariff and sourcing risks.
Future Outlook: Three Strategic Trends
One major trend over the next three to five years is the deepening of integrated home display ecosystems. As premium residential deployments grow, the value of standalone panels will increasingly be judged against full solution quality: processing, calibration, compatibility, installer support, and long-term serviceability. This favors organizations that can coordinate hardware, software-adjacent processing, and installation workflows into a coherent offering. The opportunity lies in owning a more complete experience pathway, especially in high-value residential projects where buyers and integrators prioritize dependable outcomes over isolated performance claims. The risk is that integration expands scope and cost, requiring disciplined execution and strong partnership models where internal capability is incomplete.
A second trend is continued coexistence and selective convergence between fine-pitch LED and alternative premium display technologies. OLED, quantum dot, mini LED, and micro LED approaches will continue to compete for attention in the premium household category, each with strengths in contrast, color volume, brightness headroom, or form factor. Rather than a single winner, the market is likely to segment by use case and buyer priorities. Some environments will favor LED for brightness robustness and modular scalability, while others will lean toward competing technologies for specific visual characteristics. The commercial opportunity here is in positioning P1.29 products with a clear, defensible advantage for particular applications and design requirements rather than attempting to win every premium use case with a single architecture. The uncertainty is that technological progress in competing categories could shift purchase criteria faster than product cycles can adapt, especially if HDR, color accuracy, and energy performance continue to improve across technologies.
A third trend is the growing importance of regional cost and compliance strategy. Tariff exposure, raw material volatility, labor intensity, and safety standards will continue to shape where and how P1.29 products are sourced, assembled, certified, and delivered. Companies that design regional flexibility into their supply and distribution models are more likely to maintain pricing stability and market access across jurisdictions. The opportunity is to build repeatable compliance and sourcing frameworks that reduce surprise costs and accelerate project execution. The risk is that trade and input cost conditions may shift in ways that disrupt assumptions built into pricing, margin planning, and regional roadmaps, especially for firms with concentrated sourcing exposure.
LED Display Market
These trends point to a market where durable advantage will come from consistency, integration, and adaptive sourcing rather than from short-lived specification leadership alone.
Actionable Guidance for Decision Makers
For manufacturers, the strategic priority is to strengthen the full product and delivery chain behind the P1.29 specification. That means investing in yield, process consistency, driver and module design, safety and compliance readiness, and supply relationships that reduce exposure to long lead times and cost volatility. Product differentiation should be tied to application outcomes, whether that is superior HDR behavior for home theater, reliable brightness uniformity for luxury interiors, or modular installation advantages for premium indoor projects. Firms that can demonstrate dependable production performance and installation confidence will be better positioned to defend pricing and win premium projects even when competition intensifies.
For investors, the emphasis should be on capability depth rather than headline unit growth alone. Organizations with strong integration strategies, credible compliance management, resilient sourcing, and clear differentiation in targeted applications are more likely to sustain margins and market access. It is equally important to assess exposure to tariff-gated cost structures and raw material volatility, since these factors can influence not only profitability but also the competitiveness of specific geographies and channel models. The most attractive opportunities are likely to be found where technology positioning, service reliability, and regional strategy reinforce one another.
For procurement and channel decision makers, the priority is to evaluate P1.29 offerings on total project value rather than panel-level specifications alone. This includes assessing certification and safety readiness for residential use, installation support, component availability, delivery reliability, and the expected lifecycle of processing and driver performance. Preference should tilt toward suppliers that can reduce integration risk and provide predictable outcomes, particularly in high-value residential projects where installation quality and long-term performance are as important as initial image quality. Clear visibility into sourcing, compliance, and support expectations will help reduce downstream disruption.
PW Consulting
The premium household P1.29 LED display market is moving from early adoption to structured competition, and the pace of change in integration, cost exposure, and application targeting makes detailed intelligence increasingly valuable. For decision makers who need granular segment data, regional cost modeling, competitive benchmarking, and scenario analysis across the 2026 to 2032 horizon, the full PW Consulting research report provides deeper segmentation detail, company-level context, and tailored strategic recommendations to support board-level planning and investment decisions.
For detailed analysis of this topic, please visit the official page: High-end Household P1.29 LED Display Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com