

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
HFC Refrigerant Market: Inside the 6.25% CAGR Trajectory to $8.45B

Strategic Trends and Commercial Opportunities in the HFC Refrigerant Market
The hydrofluorocarbon (HFC) refrigerant market is entering a period of complex transformation, driven by tightening regulatory frameworks, evolving technological standards, and shifts in global demand patterns. As of 2025, the market operates with a revenue baseline of approximately USD 5.65 billion, having grown from around USD 3.8 billion in 2020 at a compound annual growth rate of 6.25 percent through the forecast horizon extending to 2032. This trajectory reflects a sector that continues to expand in absolute terms, even as it faces structural pressures that will reshape how refrigerants are produced, allocated, and consumed. The market is not shrinking; it is recalibrating. Understanding the mechanics of that recalibration is essential for executives, investors, and procurement leaders who must align their operations with the next phase of industry evolution.
PW Consulting
The concentration of market activity among a small group of established players underscores the capital-intensive and technically specialized nature of refrigerant production. The top three participants command roughly 78.5 percent of market revenue, while the top five collectively account for approximately 95 percent. This level of concentration suggests that access to compliant production capacity, regulatory expertise, and established distribution channels remains a significant barrier. It also indicates that pricing power, product diversification, and strategic partnerships will likely play an outsized role in determining which organizations can sustain growth as the regulatory landscape tightens and raw material dynamics fluctuate.
Market Sizing and Trajectory Context
From a macroeconomic perspective, the HFC refrigerant market has demonstrated consistent expansion over the past half-decade, with revenue moving from 3.8 billion in 2020 to 5.65 billion in 2025. Projections for the coming years indicate continued growth, with revenue expected to reach 6.26 billion in 2026, 6.55 billion in 2027, and 6.76 billion in 2028. The trajectory accelerates modestly through the end of the decade, reaching 7.23 billion in 2029, 7.57 billion in 2030, 7.95 billion in 2031, and 8.45 billion in 2032. A 6.25 percent compound annual growth rate across the 2026 to 2032 forecast period signals that demand will remain resilient, particularly in cooling-intensive applications, even as regulatory mechanisms systematically reduce the availability of high-global-warming-potential compounds.
Worldwide Freon Refrigerant Market
This growth pattern should not be interpreted as a simple continuation of past trends. The composition of demand is shifting, the cost structure of production is becoming more volatile, and regulatory compliance is adding new layers of operational complexity. Organizations that treat the market as a static volume play risk misallocating capital and missing the strategic inflection points that will define competitive positioning over the next several years.
Core Challenges and Inflection Points
Three structural challenges are converging to create a pivotal moment for the HFC refrigerant sector. The first is the regulatory mandate to reduce production and consumption of high-GWP HFCs. Under the AIM Act framework, an 85 percent reduction in production and consumption is required by 2036, with application-specific allowances renewed through 2030 and reporting requirements for 2025 data due by March 31, 2026. This phasedown schedule forces manufacturers, equipment builders, and end users to plan around a shrinking pool of conventional refrigerants, while simultaneously managing transition timelines for alternative formulations.
The second challenge lies in the tightening of operational compliance at the equipment level. Effective January 1, 2026, EPA Subsection H rules require leak inspection and repair protocols for HFC systems containing 15 pounds or more of refrigerant, with GWP limits of 300 for systems over 200 pounds. The EPA HFC Leak Repair and Management Rule (Subsection H) came into effect in January 2026, imposing leak detection and repair requirements on HFC-containing appliances meeting the threshold. This rule changes the economics of refrigerant use by increasing maintenance obligations, raising the cost of compliance, and making leak prevention a material factor in total cost of ownership.
The third challenge is the volatility and upward pressure in raw material costs. Chinese hydrofluoric acid prices rose with an annual average increase of 12.52 percent in 2025, supported by stable costs and peak-season refrigerant demand. HFC refrigerant spot market prices remained firm at elevated levels in April 2026 amid subdued trading activity. These cost dynamics compress margins for producers and increase procurement risk for buyers, particularly when combined with supply chain strains that have already triggered significant price adjustments in specific product lines. A notable example occurred in April 2025, when a leading manufacturer announced a 42 percent price increase on R-454B refrigerant cylinders due to supply chain strains and regulatory transitions. This type of pricing movement illustrates how regulatory transition pressure and logistics constraints can combine to create abrupt cost shocks for end users.
Key Drivers of Market Change
The trajectory of the HFC refrigerant market is being shaped by a tightly interconnected set of drivers that span technology, regulation, demand behavior, and supply chain economics. Understanding these drivers in isolation is insufficient; their interaction is what determines where value will be created and where risk will accumulate.
Technological Innovation and Formulation Shifts
The push toward lower-GWP formulations has accelerated the development and commercialization of refrigerant blends and alternative chemistries that can operate within existing or slightly modified equipment architectures. Manufacturers are increasingly focused on HFC-32 blends, R-454B, and other intermediate-GWP options that offer a pragmatic balance between performance, safety, and regulatory compliance. One recent example of this dynamic is the May 2025 commercial arrangement between Arkema and Honeywell, which strengthened Arkema’s range of lower-GWP refrigerants through expanded access to HFO blends for HVACR applications while supporting the HFC phasedown. This type of portfolio expansion allows equipment manufacturers and service providers to access compliant alternatives without waiting for entirely new production ecosystems to mature.
From a strategic standpoint, the innovation frontier is not solely about replacing one molecule with another. It is about building product portfolios that can adapt to regional regulatory variation, application-specific performance requirements, and evolving safety classifications. Companies that can offer a graduated pathway—from current HFCs to lower-GWP blends and ultimately to next-generation alternatives—will be better positioned to retain customer relationships across multiple transition cycles.
Policy and Regulatory Environment
Regulatory pressure is the single most consequential driver in the current market cycle. The combination of an 85 percent phasedown target by 2036, application-specific allowance renewals through 2030, and the new leak detection and repair obligations creates a multi-layered compliance environment. The EPA’s proposed rule to address stranded high-GWP HFC inventory extends compliance deadlines, with effects on food retail refrigeration equipment use extended to 2032. This extension provides temporary relief for certain end-use sectors, but it also prolongs the coexistence of legacy and transitional refrigerants, complicating procurement planning and inventory management.
For industry participants, regulation is no longer a distant compliance issue. It is an active determinant of pricing, availability, and product design. Reporting obligations for 2025 data due by March 31, 2026 add a transparency layer that increases visibility into production and consumption patterns, which in turn can influence allowance allocation and market expectations. Organizations that integrate regulatory tracking into their strategic planning will be better equipped to anticipate allowance constraints, adjust product roadmaps, and avoid reactive procurement decisions.
Demand-Side Shifts in Consumer and Enterprise Behavior
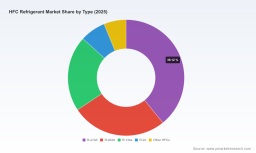
Demand for cooling and refrigeration continues to grow, driven by rising ambient temperatures, expanded cold-chain requirements, and the electrification of heating and cooling in both residential and commercial segments. Air conditioning remains the largest application category, followed by refrigeration and a smaller share of other applications. This demand base provides a structural floor for refrigerant consumption, even as the mix of refrigerants used shifts toward lower-GWP options.
At the same time, end users are becoming more sensitive to total cost of ownership, including maintenance, leak management, and regulatory compliance. The new leak inspection and repair protocols for systems with 15 pounds or more of refrigerant make it more expensive to operate high-GWP systems without rigorous maintenance discipline. As a result, equipment buyers and facility operators are increasingly weighing refrigerant choice against serviceability, downtime risk, and long-term compliance exposure. This behavioral shift favors suppliers and equipment manufacturers that can demonstrate reliable performance, clear compliance pathways, and lower-risk operating profiles.
Supply Chain and Cost Structure Dynamics
Cost pressures are being amplified by raw material movements and logistics constraints. The 12.52 percent annual average increase in Chinese hydrofluoric acid prices in 2025 reflects a broader environment where key inputs are subject to seasonal demand spikes and cost stability on the upstream side, while downstream demand remains strong. At the same time, HFC refrigerant spot market prices held firm at elevated levels in April 2026 despite subdued trading activity, indicating that pricing is being supported by structural factors rather than short-term speculation.
Supply chain strains have also manifested in sharp price increases for specific transitional refrigerants. The 42 percent price increase on R-454B cylinders announced in April 2025 highlights how regulatory transition demand, combined with constrained supply and logistics friction, can produce rapid cost escalation. For procurement teams, this underscores the importance of forward visibility into allowance allocations, production capacity, and regional price dynamics. For producers, it reinforces the value of diversified feedstock strategies, flexible manufacturing footprints, and stronger customer contracting approaches that can buffer against short-term volatility.
Competitive Landscape and Leading Strategies
The HFC refrigerant market is dominated by a concentrated group of global chemical and industrial companies, complemented by a set of equipment-focused and specialty producers that play important roles in specific channels. The strategic positioning of these players reveals a landscape where portfolio breadth, regulatory agility, and partnership networks are becoming as important as raw production capacity.
Worldwide Refrigerant Cylinder Market
Strategic Positioning of Core Players
Honeywell International Inc., based in Charlotte, North Carolina, is a leading producer of HFC refrigerants through its Solstice line and HFC-32 blends for HVAC and refrigeration systems. Its strategic emphasis on lower-GWP formulations and blend technology positions it as a bridge supplier during the transition from legacy HFCs to next-generation options. The company’s April 2025 price adjustment on R-454B cylinders reflects both the realities of supply chain strain and the pricing leverage that can emerge when compliant transitional products are in high demand.
The Chemours Company, headquartered in Wilmington, Delaware, is a major supplier of HFC refrigerants under its Freon and Opteon brands, with a clear focus on R-410A alternatives and blends. Chemours’ brand heritage and broad distribution relationships give it significant visibility across multiple end markets, while its blend-oriented portfolio supports customers seeking compliance pathways that can be implemented with relatively modest equipment modifications.
Arkema S.A., based in Colombes, France, provides HFC-32 and low-GWP HFC refrigerants for commercial and industrial refrigeration applications. Its May 2025 commercial arrangement with Honeywell demonstrates a strategy of expanding access to HFO blends and lower-GWP options without requiring full vertical integration of every technology pathway. This partnership model allows Arkema to widen its offering while participating in the broader phasedown trajectory.
Daikin Industries Ltd., headquartered in Osaka, Japan, is both a manufacturer and supplier of HFC refrigerants, including R-32 and R-454B for air conditioning and heat pump systems. Daikin’s vertical integration across equipment and refrigerant supply gives it a distinctive ability to align refrigerant development with system design, which can reduce transition friction for customers and create a more controlled path to compliance.
Carrier Corporation, based in Palm Beach Gardens, Florida, produces and distributes HFC refrigerants and refrigerant-containing HVAC equipment systems. Its equipment-centric orientation means that refrigerant strategy is tightly linked to product roadmaps, service networks, and customer migration plans. Trane Technologies plc, located in Davidson, North Carolina, supplies HFC refrigerants for commercial refrigeration and HVAC systems, with a similar emphasis on application-specific solutions and service compatibility.
Iofina Chemical, based in Maryland, remains an active producer of HFC refrigerants under EPA production for export allowances, reflecting the continued importance of trade dynamics and regulatory allowances in shaping global supply. Linde plc, headquartered in Wicklow, Ireland, supplies HFC refrigerants and related industrial gases for refrigeration and HVAC applications, leveraging its broader industrial gas infrastructure to support integrated supply and logistics across multiple end-use channels.
Market Structure Evolution
The market is likely to continue evolving along three tracks. First, consolidation pressure will persist among producers with undifferentiated assets or limited access to compliant portfolios, while companies with strong blend technology, regulatory expertise, and global distribution will be better positioned to capture share. Second, differentiation will increasingly center on transition readiness: the ability to supply intermediate-GWP blends, support leak management compliance, and provide application-specific guidance will become more valuable than commodity volume alone. Third, new entry will remain challenging due to concentration, capital intensity, and regulatory complexity, but selective partnerships, licensing arrangements, and regional niche plays can still create meaningful footholds.
In this environment, competitive advantage will depend less on asserting scale for its own sake and more on demonstrating the ability to navigate phasedown schedules, manage input cost volatility, and deliver reliable compliance pathways. The companies that can combine product flexibility with regulatory foresight and supply chain resilience will be the ones that shape the next phase of market development.
Future Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to define the market’s evolution and create distinct commercial opportunities for organizations that respond proactively.
Trend 1: Accelerated Migration to Intermediate and Lower-GWP Blends
The combination of phasedown targets, allowance constraints, and leak management requirements will drive a faster shift toward intermediate-GWP blends and lower-GWP alternatives in both air conditioning and refrigeration. This migration will create opportunities for suppliers that can offer clear formulation pathways, consistent quality, and application-specific support. It will also create opportunities for equipment manufacturers that align product lines with compliant refrigerants and simplify the transition for end users. The commercial value here lies in reducing transition risk: customers will pay a premium for clarity, reliability, and a credible path through the regulatory timeline.
Trend 2: Compliance-Driven Service and Lifecycle Value
The EPA Subsection H leak detection and repair requirements, together with GWP limits for larger systems, will make maintenance and leak prevention central to the economics of refrigerant use. This shifts the competitive focus from initial product price to lifecycle performance, service quality, and compliance assurance. Providers that integrate refrigerant supply with leak management guidance, inspection protocols, and repair support can capture additional value while helping customers avoid regulatory exposure. Over time, this may lead to more bundled offerings that combine refrigerant, equipment, and service components into a single compliance-oriented solution.
Trend 3: Regional Divergence and Strategic Sourcing
Regulatory timelines, allowance structures, and raw material dynamics will not move uniformly across regions. Asia Pacific is expected to continue representing a substantial share of market revenue, while North America and Europe will be shaped by their own phasedown schedules and compliance frameworks. Latin America and the Middle East and Africa will remain smaller but potentially fast-moving in specific application segments. This regional divergence will reward organizations that can tailor sourcing, product mix, and compliance strategy to local conditions rather than applying a single global template. Strategic sourcing relationships, allowance-aware procurement, and region-specific product planning will become important differentiators.
Risks and Uncertainties
Several uncertainties could alter this trajectory. If regulatory timelines are adjusted further, or if allowance allocation mechanisms create unexpected shortages, price volatility could intensify and disrupt procurement plans. If raw material costs continue to rise, margins may be squeezed and end-user adoption of transitional products could slow in price-sensitive segments. If leak management compliance proves more costly or operationally complex than anticipated, some customers may delay transitions or seek alternative solutions that reduce exposure. Finally, the coexistence of legacy, transitional, and next-generation refrigerants could create fragmentation in service practices and supply chains, increasing complexity for multi-site operators and distributors.
Strategic Recommendations for Decision Makers
For manufacturers, the priority should be to build transition-ready portfolios that span current HFCs, intermediate blends, and lower-GWP options, while investing in regulatory tracking and compliance support capabilities. Product roadmaps should be aligned not just with technology development but with phasedown schedules, application-specific rules, and leak management obligations. Supply chain resilience should be strengthened through feedstock diversification, flexible production planning, and forward visibility into allowance and export dynamics.
For investors, the market offers exposure to a sector that is growing in absolute terms but undergoing significant structural change. The most compelling opportunities are likely to be found in companies with differentiated blend technology, strong compliance orientation, and the ability to serve high-value applications with lower transition risk. Due diligence should focus on regulatory exposure, allowance dependency, raw material sensitivity, and the strength of customer relationships in segments where compliance and service quality matter most.
For procurement and supply chain leaders, the most important action is to move from reactive purchasing to forward-looking planning. This means mapping refrigerant needs against phasedown timelines, understanding leak management obligations for relevant systems, and building sourcing strategies that account for regional price divergence and supply constraints. Long-term agreements, diversified supplier bases, and early engagement with compliance requirements can reduce exposure to sudden price shocks and availability gaps.
As the HFC refrigerant market continues to evolve, the organizations that succeed will be those that treat regulatory change, cost dynamics, and technology transition as interconnected strategic variables rather than isolated operational issues. For decision makers seeking a more granular view of segmentation dynamics, regional variations, and customized scenario planning, the full research report provides deeper data and tailored analysis to support implementation.
For detailed analysis of this topic, please visit the official page: HFC Refrigerant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com