

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Paint Remover Market: 5.6% CAGR Trajectory and Solvent Bio Shifts

Paint Remover Market: Strategic Shifts, Regulatory Headwinds, and the Bio-Based Transition
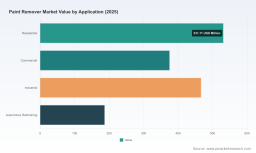
The global paint remover market has moved past a period of incremental growth and entered a phase of structural transformation. Valued at approximately $1.56 billion in 2025 and projected to reach $2.29 billion by 2032, the market is expanding at a compound annual growth rate of 5.6 percent from 2020 through 2032. This trajectory reflects more than steady demand for surface preparation solutions. It signals a fundamental recalibration of product chemistry, regulatory compliance requirements, and end-user expectations across residential, commercial, industrial, and automotive refinishing channels. For executives and investors evaluating chemical specialties and maintenance markets, the paint remover segment offers a clear case study in how environmental regulation and innovation intersect to reshape competitive advantage.
The market remains moderately concentrated, with the top three firms accounting for roughly 42.5 percent of revenue and the top five capturing approximately 52.1 percent. This concentration suggests that established names retain significant shelf presence and distribution leverage, yet it also leaves meaningful room for differentiated entrants that can solve persistent performance and compliance pain points. The growth profile from 2026 onward indicates that demand will not be evenly distributed across product categories or end-use segments. Instead, value will accrue to formulations that reconcile removal effectiveness with worker safety, environmental stewardship, and application convenience.
Current Market Conditions and Critical Inflection Points
The paint remover industry is operating at the intersection of three converging pressures. First, legacy solvent chemistries face mounting regulatory and reputational constraints, forcing both consumer and industrial buyers to rethink procurement standards. Second, reformulation costs and supply-chain complexity are raising per-unit economics for compliant alternatives, which compresses margins for firms slow to adapt their manufacturing footprints. Third, end-users increasingly expect products that perform reliably on vertical surfaces, detailed trim, and mixed substrates without sacrificing usability or indoor air quality. These forces are not separate issues; they reinforce one another and define the strategic agenda for the next cycle.
A clear inflection point is the post-ban operating environment for methylene chloride and related restricted solvents. The U.S. Environmental Protection Agency finalized a ban on most uses of methylene chloride in April 2024, with consumer sales already prohibited since 2019 and remaining industrial uses subject to strict workplace protections. In Europe, REACH restrictions have limited dichloromethane concentrations in consumer paint strippers across member states since 2010, with full implementation completed in 2012. California has gone further by classifying paint strippers containing methylene chloride as a Priority Product, requiring evaluation of safer alternatives for both consumer and commercial channels. These measures have shifted the center of gravity in product design from performance-only optimization to performance-plus-compliance.
A second inflection point lies in the economics of reformulation. Moving away from methylene chloride and N-methyl-2-pyrrolidone is accelerating adoption of acetone, dimethyl carbonate, and water-based systems that trade off higher per-gallon costs for regulatory certainty and safer handling profiles. For manufacturers, this means that compliance is no longer a checkbox but a cost-structure decision with direct implications for pricing, channel strategy, and margin defense. For buyers, it means that total cost of use now includes exposure management, disposal considerations, and training burden, not just purchase price.
Core Drivers Reshaping Demand and Competitive Advantage
Technology and formulation innovation are the most visible drivers of change. The market is seeing a steady shift toward bio-based and lower-toxicity solvent systems that maintain stripping efficacy while reducing environmental and occupational risk. Recent product launches illustrate how companies are translating regulatory pressure into commercial opportunity. In March 2026, Cortec Corporation introduced EcoLine Surface Reveal with 77 percent USDA-certified biobased content and biodegradable ingredients, formulated without methylene chloride or NMP for metal surface cleaning. In the same month, Rust-Oleum Corporation released a gel-based paint remover designed for vertical surfaces and intricate detailing in home renovations. By April 2026, 3M Company launched a next-generation solvent-based paint remover with a low-odor, biodegradable formula. These launches are not isolated product updates; they reflect a broader pattern in which formulators are building differentiation on biobased content, application geometry, and odor and disposal profiles.
PW Consulting
Policy and regulatory environment is the second core driver. Beyond the bans and concentration limits already in force, the direction of travel is toward tighter workplace protections, greater ingredient disclosure, and increased scrutiny of safer alternative assessment. The EU’s earlier REACH framework set a long-standing precedent for limiting hazardous solvents in consumer products, while U.S. federal and state actions have added friction to legacy chemistries and incentivized reformulation. For global suppliers, regulatory divergence between regions creates both complexity and opportunity: products that satisfy stringent U.S. and European standards can command premium positioning in channels where compliance is a purchasing criterion, while also future-proofing portfolios against further restrictions.
Demand-side behavior is changing in ways that reward usability and transparency. In residential renovation, buyers and professional contractors alike prefer gel and targeted formulations that cling to vertical surfaces, control runoff, and simplify cleanup. In industrial and maintenance contexts, surface preparation teams are increasingly weighing total application time, safety training requirements, and waste handling against raw removal speed. Rising demand for biobased alternatives is also increasing supply-chain transparency expectations among home-improvement buyers, who want clearer information about ingredient origins and environmental claims. This shift in procurement mindset is pushing manufacturers to communicate performance and sustainability attributes with greater precision.
Supply-chain and cost-structure changes form the fourth driver. Reformulation away from restricted solvents is raising per-gallon costs by an estimated 20 to 30 percent for certain alternative systems, which reshapes the economics of production and distribution. At the same time, rising interest in biobased inputs is pressuring suppliers to improve traceability, certify content claims, and manage feedstock variability. Firms that can secure reliable access to alternative solvents, optimize process efficiency, and align packaging and application design with end-user workflows are better positioned to absorb cost increases without losing competitiveness. Those that treat reformulation as a one-time compliance exercise risk ceding ground to rivals who embed safer chemistry into a broader value proposition.
Competitive Landscape and Strategic Positioning
The competitive set spans established chemical and coatings players, specialty formulators, and regional suppliers serving professional and consumer channels. Cortecx Corporation and 3M Company illustrate how large innovators are leveraging R&D capacity to introduce biodegradable and low-odor solvent systems that align with shifting regulatory and user expectations. The Sherwin-Williams Company and Rust-Oleum Corporation continue to strengthen retail-facing gel products tailored to vertical surfaces and detailed renovation work, where ease of application directly influences purchase decisions. Henkel AG & Co. KGaA has doubled down on sustainable, non-toxic stripping technologies, including an R&D facility expansion in Germany in March 2025 aimed at developing solutions compliant with EU chemical safety directives. PPG Industries, WM Barr & Co., Dumond Chemicals, Sunnyside Corporation, and Twin Specialties, Inc. each occupy distinct niches, from consumer-friendly citrus and fast-acting options to professional-grade stripping for maintenance and repair markets.
The strategic positioning that separates leaders from followers is increasingly built on three elements. The first is chemistry differentiation that does more than remove paint. Biobased content, absence of methylene chloride and NMP, low odor, and biodegradable profiles are becoming selling points in channels where safety and environmental claims influence repeat purchase. The second is application engineering. Gel formulations, controlled viscosity, and surface-specific guides reduce misuse, improve outcomes on vertical and detailed surfaces, and lower the perceived effort of the job. The third is compliance storytelling and transparency. Suppliers that can demonstrate ingredient safety, certification where relevant, and practical handling benefits are better equipped to navigate regulated procurement and to justify price premiums in a market where reformulation costs are rising.
Market structure is evolving along two parallel paths. Consolidation pressure exists where scale in distribution, brand recognition, and R&D budgets create barriers for smaller generic players. At the same time, differentiation and fragmentation are evident in the number of niche launches targeting specific substrates, surface geometries, and compliance requirements. New entrants and smaller specialists can still win by solving a narrow but valuable problem well: a gel for vertical renovation work, a biobased metal-cleaning stripper, or a fast-acting consumer option with a clear safety narrative. The broader trend is toward a market where incumbents defend share through portfolio breadth and compliance leadership, while challengers gain traction with focused formulation and application advantages.
Worldwide Oil Stain Remover Market
Strategic Outlook: Three Trends to Watch Over the Next Three to Five Years
The first trend is accelerating adoption of bio-based and low-toxicity chemistries as the default expectation in consumer and many professional channels. As regulatory restrictions on legacy solvents continue to bite and buyers become more familiar with safer alternatives, products that combine effective removal with biobased content, low odor, and biodegradable attributes will capture a growing share of new adoption. The commercial opportunity lies in designing complete value propositions around these attributes, including packaging, instructional support, and claims that withstand scrutiny. The risk is overclaiming or inconsistent performance, which can erode trust quickly in a category where results are immediately visible to the end-user.
The second trend is application-specific innovation becoming a central battleground. Vertical surfaces, intricate detailing, mixed substrates, and metal cleaning each impose different requirements on viscosity, dwell time, rinsing, and waste handling. Companies that tailor formulations and application guides to these scenarios can command stronger loyalty and reduce the likelihood of product substitution. For industrial and maintenance buyers, the opportunity is to reduce total cycle time and exposure risk; for consumer channels, the opportunity is to simplify the job and improve perceived ease of use. The uncertainty here is that over-specialization can fragment production and inflate inventory complexity, so firms need to balance segment focus with manufacturing efficiency.
The third trend is the widening gap between firms that treat compliance as a cost center and those that treat it as a design parameter. Reformulation cost pressure, estimated at 20 to 30 percent higher per gallon for certain alternative systems, will not disappear. The winners will be those that integrate safer chemistry into product architecture, supply-chain planning, and channel messaging from the outset, rather than retrofitting after regulatory events. There is real upside in using compliance leadership to access regulated procurement and to build brand trust, but there is also exposure if ingredient claims, supply continuity, or performance consistency do not hold up under real-world use. Additionally, regional regulatory divergence means that global portfolios must be designed with modularity and local adaptation in mind, not just a single global formula.
Actionable Recommendations for Decision-Makers
For manufacturers and formulators, the priority is to align product development with the dual demands of performance and compliance. Investment should focus on biobased and low-toxicity solvent systems that can demonstrate reliable removal on target substrates, along with application formats such as gels and targeted formulas that reduce misuse and improve outcomes on vertical and detailed surfaces. Equally important is supply-chain readiness: securing feedstock for alternative solvents, validating ingredient claims, and building manufacturing flexibility to manage cost variability. Firms should also strengthen instructional content and safety resources, because in a category where handling and disposal matter, guidance is part of the product experience.
Worldwide Photoresist Remover Market
For investors, the appeal of the paint remover market lies in its shift from commodity-like competition to value-driven differentiation. Due diligence should weigh formulation capability, regulatory responsiveness, and the credibility of sustainability claims more heavily than historical revenue alone. Companies with credible biobased or low-toxicity portfolios, clear application advantages, and disciplined cost management are better positioned to defend margins in a higher-cost reformulation environment. At the same time, investors should monitor exposure to regional regulatory divergence and the risk that overconcentration in any single chemistry could become a liability if standards tighten further.
For procurement and channel leaders, the strategic task is to evaluate total cost of use rather than list price. Safer, application-specific formulations may carry higher unit costs but can reduce training burden, exposure management, and waste handling, while improving consistency on difficult surfaces. Procurement criteria should include ingredient safety, compatibility with target substrates, and the quality of application guidance and support resources. Building relationships with suppliers that can demonstrate compliance leadership and transparent ingredient information will reduce downstream risk and improve purchasing confidence in regulated environments.
Understanding where the market is heading requires more than headline growth figures. The interplay of formulation innovation, regulatory pressure, application specificity, and cost structure is reshaping how value is created and captured in this category. For teams that need granular segmentation data, regional demand patterns, competitive share estimates, and tailored commercial scenarios, the full PW Consulting study provides the detailed breakdown and working assumptions behind these trends. It is designed to support product roadmap decisions, investment screening, and procurement strategy with the level of specificity that general market narratives cannot provide.
For detailed analysis of this topic, please visit the official page: Paint Remover Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com