

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Steam Dryer Market 2026: How Asia Pacific's 5.9% CAGR Reshapes Global Growth

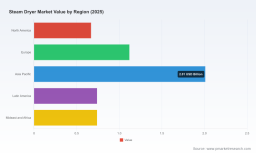
Steam Dryer Market: Strategic Trends and Commercial Opportunities Through 2032
The steam dryer market has entered a phase of measured expansion, with global revenue projected to grow from approximately $5.28 billion in 2025 to $7.19 billion by 2032, reflecting a compound annual growth rate of 5.9 percent. This trajectory is neither explosive nor stagnant; it signals a maturing industrial ecosystem where capital discipline, energy economics, and process innovation intersect. For executives and investors evaluating exposure to thermal processing equipment, the market offers steady returns but demands sharper segmentation, regional nuance, and a clear view of where competitive advantage is being rebuilt.
Underlying the headline numbers is a sector shaped by continuous drying demands across food, chemical, pharmaceutical, and bulk material applications. The revenue base has expanded consistently over the past five years, yet growth rates vary by geography, equipment type, and end-use segment. What matters now is not simply that the market is growing, but how the growth is being distributed and what structural forces are reallocating value among participants.
PW Consulting
Market Landscape and Core Challenges
At a macro level, the steam dryer market is characterized by moderate consolidation and a wide dispersion of equipment formats. The top three players account for roughly 47 percent of revenue, while the top five capture just over half. This concentration indicates a competitive environment where scale, application coverage, and service integration matter, but it also leaves substantial room for specialized suppliers and regional challengers to compete on customization, lead times, and local support.
One of the most pressing challenges is the tension between operational efficiency and input cost volatility. Industrial dryer manufacturing relies heavily on steel-intensive components, and hot rolled coil prices for dryer components hovered in the $904 to $940 per ton range in March 2025, with upward pressure linked to demand and raw material costs. Even as operators seek energy-efficient drying solutions, OEMs face margin compression if they cannot pass through material costs without sacrificing order momentum. This dynamic is reshaping pricing strategies, contract structures, and the economics of customization versus standardization.
Food Dryer Market
A second challenge lies in the skilled labor constraint affecting specialized engineering and assembly roles. Complex steam drying systems require precision fabrication, integrated controls, and commissioning expertise. Persistent shortages in these functions extend lead times and raise execution risk, particularly for large-scale or custom installations. For buyers, this translates into longer project cycles and greater dependency on supplier capacity; for manufacturers, it raises the stakes around workforce planning, modular design, and remote support capabilities.
A third inflection point is arriving through regulatory and standards-driven change. In the United States, federal energy efficiency standards for consumer clothes dryers now incorporate performance measures under Appendix D1, with updates effective after 2024. While this change primarily affects consumer equipment, it reflects a broader policy momentum around energy performance, lifecycle efficiency, and verifiable process outcomes. Industrial steam dryer buyers are increasingly exposed to similar expectations through corporate sustainability targets, utility incentives, and procurement standards that reward demonstrable energy recovery and lower thermal waste.
The practical implication is that market growth alone does not guarantee profitable growth. Companies that succeed will be those that can align equipment design with total cost of ownership, manage input cost exposure, and navigate a landscape where efficiency expectations are rising faster than in prior cycles.
Key Drivers Reshaping the Market
Technology Innovation and Breakthroughs
The most strategically important driver is the shift toward higher-efficiency steam drying architectures. Leading OEMs are investing in next-generation steam dryer platforms featuring advanced heat exchanger geometries and self-cleaning tube bundles. These improvements are not incremental cosmetics; they directly affect throughput, maintenance frequency, and energy utilization in continuous drying processes. Self-cleaning designs reduce fouling-related downtime, while refined heat exchange surfaces improve heat transfer consistency across varying load conditions.
Superheated steam drying is another area gaining traction, particularly where moisture removal, product quality, and sterilization must be managed together. The interest in this approach is reinforced by collaborative research efforts, including Valmet Corporation’s participation in the SteamDry research project for superheated steam drying technology in the paper industry. Such initiatives signal a transition from standalone equipment sales toward system-level solutions where drying, heat recovery, and condensate management are integrated.
Perhaps the most visible endorsement of scale and engineering maturity is Tsukishima Kikai Co., Ltd.’s delivery of the largest steam tube dryer to date in November 2025. Large-format units matter because they expand the feasible envelope for high-throughput applications and can improve unit economics in volume-intensive processes. At the same time, they raise the bar for installation logistics, structural support, and after-sales service, reinforcing the differentiation between suppliers that can execute complex projects and those positioned for smaller, more standardized orders.
For decision-makers, the message is clear: technology competition is moving from basic drying capability to integrated performance, reliability, and energy recovery. Procurement teams should evaluate not only drying capacity but also downtime sensitivity, cleaning cycles, and the extent to which steam condensate and waste heat can be recovered within the broader plantutility system.
Policy and Regulatory Environment
Policy dynamics are becoming a more explicit factor in demand patterns and vendor selection. Energy-related standards and efficiency expectations are no longer confined to consumer appliances; they are increasingly shaping procurement criteria in industrial contexts as well. In practical terms, buyers are looking for equipment that supports measurable efficiency gains, whether through reduced steam consumption, improved heat recovery, or process designs that lower the carbon intensity of drying operations.
At the same time, regulatory scrutiny can create both compliance burdens and differentiation opportunities. Suppliers that can document performance, provide transparent energy metrics, and align with regional standards are better positioned in tenders where efficiency is a scoring criterion. This is especially relevant in sectors such as food and pharmaceuticals, where process integrity and hygiene add further layers of specification. The regulatory environment is therefore not simply a constraint; it is a filter that rewards suppliers with robust technical documentation, application-specific validation, and lifecycle thinking.
Demand-Side Shifts in Consumer and Business Behavior
Demand is being shaped by broader industrial priorities rather than by a single sectoral surge. Food processing continues to be a major application area, driven by the need for consistent drying, shelf-life management, and scale. Chemical applications remain significant where thermal separation and moisture control are core to product specifications. Pharmaceutical and related sterile-processing environments contribute demand where drying must align with contamination control and process asepsis.
What ties these segments together is a growing emphasis on reliability and operating cost over pure purchase price. In many industrial settings, the economic case for a steam dryer is increasingly evaluated across energy consumption, maintenance intervals, cleaning requirements, and integration with existing steam and condensate systems. This is pushing buyers toward suppliers that can offer application engineering, commissioning support, and measurable performance guarantees.
Demand is also being influenced by regional industrialization patterns and the location of processing capacity. As production footprints adjust in response to logistics, labor, and market access, new drying capacity is being planned in diverse geographies. This does not automatically translate into uniform growth, but it does suggest that local service capability, parts availability, and application knowledge are becoming more valuable than in an era when equipment purchases were more centralized.
Supply Chain and Cost Structure Dynamics
The cost structure of steam dryer manufacturing is being tested by material price movement and labor availability. Steel-based components remain a core cost driver, and the recent range in hot rolled coil prices points to continued exposure for fabrication-intensive equipment. In response, some manufacturers are exploring more standardized module designs, improved procurement hedging, and design choices that reduce weight or material intensity without compromising performance.
Steam Water Heater Market
Labor shortages in specialized engineering and assembly roles add another layer of complexity. Where skilled capacity is constrained, projects can face scheduling risk, and the value of repeatable designs and remote diagnostics increases. A supply chain that can deliver consistent quality, predictable lead times, and responsive field support is becoming a competitive asset in its own right. This is particularly important for large installations and for customers operating in regions where local technical support is limited.
For commercial strategy, these dynamics suggest that cost leadership alone is increasingly difficult to sustain unless it is paired with process efficiency and service reliability. Suppliers that can manage material exposure, streamline assembly, and reduce dependency on scarce specialized labor are better placed to protect margins while maintaining competitive pricing.
Competitive Landscape and Leading Strategies
The competitive field blends global engineering groups, application-focused specialists, and regional manufacturers with strong local presence. The strategic question is not simply who is largest, but where each participant derives defensible advantage and how that advantage is likely to translate into share over the next several years.
Andritz AG operates from a position of broad process integration, offering rotary steam tube dryers, fluidized bed systems, and superheated steam dryers for pulp, paper, food processing, biomass, and bulk chemicals. Its emphasis on high-throughput continuous drying and energy recovery positions it as a solution provider for large industrial flows rather than a narrow equipment vendor. The strategic advantage here is the ability to connect drying performance with upstream and downstream process needs, which can be compelling in complex installations where overall plant efficiency matters.
GEA Group AG brings strength in spray drying and heat recovery, including aseptic-oriented systems for pharmaceutical and food applications. Its focus on aseptic sterilization and energy efficiency in steam-based processes aligns well with demand in sectors where hygiene and process control carry high value. In competitive terms, this creates a clear niche where reliability, validation, and specialized servicing can support premium positioning.
Valmet Corporation specializes in pulp drying machines, airborne dryers, and steam recovery systems with high-capacity designs and integrated steam-condensate management. Its participation in research on superheated steam drying indicates a willingness to shape emerging process directions rather than merely respond to them. For paper and adjacent industrial drying contexts, that combination of capacity leadership and technology exploration can be a durable source of relevance.
Alfa Laval AB focuses on heat transfer and condensation through plate heat exchangers and vacuum dryers for food, dairy, and industrial applications. Its orientation toward energy-efficient steam recovery and condensation gives it a distinct angle in markets where thermal efficiency and compactness are priorities. Rather than competing purely on dryer size or throughput, Alfa Laval’s value proposition often centers on how effectively steam energy is managed within the system.
In the United States, Louisville Dryer Company and Williams, White & Company illustrate the continued importance of custom and application-tailored engineering. Louisville Dryer Company manufactures custom rotary steam tube dryers and ASME Division I certified systems for bulk materials and high-volume thermal processing. Williams, White & Company provides Davenport Dryers rotary steam tube dryers and water tube coolers for ethanol, biomass, food processing, and industrial bulk materials, with a long-term efficiency focus. These firms compete by serving specialized requirements, often where standard packages are insufficient and where engineering flexibility, certification, and service continuity matter.
Tsukishima Kikai Co., Ltd. stands out for large-scale steam tube dryer capability, including the largest units manufactured and supplied globally. Recent delivery of the largest steam tube dryer to date underscores its position in high-capacity applications and its ability to execute demanding projects. This scale advantage is most relevant where volume processing justifies large equipment footprints and where supplier execution capability is a decisive factor.
In parallel, region-specific players such as Jiangsu Chuandao Washing Machinery Technology Co., Ltd. in China and Ace Industries in India illustrate how local manufacturing and application focus can support growth in laundry, commercial processing, and batch-oriented pharmaceutical, food, and chemical applications. Their relevance often lies in responsiveness, cost-appropriate engineering, and proximity to local end-users, rather than in competing directly on global scale.
The broader pattern is one of differentiation rather than uniform convergence. Some suppliers compete on integration and large continuous processes, others on hygiene-sensitive applications, and others on customization and regional service. Market evolution is likely to remain fragmented at the application level while consolidating where scale, engineering intensity, and service networks create clear cost and performance advantages. New entry will probably be most viable where a supplier can address a specific application gap, offer a compelling efficiency story, or serve an underserved geography with credible local support.
Forward Outlook: Trends and Commercial Opportunities
Over the next three to five years, three trends are likely to shape the market's commercial center of gravity.
The first is the widening premium on efficiency-enabled drying systems. As energy costs, sustainability commitments, and procurement standards become more demanding, equipment that delivers better heat recovery, lower steam intensity, and reduced maintenance burden will gain preference. The opportunity lies not only in selling dryers, but in positioning drying as part of an integrated thermal management solution. Suppliers and buyers alike will benefit from clearer comparisons of total operating cost rather than upfront price alone.
The second trend is continued segmentation by application intensity. High-throughput continuous drying, hygiene-critical batch processing, and specialized bulk material handling will not compete on identical criteria. This creates room for targeted strategies: large-scale engineering for volume applications, aseptic and validated solutions for pharmaceutical and food uses, and flexible customized systems for niche industrial needs. Companies that align their product portfolios and service models to these distinct demand profiles are more likely to defend margins than those pursuing a one-size approach.
The third trend is the growing importance of execution capability. Large-scale equipment deliveries, complex installations, and specialized labor constraints will reward suppliers that can manage project risk, standardize where possible, and provide dependable field support. For buyers, this means that vendor selection should incorporate installation logistics, commissioning support, spare parts availability, and response time alongside technical specifications.
These trends also carry uncertainty. Material cost volatility can compress margins if pricing power is limited. Labor constraints may slow project execution and increase reliance on modular or more standardized designs. Regulatory expectations may shift faster in some regions than others, altering the relative attractiveness of efficiency-led investments. And while superheated steam and advanced heat exchange designs show promise, their adoption will depend on real-world validation, maintenance requirements, and the willingness of end-users to commit to new process configurations.
Even with these caveats, the commercial opportunity is tangible for players who treat efficiency, application fit, and service reliability as core competitive variables rather than supporting features.
Strategic Implications for Decision-Makers
The following actions are most relevant depending on the reader's role in the market.
For Manufacturers and Equipment Suppliers
Design strategies should increasingly balance customization with modular repeatability. Where specialized engineering is required, the cost of bespoke execution is rising, and suppliers that can standardize core subassemblies while retaining application flexibility will be better positioned to manage labor constraints and material exposure. Efficiency claims should be supported by verifiable performance metrics and integrated into the broader value proposition, including steam recovery, cleaning intervals, and downtime sensitivity.
Service and project execution are becoming strategic differentiators. The ability to deliver large or complex installations on schedule, provide local technical support, and maintain spare parts availability can matter as much as hardware specifications in competitive bids. Suppliers should also evaluate where partnerships, channel models, or regional assembly can reduce lead times and improve responsiveness.
For Investors and Corporate Development Teams
Investment judgment should focus on business models that can convert efficiency trends into recurring value. This may include suppliers with strong application engineering, service-intensive revenue streams, or exposure to sectors where hygiene, validation, and continuous processing command higher willingness to pay. Scale leaders with integration capabilities and specialized providers with defensible niches can both be attractive, but for different reasons and with different risk profiles.
It is also important to monitor where consolidation is likely to be driven by service networks and project execution rather than by product overlap alone. In a market where the top three hold roughly 47 percent and the top five just over half, there is still meaningful fragmentation, but share shifts will probably come from differentiation in application coverage, regional reach, and reliability rather than from price competition in commoditized segments.
For Procurement and Operations Leaders
Buying decisions should weigh total cost of ownership more heavily than initial equipment price. Key evaluation areas include steam consumption patterns, heat recovery potential, cleaning and fouling behavior, commissioning complexity, and the supplier's capacity to support the installation over time. For large or specialized projects, the execution track record of the supplier is especially important given ongoing labor and supply chain constraints.
Procurement teams should also consider how drying equipment interacts with plant-level steam and condensate systems. A dryer that performs well in isolation may underdeliver if it is not aligned with site utility infrastructure or if energy recovery opportunities are overlooked. In that sense, the most valuable purchases are those that reduce operating risk and improve integration, not merely those that meet a nominal capacity requirement.
Closing Perspective
The steam dryer market through 2032 is best understood as a steadily expanding but increasingly discriminating arena. Growth is real, but value creation will depend on how well participants navigate material costs, skilled labor limits, efficiency expectations, and application-specific demand. The leaders who stand out will be those that combine technical credibility with execution discipline and a clear view of where efficiency, reliability, and integration matter most to end-users.
For organizations that need a more granular view of segmentation dynamics, regional revenue distribution, and competitive positioning across specific end-use categories, the full PW Consulting report provides detailed breakdowns and tailored scenario analysis to support planning decisions.
For detailed analysis of this topic, please visit the official page: Steam Dryer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com