

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Laptop Bag Market 2026: What 5.9% CAGR and Regional Splits Reveal

Strategic Realities of the Laptop Bag Market: Navigating Growth, Fragmentation, and Technology-Driven Value
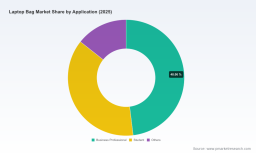
The laptop bag market has evolved far beyond a simple accessory category into a strategic intersection of mobility, security, and professional identity. With a global market valuation approaching $223 million in 2025 and a projected compound annual growth rate of 5.9 percent through 2032, the sector demonstrates consistent expansion, yet that headline growth masks significant structural shifts beneath the surface. Revenue dispersion across backpacks, messenger bags, briefcases, and other formats reveals a category in transition. The backpack segment commands the largest share of revenue, while briefcases and messenger bags continue to serve niche professional and hybrid work use cases. At the application level, business professionals and students represent the dominant demand pools, each pulling the market in different directions when it comes to durability, organization, and aesthetic expectations.
Understanding this market requires moving past aggregate numbers and examining the tension between steady demand growth and a landscape that is becoming more fragmented, more technologically demanding, and more sensitive to procurement dynamics. For executives, investors, and category managers, the laptop bag category is no longer just about carrying a device. It is about signaling competence, reducing risk, and integrating into broader workplace mobility strategies.
Market Landscape and Core Challenges
The laptop bag market's growth trajectory is built on a strong foundation of device proliferation and the enduring need for organized, protected mobility. From 2020 to 2025, revenue expanded steadily, reflecting a recovery from earlier pandemic-era discontinuities and a subsequent normalization of device-carrying habits across work, education, and travel. The forecast period through 2032 extends that momentum, though growth will not be uniform across segments or geographies. The top-line trajectory depends on how well manufacturers adapt to shifting form factors, sustainability expectations, and procurement rules that increasingly shape what gets bought and why.
Several structural challenges define the current market environment.
-
Category saturation and differentiation fatigue. As demand grows, the market has attracted a wide range of players, from global luggage and mobility brands to specialized accessory manufacturers and private-label suppliers. That breadth creates noise. Consumers and procurement teams are confronted with comparable-looking products that vary mostly in stitching, zipper quality, and minor padding differences. Without meaningful differentiation, price competition intensifies and margin structures compress.
-
Device format evolution and protection uncertainty. Laptop sizes and form factors are not static. Thinner chassis, heavier premium builds, and the continued co-existence of 13-inch to 17-inch screen sizes complicate compartment design. A bag that performs well for one generation of devices may feel misaligned with the next. This pushes manufacturers to design for flexibility rather than fixed dimensions, adding engineering complexity and testing costs.
-
Procurement rules and specification-driven purchasing. Institutional buying has become more specific. Public-sector and enterprise purchasing frameworks increasingly define acceptable materials, water resistance, and certification requirements, which narrows the pool of eligible products. This dynamic raises the barrier for generic offerings and rewards suppliers that can demonstrate compliance, traceability, and reliable product documentation.
These challenges do not negate growth, but they change the conditions under which growth is captured. The market rewards suppliers that can convert protection, compliance, and organization into defensible value rather than competing solely on appearance or brand recognition.
Key Demand Drivers Reshaping the Category
Several intersecting forces are shaping how the laptop bag market expands and where value is concentrated.
Technology Innovation and Protection Engineering
Protection has become a more sophisticated value proposition. The market is moving beyond generic padding toward engineered cushioning, impact distribution, and integrated organization systems that reduce movement and friction. RFID-blocking features, anti-theft design elements, and smarter compartment layouts are increasingly viewed as essential rather than premium extras, especially for business users who carry devices alongside credentials, payment cards, and sensitive documents.
This shift matters because protection is not just about preventing damage. It is about reducing anxiety during daily commuting, travel, and public-space use. The most relevant innovations are those that make protection feel seamless. A bag that protects effectively while remaining light, accessible, and professional in appearance can command stronger positioning than one that relies on bulky armor-like construction.
Demand-Side Behavior and Hybrid Work Realities
Work patterns continue to reshape product expectations. Hybrid and flexible work arrangements have made the laptop bag a daily transitional object, moving between home, office, co-working spaces, and client sites. That usage pattern increases the importance of versatility. Users want bags that support quick access, clean organization, and a professional look without sacrificing comfort during longer carry periods. Students, meanwhile, prioritize durability, storage flexibility, and affordability, which puts pressure on manufacturers to balance feature richness with accessible price points.
The result is a more demanding buyer profile. Consumers and institutions are not simply asking for a bag that fits a laptop. They are asking for a carry system that supports workflow, lowers risk, and remains appropriate across multiple settings. This behavioral shift is one of the strongest drivers behind continued category expansion, but it also raises the stakes for product design and messaging.
Sustainability, Certification, and Procurement Alignment
Sustainability has moved from a marketing dimension to a procurement and design consideration. Certifications, material transparency, and durable construction are increasingly relevant in commercial buying decisions. Some procurement frameworks explicitly factor in product attributes such as water-resistant nylon models or ENERGY STAR-related considerations where applicable. That does not mean every buyer demands the same credentials, but it does mean that documentation, compliance, and verifiable product claims are becoming part of the commercial conversation.
For manufacturers, the implication is clear. Sustainability is not just a narrative; it is a specification. Suppliers that can align materials, manufacturing practices, and product testing with purchasing requirements will have an advantage in institutional channels, particularly where volume purchasing and standardization matter.
PW Consulting
Supply Chain Pressures and Cost Structure Realignment
The broader cost environment continues to influence category economics. Raw materials, manufacturing processes, logistics, and compliance testing all contribute to the final cost structure. As buyers become more attuned to specifications and durability, there is less room to compete through aggressive cost-cutting that compromises quality. At the same time, efficient sourcing, modular component design, and consistent quality control can protect margins without eroding trust.
This driver is especially important because the laptop bag market is not growing through a single high-volume breakthrough. It is growing through cumulative improvements in usability, reliability, and alignment with institutional and professional buying behavior. Cost discipline, therefore, has to be balanced against the risk of weakening the very attributes that justify premium positioning.
Competitive Landscape and Leading Strategies
The competitive environment reflects a blend of established mobility brands and specialized accessory players, each pursuing a different interpretation of value. The market is not dominated by a single category standard. Instead, it is shaped by competing philosophies: professional security, urban lifestyle integration, rugged protection, and lightweight portability.
Differentiation Strategies Among Key Players
Global players such as Samsonite have built their laptop bag positioning around professional and business-oriented backpacks and briefcases with RFID blocking and anti-theft features. Their strength lies in translating trust and professional image into structured protection and organized carry. Thule approaches the category from an urban and active lifestyle angle, emphasizing padded protection and sustainability credentials that appeal to users who value both durability and responsible product design. Targus focuses on premium executive and work backpacks with innovative protection systems, reinforcing a professional identity while upgrading organization and device security. Kensington addresses rugged protection needs through cases, sleeves, and carrying bags that serve users looking for stronger device safeguards. DICOTA contributes a more lightweight and cushion-protection-oriented approach, targeting users who prioritize portability without sacrificing protection.
What these strategies share is a focus on reducing uncertainty. Whether through anti-theft features, certified protection, rugged construction, or sustainability positioning, the leading players are trying to make the laptop bag feel less like a commodity and more like a functional part of a professional or lifestyle ecosystem.
Strategic Positioning Patterns
A few patterns are emerging across the competitive field.
-
Protection as a product system, not a feature. Leading designs increasingly treat protection as an integrated outcome of compartment structure, padding distribution, closure design, and material choice. This makes it harder for followers to copy a product by imitating a single attribute.
-
Professional identity and aesthetic discipline. Business users still expect products that look appropriate in formal and semi-formal environments. That does not mean conservative design only, but it does mean restraint, clean lines, and coherent material choices often outperform visually noisy products.
-
Compliance and documentation as commercial leverage. Brands that can provide clear product information, relevant certifications, and procurement-friendly specifications gain traction in institutional channels where purchasing decisions are more structured.
Market Structure Evolution
The market is not consolidating into a single dominant model, nor is it fully fragmenting into unrelated niches. Instead, it is becoming more layered. At one level, global players maintain visibility through brand trust and broad distribution. At another level, specialized brands compete with highly focused product architectures that address a narrower set of use cases more intensely. New entrants can still find room, particularly if they target underserved intersections such as hybrid-use bags that combine professional appearance with light weight, or products designed explicitly for procurement specifications.
One notable dynamic is that recent product activity has centered on refinement rather than radical reinvention. Launches have emphasized premium protection, improved organization, convertible formats, and broader professional collections. That suggests a market that is maturing in its core expectations while still searching for better ways to combine protection, mobility, and style. Instructional and institutional buying dynamics further reinforce the importance of meeting defined product requirements rather than relying on brand appeal alone.
Future Trends and Commercial Implications
Looking ahead three to five years, several trends are likely to shape where growth and profitability concentrate.
Trend One: Protection Becomes Smarter and More Integrated
The next phase of product development will likely treat protection and organization as a unified system. Expect more designs that combine impact mitigation with smarter storage architecture, quick-access zones, and security-oriented features that do not add bulk. The commercial opportunity lies in packaging these attributes into products that are still comfortable to carry and coherent in appearance. Risk arises if protection features become overdesign-heavy, making bags feel cumbersome or visually off-putting for everyday professional use.
Trend Two: Procurement-Ready Products Gain Share in Institutional Channels
Demand from structured buying environments is likely to become more influential. As purchasing frameworks specify attributes such as material performance, water resistance, and certification alignment, suppliers with compliant, well-documented products will be better positioned to win volume business. The opportunity is to build procurement-ready portfolios that can scale across organizational buyers without sacrificing brand consistency. The uncertainty is that procurement requirements can vary widely by region and institution, making it harder to rely on a single standardized offering.
Trend Three: Hybrid-Use Design Expands the Addressable Use Case
As users continue to move between settings, hybrid-use bags are likely to become more important. Products that perform well for commuting, office use, and light travel can widen the value proposition and reduce the need for multiple specialized bags. This creates an opportunity to design for flexibility, modularity, and professional credibility at the same time. The challenge is maintaining a clear identity. A hybrid product that tries to serve too many audiences can lose coherence and weaken perceived value.
Underlying Risks and Uncertainties
A few cautionary signals should not be ignored. Device form factors will continue to evolve, and bags that are too tightly optimized for current sizes may lose relevance if sizes, weights, or carrying preferences change. Sustainability expectations may intensify, increasing the compliance burden for manufacturers that lack robust documentation or material strategies. Competition may also push the category toward incrementalism, where features accumulate without delivering a clearly superior user experience. If that happens, the market may grow but margins and brand loyalty could erode.
Strategic Action Points for Decision Makers
For Manufacturers and Brand Leaders
-
Design for system-level protection and organization rather than isolated features. Products that feel engineered, not assembled from separate add-ons, are better positioned to defend price and trust.
-
Build procurement-ready documentation and specification clarity into product development early. The ability to demonstrate compliance and performance consistency can open institutional channels that are otherwise difficult to access.
-
Balance hybrid-use versatility with a clear point of view. Versatility should expand relevance, not blur identity.
For Investors and Strategic Capital
-
Prioritize brands with defensible differentiation in protection, organization, or procurement alignment. Growth alone is not enough; the quality of growth determines whether a player can sustain margins.
-
Watch for product refinement cycles that strengthen core value propositions rather than dilute them through feature overload. Investment theses should favor companies that can convert product credibility into repeat professional demand.
-
Monitor how sustainability and specification requirements reshape sourcing and marketing costs, since those factors will increasingly influence profitability in commercial channels.
For Procurement and Enterprise Buyers
-
Evaluate laptop bags as part of a broader device-carrying and security strategy, not merely as accessories. Specifications related to protection, water resistance, and organization can directly affect daily operational reliability.
-
Prefer suppliers that can provide clear product documentation, repeatable quality, and compatibility with institutional purchasing requirements. This reduces the risk of mismatched procurement and user dissatisfaction.
-
Balance professional appearance expectations with real-world carry needs. The best choice is often the product that supports workflow across multiple environments without requiring users to compromise on protection or usability.
Conclusion
The laptop bag market is expanding on the back of device mobility, hybrid work habits, and rising expectations for protection and organization. Yet the more important story is not the growth rate itself, but the changing criteria that determine who captures value within that growth. Differentiation is increasingly tied to how well a product integrates protection, professional identity, compliance readiness, and everyday usability. Brands that treat the category as a functional system rather than a cosmetic accessory are better positioned for the next phase of expansion.
Backpack Travel Bag Market
For leaders operating in this space, the strategic question is not whether demand will continue, but whether product strategy and commercial positioning are aligned with the specifications, behaviors, and purchasing dynamics that now shape the market. More granular segmentation data, regional dynamics, and tailored strategic scenarios can help narrow the gap between market-level trends and actionable business decisions.
Luggage Market
For detailed analysis of this topic, please visit the official page: Laptop Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com