

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blood and Fluid Warmer Market: How 7.85% CAGR and Critical Care Demand Are Redefining Growth

Market Intelligence Brief: Strategic Trends and Commercial Opportunities in the Blood and Fluid Warmer Market
The blood and fluid warmer market has moved from a niche clinical niche to a strategically important segment within broader patient temperature management and infusion therapies. Driven by rising surgical volumes, stricter perioperative thermal management standards, and a shift toward portable, high-flow warming solutions, the sector is entering a phase of disciplined growth rather than speculative expansion. Market size reached approximately USD 1.29 billion in the base year before progressing to an estimated USD 2.17 billion by the end of the forecast horizon, with a compound annual growth rate of 7.85 percent. This trajectory reflects steady demand expansion, but it also masks structural shifts in how devices are engineered, regulated, reimbursed, and positioned across care settings. For executives, investors, and procurement leaders, the opportunity lies not in assuming uniform growth, but in understanding where differentiation, compliance readiness, and real-world clinical adoption will separate winners from the rest.
Market Profile and Defining Challenges
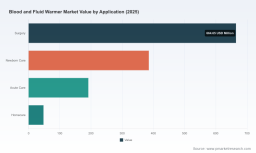
The overall market has expanded consistently from 2020 through the base year, with acceleration evident in the most recent periods. Growth is not evenly distributed across product types, clinical applications, or geographies, even though high-level splits point to clear concentration patterns. Intravenous warming systems remain the largest product category, reflecting the long-standing clinical imperative to warm fluids during transfusions, massive resuscitation, and high-volume infusion. Patient and surface warming systems also contribute meaningfully, underscoring how fluid warming is increasingly evaluated within a broader thermoregulation strategy rather than as a standalone device class. By care setting, surgical environments continue to anchor demand, while newborn care and acute care represent substantial and growing use cases. Regional dynamics show a mature, high-volume base in North America, followed by a sizable European footprint, with Asia-Pacific, Latin America, and the Middle East and Africa collectively representing a smaller but strategically important growth pool. Concentration metrics indicate a moderately consolidated environment, with the top three players holding roughly 42.5 percent of revenue and the top five approaching 58.2 percent, leaving room for specialized entrants and regional champions to compete on niche performance, portability, and workflow integration.
Against this backdrop, three challenges define the current market inflection point.
- Clinical precision and safety are now central purchase criteria, not secondary features. Fluid warming devices must deliver consistent temperature control across variable flow rates while minimizing risks such as air emboli, under-warming, or overheating. Regulatory scrutiny around labeling, performance specifications, and air-in-line risks has raised the compliance bar, making verification, documentation, and post-market monitoring essential parts of commercial viability.
- Workflow integration and portability are reshaping purchasing logic. Hospitals and emergency teams increasingly prefer solutions that can be deployed quickly, fit within limited clinical space, and integrate with existing infusion and fluid management workflows. This shifts competition away from basic heating capability toward usability, battery performance, flow range, and compatibility with high-acuity scenarios.
- Reimbursement clarity and procurement efficiency influence adoption velocity. Changes in coding status and hospital outpatient payment mechanics can alter the financial calculus for facilities evaluating warming systems, particularly in outpatient, emergency, and high-throughput surgical environments. Commercial teams therefore need to understand not only clinical evidence but also the administrative and reimbursement pathways that determine how quickly a device can be justified and deployed.
Core Demand Drivers Shaping the Market
The market’s direction is being pulled by interacting forces across technology, regulation, demand behavior, and cost structure. Each driver has practical implications for product strategy and commercial planning.
Technology Innovation and Performance Gaps
Innovation is moving beyond basic heating elements toward systems that combine flow adaptability, air detection, portability, and material safety. Recent developments illustrate how device makers are responding to performance requirements in specific use cases. One notable example is the clearance of a moderate-to-high flow blood and fluid warmer with automatic air detection, signaling that air-in-line protection and flow range are becoming baseline expectations rather than differentiators only in premium products. Another clearance focused on pediatric use, highlighting how smaller patient populations and lower flow requirements create distinct engineering challenges and open targeted commercial pathways. At the same time, device materials and manufacturing quality remain under scrutiny, with attention to components such as coated heating chambers and testing protocols aligned to recognized standards. These details matter because clinicians and procurement teams increasingly evaluate the entire system, not just the warming function in isolation.
Regulatory and Guideline Environment
Guideline updates and safety communications are reshaping how facilities think about active warming. Updated perioperative guidance has reinforced the importance of active temperature management, including fluid warming, which supports more consistent adoption in surgical and acute care pathways. Equally important, ongoing safety communications related to air-in-line and embolism risks with infusion pumps, fluid warmers, and rapid infusers continue to influence device design expectations and hospital vigilance. Rather than slowing the market, these dynamics tend to reward manufacturers that can demonstrate robust risk mitigation, clear labeling, and credible post-market documentation. For commercial leaders, regulatory readiness is becoming a market access advantage because it reduces adoption friction in risk-averse procurement environments.
Worldwide Peritoneal Dialysis Bag Warmer Market
Demand-Side Behavior and Care Setting Evolution
Clinical demand is expanding beyond traditional operating room settings. Emergency, trauma, newborn, and acute care teams are increasingly seeking warming options that can be mobilized quickly and used across variable flow conditions. Portable and battery-capable systems are particularly relevant where immediate access matters and where reliance on fixed infrastructure may limit responsiveness. This shift changes the purchasing conversation: it is less about buying a warming device for a single department and more about equipping multiple care points with solutions that fit fast-paced workflows. The practical effect is greater interest in devices that can support both high-flow resuscitation and lower-flow maintenance scenarios without forcing clinicians to switch between disconnected systems.
Supply Chain, Cost Structure, and Commercial Execution
Cost pressures and supply chain reliability remain important but are now intertwined with product complexity. Devices with more advanced sensing, air detection, and portability requirements require disciplined component sourcing and quality assurance. At the same time, procurement groups are under pressure to reduce total cost of ownership, standardize wherever possible, and avoid device proliferation that complicates training and maintenance. The result is a market where value is increasingly defined by the combination of clinical performance, training burden, service reliability, and compliance support. Manufacturers that can present a complete operational case, not just a hardware specification, are better positioned to win recurring adoption and repeat purchases.
Competitive Landscape and Strategic Positioning
The competitive field includes large diversified healthcare companies, specialized device manufacturers, and regional players with focused product lines. Profiles span companies offering integrated fluid warming within broader portfolios, portable systems designed for emergency and transport use, and engineered solutions emphasizing battery operation, flow range, or compact design. This mix creates a multi-layered market in which some competitors compete on scale, distribution, and cross-product integration, while others compete on portability, specialized clinical scenarios, and rapid deployment.
Differentiation Paths Among Leading Players
Several strategic positions are visible across the field.
- Portfolio integration plays: Some companies embed blood and fluid warming within wider fluid management, infusion, or critical care offerings. The advantage is cross-selling leverage, existing clinical relationships, and the ability to present a coordinated solution rather than a standalone device. The challenge is maintaining product-level excellence and responsiveness when warming is one component among many priorities.
- Specialized portable and high-flow solutions: Other players focus on compact, battery-powered, or high-flow devices built for emergency, trauma, and transport contexts. Their edge comes from mobility, quick setup, and performance in scenarios where fixed systems are impractical. These offerings can win strong loyalty in specific departments but must demonstrate durable reliability and regulatory compliance to scale.
- Niche engineering and targeted clearances: A subset of manufacturers builds differentiation around specific use cases, such as pediatric applications, air detection, or moderate-to-high flow performance. Targeted clearances can open distinct customer segments and provide a clearer value proposition to clinicians who need validated performance for a defined population or workflow.
Market Evolution: Consolidation, Fragmentation, and Entry Dynamics
The market appears likely to evolve along parallel tracks. Incumbent positions are supported by installed bases, regulatory histories, and distribution reach, which creates some resilience at the top of the market. At the same time, the breadth of clinical needs and the importance of specialized features prevent full commoditization. New entrants and smaller specialists can gain traction by solving concrete workflow problems, particularly where portability, air-in-line safety, and flow versatility matter most. M&A or partnership activity may increase as larger players seek to fill capability gaps in portability, digital integration, or specific clinical indications. For investors and strategic planners, the key question is not whether the market is consolidating in a simple sense, but where value is being created: in scale, in engineering specificity, or in the operational compatibility of the device with real clinical environments.
Forward-Looking Trends and Associated Opportunities
Looking across the current data and recent developments, three trends are likely to shape the next three to five years.
Infant Radiant Warmer Market
Trend 1: Performance Standardization Will Raise the Entry Bar
Air detection, flow adaptability, temperature consistency, and labeling clarity are becoming more central to purchasing decisions. As these capabilities become expected rather than exceptional, the practical barriers to entry rise. Devices that cannot demonstrate reliable performance across stated flow ranges, or that carry unresolved labeling or specification issues, face heightened scrutiny. The commercial opportunity lies in building compelling, verifiable performance narratives that reduce adoption risk for hospital teams and procurement groups. Manufacturers that treat compliance and performance documentation as part of the product story, not a back-office task, will likely see faster evaluation cycles and stronger trust from clinical buyers.
Trend 2: Portable, Multi-Scenario Warming Will Expand Beyond Traditional Settings
Demand is broadening into emergency, trauma, newborn, and acute care workflows where rapid deployment and flexibility matter. This creates opportunities for systems that can serve more than one clinical scenario without sacrificing safety or usability. Battery operation, compact form factors, and compatibility with varied infusion setups are likely to become increasingly important in procurement evaluations. Companies that design for these scenarios with clinically credible performance and clear practical advantages can capture share in segments where conventional warming solutions are less convenient. The risk is that portability claims outpace real-world reliability, so field validation and service support will be decisive.
Trend 3: Reimbursement and Guideline Alignment Will Influence Adoption Speed
Changes in coding status and payment mechanics, alongside stronger guideline emphasis on active warming, are likely to affect how quickly facilities adopt or expand warming programs. While these factors do not determine clinical value, they influence purchasing timelines, budget justification, and the administrative burden of adopting new devices. Commercial strategies that account for reimbursement pathways and guideline alignment can reduce friction and improve forecasting accuracy. At the same time, uncertainty remains because payment policy and institutional procurement behavior can shift, and any delay in reimbursement clarity can slow adoption even when clinical interest is strong.
Across these trends, the most durable commercial opportunities belong to organizations that can connect technical performance with operational fit. That means designing for the realities of busy clinical environments, providing evidence and documentation that support procurement decisions, and preparing for a market where safety, portability, and workflow compatibility are evaluated together rather than in isolation.
Strategic Actions for Decision Makers
Different audiences will extract value from the market in different ways. The following actions are most relevant for manufacturers, investors, and procurement or clinical leadership teams.
PW Consulting
For Manufacturers and Product Strategy Teams
- Prioritize verifiable differentiation. Build product narratives around flow range, air detection, portability, and material and labeling integrity, backed by clear documentation that procurement and clinical teams can evaluate quickly.
- Design for multi-scenario use where possible. Devices that can serve both higher-flow and lower-flow needs, or that fit emergency and inpatient contexts alike, reduce the need for multiple product acquisitions and simplify training.
- Treat regulatory and reimbursement readiness as commercial infrastructure. Maintain robust post-market processes, clear labeling, and an understanding of payment and coding developments so that market access is not delayed by avoidable administrative friction.
For Investors and Corporate Development Teams
- Focus on adoption readiness rather than headline growth alone. Assess whether a company’s technology fits real workflows, whether it has credible safety and compliance posture, and whether its distribution and service model can sustain repeat business.
- Watch for capability gaps that larger portfolios may want to fill. Solutions with strong portability, specialized flow performance, or validated pediatric or emergency use cases may attract interest from broader healthcare portfolios seeking to strengthen temperature management offerings.
- Factor reimbursement and guideline dynamics into valuation assumptions. Adoption speed can be influenced by coding status, payment updates, and institutional procurement cycles, so these elements should be part of scenario planning.
For Procurement, Clinical, and Hospital Leadership
- Evaluate total operational fit, not just warming capability. Consider setup time, staff training burden, compatibility with existing infusion workflows, service reliability, and how well the device supports both routine and high-acuity scenarios.
- Align device selection with guideline expectations and internal safety protocols. Preference for solutions that support active temperature management and address known risks such as air-in-line concerns can simplify internal justification and reduce clinical risk.
- Use evidence and post-market documentation as part of the evaluation process. Clear specifications, reliable labeling, and transparent performance claims help reduce uncertainty and support consistent adoption across departments.
The blood and fluid warmer market is moving toward a more disciplined, performance-driven phase in which growth is real but increasingly dependent on compliance readiness, workflow fit, and credible differentiation. For leaders evaluating entry, expansion, or procurement decisions, the most valuable intelligence is the kind that connects market size and trend direction to the specific operational realities of each purchase environment. Detailed segmentation data, company-level profiles, regulatory timelines, reimbursement mechanics, and region- and application-specific demand patterns can sharpen those decisions significantly. For teams that need that level of granularity, the full research report provides deeper breakdowns and tailored guidance to support planning with more precision.
For detailed analysis of this topic, please visit the official page: Blood and Fluid Warmer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com