

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PMSM Market to Hit $28.81B by 2032: Why 7.7% CAGR Signals a Strategic Shift

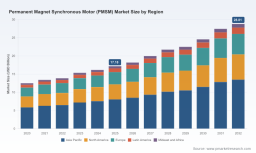
The PMSM Market at a Strategic Inflection Point: Trends, Challenges, and Where Value Is Created
The global landscape for Permanent Magnet Synchronous Motors (PMSM) has shifted from a niche technology segment to a foundational power transmission architecture across multiple industries. Over the 2020–2025 cycle, the market expanded from approximately $12.5 billion to $17.18 billion, reflecting a steady compound annual growth trajectory that analysts project to continue through 2032. At a 7.7 percent CAGR, the segment is expected to reach roughly $28.81 billion by the end of the forecast period, signaling a structural expansion rather than a temporary cyclical surge. This growth is not distributed uniformly across regions, motor configurations, or end-use sectors, and that unevenness is where competitive advantage is being forged. Executives evaluating capacity allocation, portfolio strategy, or capital deployment should recognize that the PMSM market is entering a phase where efficiency mandates, raw material dynamics, and application-specific performance requirements are converging to reshape demand patterns.
Dc Permanent Magnet Motor Market
Market Scale, Concentration, and the Shape of the Opportunity
The headline figures point to a market that has more than doubled its baseline in just over a decade, but the strategic story lies in the composition of that growth. Asia Pacific continues to anchor the largest share of revenue, reflecting the concentration of manufacturing capacity, electrification investment, and industrial modernization in the region. North America and Europe follow, each drawing strength from distinct demand engines: North America benefits from industrial automation modernization and a rapidly scaling electric mobility ecosystem, while Europe's growth is tightly coupled to energy efficiency directives and advanced manufacturing reshoring. Latin America and the Middle East and Africa represent smaller but strategically relevant footprints, often tied to infrastructure modernization, emerging industrial bases, and selective mobility programs. Across motor types, interior permanent magnet designs command the largest revenue share, a reflection of their dominance in applications demanding high power density, precise control, and compact packaging. Surface-mounted variants and other specialized configurations maintain meaningful positions in segments where thermal management, cost structure, or manufacturability favor alternative layouts. In terms of applications, electric vehicles represent the most visible growth vector, but industrial automation, robotics, conveyors, compressors, and precision motion control systems collectively account for a substantial and steadier portion of demand. The market is moderately concentrated, with the top three players capturing roughly 45 percent of revenue and the top five approaching 60 percent, a structure that suggests scale advantages, technology portfolios, and service ecosystems matter, but there remains meaningful space for differentiated specialists and regional champions.
Key Challenges and Strategic Inflection Points
Three challenges define the current operating environment for PMSM suppliers and downstream buyers. First, the economics of rare earth permanent magnets create a persistent cost and supply risk. Neodymium-iron-boron (NdFeB) magnets constitute over 90 percent of material costs in production for many PMSM designs, and the manufacturing capacity for sintered NdFeB magnets is heavily concentrated in a single geography. This concentration introduces exposure to export controls, pricing volatility, and logistics disruptions, making magnet sourcing a strategic variable rather than a routine procurement activity. Second, the market is navigating a mismatch between standardized motor offerings and the growing demand for application-specific optimization. As vehicles, industrial equipment, and precision machinery demand higher efficiency at partial loads, faster dynamic response, and tighter integration with power electronics and control software, generic motor configurations are losing relevance in premium segments. Third, the industry is facing a regulatory and standards environment that is accelerating adoption but also raising the bar for validation, lifecycle efficiency, and traceability. Energy and resource-saving PMSM and synchronous reluctance motor systems are entering commercial mass production, and efficiency mandates across industrial and automotive applications are reinforcing the shift toward high-performance synchronous architectures. The inflection point is clear: the companies that can decouple performance from raw material intensity, align product roadmaps with regulatory trajectories, and deliver integrated solutions rather than isolated motor units will capture disproportionate value.
Key Drivers Reshaping the PMSM Market
Technology Innovation and the Push for Higher Efficiency at Lower Material Intensity
Innovation in PMSM design is increasingly focused on achieving competitive power density and efficiency without proportionally increasing rare earth content. Advances in rotor topology, magnetization patterns, thermal management, and winding architecture are enabling manufacturers to optimize torque ripple, reduce losses at partial load, and improve controllability. These improvements matter because many real-world applications do not operate at peak load; they cycle through variable speeds, frequent starts and stops, and partial-load conditions where efficiency and responsiveness determine total cost of ownership. At the same time, the integration of motors with inverters, sensors, and control firmware is becoming a differentiator. A motor that performs well in isolation may underdeliver in a system where torque control, thermal limits, and communication latency intersect. As a result, engineering leadership is shifting from component-level specifications to system-level performance, and suppliers that can co-design motors with power electronics and control strategies are gaining an edge in high-value applications. The recent push toward energy- and resource-saving PMSM and synchronous reluctance motor systems entering commercial mass production illustrates this direction: performance is being redesigned to align with both efficiency mandates and material constraints.
Policy and Regulatory Tailwinds Reinforcing Adoption Across Sectors
Regulation is acting as both a demand catalyst and a design constraint. In industrial contexts, efficiency standards and corporate sustainability targets are driving retrofits and new equipment purchases toward motor systems that reduce energy consumption across duty cycles. In mobility, electrification mandates and emissions frameworks are accelerating the replacement of legacy drivetrain architectures with permanent magnet synchronous solutions that offer precise torque control and compact packaging. Compliance is no longer a checkpoint at the end of development; it is increasingly embedded in product architecture decisions, from material selection to thermal design to lifecycle documentation. This regulatory environment rewards companies that can demonstrate measurable efficiency gains, maintain consistent quality across batches, and provide evidence of performance under real operating conditions. It also raises the stakes for suppliers that rely on fragmented design approaches or inconsistent validation, because the cost of non-compliance or underperformance is rising across both industrial and automotive pipelines.
PW Consulting
Demand-Side Shifts in Mobility and Industrial Automation
On the demand side, two broad behavioral shifts are reshaping the market. Electric vehicle platforms are moving from early adoption to mainstream scaling, but the motor requirements within that segment are diversifying. Different vehicle classes, duty profiles, and packaging constraints are creating a need for motors that balance power density, cost, thermal robustness, and manufacturability. Meanwhile, industrial buyers are prioritizing automation that reduces labor dependency, improves throughput consistency, and supports energy-conscious operation. Robotics, precision motion control, conveyors, compressors, and machine tools are all seeing renewed investment in motor systems that can deliver accurate positioning, rapid acceleration, and efficient operation across variable loads. The common thread is a preference for motors that are not only efficient at peak performance but also dependable and controllable in dynamic operating conditions. This is shifting purchasing criteria from price-per-unit toward total system value, including integration ease, lifecycle serviceability, and compatibility with control and automation architectures.
Supply Chain Realities and Cost Structure Pressures
The cost structure of PMSM production is increasingly defined by magnet availability, processing capacity, and the ability to manage volatility without eroding margins. Because rare earth magnets account for such a large share of material cost, procurement strategy has become a core competitive lever. Suppliers are exploring multiple routes to resilience: diversifying magnet sources where possible, designing for reduced rare earth intensity, improving recycling and recovery pathways, and standardizing components to reduce variability. At the same time, manufacturing footprint decisions are being influenced by the location of downstream demand, the cost of energy and labor, and the need to be close to customers for customization and service. The practical effect is that scale alone is no longer the sole determinant of advantage. Companies that can combine disciplined material management with flexible manufacturing and strong supplier relationships are better positioned to protect margins through cycles of demand growth and input volatility.
Competition Landscape: Positioning, Differentiation, and the Evolution of Advantage
How Leading Players Are Building Defensible Positions
The competitive field in the PMSM market includes established industrial conglomerates, specialized motion control manufacturers, automotive-adjacent suppliers, and regional players with strong local execution. A defining feature of the leaders is the breadth of their portfolios paired with the depth of their application expertise. Large multinational suppliers typically compete by offering integrated solutions that span motors, drives, control software, and service support, which reduces integration risk for customers and creates switching costs that protect recurring revenue. Their advantage often lies in the ability to standardize core motor architectures while tailoring performance through control strategies, packaging, and optional features. This approach allows them to serve multiple verticals without fragmenting their engineering base too thinly.
Specialized and regional players compete in a different way. Rather than pursuing breadth, they focus on specific performance niches, hygiene-sensitive environments, compact applications, or regional service requirements where responsiveness and customization matter more than scale. Their differentiation often comes from mastering a narrow set of requirements exceptionally well, whether that is high-precision motion, harsh-environment reliability, cost-efficient manufacturability for a particular motor form factor, or close collaboration with local system integrators. The recent product activity in the sector reflects these divergent strategies. For example, Yaskawa Electric Corporation launched the MOTOMAN-HD7 and HD8 servo systems designed for hygienic environments, an indication that application-specific robustness and compliance with stringent cleanliness requirements are becoming valued differentiators in selected industrial and life sciences contexts. In mobility, Nidec Corporation signaled its intent to unveil next-generation mobility technologies, including advanced motors, at a major industry exhibition, reinforcing the continued focus on drivetrain performance, packaging, and integration as competitive battlegrounds. Mitsubishi Electric Corporation also received recognition for its railcar motor system, an example of how synchronous motor solutions are being validated in demanding transportation applications where reliability, efficiency, and lifecycle performance are closely scrutinized.
Strategic Positioning and the Role of Integration
The most resilient positions in this market are built on integration and system-level value creation. Suppliers that can deliver not only a motor but also the accompanying control logic, thermal strategy, and service model reduce the complexity burden for end users and increase the likelihood that their products become embedded in long-lived deployments. This is especially relevant in industrial automation, where downtime costs and retrofit complexity influence purchasing decisions, and in mobility, where packaging constraints and performance consistency shape platform choices. In contrast, companies that compete primarily on component price without differentiation in control, reliability, or service face greater exposure to margin pressure and substitution risk. As efficiency mandates tighten and application demands become more specific, the premium on integration capability is likely to increase, favoring players that can orchestrate the interaction between motor, drive, and control layers.
Consolidation, Fragmentation, and the Role of New Entrants
The market's moderate concentration suggests room for both consolidation and fragmentation depending on the segment. In high-volume, standardized applications, scale advantages in manufacturing, procurement, and distribution can drive consolidation, as larger players capture efficiencies and downstream customers prefer fewer, more capable suppliers. In specialized segments, fragmentation can persist or even intensify, because the value lies in solving distinct technical challenges rather than in pure volume. New entrants are most likely to succeed when they address a clearly defined performance gap, such as lower rare earth dependence, improved thermal behavior in a specific duty cycle, or a control architecture that simplifies integration for a particular customer segment. The strategic implication is that market share movements will not be uniform. Growth will be redistributed toward firms that align their capabilities with the most valuable application requirements, while undifferentiated offerings face increasing pressure from both incumbents and targeted newcomers.
Forward Outlook: Trends to Watch and Where the Opportunities Lie
Trend 1: Efficiency as a System Property, Not Just a Motor Specification
Over the next three to five years, PMSM value will increasingly be defined by system-level efficiency across real operating profiles rather than peak-rated performance alone. Buyers in industrial and mobility applications will continue to prioritize motors that maintain strong efficiency at partial loads, respond quickly to control inputs, and integrate cleanly with power electronics and automation software. This trend creates opportunities for suppliers that can offer configurable performance, application-tuned control strategies, and documentation that supports compliance and lifecycle planning. It also raises the importance of validation under representative conditions, because efficiency claims that look strong on paper but underperform in the field will erode trust and purchasing preference.
Trend 2: Material Strategy Becomes a Competitive Capability
The rare earth dependency embedded in many PMSM designs will keep material strategy in the foreground. Companies that can reduce magnet intensity without sacrificing critical performance attributes, manage supply relationships intelligently, and explore recovery or substitution pathways where technically and economically feasible will gain resilience. This is not solely a cost issue; it is also a risk management and continuity issue. In periods of pricing volatility or policy change, the ability to maintain consistent output and margin can distinguish winners from laggards. Opportunities here include design optimization that preserves torque and efficiency with smarter magnet placement, improved recycling loops, and procurement models that reduce exposure to single-source bottlenecks.
Trend 3: Application-Specific Solutions Gain Premium Positioning
As the market matures, the most attractive margins are likely to shift toward applications where motors must meet specialized requirements. Hygiene-sensitive industrial environments, high-precision motion control, demanding transportation duty cycles, and compact mobility architectures are all examples where tailored engineering can command premium positioning. The commercial launch of servo systems designed for hygienic environments and continued activity in mobility technology exhibitions point to this direction. Suppliers that invest in understanding the operating context, regulatory constraints, and lifecycle needs of specific segments can build defensible niches, while those that rely on broad, undifferentiated portfolios may find themselves competing primarily on price in more commoditized parts of the market.
Portable Permanent Magnet Pump Market
Risks and Uncertainties to Monitor
Several uncertainties could shape the trajectory of the market. Input availability and pricing for rare earth materials remain volatile, and any disruption can affect cost structures and time-to-market for new designs. Regulatory timelines and efficiency standards may accelerate adoption in some regions while creating compliance complexity in others, especially where validation requirements differ across jurisdictions. Competitive intensity may increase as incumbents deepen integration capabilities and new entrants target specific niches, which could pressure margins in segments that fail to differentiate. Finally, demand growth in electric vehicles and industrial automation is subject to broader macroeconomic conditions, investment cycles, and the pace of electrification adoption in different geographies. Executives should treat these variables as integral to planning rather than peripheral risks, because they affect sourcing, product roadmaps, and the timing of capacity decisions.
Actionable Implications for Decision-Makers
For Manufacturers and Product Leaders
Align engineering roadmaps with system-level value rather than motor-only specifications. Prioritize designs that perform well across variable duty cycles, integrate readily with control and power electronics, and offer flexibility for application-specific customization. Strengthen material strategy by evaluating magnet intensity, sourcing diversification, and recovery pathways as core design parameters. Where possible, build modular architectures that allow performance to be tuned through control and packaging instead of relying solely on changes in magnet content. This approach can improve resilience while preserving the ability to serve both standardized and specialized segments.
For Investors and Capital Allocators
Focus on companies that demonstrate a credible path to combining efficiency, integration, and material resilience. Scale matters, but in this market it is most valuable when paired with application expertise and the ability to deliver total system performance. Differentiated niches in hygiene-sensitive environments, precision motion, mobility packaging constraints, and other high-specification applications can offer stronger margin potential than undifferentiated volume plays. Pay attention to how suppliers manage rare earth exposure and whether they have clear strategies for continuity, cost control, and product evolution. The winners are likely to be those that can convert technical capability into embedded, long-lived deployments.
For Procurement and Operations Leaders
Shift evaluation criteria toward total cost of ownership, integration effort, and lifecycle reliability. A lower upfront price can be offset by higher integration cost, poorer partial-load efficiency, or greater service complexity. Where critical applications are concerned, prioritize suppliers that can provide consistent validation, predictable service support, and clear documentation of performance under representative conditions. Diversify sourcing where feasible to reduce exposure to single-point material or manufacturing risks, and consider long-term collaboration with suppliers that demonstrate a strong plan for managing magnet-related volatility. Procurement decisions made with system value in mind tend to reduce downstream risk and improve operational predictability.
The strategic picture for the PMSM market is one of durable growth shaped by efficiency mandates, material constraints, and application diversification. The companies that will capture the most value are those that treat the motor as part of a broader system, build resilience into material and supply decisions, and tailor performance to the real operating conditions their customers face. For decision-makers looking to move from high-level trends to segment-level detail, the full research report provides a deeper breakdown of subsegments, regional demand patterns, competitive positioning, and scenario-based implications that can inform capacity, sourcing, and portfolio choices.
For detailed analysis of this topic, please visit the official page: Permanent Magnet Synchronous Motor (PMSM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com