

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Low Pressure Molding Polyamides Market 2026: Beyond the 7.5% CAGR Story

The Strategic Evolution of Low Pressure Molding with Polyamides: Market Outlook and Commercial Opportunities
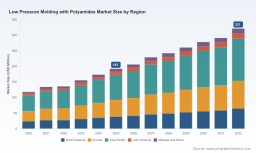
The low pressure molding (LPM) with polyamides sector has transitioned from a niche encapsulation technique to a strategic manufacturing capability across multiple high-value industries. Between 2020 and 2025, the global market expanded from approximately 118 million USD to 192 million USD, establishing a base for sustained growth. Forward-looking projections through 2032 indicate a compound annual growth rate of 7.5 percent, positioning the total addressable market to exceed 320 million USD within the forecast horizon. This trajectory reflects a structural shift in how engineers approach component protection, miniaturization, and sustainability compliance rather than a temporary production cycle fluctuation. For executives and investors evaluating advanced manufacturing materials, the numbers themselves tell only part of the story. The underlying value lies in understanding how formulation chemistry, equipment engineering, regulatory pressure, and end-use demand are converging to reshape commercial positioning.
Despite the clear growth momentum, the industry operates at a critical inflection point. Three structural challenges demand strategic attention. First, raw material supply volatility continues to create margin pressure, as specialty polyamide feedstocks and performance additives experience periodic shortages and pricing swings that complicate long-term planning. Second, regulatory tightening around volatile organic compound emissions, particularly across Europe and China, is forcing material suppliers to redesign formulations without sacrificing thermal stability, adhesion reliability, or processing speed. Third, the high initial capital outlay for compatible LPM equipment, combined with the premium cost of engineered polyamide compounds, remains a barrier for mid-tier manufacturers who recognize the performance benefits but struggle to justify the investment against legacy potting or traditional molding alternatives. These pressures are not transient obstacles; they are forcing a market recalibration where operational efficiency, material sustainability, and total cost of ownership will determine which participants capture durable share.
Key Drivers Reshaping the Market Trajectory
Several interconnected forces are accelerating adoption and redefining how value is created in the low pressure molding with polyamides ecosystem. Understanding these drivers is essential for anticipating where capital, capability, and competitive advantage will concentrate over the next several years.
PW Consulting
Technical Innovation in Materials and Processing Systems
Material science and equipment engineering are advancing in tandem, creating compounding productivity gains. Polyamide-based hot melt compounds are being optimized for lower processing temperatures, faster cycle times, and enhanced mechanical resilience, while LPM machinery platforms are being upgraded to deliver tighter process control and reduced energy consumption. Recent system upgrades in the industry have demonstrated efficiency improvements approaching 28 percent alongside energy reductions near 20 percent, illustrating how hardware and chemistry improvements reinforce one another. Equally significant is the expansion into specialized performance grades. New polyamide formulations designed for medical device encapsulation have shown durability increases around 24 percent and equipment failure rate reductions near 16 percent, opening doors to higher-margin regulated applications. In automotive contexts, high-strength molding compounds introduced in late 2024 have boosted demand by roughly 25 percent while cutting defect rates by 15 percent, signaling that material performance gains can directly translate into production yield improvements and lower warranty exposure.
Regulatory and Sustainability Pressures as Catalysts
Environmental regulation is no longer a compliance footnote; it is becoming a primary procurement driver. The European Chemicals Strategy for Sustainability and China's Green Manufacturing Standards are reshaping acceptable formulation parameters for polyamide hot melts used in low pressure molding. Compliance now requires meaningful reductions in VOC emissions and, increasingly, measurable progress toward circularity. This regulatory trajectory is pushing suppliers toward bio-sourced feedstocks and recyclable compound architectures. One notable industry example demonstrated a bio-based polyamide launch that reduced emissions by 20 percent and improved recycling rates by 18 percent within electronics applications, establishing a benchmark for what sustainability-compliant processing can achieve. For manufacturers and specifiers, these regulatory shifts create a dual imperative: investments in cleaner formulations protect market access, while proactive sustainability positioning can become a competitive differentiator in tenders where environmental criteria carry increasing weight.
Demand-Side Shifts Across End-Use Markets
The demand landscape is being restructured by electrification, miniaturization, and reliability expectations across discrete industries. Electronics remains the largest application segment, driven by the ongoing need to protect densely packed PCBs, sensors, and connectors from moisture, thermal stress, and mechanical shock. Automotive demand is intensifying as vehicle architectures incorporate more power electronics, battery-adjacent components, and advanced driver-assistance systems that require robust encapsulation without adding significant mass or thermal resistance. Appliance and industrial automation applications are expanding more gradually, but they are benefiting from the same overarching themes: tighter space constraints, higher operating temperatures, and a preference for process methods that minimize post-mold finishing. The common thread across these sectors is that LPM with polyamides is increasingly viewed as a solution that combines protection, automation compatibility, and material efficiency in a single step, reducing downstream assembly complexity.
Supply Chain and Cost Structure Dynamics
Cost structures are evolving as the industry matures. While the upfront expense of polyamide compounds and compatible molding equipment remains a consideration, the total cost calculus is shifting when yield improvement, rework reduction, and energy efficiency are factored in. At the same time, feedstock volatility and additive availability continue to introduce uncertainty into production scheduling and pricing strategies. Companies that are building more resilient supplier relationships, standardizing compound specifications across product families, and investing in process control are better positioned to absorb input cost fluctuations without eroding margins. The strategic lesson is clear: procurement and manufacturing strategy can no longer be treated separately. In this market, material sourcing decisions directly influence process stability, quality consistency, and ultimately, the economic justification for adopting LPM at scale.
Competitive Landscape and Strategic Positioning
The competitive environment in low pressure molding with polyamides is characterized by a mix of established adhesive and materials giants, specialized compound developers, and equipment-focused system providers. Market concentration indicates that a relatively small group of participants commands a significant share of revenue, with the top three firms accounting for approximately 46 percent and the top five reaching around 68 percent. This concentration reflects the technical barriers to entry, the importance of validated performance in demanding applications, and the value of integrated offerings that span materials, equipment know-how, and application support.
Leading players are differentiating through distinct strategic vectors. One major global materials company has built its position around recognized hot melt adhesive platforms for electronics, medical, industrial automation, HVAC, and lighting encapsulation, leveraging brand trust and broad application coverage. Another key competitor has leaned into sustainability and vertical application strength, offering polyamide hot melt adhesives based on substantial bio-sourced content and expanding into high-strength automotive molding compounds that directly address yield and defect performance. Regional and specialized players are carving out space through equipment compatibility, localized service, and targeted compound development. Several suppliers focus on polyamide hot melt compounds engineered specifically for LPM systems, while equipment-oriented firms emphasize machine design, process optimization, and integration support that reduce the learning curve for manufacturers transitioning from traditional methods.
Recent industry developments highlight how quickly competitive advantage can shift when technical execution aligns with market needs. System upgrades have improved throughput and energy efficiency, bio-based launches have advanced sustainability credentials in electronics, product line expansions have strengthened automotive demand and quality outcomes, and specialized medical-grade polyamides have enhanced durability and reliability. These moves demonstrate that the market rewards participants who can simultaneously deliver material performance, processing efficiency, and application-specific validation. Looking ahead, the landscape is likely to evolve through a combination of consolidation among materials and adhesive players seeking broader portfolios, continued differentiation by equipment and compound specialists capturing regional or vertical niches, and potential new entry from organizations that can bridge formulation chemistry with automated encapsulation systems. The companies that will lead are those that treat LPM not merely as a material sell, but as an integrated process solution with measurable operational and sustainability returns.
Forward-Looking Trends and Commercial Implications
The next three to five years will likely be defined by a small number of high-impact trends that connect technical progress with commercial opportunity. Anticipating these trends allows decision-makers to prioritize investments, shape procurement strategies, and identify where new value can be captured.
- Sustainability-driven formulation leadership will become a market access requirement and a sales advantage. As regulatory expectations around emissions and circularity tighten, polyamide compounds that demonstrate lower VOC profiles, bio-sourced content, and improved recyclability will be preferred in regulated electronics, automotive, and medical applications. Suppliers and manufacturers that standardize sustainable grades early will reduce reformulation risk and position themselves favorably in procurement evaluations where environmental criteria are increasingly quantified.
- Process integration and smart manufacturing will deepen the value proposition of LPM systems. Equipment upgrades that improve yield, cut energy use, and enable tighter process control are already delivering measurable efficiency gains. Over the forecast period, the integration of real-time monitoring, predictive maintenance, and closed-loop process adjustments is expected to further reduce variability and support higher-volume production. Manufacturers that invest in compatible equipment and data-driven process control can convert material performance into repeatably lower cost per protected unit, strengthening the economic case for LPM adoption.
- Application expansion into higher-margin regulated segments will accelerate. Medical device encapsulation and advanced automotive electronics represent areas where durability, failure reduction, and compliance documentation carry substantial commercial weight. Materials and systems that can prove enhanced reliability and meet sector-specific standards will command premium positioning. The opportunity here is not simply incremental volume growth but a shift toward applications where performance validation and regulatory readiness create higher barriers to competition and more resilient pricing power.
These trends carry inherent uncertainties. Feedstock volatility can disrupt cost planning and production continuity, particularly when specialty additives or specific polyamide variants face constrained availability. Regulatory evolution may outpace formulation development in some regions, creating temporary compliance gaps that affect time-to-market. In addition, the capital intensity of equipment and engineered compounds may slow adoption among cost-sensitive manufacturers unless the total cost benefits are clearly demonstrated through pilot programs and lifecycle economics. Organizations that monitor these variables closely and build flexibility into their sourcing, formulation, and equipment strategies will be better equipped to navigate shifts without losing competitive momentum.
Polyamide Hot Melt Adhesives Market
Strategic Actions for Decision-Makers
Translating market dynamics into concrete decisions requires a clear view of where to allocate attention and resources. The following recommendations are tailored to the primary audiences evaluating low pressure molding with polyamides.
For Manufacturers and Process Engineers
Prioritize pilot-scale validation that measures total cost of ownership rather than material price alone. Quantify yield improvements, rework reduction, energy consumption, and cycle-time changes when evaluating polyamide compounds and LPM equipment. Where possible, standardize compound specifications across product families to simplify procurement and reduce exposure to feedstock volatility. Invest in operator training and process control capabilities early, as the performance advantage of LPM is often realized through repeatable process execution rather than material selection in isolation. For manufacturers serving regulated sectors, establish documentation and compliance pathways for sustainable formulations to protect future market access.
Thermoplastic Polyamide Market
For Investors and Strategists
Focus on participants that combine material innovation with equipment compatibility and application-specific validation, as integrated solutions are earning share in a concentrated market. Pay attention to companies expanding into bio-based or high-strength grades that address automotive and medical demand, since these segments offer stronger margin resilience and clearer differentiation. Monitor consolidation signals and regional expansion patterns, particularly where localized compound development or equipment support can reduce lead times and improve customer retention. When evaluating opportunities, weigh feedstock supply resilience and regulatory readiness as much as current revenue, because these factors will increasingly determine long-term competitiveness.
For Procurement and Supply Chain Leaders
Treat material sourcing as a strategic lever rather than a transactional function. Develop dual or multi-source strategies for critical polyamide feedstocks and additives to mitigate volatility, and work with suppliers to lock in quality specifications that align with downstream process requirements. Where sustainability criteria are entering tender evaluations, require transparent formulation data and recycling or emissions performance indicators, not just price benchmarks. Collaborate with R&D and manufacturing teams to align procurement decisions with process goals, ensuring that material choices support cycle-time targets, defect reduction, and compliance obligations simultaneously.
The market for low pressure molding with polyamides is moving beyond a phase of basic adoption into one where formulation sophistication, process efficiency, sustainability compliance, and application-specific validation determine commercial outcomes. Executing effectively in this environment requires access to granular segmentation data, competitive benchmarking, and scenario-based planning that go beyond headline market size and growth rates. For decision-makers seeking to refine entry timing, portfolio focus, or supply strategy, a detailed research report can provide the segmented revenue breakdowns, company-level positioning maps, and forward indicators needed to convert these strategic themes into precise, executable plans.
For detailed analysis of this topic, please visit the official page: Low Pressure Molding with Polyamides Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com