

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Corn Starch Market: Beyond 8.1% CAGR, What's Driving $41.4B Growth by 2032

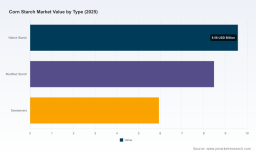
The Corn Starch Market: Strategic Trends and Commercial Opportunities Through 2032
The global corn starch market has entered a phase of accelerated expansion, driven by converging forces across food innovation, pharmaceutical formulation, and industrial substitution. With total market revenue reaching USD 24.0 billion in 2025 and a projected compound annual growth rate of 8.1 percent through 2032, the sector is evolving from a commoditized feedstock into a specialized functional ingredient landscape. This shift demands that executives, planners, and investors recalibrate their strategic assumptions. The following analysis maps the market's structural dynamics, identifies the forces reshaping competitive positioning, and outlines actionable implications for decision-makers.
Market Landscape and Structural Challenges
Historical trajectory underscores the market's momentum. Revenue climbed from USD 12.0 billion in 2020 to USD 15.49 billion in 2023, then accelerated sharply to USD 20.08 billion in 2024 and USD 24.0 billion in 2025. Forecasts project continued growth to USD 25.31 billion in 2026, USD 28.53 billion in 2027, and a terminal value of USD 41.4 billion by 2032. This trajectory reflects both volume expansion and value migration toward higher-margin specialty grades. The market remains moderately concentrated, with the top three players capturing 45.2 percent of revenue and the top five holding 58.6 percent, indicating room for regional challengers and niche specialists to compete on formulation expertise, certification portfolios, and supply reliability.
Despite the favorable macro trajectory, the industry faces several structural inflection points that will separate resilient operators from those caught off-guard.
- Feedstock volatility and margin asymmetry. Corn starch economics are tightly coupled to agricultural commodity cycles. While recent U.S. corn futures for the July 2026 contract traded between USD 4.11 and USD 4.73 per bushel in early 2026, below the 2022 peaks and hovering near the 2015-2019 average of USD 3.50 per bushel, the structural risk remains. Feedstock cost advantages can compress quickly, forcing producers to rely on operational efficiency, long-term supply agreements, and formulation differentiation rather than raw material arbitrage alone.
- Regulatory divergence across pharmaceuticals and foods. The excipient and functional ingredient landscape is being reshaped by region-specific mandates. In India, draft guidance from the Central Drugs Standard Control Organisation issued in March 2025 requires domestic tablet manufacturers to source at least 30 percent of excipients from plant-based or mineral origins by 2028, favoring suppliers with ISO 9001 and Good Manufacturing Practice certifications. In China, the National Medical Products Administration mandated in August 2025 that new generic applications justify the use of synthetic excipients over natural alternatives, accelerating the transition to pregelatinized corn starch in Asian pharmaceutical manufacturing. These divergent requirements elevate compliance complexity and reward suppliers with robust quality systems and regional regulatory fluency.
- Substitution pressure and functional performance thresholds. End-use industries are increasingly demanding ingredients that deliver specific rheological, textural, or health-related properties without compromising cost or label cleanliness. The European Commission's Farm to Fork Strategy update in May 2025 targets a 15 percent reduction in average per-capita saturated-fat intake by 2030, driving substitution of butter or cream with enzymatically modified waxy corn starch. Meeting these performance benchmarks requires continuous R&D investment and close co-development with downstream customers, raising the barrier for commoditized entrants.
Core Demand Drivers Reshaping the Market
The market's growth is not a single-factor story. It emerges from the intersection of technical capability, policy direction, consumer and industrial behavior, and shifting cost structures. Understanding how these forces interact clarifies where value will accumulate over the next several years.
Technological Innovation and Formulation Breakthroughs
The most consequential advances are occurring in modification science and application-specific engineering. Enzymatic modification, pregelatinization, and resistant starch development are expanding the functional envelope of corn starch beyond traditional thickening and binding roles. In pharmaceuticals, pregelatinized grades are improving tablet compression characteristics and disintegration profiles, directly supporting generic manufacturing efficiency. In food and beverage, enzymatically modified waxy corn starch is enabling fat reduction while preserving mouthfeel, aligning with clean-label and health-forward product pipelines. These capabilities are not incremental; they redefine the ingredient's role from a bulk commodity to a performance enabler, which in turn supports premium pricing and longer-term customer lock-in.
Policy and Regulatory Tailwinds
Regulation is acting as both a filter and an accelerant. The U.S. Department of Agriculture's BioPreferred Program, reauthorized in the 2024 Farm Bill with a 40 percent budget increase, requires federal agencies to prioritize products containing at least 25 percent bio-based carbon. Since 100 percent plant-derived corn starch qualifies automatically, this policy creates a structural procurement advantage for bio-based formulations in government-adjacent and institutional supply chains. Meanwhile, pharmaceutical regulatory shifts in India and China are pulling demand toward plant-based excipients with verifiable quality certifications. The net effect is a policy environment that rewards certified, traceable, and bio-based corn starch offerings while penalizing opaque or synthetic-heavy supply chains.
Demand-Side Shifts in Consumer and Industrial Behavior
Downstream demand is being reshaped by three interrelated trends. First, food and beverage formulators are prioritizing texture modification, fat replacement, and clean-label positioning, which elevates the role of modified and specialty starches. Second, pharmaceutical manufacturers are optimizing excipient selection to meet regional mandates and improve process reliability, particularly in generic drug production where cost and compliance are tightly coupled. Third, industrial applications such as paper, corrugated, and technical coatings continue to rely on starch-based solutions for binding, sizing, and surface strength, but with growing expectations for consistency and supply security. These demand signals favor suppliers that can pair technical service with robust logistics and certification documentation.
Supply Chain and Cost Structure Dynamics
Cost structures are improving in the near term, but the long-term advantage will belong to operators who build resilience. The recent moderation in U.S. corn futures has lowered feedstock costs for corn starch production, providing margin relief and enabling reinvestment in capacity and quality systems. Yet the more strategic opportunity lies in supply chain design. Regional capacity expansions are reducing logistics friction and improving service levels for local markets. Certifications and quality management systems are becoming differentiators in regulated segments. Producers that integrate feedstock procurement, modification capability, and application support into a coherent value proposition will capture more of the margin pool than those competing solely on volume.
Potato Starch Market
Competitive Landscape and Strategic Positioning
The corn starch market is shaped by a mix of global agribusiness integrators, specialty starch specialists, and regional capacity builders. Their strategies reveal how value is being captured and where gaps remain for new entrants or focused challengers.
Large, diversified players are leveraging scale, integrated supply chains, and broad application portfolios to anchor their positions. Their advantage lies in the ability to serve multiple downstream industries simultaneously, smoothing cyclicality and cross-selling functional ingredients across food, beverage, industrial, and pharmaceutical channels. These firms are increasingly emphasizing modification technology and certification readiness to compete in higher-value segments rather than relying on commodity throughput alone.
PW Consulting
Specialty and regional operators are differentiating through formulation depth, pharma-grade quality systems, and localized service. Companies with strong positions in modified starches, resistant starches, and pharmaceutical excipients are capturing demand from tablet manufacturers, infant formula producers, and dairy formulators seeking reliable, certified inputs. Their strategic edge often comes from technical collaboration, rapid customization, and the ability to meet region-specific regulatory requirements without the overhead of a fully integrated global network.
Capacity expansion is a visible signal of where demand is heading. In October 2025, Al Ghurair Foods announced the phased completion of the UAE's first corn starch plant in the Khalifa Economic Zones Abu Dhabi, targeting processing capacity of up to 1,000 tons per day for food, pharmaceutical, paper, and chemical industries, with completion expected by the first quarter of 2026. This move reflects a broader pattern of regional supply 구축 to reduce logistics dependency and serve Middle East and Africa demand with shorter lead times and localized certification support. In May 2025, Cargill inaugurated a new corn milling plant in Gwalior, India, operated through Saatvik Agro Processors, to support increasing demand from confectionery, infant formula, and dairy sectors. The expansion underscores the strategic importance of India as a growth node for food-grade and specialty starches. In August 2025, Ingredion expanded its Cardinal plant in Ontario, Canada with a CAD 28 million investment to meet domestic and export demand for tablet manufacturers and specialty starches, highlighting the continued relevance of North American capacity for pharmaceutical and technical grades.
The competitive landscape is evolving along two axes. On one hand, consolidation pressure persists among the largest players as they seek to widen application coverage and secure feedstock and logistics advantages. On the other hand, differentiation is intensifying in specialty segments where certification, modification expertise, and regional compliance matter more than sheer scale. New entrants and regional challengers can succeed by targeting underserved application-grade combinations, building strong quality and regulatory profiles, and forming strategic partnerships with downstream formulators. The market is therefore not converging into a pure commodity oligopoly; it is fragmenting into performance tiers where technical service, certification, and supply reliability command measurable premiums.
Forward-Looking Trends and Commercial Implications
Looking ahead to the mid-2020s and toward 2032, several trends are likely to define the market's trajectory and create distinct commercial opportunities.
Bio-based procurement standards will become a structural advantage
As public procurement and institutional supply chains increasingly prioritize bio-based content, 100 percent plant-derived corn starch is well positioned to benefit from automatic qualification under programs like the USDA BioPreferred reauthorization. This trend favors suppliers that can document bio-based content, maintain consistent quality, and serve government-adjacent and institutional customers with reliable logistics. Commercial opportunity lies in aligning product portfolios with bio-based procurement criteria and building the certification and traceability infrastructure to capture these contracts early.
Pharmaceutical excipient substitution will accelerate in Asia and beyond
Regulatory guidance in India and China is nudging generic manufacturers toward plant-based excipients, with pregelatinized corn starch emerging as a preferred option for tablet compression and disintegration. As these mandates take effect, demand for pharma-grade, certified corn starch is likely to grow, particularly where suppliers can demonstrate GMP compliance and consistent batch-to-batch quality. The opportunity extends beyond Asia, as multinational generic producers align their excipient sourcing with the most stringent regional requirements to simplify compliance across markets.
Functional modification will drive value migration in food and beverage
The drive to reduce saturated fat, improve texture, and maintain clean labels is expanding the role of enzymatically modified waxy corn starch and other specialty grades. As formulators seek ingredients that deliver specific sensory and functional outcomes, the market will increasingly reward modification capability and co-development expertise. Commercial advantage will accrue to suppliers that can translate technical performance into measurable product benefits, support customer innovation pipelines, and secure long-term formulation partnerships rather than one-off transactions.
These trends carry inherent uncertainties. Feedstock prices could reverse course if weather patterns, trade policy, or energy costs disrupt agricultural markets, compressing margins for producers without hedging strategies or cost flexibility. Regulatory requirements may diverge further across regions, increasing compliance costs and complicating global supply strategies. Substitution risk also remains, as alternative starches, fibers, and synthetic excipients could capture share in specific applications if they offer better cost or performance profiles. Operators should therefore treat these trends as directional signals rather than guaranteed outcomes, and build optionality into capacity, certification, and customer engagement plans.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align capacity and capability with the segments where performance and compliance command premiums. This means investing in modification technology, pharma-grade quality systems, and bio-based documentation where demand is growing, while maintaining cost discipline in commoditized segments. Close technical collaboration with downstream formulators can shorten development cycles and lock in specification preferences early. Where regional demand is strong, localized capacity or partnership models can reduce logistics risk and improve service levels, as illustrated by recent expansions in the Middle East, India, and North America.
For investors, the market offers a differentiated risk-return profile across tiers. Commodity-scale operations provide volume and cash flow but face margin sensitivity to feedstock cycles and substitution pressure. Specialty and pharma-grade positions offer higher margins and regulatory-driven demand, but require sustained investment in quality systems, certifications, and technical service. Regional capacity plays can capture growth in underserved markets, though they carry execution and regulatory risk. A balanced view should weigh feedstock exposure, certification readiness, application mix, and the ability to serve regulated segments when evaluating potential investments or partnerships.
Modified Starch Market
For procurement and supply chain leaders, the strategic imperative is to diversify toward certified, bio-based, and functionally appropriate inputs while preserving supply security. Building relationships with suppliers that can demonstrate GMP compliance, ISO quality systems, and consistent bio-based content will reduce regulatory and reputational risk, particularly in pharmaceutical and institutional procurement. Qualifying multiple grades and regions can mitigate disruption risk, while co-development with suppliers can unlock formulation improvements that reduce total cost of ownership. In a market where performance and compliance increasingly determine supplier selection, procurement strategy should be treated as a value-creation function rather than a cost-minimization exercise.
The corn starch market is transitioning from a volume-driven commodity landscape to a performance-and-compliance-led specialty market. Capturing the available opportunities requires timely access to granular segmentation data, regional regulatory mapping, and supplier-level capability assessments. Decision-makers who integrate these inputs into capacity planning, investment selection, and procurement strategy will be better positioned to navigate feedstock volatility, regulatory divergence, and functional substitution while participating in the market's projected growth trajectory through 2032.
For detailed analysis of this topic, please visit the official page: Corn Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com