

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Steel Roofing Market Set to Hit $27B by 2032: 5 Key Drivers Behind the 6.5% CAGR Surge

Steel Roofing Market: Navigating Growth, Resilience, and Strategic Opportunities Through 2032
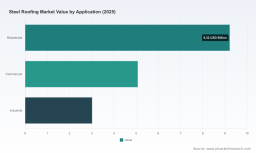
The global steel roofing market has entered a period of sustained expansion, underpinned by durable construction demand, evolving material performance standards, and shifting sustainability expectations. Revenue reached approximately $17.3 billion in 2025, reflecting a broader trajectory that has seen the sector climb from roughly $12.7 billion in 2020. Over the full forecast window extending to 2032, the market is projected to advance at a compound annual growth rate of 6.5 percent, reaching a valuation near $27 billion by the close of the decade. This growth is not merely a function of incremental volume; it reflects structural repositioning in how steel roofing is specified, manufactured, installed, and repurposed across residential, commercial, and industrial applications. For decision-makers, the scale of expansion masks beneath the surface a set of nuanced transitions in product design, regional demand intensity, raw material exposure, and competitive positioning. Understanding these dynamics is essential for aligning capital allocation, product portfolios, and go-to-market strategies with the market's next phase of evolution.
市场现状与核心挑战
Steel roofing has matured from a utilitarian building component into a differentiated product category where longevity, weather performance, and recyclability increasingly factor into procurement decisions. The transition is visible in the steady upward revision of revenue estimates and in the way buyers are evaluating upfront costs against multi-decade service life. At a market concentration that leaves a substantial share of activity outside the top tier, the competitive space remains heterogeneous, with large-scale manufacturers, specialized formulators, and regional fabricators competing across different price and performance bands. This fragmentation is simultaneously a hallmark of resilience and a source of strategic friction, because buyers can choose from a wide spectrum of solutions, but vendors must navigate uneven margin structures and highly localized specification habits.
Three interconnected challenges define the current inflection point. The first is cost volatility tied to base material inputs. Market participants are operating in an environment where steel coil pricing has shifted sharply over recent periods, creating margin uncertainty for manufacturers and pricing complexity for distributors and end-users. The second challenge is the alignment of product standards with increasingly stringent performance expectations. Buyers and regulatory bodies are paying closer attention to structural integrity, water penetration resistance, and long-term durability, which elevates the importance of testing, certification, and engineering documentation in winning specification decisions. The third challenge is converting environmental advantages into commercial preference at scale. The category's recyclability and long service life are compelling claims, yet translating them into consistent demand requires more than technical merit; it depends on customer education, procurement frameworks, and the ability to demonstrate whole-life value in comparison with alternative materials.
These challenges are not obstacles that simply need to be survived. They are signals of where value is migrating. Manufacturers that can stabilize input exposure, demonstrate verifiable performance, and articulate lifecycle economics are positioned to capture share from competitors that continue to compete primarily on initial price. For investors and strategic planners, the implication is clear: the market's growth story is increasingly tied to capabilities in cost management, compliance readiness, and value communication rather than capacity expansion alone.
关键驱动因素分析
The expansion of steel roofing is being propelled by a set of reinforcing drivers that cut across technology, policy, demand behavior, and supply-side economics. Taken together, they are reshaping what buyers expect and what producers must deliver.
技术创新与产品性能演进
Product design innovation is moving steel roofing beyond conventional profiles toward systems that combine structural efficiency, installation practicality, and architectural versatility. Recent introductions such as new metal roofing panel designs reflect a broader push to improve compatibility with different substrates, climatic conditions, and aesthetic requirements. Parallel advances in accessory systems, including fall protection anchor solutions tailored to snap-lock panel installations, indicate that the differentiation frontier is expanding beyond the panel itself to the ecosystem of installation and worker safety. These developments matter because they lower adoption friction: when a roofing system is easier to specify, install, and maintain, specification cycles shorten and buyer confidence improves. For manufacturers, the strategic question is whether to compete through incremental design refinement or to lead with platform-level innovation that can serve multiple end-use segments without fragmenting production complexity.
政策、标准与监管环境
Regulatory and standardization activity is sharpening the performance baseline for steel roofing systems. Updated structural standards for standing seam roof panel systems and water penetration testing protocols are pushing the market toward more rigorous verification of durability and weathertightness. Rather than merely constraining the market, these standards are shaping a competitive environment in which documented compliance becomes a commercial asset. Specifiers in commercial and institutional projects, in particular, are increasingly relying on certified performance criteria to reduce project risk. In this context, manufacturers that maintain robust testing programs and clear alignment with recognized standards gain credibility that can translate into repeat specification and stronger positioning in tenders and design-led projects. The broader implication is that compliance is not a cost center to be minimized; it is a differentiator that can create defensible demand in segments where long-term performance is heavily weighted.
需求侧变化与行为迁移
On the demand side, procurement behavior is increasingly influenced by the combination of lifespan expectations and end-of-life recyclability. Steel roofing's long average service life and full recyclability at end of use resonate with buyers who are evaluating whole-project economics rather than first-cost alone. This shift is especially relevant in markets where replacement cycles, maintenance exposure, and disposal considerations are receiving greater attention. Residential applications continue to play a major role in volume, supported by replacement demand and aesthetic upgrading, while commercial and industrial users are prioritizing reliability, standardized performance, and ease of integration with broader building systems. The trend is not uniform across segments, but the directional signal is consistent: buyers are more receptive to durable solutions when the value case can be framed in terms of lifecycle cost, reduced maintenance exposure, and material circularity.
供应链与成本结构的调整
Supply-side dynamics are exerting both pressure and opportunity. Elevated hot rolled coil steel prices relative to prior-year levels illustrate how raw material cost movements can compress margins and trigger price adjustments downstream. At the same time, cost pressure is encouraging operational discipline, including improved yield management, product mix optimization, and closer coordination between fabrication capacity and demand geography. The market's response to input volatility is revealing which players have invested in flexible production arrangements, inventory strategy, and contracting models that can absorb price fluctuations without sacrificing competitiveness. For the sector as a whole, cost structure is becoming a strategic variable as important as product features, because the ability to manage cost pass-through, protect margin integrity, and maintain service continuity will influence both share stability and customer retention.
These four drivers are not independent. Technology improvements influence specification under stricter standards; performance credibility strengthens demand-side adoption; and cost discipline determines whether innovation and compliance investments can be scaled profitably. The market is rewarding participants that treat these elements as an integrated system rather than as separate workstreams.
竞争格局与领先策略
The competitive landscape is populated by manufacturers with distinct reputations across residential, commercial, and industrial end-use markets. Several large U.S.-based producers have established positions through broad product line breadth, established distribution relationships, and strong brand familiarity among contractors and specifiers. Their scale allows them to serve multiple application types, which is valuable in a market where project types vary widely and where the ability to offer related panels, accessories, and system-level components can reduce procurement complexity for buyers. Alongside these broader specialists, other manufacturers have built identities around particular product strengths, such as stone-coated aesthetics, architectural detailing, or commercial panel solutions. This mix of scale players and specialized producers creates a layered competitive environment in which differentiation often comes from the fit between product attributes and project requirements rather than from price alone.
Leading strategies in this environment tend to converge around a few recognizable approaches. One is portfolio breadth that enables cross-application coverage, allowing a manufacturer to capture demand from a single customer or specification source across multiple project types. Another is product-line specialization, where a narrower range is developed to a higher level of performance or visual refinement, supporting premium positioning and repeated specification in targeted segments. A third approach is ecosystem development, including accessories and installation-support solutions that make a roofing system more practical to deploy and maintain. The recent introduction of new panel series and fall protection anchor systems illustrates this ecosystem-oriented thinking: companies are increasingly aware that winning in steel roofing is not only about the panel, but also about the installation context and the safety, speed, and reliability of the overall system.
Worldwide Roofing Market
The competitive trajectory is likely to involve both consolidation and continued segmentation. Consolidation can create advantages in procurement leverage, manufacturing efficiency, and geographic coverage, particularly for players seeking to scale their position against volatile input costs and rising compliance expectations. At the same time, segmentation is expected to persist because project-specific requirements, regional specification habits, and design preferences continue to reward targeted solutions. New entrants and smaller manufacturers can still find room by focusing on underserved niches, specialized coatings or finishes, or regionally concentrated customer relationships. The more durable competitive threat may come not from sheer capacity, but from organizations that combine credible performance documentation, stable cost management, and clear installation value into a repeatable commercial proposition.
A useful way to read the competitive field is to ask where each player is most difficult to displace. For some, it is breadth and supply reliability; for others, it is a particular performance profile or design language; for still others, it is the strength of contractor and distributor relationships. The companies that are expanding their strategic options are generally those that are reducing customer switching costs in positive ways, by offering integrated system solutions, clearer performance evidence, or more predictable commercial terms.
未来趋势预测
Looking across the next three to five years, three trends are likely to shape how the steel roofing market evolves and where profitable opportunities emerge.
PW Consulting
性能验证与标准契合度将成为获胜因素
As specification practices become more risk-aware and performance expectations tighten, verifiable durability and water penetration performance will increasingly influence procurement decisions. The trend favors companies that can provide clear documentation, repeatable testing alignment, and engineering support that simplifies specification. The commercial opportunity lies in turning standards compliance into a reliable source of preference, particularly in commercial and institutional segments where project risk reduction carries substantial weight. The associated uncertainty is that compliance expectations may continue to rise, requiring sustained investment in testing infrastructure and technical sales capability.
循环经济与寿命优势的商业化将加速
The combination of long service life and full recyclability is well suited to growing interest in material efficiency and end-of-life responsibility. Over the forecast period, more buyers are likely to frame roofing decisions around lifecycle value, maintenance exposure, and material recovery, especially where procurement mandates or corporate sustainability objectives are in play. The opportunity is to build value narratives that connect technical performance with circularity in a way that procurement teams can act upon. The risk is that environmental attributes may be overstated or undervalued depending on local market maturity, meaning that claims must be matched with clear proof points and credible comparison frameworks.
成本韧性将区分领导者与追随者
Raw material price sensitivity is expected to remain a persistent feature of the operating environment. Companies that can manage input exposure through mix strategy, production discipline, and transparent commercial terms will be better positioned to preserve margin integrity while sustaining volume growth. This creates a strategic opportunity for manufacturers and supply partners that can offer predictability, whether through product configurations that optimize yield, contracting structures that share risk responsibly, or regional production footprints that reduce freight and inventory burden. The uncertainty is that cost volatility can reshape comparative advantage quickly, and players that depend on narrow margin buffers may face pressure if input trends shift materially.
These trends point toward a market in which growth is increasingly earned through credibility, efficiency, and integration rather than through volume alone. For businesses evaluating their next moves, the most valuable question is not whether the market will expand, but which capabilities will determine who captures the higher-value portions of that expansion.
决策者行动建议
Different participant types will derive value from different strategic priorities, but several practical actions apply across the board.
Metal Roofing Market
-
For manufacturers, invest in the intersection of product performance, installation practicality, and cost discipline. That means maintaining rigorous testing and standards alignment, expanding system-level accessories that reduce installation friction, and improving production flexibility to respond to input volatility without eroding margin. Companies that can present steel roofing as a coherent, low-friction solution rather than a commodity panel are better positioned to defend price and win repeat specification.
-
For investors, evaluate exposure to the segments and capabilities most likely to benefit from durability-driven demand and lifecycle value framing. Look for operators with credible compliance documentation, diversified end-use reach, and operational strategies that can withstand raw material swings. The opportunity is strongest where growth is supported by structural demand and where differentiation is built on verifiable performance and efficient cost management rather than on temporary input advantages.
-
For procurement and specifier teams, broaden the evaluation framework beyond first cost. Give appropriate weight to service life, maintenance exposure, water penetration and structural performance evidence, and material recyclability. Where possible, standardize on solutions that reduce project risk and installation complexity, and request documentation that supports whole-life comparisons. This approach can improve project outcomes and reduce downstream exposure to performance-related issues.
In a market expanding at a steady multi-year pace, the practical edge comes from access to granular insight: which product segments are expanding fastest, how regional demand intensity is shifting, where price and margin pressure is concentrated, and how leading competitors are positioning their portfolios. Detailed segmentation, scenario modeling, and competitor-level benchmarking can sharpen those decisions and reduce the risk of acting on averages rather than on the segments that matter most. For teams that want to move from high-level awareness to targeted action, a deeper review of the full research can provide the segmented detail and customized context needed to prioritize investments, pricing strategy, specification support, and regional expansion with greater precision.
For detailed analysis of this topic, please visit the official page: Steel Roofing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com