

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
Car Batteries Market Analysis: Why 5.75% CAGR and Regional Shifts Redefine Growth
By pmarketresearch, 2026-09-21
The Car Batteries Market: Navigating Transition, Value Chains, and Strategic Opportunities
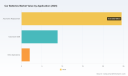
The automotive energy storage landscape is entering a decisive inflection point. Measured in billions of U.S. dollars, the total market expanded from roughly $27.85 billion in 2020 to $35.4 billion in 2025, reflecting a compound annual growth rate of 5.75 percent through 2032. The trajectory is not a straight line. After a dip in 2022, volumes recovered through 2023 and 2024, and the forecast path shows steady expansion with a modest plateau near 2029 before renewed acceleration. This pattern matters because it reveals a market that is maturing in conventional segments while reallocating capital toward new chemistries, regional supply strategies, and application-specific designs. For executives and investors, the central question is no longer whether the market will grow, but where margin, scale, and resilience will concentrate over the next cycle.
Three structural challenges define the current turning point. First, the industry is balancing a dominant incumbent chemistry with a faster-growing alternative that carries different economics, sourcing risks, and performance expectations. Second, regional trade and resource policies are reshaping cost structures and forcing companies to rethink where they source, assemble, and sell. Third, the application mix is shifting as original equipment demand evolves alongside a large and still-growing replacement segment, creating diverging requirements for durability, service life, and total cost of ownership. These forces interact rather than operate in isolation, which is why portfolio strategy and geographic positioning now matter as much as unit economics.
PW Consulting
Key Drivers Reshaping the Market
Technology Innovation and Product Differentiation
Innovation is no longer confined to a single chemistry roadmap. Advanced lead-acid designs continue to improve performance in start-stop, micro-hybrid, and certain backup roles, while lithium-ion platforms extend their footprint in applications that reward higher energy density and longer cycle life. The practical impact is a widening performance envelope across the product spectrum. Manufacturers are differentiating through tighter tolerances, improved thermal behavior, and application-tuned durability rather than competing solely on price. This matters for buyers because the selection criterion is shifting from price per unit to risk-adjusted service life, integration complexity, and warranty exposure. For producers, the strategic prize is to align product architecture with the duty cycle of each application, capturing premium segments where reliability and consistency justify higher value.
Policy and Regulatory Environment
Regulation is becoming a first-order driver of sourcing, pricing, and competitive positioning. Trade actions and export controls are altering the cost baseline for key materials and components, while regional content expectations are pushing development of more localized supply chains. Recent movements in trade policy illustrate the point: tariffs on selected graphite imports into the United States and adjustments to export controls on battery-related components and materials in other major economies have added new layers of cost and compliance. These measures do more than move prices in the short term. They influence where capacity is built, which suppliers are viable across regions, and how quickly product specifications must adapt to meet local content or traceability expectations. The durable takeaway is that regulatory trajectory now belongs in the core of product planning, not in a separate compliance function.
Demand-Side Shifts in Consumer and Fleet Behavior
Demand patterns are bifurcating. A substantial portion of activity continues to come from replacement and aftermarket needs, where fleet managers, service networks, and individual consumers prioritize availability, interchangeability, and predictable cost. At the same time, original equipment demand is being reshaped by vehicle electrical architectures that place different burdens on energy storage, especially in hybrids and vehicles with higher accessory loads. The practical result is that volume growth is being accompanied by more demanding specifications in a subset of applications, while the replacement market keeps the baseline stable. For commercial buyers, the implication is to manage two different procurement logics at once: one optimized for uptime and service simplicity, the other optimized for integration and performance over a longer design life.
Supply Chain and Cost Structure Dynamics
Material prices and sourcing options are reintroducing volatility into cost planning. Spot prices for lithium carbonate, for example, moved sharply lower through mid-2025 before rebounding to a materially higher range by early 2026, a swing that affects input planning for lithium-based products and influences the relative economics of different chemistries. At the same time, cobalt availability has come under tighter constraints, with export measures converting into quota systems that contributed to price increases over the course of the year. These dynamics are not abstract. They change the relative attractiveness of design choices, the timing of capacity commitments, and the value of supplier relationships that offer flexibility or alternative material pathways. Companies that treat procurement as a strategic lever rather than a transactional function are better positioned to absorb swings without eroding margins.
Competitive Landscape and Leading Strategies
Incumbents With Scale and Application Focus
The market is led by a group of established manufacturers with deep application knowledge and broad distribution. East Penn Manufacturing operates one of the largest single-site lead-acid production platforms, with product lines spanning flooded, AGM, and gel technologies for automotive use, including start-stop systems. Its recent expansion of EHP and Extreme Power AGM automotive lines, along with a dedicated EV and hybrid battery navigation section on its website, signals an effort to make advanced lead-acid options easier to identify and specify as vehicle electrification needs broaden. GS Yuasa International remains a major producer of high-performance lead-acid batteries for original equipment and aftermarket channels, with a long-standing emphasis on reliability and application fit. Exide Industries continues to scale its position across passenger cars and commercial vehicles, leveraging a broad manufacturing footprint and strong regional reach. Together, these companies illustrate how incumbents defend their position by combining scale, service networks, and product breadth rather than relying on a single technology narrative.
Specialists and Integrated Suppliers Extending Their Reach
A second layer of competitors competes through specialization and integration. Kung Long Batteries focuses on lead-acid products for automotive, motorcycle, and marine use, with manufacturing operations structured to support export-oriented volume. Furukawa Battery Co. has built recognition around advanced lead-acid technologies, including UltraBattery and AGM variants for starting and hybrid applications, positioning itself where performance under partial state-of-charge and cycling matters. Clarios operates as a global automotive battery producer with well-known consumer and retail brands, giving it strong visibility in replacement channels. Robert Bosch and Denso Corporation bring complementary strength through components and thermal management integration, linking battery supply to broader vehicle electrical and thermal systems. EnerSys rounds out the field with automotive and industrial battery offerings, including AGM and flooded types, where stationary and commercial demands intersect with automotive requirements. The differentiating theme among these players is the ability to serve specific application needs or to integrate battery hardware into wider system solutions, rather than competing purely on commodity volume.
Battery Market
Market Structure and Evolution Pathways
Concentration in the market is moderate. The three largest firms account for roughly 37.4 percent of revenue, while the top five approach 51.2 percent, leaving meaningful room for regional leaders, specialists, and brand-driven retail channels. This structure shapes strategy in two ways. First, it allows differentiated players to win in niches by solving specific performance, service, or integration problems. Second, it creates pressure for scale players to defend share through cost discipline, distribution strength, and portfolio breadth. The likely evolution is a combination of consolidation at the top, continued regional strength below the leaders, and selective entry by new participants where a clear application advantage or supply advantage can be established quickly. For buyers and investors, the important signal is that leadership will increasingly be measured by the ability to manage technology transitions, regional sourcing, and application-specific value rather than by volume alone.
Future Trends and Commercial Implications
Chemstry Coexistence and Application-Specific Design
Over the next three to five years, the market is likely to see continued coexistence of advanced lead-acid and lithium-ion solutions, with the split shaped by application requirements, total cost of ownership, and regional economics rather than by a single replacement curve. This creates clear commercial opportunities for suppliers that can engineer for specific duty cycles, demonstrate reliability in service, and simplify specification for buyers. The opportunity is not simply to offer both chemistries, but to reduce the decision burden for customers by matching product architecture to real-world use, backing claims with consistent quality, and aligning warranty and support structures accordingly. The principal risk is misjudging the pace of adoption in applications where expectations are rising faster than cost structures can justify, which can leave inventory or positioning misaligned with demand.
Regionalization of Supply and Sourcing Flexibility
Trade policy and resource constraints are accelerating a shift toward more regionally aware sourcing and, in some cases, more localized assembly or component supply. The commercial implication is twofold. Companies can gain from nearer-term supply resilience and improved alignment with regional content expectations, but they must also absorb higher coordination costs and potentially higher input prices in the short run. The strategic opportunity lies in building a flexible supplier base, qualifying alternative materials or sub-suppliers where feasible, and designing products that can tolerate modest specification changes without compromising performance. The risk is overcommitting to a single geography or a single sourcing route in a period when trade measures and export controls can change quickly, as seen with graphite tariffs and adjustments to battery-related export controls.
Value Migration Toward Integration and After-Sales Reliability
As vehicle electrical systems become more complex and replacement demand remains large, value is migrating toward providers that can reduce downtime, simplify servicing, and deliver consistent performance across a wide installed base. For manufacturers, this means investing in quality consistency, traceability, and support models that matter to fleet operators and service networks. For channel and retail partners, it means winning on availability, brand trust, and clear differentiation in product tiers. For OEMs and Tier-1 integrators, it means treating energy storage as part of a broader system where thermal behavior, charging profiles, and service life interact with vehicle design. The risk in this trend is underinvestment in the service and reliability dimension, which can erode margin even when unit sales grow, particularly in markets where replacement activity remains the backbone of demand.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product roadmaps with application realities and to build sourcing flexibility into the cost model. That means mapping each product line to the duty cycle it is designed for, stress-testing specifications against material price volatility, and maintaining qualified alternatives for critical inputs where possible. It also means treating advanced lead-acid and lithium-ion portfolios as complementary tools rather than competing narratives, using each where its economics and performance profile are strongest. Companies that can reduce specification friction for buyers and demonstrate dependable service life will capture more value than those competing on unit price alone.
Primary Battery Market
For investors, the central task is to assess which players are positioned to earn durable margins through the current transition. Look for evidence of application-specific differentiation, distribution strength in replacement channels, and supply strategies that reduce exposure to concentrated sourcing or abrupt trade changes. Favor organizations that combine scale with clear technical focus, because that combination tends to preserve pricing power while allowing selective growth in higher-value segments. Be cautious about assumptions that any single chemistry shift will simplify the competitive field; the more likely outcome is a wider, more application-diverse market in which execution quality determines who captures premium positioning.
For procurement and supply-chain leaders, the actionable step is to manage the baseline and the innovation path at the same time. Maintain a resilient core supply arrangement for high-volume replacement needs, where availability and interchangeability are paramount, while establishing a separate evaluation track for new specifications tied to OEM or hybrid applications. Build visibility into input price cycles and policy developments so that purchasing decisions do not lag behind market changes. Where possible, structure contracts and supplier relationships to preserve optionality, because the next few years are likely to bring further swings in material costs and regional trade conditions rather than a return to a stable baseline.
The strategic picture is clear enough to act on, but the granular choices depend on segment-specific data, regional cost structures, and the timing of policy and material movements. Detailed segmentation, regional revenue splits, application-level volumes, and company-level benchmarking provide the precision needed to convert these trends into concrete plans. For teams that require that level of detail, the full PW Consulting report on the car batteries market offers deeper figures, scenario breakdowns, and customized recommendations aligned to specific business models and geographies.
For detailed analysis of this topic, please visit the official page: Car Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fuel Cell Membranes Market: Why 17.4% CAGR and APAC Shift Redefine Growth
By pmarketresearch, 2026-09-21
Fuel Cell Membranes Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
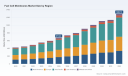
The fuel cell membranes market has evolved from a niche component sector into a critical enabler of the broader hydrogen economy. Measured by global revenue, the industry generated approximately 671.23 USD Million in 2025, up from 423.74 USD Million in 2020. This trajectory reflects a compound annual growth rate of 17.4 percent through 2032, with revenue projected to surpass 1.2 billion USD Million by the end of the forecast period. The growth is not uniform. Demand is spreading across stationary power, transportation, and portable applications, while regional momentum is shifting toward Asia Pacific, followed by Europe and North America.
Behind these headline figures, the industry is navigating a series of structural tensions. First, membrane performance must keep pace with increasingly stringent operational requirements. Fuel cell stacks are being pushed toward higher power densities, lower operating temperatures in some configurations, and longer lifetimes in harsh environments. Meeting these demands requires membranes that balance proton conductivity, mechanical durability, and chemical stability, a combination that remains technically demanding even as material science advances.
Second, cost and supply chain resilience are becoming decisive competitive factors. The membranes segment relies on specialized polymers, ionomers, and precise manufacturing processes that have historically been concentrated among a small number of suppliers. As scale increases, manufacturers are under pressure to reduce bill-of-materials costs while maintaining quality consistency. Any disruption in raw material availability or production capacity can ripple through downstream stack assembly and system deployment timelines.
Third, the market is experiencing a policy-driven inflection point. Public support for hydrogen technologies is expanding, but the pace and shape of that support vary widely across jurisdictions. Incentive structures, emissions criteria, and technical targets are reshaping what qualifies as commercially viable. Companies that cannot align their product roadmaps with evolving regulatory expectations risk being sidelined, even if their technology is technically sound.
Key Drivers of Market Change
Technology Innovation and Material Breakthroughs
Material innovation is the most direct lever for expanding the addressable market for fuel cell membranes. Researchers and manufacturers are pursuing thinner membranes with higher proton conductivity, improved thermal and mechanical robustness, and reduced reliance on scarce or costly inputs. These improvements matter because they influence stack efficiency, system size, and lifetime performance. A membrane that conducts more effectively at lower thickness can enable more compact stacks, which in turn opens new design possibilities for vehicles, stationary units, and portable devices.
Recent technical targets from the U.S. Department of Energy illustrate the direction of travel. The department has articulated performance expectations for PEM fuel cell components that include membranes with less than 10 micrometer thickness and proton conductivity around 0.2 S/cm at 80 degrees Celsius. These benchmarks are not merely laboratory aspirations; they signal the performance threshold that commercialization efforts increasingly need to meet. Companies that can deliver membranes consistently at or near these specifications are better positioned to win contracts in mobility and stationary applications where efficiency and packaging constraints are tight.
Policy and Regulatory Environment
Policy support is reshaping both demand and economics. In the United States, the Inflation Reduction Act provides a Clean Hydrogen Production Tax Credit of up to 3 USD per kilogram for hydrogen with well-to-gate emissions below 0.45 kg CO2e per kg H2. This incentive changes the economics of hydrogen supply, which in turn affects the attractiveness of fuel cell deployments that depend on affordable, low-carbon hydrogen. When hydrogen production becomes more cost-competitive, downstream applications become more viable, and membrane demand follows.
Alongside production incentives, technical targets and cost-roadmap goals are influencing procurement and product development. U.S. Department of Energy multi-year plans outline hydrogen production cost targets of 2 USD per kilogram by 2026 and 1 USD per kilogram by 2031. These targets frame the cost structure that fuel cell systems, including membrane-based components, need to support. The implication is clear: membrane suppliers and system integrators must anticipate not just performance requirements, but the cost trajectory that policy and public investment are pushing the industry toward.
PW Consulting
Demand-Side Behavior and Application Expansion
Demand is broadening beyond early adopters and demonstration projects. Stationary applications continue to represent a substantial share of membrane demand, driven by power generation, backup power, and distributed energy needs. Transportation remains a strong growth vector, particularly where electrification alternatives face range, payload, or refueling time constraints. Portable applications add another layer of diversification, though at a smaller scale.
A telling example of how demand can pivot comes from the stationary power segment. In November 2025, Ceres Power signed a manufacturing licence agreement with Weichai Power for production of Ceres-designed fuel cells and stacks targeting stationary power markets, including AI data centres. This agreement highlights how fuel cell technology is being positioned for high-value, continuous-power applications where reliability and footprint matter. For membrane suppliers, such partnerships expand the pool of potential manufacturing and deployment partners, while also signaling that data centre and critical infrastructure power needs are becoming a strategic demand source.
Supply Chain and Cost Structure Shifts
Cost reduction is increasingly tied to vertical integration, manufacturing scale, and material strategy. Several companies are expanding in-house capacity for membrane-related components, including membrane electrode assemblies, to gain control over quality, lead times, and unit economics. Roll-to-roll manufacturing and other continuous production methods are being explored to improve throughput and consistency. At the same time, supply chain resilience has become a priority, with U.S. Department of Energy project work identifying membrane and ionomer materials as critical components for both supply chain resilience and cost reduction in fuel cell manufacturing.
For commercial strategy, this means that membranes are no longer just a performance component; they are a strategic supply chain asset. Companies that can secure reliable material inputs, optimize manufacturing processes, and reduce dependency on a narrow supplier base are gaining an advantage. Conversely, organizations that rely on fragmented sourcing or lack visibility into material availability may face cost volatility and deployment delays.
Competitive Landscape and Leading Strategies
The competitive field is defined by a mix of system integrators, component specialists, and manufacturers pursuing in-house production of membrane-related assemblies. Market concentration remains notable, with the top three companies accounting for roughly 61 percent of market revenue and the top five reaching about 67 percent. This concentration suggests that scale, brand recognition, and established customer relationships still matter greatly, even as innovation and niche differentiation create openings for new entrants.
Ballard Power Systems, based in Burnaby, British Columbia, Canada, is one of the most recognized names in PEM fuel cell systems. Its profile centers on designing, developing, manufacturing, and selling fuel cell systems for mobility, stationary, and marine applications. Proprietary membrane electrode assemblies, including membranes, form a core part of its fuel cell stacks. Ballard’s strategic positioning is built on broad application coverage and long-standing system-level expertise, which gives it visibility across multiple end markets and a platform for iterative membrane and MEA improvements tied to real-world stack performance.
Plug Power Inc., headquartered in Latham, New York, USA, operates as a manufacturer and supplier of PEM fuel cell systems and MEAs, with in-house production of membranes for its GenDrive mobility and GenSure stationary products. This in-house capability is strategically significant. By controlling more of the membrane and MEA supply chain, Plug Power can better align component production with its system roadmap, reduce dependency on external suppliers, and respond more quickly to volume changes. Its commercial focus on both mobility and stationary applications also diversifies revenue exposure.
Hyzon Motors Inc., based in Bolingbrook, Illinois, USA, develops and manufactures high-performance hydrogen fuel cell systems and operates an in-house roll-to-roll membrane electrode assembly manufacturing line for proprietary components. This manufacturing approach points to a strategy centered on performance customization and production control. For Hyzon, the ability to produce proprietary membrane-related components in-house supports differentiation in the commercial vehicle and heavy-duty segments, where performance, durability, and system integration are central buying criteria.
Freudenberg e-Power Systems, located in Weinheim, Germany, supplies fuel cell components including membranes and seals for PEM and other fuel cell technologies. Its role illustrates a different competitive posture: component supply and engineering partnership rather than full system branding. Freudenberg’s strengths lie in material expertise, precision component supply, and the ability to serve multiple customers and applications through a focused components business. This model can be attractive in a market where some system builders prefer to source advanced membranes and related parts from specialized suppliers rather than internalize all production.
The recent Ceres Power and Weichai Power agreement also illustrates a broader competitive trend: licensing and partnership models are becoming more prominent alongside direct manufacturing. In this case, the agreement targets stationary power markets including AI data centres, signaling that intellectual property and licensed manufacturing can be a viable route to scale, especially when paired with a strong local manufacturing partner. This pattern suggests the competitive landscape is not only about who makes membranes, but also about who controls the design, licensing, and deployment pathways that turn membrane technology into deployed systems.
Strategic Evolution: Consolidation, Fragmentation, and New Entry
The market is showing signs of both consolidation and fragmentation, depending on the segment. In established system-level applications, scale advantages and customer qualification cycles favor larger players with proven track records. At the same time, new entry remains possible in component supply, specialized membrane formulations, and licensed manufacturing. The presence of in-house MEA production among several leading companies indicates that vertical integration is becoming a more common response to cost, quality, and supply chain concerns.
At the same time, end-use diversification is fragmenting demand patterns. Stationary, transportation, and portable applications each impose different technical and commercial requirements, which means a single membrane strategy is rarely sufficient. Companies that can tailor products to application-specific needs, or that can supply a broad range of customers through component Sales, are better positioned to capture growth across multiple demand pockets. The strategic question is whether to compete as a system-level brand, a high-value component supplier, or a licensed technology partner. Each path carries a different risk-return profile.
Future Trends and Commercial Implications
Trend 1: Performance-Barrier Reduction and Wider Adoption
As membrane technology advances toward thinner, more conductive, and more durable formulations, the performance barriers that have limited adoption in certain applications are likely to ease. This trend should support broader use in transportation and stationary deployments where efficiency, packaging, and operating lifetime are decisive. Commercially, this creates opportunities for suppliers that can reliably meet higher performance expectations while maintaining cost discipline. It also raises the stakes for producers that fail to keep pace with evolving specifications.
Ceramic Membrane Market
Trend 2: Policy-Aligned Economics Becoming a Purchasing Criterion
Hydrogen production incentives, emissions thresholds, and cost targets are increasingly shaping procurement decisions. Buyers are not just evaluating membrane performance; they are evaluating how component choices fit into a broader system that must meet policy-driven cost and emissions expectations. This trend favors suppliers and integrators that can articulate the link between membrane selection, stack efficiency, hydrogen utilization, and total cost of ownership. It also means that regulatory developments in major markets can quickly alter demand patterns, making policy monitoring a core business function rather than a peripheral activity.
Worldwide Breathable Membranes Market
Trend 3: Manufacturing Control and Supply Chain Resilience as Competitive Moats
As volumes grow, manufacturing capability and material security will become more important differentiators. Companies with in-house MEA production, continuous manufacturing processes, and diversified material sourcing are likely to be better positioned to manage cost, quality, and lead-time risk. This trend could accelerate partnership, licensing, and selective vertical integration across the value chain. It also introduces a cautionary note: over-investment in fixed manufacturing capacity without aligned demand can create financial strain, especially if deployment timelines shift or policy support changes.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Policy support may change in pace or design, affecting hydrogen economics and demand timing. Technical targets may prove difficult to meet consistently at scale, especially under real-world operating conditions. Raw material availability and pricing can affect margin stability, particularly for specialized polymers and ionomers. Finally, competition from alternative power technologies, including advances in batteries and hybrid systems, continues to shape the commercial context in which fuel cell membranes are evaluated. These risks do not negate the growth outlook, but they do suggest that strategy should be built around flexibility, scenario planning, and close monitoring of both technology and policy developments.
Actionable Recommendations for Decision-Makers
For Manufacturers and Component Suppliers
- Align membrane development with application-specific performance targets rather than pursuing a single universal specification. Stationary, transportation, and portable uses impose different durability, conductivity, and packaging needs, and product portfolios should reflect that reality.
- Evaluate selective vertical integration or partnership models for membrane electrode assemblies and related components. In-house capability can improve quality control and responsiveness, but it should be weighed against capital intensity and demand uncertainty.
- Treat material security and manufacturing resilience as strategic priorities. Diversify sourcing where possible, monitor critical material dependencies, and build production processes that can support consistent quality at higher volumes.
For Investors
- Focus on companies with clear pathways to scale, whether through in-house manufacturing, licensing, or strong system-level customer relationships. Revenue concentration in the market means that competitive positioning and customer access are especially important.
- Assess exposure to policy-driven economics, particularly hydrogen production incentives and technical targets that influence downstream demand. Companies that can connect their component or system offerings to these macroeconomic drivers may have stronger commercial momentum.
- Watch for partnerships and licensing agreements that expand reach into high-value stationary applications, such as data centre power and critical infrastructure, where reliability and continuous operation can support premium positioning.
For Procurement and Strategic Buyers
- Evaluate membrane and MEA suppliers not only on performance specifications, but also on manufacturing reliability, supply chain transparency, and the ability to support long-term volume needs. Qualification cycles are often long, so supplier stability matters.
- Consider total system economics, including how membrane choices affect stack efficiency, lifetime, and hydrogen utilization. In policy-supported markets, these factors can be as important as upfront component cost.
- Plan for evolving technical targets and regulatory expectations. Procurement strategies should remain flexible enough to accommodate performance improvements and cost changes as the market matures.
Conclusion
The fuel cell membranes market is entering a phase where performance, cost, policy, and supply chain strategy are tightly intertwined. Growth is supported by expanding demand across stationary, transportation, and portable applications, while technical targets and hydrogen economics are sharpening the requirements that suppliers must meet. Market concentration indicates that scale and established relationships remain powerful advantages, but the rise of in-house manufacturing, licensing models, and application-specific differentiation shows that the competitive field is still evolving.
For organizations operating in or adjacent to this market, the most valuable next step is to convert broad trends into specific decisions about product positioning, manufacturing strategy, supplier selection, and investment timing. Detailed segmentation data, regional breakdowns, and company-level assessments can make those decisions more precise and less dependent on generalization. The full research report provides that deeper view, with granular market splits, competitive profiling, and structured scenarios designed to support planning across manufacturing, investment, and procurement teams.
For detailed analysis of this topic, please visit the official page: Fuel Cell Membranes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
L-Cysteine Market 5.85% CAGR Trajectory: What Asia Pacific and Fermentation Demand Reveal
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the L-Cysteine Market: A 2032 Outlook
The global L-Cysteine market has entered a phase of steady expansion, driven by structural shifts in production methods, evolving regulatory frameworks, and sustained demand across multiple end-use sectors. Over the historical period from 2020 to 2025, the market demonstrated resilience amid supply chain volatility and cost pressures, reaching a base valuation that sets the foundation for the forecast window through 2032. With a projected compound annual growth rate of 5.85 percent, the trajectory points toward incremental but meaningful scaling, particularly as fermentation-based production gains share over traditional synthetic routes. For decision-makers operating in amino acid sourcing, formulation, or downstream applications, the market is transitioning from a commodity-adjacent space into a more differentiated, quality-sensitive arena where certification, sustainability positioning, and supply reliability increasingly influence procurement and partnership decisions.
Market Overview and Core Challenges
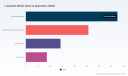
The revenue scale of the L-Cysteine market reflects consistent upward movement, with total valuation climbing from the low 135 million range in 2020 to approximately 172 million by 2025. The forecast period extends this pattern, projecting sequential gains that push the market toward the mid-250 million range by 2032. Growth is not uniform across geographies or application areas, but the aggregate trajectory underscores a market that is expanding through both volume increases and a gradual shift toward higher-value grades. The moderate level of market concentration, with the top three players accounting for roughly a quarter of share and the top five holding closer to a third, signals a fragmented but competitive landscape where scale, regional presence, and product specialization shape positioning more than outright dominance.
Key Challenges Shaping the Market
Several structural pressures are defining the near-term operating environment for L-Cysteine producers and buyers. First, production economics remain a persistent constraint. Fermentation-based processes, while increasingly preferred for their alignment with cleaner labeling and sustainability expectations, carry higher process complexity and compliance costs. These elevated production expenses continue to act as a restraint, particularly for manufacturers balancing yield optimization, quality control, and regulatory requirements across food, pharmaceutical, and feed grades. Second, regulatory differentiation across end markets creates fragmented compliance burdens. L-Cysteine benefits from recognized food additive status in major markets, including its GRAS designation and permission as an E920 additive under U.S. food regulations for dough strengthening and flavor enhancement. At the same time, pharmaceutical and cell culture applications impose stricter purity, documentation, and traceability expectations. This dual reality means that suppliers must maintain distinct quality systems and certification pathways, which can limit the ability to move inventory fluidly across segments. Third, supply chain stability is increasingly tied to facility capability and certification credibility rather than price alone. Recent investments in certified fermentation capacity signal that buyers are prioritizing auditable food safety systems and consistent quality over short-term cost advantages. This shift places pressure on smaller or less-resourced producers to either upgrade capabilities or risk erosion in procurement preference.
Key Drivers of Market Change
The market’s growth path is being shaped by a combination of technological, regulatory, demand-side, and supply-side forces that interact more strongly than in prior cycles. Rather than a single dominant catalyst, the current environment favors players who can align process innovation with specification reliability and end-market demand patterns.
Technological Innovation and Process Shifts
Fermentation continues to be the defining technical transition in L-Cysteine production. The migration toward bio-based routes is not merely a response to sustainability narratives; it is a practical means of achieving consistent purity, reducing reliance on petrochemical feedstocks, and meeting the increasingly strict documentation expectations of food and pharmaceutical customers. Suppliers investing in fermentation platforms are positioning themselves to serve multiple grades from shared infrastructure, while also differentiating through certification and traceability. Recent product catalog updates and facility expansions highlight how leading producers are embedding food safety and quality management systems directly into fermentation operations, strengthening their ability to supply bakery, food, and animal feed markets with auditable credentials. This process orientation is becoming a competitive asset, especially where buyers need assurance that ingredients meet both performance and regulatory standards.
Policy and Regulatory Environment
Regulatory clarity in key end markets provides a supportive backdrop, but it also raises the bar for compliance execution. Recognition of L-Cysteine as a permitted food additive in the United States, along with its established role as a dough strengthener and flavor enhancer, reinforces demand stability in the food and beverage segment. In parallel, pharmaceutical and healthcare applications demand tighter control over impurity profiles, documentation, and manufacturing consistency. The result is a market where regulatory acceptance is necessary but not sufficient; the practical differentiator is the ability to demonstrate repeatable quality across audits and batches. Suppliers with certified facilities and clearly defined grade portfolios are better placed to navigate this environment, while those without robust quality systems face higher barriers to entry in specification-driven segments.
Demand-Side Evolution
End-user demand is expanding across food, pharmaceutical, personal care, and animal feed applications, but with different growth drivers in each. In food and beverage, the appeal of L-Cysteine lies in functional performance and formulation stability, particularly in bakery and processed food categories where dough handling and shelf-quality considerations matter. In pharmaceutical and healthcare settings, demand is tied to applications requiring high-purity amino acid inputs and specialized derivatives, where consistency and regulatory alignment are central to procurement decisions. Personal care and animal feed applications add further volume potential, though they often emphasize cost efficiency and supply reliability. A notable trend is the increasing preference for plant-based and fermentation-derived inputs in categories where ingredient origin and labeling clarity influence customer acceptance. This demand shift is encouraging suppliers to structure product lines around vegan, natural, Kosher, and Halal attributes, broadening their addressable market while also requiring stronger documentation and certification management.
Supply Chain and Cost Structure Dynamics
Cost structures remain a defining consideration, especially as fermentation-based routes become more prominent. The process demands precise control, quality assurance, and regulatory compliance, which together contribute to elevated production costs. Rather than treating these costs as a fixed disadvantage, market participants are increasingly viewing them through the lens of value capture: higher-quality grades, certified production, and reliable supply can support pricing resilience in segments where performance and trust matter more than lowest-cost sourcing. At the same time, geographic diversification of fermentation capacity is becoming a practical hedge against localized disruption. The expansion of certified facilities in new locations reflects a broader supply chain logic that favors redundancy, audit readiness, and proximity to end-user expectations over simple volume consolidation. For buyers, this means the supply base is slowly shifting from a price-first model to a reliability-and-qualification-first model.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of established multinational producers and specialized regional manufacturers, each pursuing distinct positioning strategies. Market share remains distributed rather than concentrated, giving room for differentiation through grade portfolios, certification strength, and application-specific support. Several companies illustrate the strategic directions shaping the market.
Strategic Positioning Among Core Players
Wacker Chemie AG has emphasized a plant-based, fermentation-derived L-Cysteine offering under its FERMOPURE® brand, spanning food, pharma, and free base grades. The company’s recent catalog updates and participation in food and nutrition trade events underscore a deliberate push to communicate vegan L-Cysteine solutions for bakery and animal feed applications. The opening of a new fermentation facility in León, Spain, with FSSC 22000 and ISO 9001:2015 certifications reflects a strategy centered on certified quality infrastructure and regional supply capability.
Ajinomoto Co., Inc. continues to leverage its fermentation expertise to supply pharmaceutical- and food-grade L-Cysteine derivatives. Its positioning aligns with customers that require advanced process capability and consistent derivative production, particularly where formulation specificity and regulatory alignment are important.
Merck KGaA provides L-Cysteine and derivatives across chemical, pharmaceutical, and food applications, supporting a broad specification range. Its relevance in the market stems from the ability to connect amino acid supply with higher-specification use cases where documentation and grade control are critical.
Evonik Industries AG has focused on L-Cysteine in cell culture media and supplements, including peptide-related offerings under its cQrex® platform. This positions the company closer to life-science and bioprocessing demand, where purity, consistency, and technical support can be more valuable than volume pricing alone.
In the regional and specialized segment, Shine Star (Hubei) Biological Engineering Co., Ltd. produces L-Cysteine HCl Monohydrate across multiple pharmacopeial and food-grade standards using biological fermentation. NIPPON RIKA Co., Ltd. supplies L-Cysteine that meets international standards for amino acid and culture media applications, emphasizing specification compliance for technical and bioprocessing customers. Penta Manufacturing Company manufactures and supplies L-Cysteine HCl Anhydrous in Natural, Kosher, Halal, and FCC grades, illustrating a grade-diversification approach that addresses food, regulatory, and cultural market requirements.
How Leading Strategies Are Differencing
Across these players, several strategic threads emerge. First, certification and quality infrastructure are increasingly used as market access tools, not just compliance checkboxes. Facilities designed around recognized food safety and quality standards can enter or expand in specification-sensitive segments more readily than those relying on less documented processes. Second, portfolio breadth by grade and application is becoming a way to capture demand across food, pharma, personal care, and feed without forcing customers to accept a one-size approach. Third, the vegan and fermentation narrative is being converted into tangible product architectures, particularly where bakery, food, and feed buyers value plant-based positioning and clear documentation. Fourth, geographic expansion of fermentation capacity is being used to strengthen supply resilience and alignment with regional customer expectations.
PW Consulting
Market Structure Evolution
The market is likely to continue evolving along two parallel paths. On one side, consolidation pressure may build among smaller producers who struggle to fund certified fermentation capacity, multi-grade portfolios, and audit-ready quality systems. On the other, specialization will remain attractive, especially where companies can serve pharma, cell culture, or culturally specific food requirements with differentiated grades and documentation. New entrants will face a higher threshold than in the past, because credibility in food safety, specification consistency, and certification is now part of the commercial equation. The net effect is a landscape that is neither fully consolidated nor purely commoditized, but increasingly shaped by capability, compliance, and application alignment.
Future Trends and Commercial Implications
Looking toward the 2026 to 2032 window, several trends are likely to influence how value is created and captured in the L-Cysteine market. These trends do not guarantee uniform growth, but they point to where commercial opportunities are most likely to materialize.
Lysine Market
Fermentation-Based Supply Will Continue Gaining Relevance
Fermentation is expected to maintain its upward trajectory as the preferred production route for a growing share of demand. The combination of cleaner ingredient positioning, stronger alignment with food safety expectations, and the ability to support multiple grades from a single platform makes fermentation a strategic foundation rather than a niche alternative. Commercially, this favors suppliers that can demonstrate certified processes, stable batch quality, and clear grade segmentation. For buyers, it means sourcing strategies will increasingly weigh fermentation capability and certification as core criteria, especially when ingredient origin and quality assurance affect downstream customer acceptance.
Demand Growth Will Remain Broad but Uneven
The overall market expansion is supported by demand across food, pharmaceutical, personal care, and animal feed applications, but growth rates and value capture will differ by segment. Food and beverage applications benefit from functional use cases and regulatory acceptance, while pharmaceutical and healthcare applications prioritize purity and documentation. Personal care and animal feed add volume potential, often with a stronger emphasis on cost and reliability. The commercial implication is that portfolio strategy matters: companies able to serve multiple demand profiles with appropriate grades and certifications are better positioned to capture growth without overrelying on any single end market.
Certification and Supply Reliability Will Become More Valuable Than Price Alone
As certified fermentation capacity expands and buyers become more accustomed to auditable quality systems, the relative importance of price-only competition is likely to diminish in specification-sensitive segments. This does not mean price becomes irrelevant, but it does suggest that reliability, traceability, and certification readiness will increasingly support premium positioning or at least protect share against lower-cost but less-qualified alternatives. The risk side of this trend is that any lapse in quality documentation or facility certification can quickly erode buyer confidence, particularly in food and pharma channels. Companies that treat compliance and quality systems as strategic assets rather than overhead will be better placed to sustain relationships through demand fluctuations.
Potential Risks and Uncertainties
Despite the constructive outlook, several uncertainties deserve attention. Production cost pressure from fermentation complexity and regulatory compliance can cap margin expansion if not offset by grade differentiation or efficient scale. Regulatory divergence across regions and applications may increase operational complexity, especially for suppliers serving both food and pharmaceutical customers from shared infrastructure. Demand growth may also vary more than expected if economic conditions affect discretionary food and personal care spending or if feed demand responds to broader agricultural and livestock cycles. Finally, the expanding importance of certified capacity could intensify competition for audit-ready facilities and skilled process talent, creating bottlenecks for companies trying to scale quickly without compromising quality standards.
Actionable Guidance for Decision-Makers
The L-Cysteine market is moving toward a structure where capability, certification, and application alignment matter as much as volume and cost. The following considerations can help different stakeholder groups translate the market direction into practical decisions.
For Manufacturers and Producers
Evaluate whether production strategy is aligned with the shift toward fermentation-based, certification-ready supply. Where feasible, invest in auditable quality systems and grade segmentation that allows the same core capability to serve food, pharma, and feed requirements without compromising documentation standards. Differentiation through vegan, natural, Kosher, and Halal attributes can widen addressable demand, but only if supported by verifiable processes and clear grade definitions. Avoid overexposure to price-only competition in segments where buyers increasingly value reliability and compliance.
NAC (Acetylcisteine) Market
For Investors and Strategic Partners
Focus on companies that demonstrate a credible link between fermentation capability, certified facilities, and application-specific grade portfolios. The most resilient positioning is likely to come from producers that can expand across multiple end-use sectors while maintaining specification integrity. Geographic diversification of production capacity and a clear plan for food safety and quality certification are indicators of supply resilience that can matter during disruption. In addition, pay attention to the balance between scale and specialization, since both models can succeed if matched to the right end markets and grade requirements.
For Procurement and Supply Chain Leaders
Treat certification, traceability, and production method as core sourcing criteria alongside price. Where downstream customers care about ingredient origin, labeling clarity, or application-specific performance, supplier qualification should include facility certifications, grade documentation, and consistency evidence rather than relying on spot-market pricing alone. Diversifying the supplier base across regions and fermentation capabilities can reduce exposure to localized disruption while preserving access to the grade profiles needed for food, pharma, personal care, or feed use cases.
The strategic picture for the L-Cysteine market is one of steady expansion shaped by process transition, regulatory acceptance, and demand diversification. The companies and buyers that benefit most will be those who treat quality systems, certification, and application alignment as central to commercial strategy rather than secondary to volume. For decision-makers seeking deeper segmentation data, regional granularity, and customized assessments of supply, pricing, and competitive positioning, the full research report provides more detailed coverage to support planning and benchmarking across the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: L-Cysteine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sports Turf Market 2026: What a 7.45% CAGR Said About Polyethylene's 182.8M Dominance
By pmarketresearch, 2026-09-21
Sports Turf Market: Strategic Shifts and Commercial Opportunities in a Rapidly Evolving Landscape
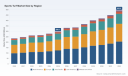
The global sports turf market has entered a phase of measurable expansion, driven by sustained investment in athletic infrastructure, advances in turf maintenance technology, and shifting demands from end users. From 2020 through 2025, the market grew from approximately 235.5 million to 299.1 million in annual revenue. Forward projections indicate continued traction, with revenue expected to climb toward 332.3 million by 2026 and continue expanding through 2032. The implied compound annual growth rate across the forecast window sits at roughly 7.45 percent, signaling a market that is moving beyond cyclical recovery into a structurally healthier trajectory. This expansion is not uniform across categories or geographies, and the companies that will capture disproportionate value are those that align product development, service models, and go-to-market strategies with where capital and operational priorities are actually shifting.
Artificial Grass Turf Market
For executives evaluating exposure to this space, the central question is less about whether the market is growing and more about which segments will compound faster, which cost pressures will reshape margins, and where competitive moats are being built or eroded. The following sections outline the current market context, the forces reshaping demand and supply, the competitive posture of leading players, and the strategic implications for manufacturers, investors, and procurement teams.
Market Context and Core Challenges
Revenue growth in the sports turf market reflects a combination of new field installations, replacement cycles, and higher spending on maintenance equipment that improves consistency and reduces downtime. Demand is anchored in football, baseball, hockey, golf, tennis, and rugby facilities, with broader discretionary sports and recreational applications contributing additional volume. The mix of product types continues to lean heavily toward polyethylene-based solutions, while polypropylene, nylon, hybrid constructions, and other materials serve more specialized performance or durability requirements. Regionally, North America and Europe account for the largest shares of activity, followed by the Asia Pacific region, with Latin America and the Middle East and Africa representing smaller but growing bases.
Despite the positive trajectory, the market faces a handful of structural challenges that will determine which operators thrive over the next several years.
Cost Pressures on Key Inputs
Steel and lithium-ion battery cells are among the components experiencing near-term inflationary pressure in sports turf equipment. For manufacturers, this translates into tighter margin management, more deliberate bill-of-materials engineering, and potentially longer development cycles as teams balance performance targets against total cost of ownership. For buyers, the same dynamics raise questions about whether newer electric or robotic platforms will deliver net savings over the full lifecycle, especially when factoring in charging infrastructure, servicing, and replacement part pricing. The implication is that equipment roadmaps will need to be evaluated not only by feature sets but by sensitivity to input cost volatility and the ability to pass through or absorb those costs across regions.
Labor Economics and Automation Adoption
Ride-on robotic mowers and related autonomous platforms are compressing labor costs for stadium operators and golf course superintendents managing sports turf. This is a meaningful shift because labor availability, wage inflation, and skill scarcity have become persistent constraints in field maintenance. Automation is no longer a niche experiment; it is increasingly positioned as a solution to scheduling reliability, consistency of cut, and reduced reliance on specialized crews. The challenge for adoption is not only capital expenditure but also integration with existing workflows, training requirements, and the need to validate performance under varying field conditions, weather exposure, and usage intensity.
Standards, Certification, and Operational Expectations
The regulatory and standards environment is becoming more consequential as facility owners, municipalities, and sports organizations seek to formalize best practices. ISO/TC 83 develops standards for sports and recreational facilities and equipment, including operational, maintenance, and safety requirements. In parallel, the Sports Turf Managers Association publishes Best Management Practices covering environmental facility certification and maintenance for sports turf. These frameworks do not simply impose compliance costs; they reshape procurement criteria, influence specifications, and create a reference point for product validation. Manufacturers and service providers that align early with recognized standards and provide documentation or performance evidence can reduce friction at the point of sale, while slower followers may face longer evaluation cycles and more demanding proof points.
Key Drivers Reshaping the Market
Technology Innovation and Performance Differentiation
The most visible driver is the pace of innovation in turf care equipment, particularly around electrification, autonomy, and precision maintenance. Recent product introductions illustrate how vendors are moving from incremental improvements to differentiated offerings with clear operational benefits. For example, in early 2026 Toro introduced the GreensPro e1700 all-electric greens roller designed for smooth, consistent golf greens and sports turf while boosting operator efficiency. This type of launch signals a broader direction: equipment is increasingly being designed for repeatability, reduced operator fatigue, and tighter control over surface conditions.
For the market, this matters because performance thresholds are rising. Field managers are not only looking for machines that can cut or roll; they are looking for tools that support consistent play quality, predictable maintenance windows, and lower operating disruption. As electric and robotic platforms mature, the competitive conversation is shifting from raw power to system-level value, including battery management, navigation reliability, service access, and integration with turf monitoring workflows. Companies that can package these capabilities into dependable, easy-to-deploy solutions are likely to see stronger pull from professional facilities and higher-tier recreational markets.
Policy and Standards as a Procurement Filter
Regulatory and standards activity is influencing market behavior by changing how facilities justify purchases and how vendors substantiate claims. ISO/TC 83's work on operational, maintenance, and safety requirements for sports and recreational facilities provides a reference structure that procurement teams can use to evaluate equipment and practices. At the same time, the Sports Turf Managers Association's Best Management Practices create an ongoing benchmark for environmental and maintenance standards. Together, these frameworks encourage a more disciplined purchasing environment where consistency, documentation, and adherence to recognized practices carry additional weight.
This does not mean regulation is a constraint in the traditional sense; it also creates a pathway for differentiation. Vendors that provide evidence of alignment with maintenance standards, that design for easier compliance, or that partner with facility managers on certification pathways can reduce uncertainty for buyers. In practice, this can shorten evaluation timelines and increase the likelihood that equipment is specified in tenders where standards are part of the scoring criteria.
Demand-Side Shifts in Facility Operations
On the demand side, facility operators are facing pressure to do more with constrained labor and tighter operating budgets. Stadiums, college campuses, high school programs, and golf operations are all managing higher expectations for surface quality while contending with scheduling intensity and maintenance cost control. This environment favors equipment and service models that improve throughput, reduce variability, and enable fewer skilled hours to cover more area without sacrificing quality.
The result is an incremental but durable shift toward solutions that address total cost of ownership rather than purchase price alone. Buyers are increasingly interested in whether a mower, roller, sprayer, or sweeper can reduce passes, improve consistency, lower fuel or charging overhead, and simplify maintenance. This dynamic also supports growth in replacement and refresh activity: as existing fleets age or fail to meet evolving performance expectations, operators reassess whether to continue with legacy equipment or transition to more automated or electrified alternatives.
Supply Chain and Cost Structure Realignment
Supply chain realities are influencing both product design and commercial strategy. Input cost volatility, particularly around steel and battery cells, is forcing more deliberate sourcing decisions and encouraging manufacturers to evaluate regional supply options, component standardization, and serviceability. At the same time, the growing interest in electric and robotic equipment introduces new dependencies on battery supply, power electronics, and software-enabled subsystems, which can change the shape of lead times and after-sales support requirements.
For the broader market, this realignment creates a split incentive. One path is toward more consolidated, engineered platforms with predictable support networks and stronger lifecycle value propositions. Another is toward specialized, application-focused tools that address discrete maintenance tasks where performance and reliability matter most. How companies navigate these two directions, and how they manage cost exposure while preserving differentiation, will be a defining factor in margin outcomes over the forecast period.
Competitive Landscape and Leading Strategies
The market features a mix of established equipment manufacturers, focused turf specialists, and distribution-oriented players. The competitive field is not defined solely by scale; it is increasingly shaped by how well companies tailor their offerings to professional sports turf use cases, from maintenance machinery to specialized construction and field-support equipment. A review of recent activity and company positioning shows several distinct strategic stances.
Strategic Postures Among Leading Players
The Toro Company, headquartered in Bloomington, Minnesota, focuses on sports turf maintenance through mowers, greens rollers, utility vehicles, and autonomous solutions tailored for athletic fields and sports turf. Its recent introduction of the GreensPro e1700 all-electric greens roller highlights a push into electrification and operator efficiency for precision surfaces. Deere & Company, based in Moline, Illinois, maintains a presence in golf and sports turf equipment, including mowers, sprayers, and maintenance machinery for athletic fields, with an emphasis on breadth across turf care and application equipment.
Playground Artificial Grass Turf Market
Husqvarna Group, headquartered in Stockholm, Sweden, offers commercial turf care equipment, CEORA robotic platforms, and ride-on mowers for professional sports field operations, placing it in a strong position around automation and robotic maintenance. STIHL, based in Waiblingen, Germany, contributes backpack and handheld equipment for turf and sports field maintenance, serving more targeted operator needs where maneuverability and access matter. Smithco, in Wayne, Pennsylvania, provides rollers, sweepers, sprayers, and GPS-enabled turf management machinery for athletic fields, reinforcing the trend toward data-enabled maintenance and more precise field conditioning.
Smaller but strategically relevant specialists round out the landscape. Progressive Turf Equipment offers rotary finishing mowers and autonomous mowing systems for natural grass and sports turf maintenance. Sportsfield Specialties focuses on sports construction and maintenance equipment for high school, college, and professional fields. MTD Products supplies lawn and garden equipment, including mowers and sprayers used in sports turf applications. Kubota Corporation, based in Osaka, Japan, provides compact tractors and turf care machinery for sports field management. Turf Equipment and Supply Company operates as a distributor and seller of Toro consumer and landscape contractor equipment for sports and turf maintenance, illustrating how distribution partnerships can extend reach and service coverage.
Differentiation and Emerging Trends in Competitive Positioning
Several patterns are visible across this group. First, differentiation is moving toward application-specific performance and operational efficiency rather than generic equipment capabilities. Companies are increasingly expected to demonstrate that their products handle the demands of repeated use on football pitches, baseball fields, hockey surfaces, golf areas, tennis courts, and rugby pitches, each with different wear patterns and maintenance priorities.
Second, autonomy and electrification are becoming strategic wedges. Robotic platforms and electric rollers or mowers are not just product categories; they are signals that a company is addressing labor constraints, consistency goals, and operating cost sensitivity. This creates a competitive dynamic in which vendors that can deliver dependable automation, strong service support, and a credible total-cost narrative may gain preference over those offering lower upfront price but weaker lifecycle economics.
Third, distribution and service reach remain critical. Equipment in this market is only as valuable as its availability, maintenance pathway, and local expertise. This gives distributors and service-oriented partners a meaningful role in shaping customer experience, especially in regions where facility managers depend on responsive support and parts access. The presence of dedicated distributors and regional specialists suggests that competitive advantage will continue to depend heavily on execution at the local level, not just product engineering at the corporate level.
The overall market concentration underscores the importance of both scale and specialization. With a moderately concentrated structure at the top, larger players have room to leverage breadth, brand recognition, and installed-base relationships, while focused specialists can compete by addressing niche performance requirements, specific sports, or particular maintenance workflows. Over time, this may lead to selective consolidation among companies seeking broader portfolios or regional coverage, alongside continued entry of specialized solutions in automation, precision maintenance, and field construction support.
Forward-Looking Trends and Commercial Implications
Accelerated Adoption of Electrified and Autonomous Maintenance Tools
Over the next three to five years, electrified rollers, mowers, and robotic platforms are likely to move from differentiated offerings to more mainstream considerations for a broader set of facilities. The driver is not only sustainability positioning; it is the operational case around labor savings, consistency, and reduced exposure to fuel management and engine maintenance. As these systems become more common, the market will likely see increased demand for charging infrastructure, service training, parts availability, and lifecycle support. Commercial opportunities will emerge for companies that can bundle equipment with deployment assistance, monitoring capabilities, or service agreements that reduce adoption risk.
Standards-Aligned Procurement as a Competitive Filter
As standards and best-practice frameworks become more embedded in facility decision-making, procurement processes are likely to place greater weight on documented compliance, maintainability, and safety performance. This trend favors vendors that can provide clear evidence of alignment and that design equipment to make compliance and maintenance more straightforward. It also creates a risk for companies that rely on less formal purchasing environments and are unprepared for increasing documentation and specification requirements. The opportunity lies in turning standards alignment into a sales enabler rather than treating it as a back-office requirement.
Regional Divergence in Investment Priorities
While North America and Europe remain pivotal, regional growth patterns will likely diverge based on sport development, public investment, and the pace of facility modernization. Areas with expanding sports infrastructure and growing interest in field quality may see faster uptake of newer equipment categories, while more mature markets may focus on replacement cycles, automation retrofits, and efficiency improvements. This divergence means that product portfolios, pricing strategies, and service models may need to be tuned to regional operating realities rather than delivered as one-size-fits-all solutions. Companies that understand local procurement behavior, service expectations, and field-use intensity will be better positioned to convert interest into installed equipment.
Risks and Uncertainties to Watch
Input cost volatility remains a key uncertainty, particularly for equipment dependent on steel and battery cells. If cost pressures persist or spike, pricing dynamics and margin expectations could shift quickly, affecting both manufacturers and buyers. Adoption of autonomous and electric systems may also face practical friction if field conditions, maintenance requirements, or support networks do not meet expectations in real-world use. In addition, standards-driven procurement can create short-term complexity if specifications evolve faster than product documentation or certification processes. Companies should monitor these variables as leading indicators of where demand may accelerate, slow, or redirect.
PW Consulting
Strategic Actions for Decision Makers
For manufacturers, the priority is to align product roadmaps with where operational value is being created. That means evaluating not just feature additions but the full lifecycle economics of electrification, autonomy, and precision maintenance. Designing for serviceability, predictable parts availability, and clear documentation of standards alignment can strengthen commercial positioning as procurement becomes more structured. It also pays to assess exposure to input cost volatility and to model how cost changes affect both pricing strategy and margin resilience across the forecast period.
For investors, the market suggests value in companies that have credible answers to labor constraints and operational consistency. Interest is likely to persist for platforms that combine dependable performance with serviceability and a believable total-cost proposition, especially where automation or electrification is central to the offering. Equally important is the quality of distribution and service reach, since equipment adoption in sports turf depends heavily on local support and repeat purchasing behavior. Monitoring regulatory and standards activity, as well as input cost trends, can provide early signals about which business models are more durable.
For procurement teams and facility operators, the practical task is to evaluate equipment against real operating conditions rather than headline specifications. Total cost of ownership, integration with existing workflows, service responsiveness, and alignment with recognized maintenance practices should carry significant weight. Piloting or phased adoption of robotic and electric solutions can help validate performance and labor savings before broader rollout. In addition, engaging early with vendors that can support documentation and standards-related requirements may reduce friction in future procurement cycles.
As the sports turf market continues to expand and its competitive dynamics become more performance- and operations-driven, the organizations that act early on these shifts will have a clearer path to capturing durable value. For readers seeking a more granular view of segment dynamics, regional patterns, and customized strategic options, the full PW Consulting market analysis provides deeper segmentation detail, updated company benchmarking, and scenario-based guidance tailored to specific business objectives.
For detailed analysis of this topic, please visit the official page: Sports Turf Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Triazine Market CAGR of 6.46%: Real Drivers Behind the $995 Million Growth by 2032
By pmarketresearch, 2026-09-21
Navigating the Triazine Market: Strategic Trends and Commercial Opportunities Through 2032
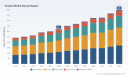
The triazine market has entered a phase of steady, structurally supported expansion. Valued at approximately 641.0 million USD in 2025, the sector is projected to reach 995.0 million USD by 2032, reflecting a compound annual growth rate of 6.46 percent across the 2026–2032 forecast window. This trajectory is anchored in consistent historical momentum, with revenues climbing from 484.2 million USD in 2020 through incremental annual gains that accelerated noticeably after 2022. The growth profile is not merely a function of volume expansion; it signals a market undergoing structural recalibration, where application diversification, regulatory navigation, and supply chain discipline are reshaping competitive advantage.
For executives and capital allocators, the central question is no longer whether triazine-derived products will continue to grow, but how value will be captured amid tightening environmental scrutiny, feedstock volatility, and shifting end-user expectations. The market’s evolution demands a clear view of the forces currently dictating margin profiles, capacity allocation, and strategic positioning.
Market Snapshot and Structural Headwinds
The triazine landscape in 2025 is defined by a mature yet still expanding revenue base, with growth increasingly concentrated in high-value applications and regions demonstrating strong agricultural productivity or industrial demand. The compound annual growth rate of 6.46 percent underscores a market that is outpacing broader chemical sector averages, yet this expansion is not uniformly distributed across all segments. Pricing dynamics, regulatory compliance costs, and regional feedstock availability are creating a bifurcated environment where well-positioned players capture disproportionate value while others face margin compression.
A first critical challenge lies in regulatory persistence and environmental scrutiny. Triazine-class herbicides have long operated under strict monitoring frameworks, and the continued enforcement of legacy agreements means that compliance is not a periodic hurdle but a permanent operational overhead. Companies that treat regulatory engagement as a reactive exercise increasingly find themselves constrained in formulation flexibility, geographic expansion, and product lifecycle management. The second challenge is supply chain fragility tied to feedstock and intermediate pricing. Fluctuations in melamine, cyanuric acid, and cyanuric chloride markets directly compress or expand manufacturing margins, and recent price behavior in these inputs has introduced greater unpredictability into cost planning. The third challenge is the tension between volume growth and formulation sustainability. End-users in agriculture are demanding higher efficacy with lower environmental residue, while industrial buyers seek reliable performance in gas treatment and water management applications. Balancing these expectations without compromising cost structure requires capabilities that many mid-tier producers have not yet fully developed.
These headwinds are not insurmountable barriers; rather, they function as filters that reward operational discipline, regulatory fluency, and application-specific innovation. The market is gradually rewarding players who can integrate compliance, cost control, and differentiated performance into a single strategic narrative.
Core Drivers Shaping Market Trajectory
Technological Innovation and Formulation Precision
Innovation in triazine chemistry is increasingly oriented toward precision, selectivity, and application efficiency rather than broad commodity volume. Recent developments illustrate this shift clearly. In late 2025, a major industry participant launched a new line of triazine-based herbicides explicitly engineered for precision agriculture, reflecting a broader move toward formulations that align with variable-rate application, crop-specific tolerance profiles, and reduced off-target exposure. Simultaneously, research expansions in Brazil have focused on tailoring triazine herbicides to local crop varieties, highlighting how regional agronomic conditions are driving customized product development rather than one-size-fits-all offerings.
Beyond agriculture, technological progress in triazine-based H2S scavenging and desulfurization is expanding the industrial application envelope. Capacity expansions for triazine-based scavengers in 2025 demonstrate how oil and gas operators are increasingly relying on tailored chemistries to manage sulfur challenges in production streams. The release of updated product catalogs offering MEA triazine grades in concentrated ranges further indicates that suppliers are refining performance consistency and handling characteristics to meet demanding industrial specifications. For manufacturers, the strategic implication is clear: incremental formulation improvements, application-specific packaging, and performance reliability are becoming more valuable than pure volume scaling.
Policy and Regulatory Environment as a Strategic Variable
Regulatory frameworks continue to shape market behavior more than any single pricing or demand variable. Ongoing monitoring programs for triazine herbicides remain in force under longstanding reregistration eligibility decisions and associated memoranda of agreement, meaning compliance documentation, environmental monitoring, and residue management are integral to market access rather than optional enhancements. This regulatory continuity creates a high barrier for informal or under-resourced market entry, consolidating advantage for companies with established compliance infrastructure and transparent reporting practices.
Mma Triazine H2S Scavengers Market
At the same time, broader trade and export dynamics are influencing input availability and cost structures. Export controls on certain medium and heavy rare earth items introduced in 2025 illustrate how regulatory actions in adjacent material categories can cascade into chemical supply planning, particularly for producers dependent on complex intermediate streams or specialized processing routes. While triazine manufacturing does not directly rely on rare earths, the broader message is that policy volatility is becoming a structural feature of chemical markets. Firms that proactively map regulatory exposure across jurisdictions, maintain flexibility in sourcing, and invest in compliance-ahead product design are better positioned to avoid disruption and protect margin integrity.
Demand-Side Shifts in Agriculture and Industrial Use
Demand patterns are shifting on both the agricultural and industrial fronts, though for different reasons. In agriculture, the continued emphasis on corn and sugarcane cultivation sustains core demand for triazine herbicides, but the nature of that demand is becoming more performance-driven. Growers and agronomic advisors are prioritizing weed control solutions that integrate with precision application technologies, offer consistent efficacy under variable field conditions, and align with resistance management strategies. This shift is encouraging suppliers to emphasize formulation reliability, crop-specific compatibility, and supportive technical service rather than competing solely on price.
On the industrial side, demand for triazine-based solutions in gas treatment, desulfurization, and water management is gaining traction as operational environments become more complex. Production chemicals portfolios are increasingly integrating triazine H2S scavengers as operators seek reliable methods to manage sulfur-related challenges in extraction and processing. This diversification of end-use is important because it reduces overreliance on a single agricultural cycle and creates demand streams that are less seasonal and more tied to ongoing industrial operational requirements. For commercial strategists, the opportunity lies in recognizing that triazine demand is expanding beyond traditional herbicide channels into specialized industrial applications where performance consistency and technical support command premium positioning.
PW Consulting
Supply Chain and Cost Structure Realignment
Cost dynamics are being reshaped by feedstock behavior and production geography. Melamine pricing in Asia weakened in 2025 amid resumed production capacity, creating a narrow price range that alters input cost expectations for downstream triazine producers. In parallel, cyanuric acid prices rose during the third quarter of 2025 as higher urea feedstock costs and elevated energy expenses flowed through the value chain. Cyanuric chloride prices, by contrast, held relatively stable in late 2024 on balanced supply and steady chlorine costs. This mixed input environment means that cost leadership is no longer solely about scale; it is increasingly about feedstock agility, regional sourcing optimization, and the ability to pass through or absorb cost variation without sacrificing customer relationships.
Producers that maintain diversified input channels, invest in process efficiency, and align capacity with demand hotspots are better equipped to navigate these fluctuations. The market is also seeing renewed attention to regional production footprints, as exemplified by research and capacity investments in key agricultural markets. This suggests that supply chain resilience and local relevance are becoming competitive differentiators alongside traditional cost metrics.
Competitive Landscape and Strategic Positioning
The triazine market features a concentrated group of leading participants alongside a broader base of registered producers and specialty suppliers. Concentration metrics indicate that a relatively small number of firms command a substantial share of revenue, while the remainder compete through regional focus, formulation specialization, or application-specific niches. This structure creates a market where scale, brand trust, regulatory compliance, and technical service all contribute to durable positioning.
Large multinational players maintain advantage through integrated portfolios, global distribution networks, and the ability to invest in formulation research across multiple crop systems and industrial uses. Their strategic positioning typically centers on offering triazine-class herbicides and derivatives with consistent quality, broad geographic reach, and application support that spans agricultural and industrial channels. In the agricultural segment, some of these participants are particularly strong in corn and sorghum weed control, while others emphasize triazine-tolerant formulations and mixed-herbicide approaches that address resistance management and broader crop compatibility.
Triacetin Market
Specialized and regional players are carving out distinct roles by focusing on local crop varieties, precision agriculture alignment, and industrial application expertise. Capacity investments in triazine-based H2S scavengers, updated product grade offerings, and region-specific research expansions all point to a landscape where differentiation is increasingly tied to application performance rather than commodity availability. For industrial applications, suppliers that can deliver reliable scavenging performance, handle concentrated grades consistently, and integrate with production chemicals portfolios are gaining relevance as operators look for dependable chemical solutions in demanding environments.
Market evolution is shaped by both consolidation and fragmentation tendencies. On one side, larger players continue to strengthen their positions through portfolio breadth, global reach, and selective investments in research and capacity. On the other side, new and mid-tier entrants are finding opportunities in specialized formulations, regional crop customization, and industrial niche applications where agility and technical service can offset scale disadvantages. Acquisition activity in adjacent production chemicals and digital technology segments further signals that companies are seeking to broaden their capabilities beyond single-product offerings, integrating chemistry, application know-how, and service delivery into more comprehensive value propositions.
The competitive implication for decision-makers is that market share alone does not guarantee resilience. Firms that can combine regulatory readiness, feedstock cost discipline, application-specific innovation, and strong technical support are better positioned to defend margins and expand into higher-value channels. The landscape is gradually shifting from pure product availability toward solution-oriented positioning, where performance consistency and channel expertise matter as much as volume.
Forward View: Trends and Commercial Implications for 2026–2032
Precision-Oriented Formulation and Application Integration
Over the next three to five years, one of the most consequential trends will be the continued move toward precision-oriented triazine formulations and their integration with application technologies. As precision agriculture expands and growers demand more targeted weed control with reduced environmental exposure, suppliers that can deliver crop-specific, site-adaptive, and performance-consistent products will capture disproportionate demand. This trend creates commercial opportunities for manufacturers to strengthen technical service, develop regional formulation variants, and align product portfolios with variable-rate and data-driven application practices. It also introduces the risk that companies unable to support precision application requirements may face gradual erosion in relevance, particularly in higher-value crop systems.
Industrial Demand Diversification as a Stabilization Channel
A second trend is the gradual diversification of triazine demand beyond traditional herbicide channels into industrial applications such as gas treatment, desulfurization, and water management. This shift is likely to provide a stabilizing effect on demand profiles by reducing sensitivity to any single agricultural cycle or regional crop outcome. Commercial opportunities here include expanding production chemicals portfolios, improving grade consistency for scavenger applications, and building application support capabilities that address operational reliability in oil, gas, and industrial water contexts. The associated risk is that industrial demand can be cyclical and closely tied to capital expenditure patterns in energy and processing sectors, meaning suppliers must manage capacity and inventory with a clear view of end-user investment cycles.
Regulatory Continuity and Input Cost Volatility as Persistent Variables
The third trend is the likelihood that regulatory oversight and input cost variability will remain central strategic variables rather than transient disruptions. Continued monitoring requirements for triazine herbicides and broader policy actions affecting chemical trade and material availability will require ongoing compliance investment and supply chain flexibility. At the same time, feedstock and energy cost fluctuations will continue to influence margin outcomes. The commercial opportunity lies in building operational models that treat compliance and cost agility as core capabilities, enabling faster response to regulatory updates and input price shifts. The risk is that firms with rigid sourcing, limited compliance infrastructure, or weak regional adaptability may experience recurring margin pressure and market access constraints.
Strategic Actions for Decision-Makers
For manufacturers and product leaders, the priority is to align formulation development and capacity planning with the market’s precision and application-diversification trajectory. This means investing in crop-specific and region-specific formulations, strengthening technical service around precision application and resistance management, and ensuring that industrial-grade triazine products meet the consistency and handling expectations of gas and water treatment operators. It also means building feedstock flexibility and process efficiency to absorb input cost variability without eroding competitive positioning. Companies that can demonstrate reliable performance, regulatory readiness, and application support will be better placed to defend share and expand into higher-margin channels.
For investors and capital allocators, the market’s growth profile offers attractive exposure, but returns will increasingly depend on which participants can convert scale into differentiated value. Due diligence should focus on regulatory compliance infrastructure, feedstock cost management, regional demand alignment, and the ability to serve both agricultural and industrial applications with credible technical support. Attention to recent capacity expansions, research investments, and portfolio integration moves can provide early signals about which companies are building durable advantages versus competing primarily on price. In a market where concentration is meaningful but specialization is gaining value, identifying firms with both scale and application-relevant capabilities is a prudent approach.
For procurement and supply chain leaders, the immediate imperative is to manage input volatility and compliance risk through diversified sourcing and clear performance specifications. Engaging suppliers with transparent monitoring practices, consistent grade quality, and the ability to support regional application requirements can reduce disruption risk and improve operational reliability. In industrial procurement, prioritizing suppliers with proven scavenger performance, reliable delivery, and supportive technical service will help maintain process stability in demanding operating environments. In agricultural procurement, aligning product selection with precision application capabilities and crop-specific needs can improve efficacy outcomes while supporting compliance objectives.
The triazine market is moving from a volume-centric phase into a value-centric phase where precision, compliance, and application diversification define competitive advantage. For organizations seeking deeper segmentation data, regional demand breakdowns, and customized strategic recommendations, a comprehensive research report provides the detailed frameworks needed to translate these trends into actionable planning. Accessing that level of detail enables decision-makers to calibrate capacity, portfolio, and sourcing strategies with greater confidence as the market advances toward 2032.
For detailed analysis of this topic, please visit the official page: Triazine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Scrubber-Dryers Market 2026: Why the 4.8% CAGR Trajectory Signals a Regional Power Shift
By pmarketresearch, 2026-09-21
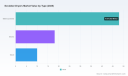
Strategic Trends and Commercial Opportunities in the Scrubber-Dryers Market
The floor cleaning equipment landscape is undergoing a structural transformation, and scrubber-dryers sit at the center of that shift. Once viewed as purely utilitarian assets, these machines are becoming platforms for resource optimization, data-driven operations, and sustainability compliance. The market already demonstrates steady expansion, and the trajectory through the next decade suggests that capital allocation, product design, and procurement strategies will need to adapt to a more performance-oriented competitive environment.
The broader market size has evolved from a modest base in 2020 to a substantially larger revenue pool by 2025, and the forward outlook continues to reflect measured but resilient growth. The forecast period through 2032 points to a market that is not simply expanding in absolute terms but also maturing in its value drivers. Growth is increasingly tied to efficiency gains, regulatory alignment, and the replacement of labor-intensive cleaning processes with mechanized and, in some cases, autonomous solutions. In practical terms, the market is moving from a volume-driven equipment category toward a performance-driven solution category.
That shift is not without friction. The industry is navigating several intersecting challenges that will shape competitive outcomes over the next few years. First, sustainability expectations are no longer peripheral. Cleaning operations face growing pressure to reduce water usage, limit detergent discharge, and adopt equipment construction practices that lower embodied material impact. This is changing purchasing criteria, because procurement teams increasingly evaluate total operating cost and environmental footprint rather than upfront price alone.
Second, labor economics are reshaping adoption patterns. Elevated facility management wages and persistent workforce constraints are making productivity-per-operator a critical decision variable. In many commercial and industrial settings, the case for ride-on or larger walk-behind units becomes stronger when manual scrubbing time and repeat passes can be reduced. The result is a market where equipment selection is increasingly justified by operational uptime and labor reallocation rather than cleaning performance alone.
Third, the competitive environment is tightening around differentiation that goes beyond basic mechanical function. Concentration among leading players indicates that scale, brand credibility, and channel reach still matter, but they are no longer sufficient by themselves. Buyers are looking for smarter dosing, easier maintenance, longer battery performance, and better integration with facility workflows. Companies that treat scrubber-dryers as static tools risk losing share to those that frame them as part of a broader cleaning and compliance system.
Key Drivers Reshaping the Market
Several forces are converging to alter demand, product design, and competitive positioning. These drivers are interconnected, and their combined effect is what gives the market its current strategic momentum.
Technology Innovation and Operational Efficiency
Product development is increasingly focused on doing more with less. Smart dosing, optimized water delivery, and improved brush mechanics are reducing consumable use while maintaining or improving cleaning outcomes. In parallel, lighter construction formats and ergonomic designs are expanding the usable range of compact units, making machine-assisted cleaning viable in smaller or more constrained spaces that were historically dependent on manual methods.
One of the clearest signals of this shift is the recent emphasis on onboard guidance, adjustable controls, and preset cleaning modes. These features reduce training friction and help standardize performance across operators, which matters in multi-site facilities where consistency is difficult to maintain. Energy efficiency improvements also carry strategic weight. When a unit can deliver cleaning coverage with lower power draw, fewer refill interruptions, and reduced chemical consumption, the value proposition extends well beyond the purchase price. Over a multi-year operating cycle, such gains influence total cost of ownership in ways that procurement teams can quantify and compare.
The broader implication is that innovation is no longer defined solely by speed or coverage area. It is increasingly defined by control, repeatability, and input efficiency. That reframing changes where manufacturers should invest and where buyers should look for differentiation.
Policy, Compliance, and Sustainability Standards
Regulatory and standards-driven expectations are becoming a meaningful influence on equipment choice. Environmental policy momentum, particularly around eco-friendly cleaning practices and water efficiency, is reinforcing demand for machines that can demonstrate measurable sustainability performance. In some contexts, mandatory sustainability metrics in cleaning equipment procurement are pushing organizations to document resource use and emissions-related performance more rigorously.
At the same time, workplace safety and environmental compliance requirements are contributing to the case for battery-powered platforms. Clean, dry floors are central to housekeeping standards, and zero-emission operation supports indoor-use constraints in sensitive environments. This is especially relevant where ventilation limitations, occupant health considerations, or operational hours make emissions and exhaust management a practical concern. Compliance is therefore not just a legal backdrop; it is becoming part of the selection logic for facility teams evaluating equipment across healthcare, hospitality, and commercial environments.
For manufacturers, this means sustainability attributes must be designed into the product rather than communicated as an afterthought. Recycled materials, reduced water and detergent consumption, and lower energy demands are moving from optional features to competitive requirements.
Demand-Side Behavior and Facility Management Priorities
End-user behavior is changing in response to both cost pressures and quality expectations. Facility managers are looking for equipment that can help stabilize cleaning outcomes while reducing variability across shifts and locations. In sectors such as healthcare and hospitality, cleanliness is directly tied to reputation, safety, and user experience, which raises the stakes for consistency and reduction in re-cleaning.
Floor Scrubbers Market
Another important demand-side shift is the growing preference for machines that can fit into tighter operational footprints. Not every environment can accommodate large ride-on systems, and not every task justifies the same level of mechanization. As a result, demand is expanding for compact and micro-scrubbing formats that can replace manual mopping in confined areas, stairs, and other specialized spaces. This is broadening the addressable use cases for scrubber-dryers beyond large open floors and into areas where labor intensity has historically been high.
The commercial implication is clear: segment boundaries are becoming more fluid. Manufacturers that offer a coherent range across compact, walk-behind, and ride-on formats are better positioned to capture demand from facilities with mixed surface types, varied room layouts, and diverse staffing models.
Supply Chain and Cost Structure Dynamics
Material selection and production efficiency are becoming more relevant to both cost positioning and sustainability claims. The use of recycled plastics in equipment construction is increasingly treated as a standard practice rather than a niche differentiator. This shift matters because it affects raw material exposure, production energy intensity, and the credibility of environmental messaging.
From a strategic standpoint, the move toward recycled content is not only about cost. It also aligns equipment manufacturing with broader procurement expectations around circularity and resource responsibility. In practical terms, companies that can source consistent grades of recycled polymers while maintaining durability and structural performance gain an advantage in both cost management and market positioning. The broader supply chain lesson is that cleaner production is increasingly tied to competitive resilience, especially when buyers expect documented environmental attributes in the products they purchase.
Competitive Landscape and Leadership Strategies
The competitive set in this market is diverse, but the leaders share a common strategic emphasis: they are building product portfolios that connect cleaning performance with efficiency, sustainability, and ease of use. The field includes established multinational manufacturers with broad commercial and industrial reach as well as specialized players focused on compact formats, heavy-duty applications, or integrated chemical and equipment solutions.
Nilfisk Group stands out for its focus on resource optimization and product-level efficiency messaging. Its recent activity signals an emphasis on reducing water and detergent consumption while improving energy performance, alongside construction choices that incorporate recycled materials. The company’s product actions also highlight a continued expansion into compact and micro-scrubbing formats, which suggests a deliberate effort to address smaller-space cleaning tasks that are often still handled manually. That combination of sustainability, usability, and format breadth is a meaningful strategic posture in a market where operating cost and user experience increasingly matter.
Alfred Kärcher SE & Co. KG brings a similar emphasis on efficiency, but with a strong construction and engineering identity. Its product narrative ties lithium-ion battery platforms, water dosing systems, and recycled-plastic construction together into a coherent value proposition. For commercial buyers, this creates an image of durability and operational efficiency that can be easier to justify in multi-year procurement decisions. Kärcher’s strength lies in combining recognizable brand reach with product features that support reduced resource use and practical maintenance.
Tennant Company is playing in a slightly different strategic lane by emphasizing cleaning technology that lowers water and detergent use while maintaining deep-cleaning performance. Its approach underlines the importance of differentiating through proprietary cleaning performance rather than only mechanical scale. This matters particularly in environments where floor condition, hygiene, and compliance are closely scrutinized. The expansion into smarter system capabilities illustrates a broader industry pivot toward operational optimization, where route efficiency, maintenance scheduling, and consistent output become part of the commercial argument.
Other notable players contribute additional forms of differentiation. Hako GmbH reinforces the professional floor maintenance segment with ride-on and walk-behind equipment, often valued for reliability and industrial usability. Taski, operating within a broader hygiene and cleaning portfolio, emphasizes integration between equipment and cleaning chemicals, which can be attractive to buyers seeking consistency between machine performance and consumable use. Numatic International Ltd addresses small to medium spaces with battery-powered walk-behind options, while companies such as RPS Corporation, Polivac, Eureka Sweepers, and Comac S.p.A. extend the market’s breadth across heavy-duty, large-area, and commercial maintenance applications. This diversity ensures that competition is not confined to a single format or use case; instead, it plays out across a set of overlapping customer needs.
Recent market activity highlights how rapidly the competitive conversation is moving. Product launches have centered on energy efficiency, reduced water and chemical consumption, recycled content, and ergonomic improvements that make machines easier to deploy in varied environments. At the same time, innovation recognition and exhibition activity have showcased telematics integration and smarter cleaning motion systems, pointing toward a future in which data visibility and operational control become more prominent.
The competitive landscape appears to be evolving along three main lines. First, there is consolidation of value around trusted brands that can offer multiple formats and demonstrable efficiency improvements. Second, there is fragmentation in specialized niches, particularly for compact cleaning, micro-scrubbing, and facility-specific applications where a general-purpose machine is not the best fit. Third, new entrants and technology-driven innovators are beginning to reshape expectations around autonomy, connectivity, and service integration. The likely outcome is not a single dominant model, but a layered market in which incumbents defend scale and breadth while challengers compete on intelligence, efficiency, and workflow fit.
Future Trends and Commercial Opportunities
Looking ahead, several trends are likely to define the next phase of market development. These are not speculative embellishments; they follow logically from current product direction, compliance pressure, and operational economics.
Efficiency as the Central Purchase Criterion
Over the next three to five years, the most decisive purchasing criterion will likely be resource efficiency paired with consistent output. Buyers will increasingly compare equipment not only by cleaning speed but by water consumption, detergent use, energy demand, and maintenance burden. This creates an opportunity for manufacturers that can quantify and standardize these benefits across product lines. For distributors and commercial end users, it creates an opportunity to shift procurement conversations from unit cost to lifecycle performance. The commercial opportunity lies in building credible efficiency benchmarks and aligning product portfolios so that each format has a clear operating-cost story.
Worldwide Spray Scrubbers Market
Growth of Compact and Specialized Cleaning Formats
Compact, battery-powered, and micro-scrubbing formats are poised to gain share in environments where manual cleaning remains common. This trend opens a meaningful opportunity for companies that can deliver ergonomic, easy-to-deploy machines that replace labor-intensive tasks without requiring large operational changes. The addressable opportunity is not just in new equipment sales but in expanding the number of spaces where mechanized cleaning is considered practical. At the same time, the opportunity depends on practical usability: compact units must be genuinely easier to handle, faster to set up, and simple enough to encourage adoption across different staff skill levels.
Smarter Operations and Connected Maintenance
Telematics, route optimization, and maintenance scheduling are likely to become more central to high-value deployments, especially in larger commercial facilities. As equipment becomes more connected, the value of the machine extends into facility management visibility: operators can better plan labor, anticipate servicing needs, and reduce downtime. This trend favors manufacturers and service providers that can integrate hardware, software, and support into a coherent offering. The strategic risk is that connectivity becomes an expected baseline rather than a differentiator, which means early leaders must continue improving data quality, usability, and integration depth to stay ahead.
PW Consulting
These trends carry uncertainties. One risk is that regulatory expectations continue to evolve faster than product documentation and verification practices, creating compliance gaps for manufacturers and buyers alike. Another is that cost pressures could limit adoption of newer, higher-efficiency equipment in some segments, especially where budgets are constrained and procurement remains highly price-focused. A third uncertainty is the pace at which labor availability and wage dynamics will continue to push organizations toward automation and ride-on formats. If labor markets stabilize or facility budgets tighten, adoption curves could diverge by region and sector.
Strategic Actions for Decision-Makers
Different stakeholders will need different priorities, but a few strategic actions apply broadly.
- For manufacturers and product leaders: Prioritize efficiency claims that can be substantiated across energy, water, detergent, and material use. Develop portfolios that span compact, walk-behind, and ride-on formats with clear use-case positioning, so that sales conversations can match equipment to environment rather than forcing a one-size approach. Invest in serviceability and operator usability, because ease of maintenance and training often determines whether a machine is adopted consistently in day-to-day operations.
- For investors and strategic planners: Focus on companies that combine credible sustainability attributes with repeat purchase potential in service, consumables, and replacement cycles. The most durable value may come not from unit sales alone but from ecosystems that include maintenance, resource-efficient consumables, and operational support. Monitor competitive moves in connectivity, compact formats, and recycled-material construction, since these are becoming signals of longer-term pricing power and market relevance.
- For procurement and facility operators: Evaluate scrubber-dryers against total operating cost and consistency rather than sticker price. Consider how each format fits the physical layout, staffing model, and compliance requirements of the site. Where space constraints, labor intensity, or hygiene expectations are significant, compact and battery-powered options can unlock productivity gains without requiring a full fleet replacement. Where larger areas dominate, ride-on and higher-productivity units may offer stronger labor reallocation benefits.
The strategic throughline is that scrubber-dryers are becoming decision platforms rather than simple cleaning tools. Efficiency, sustainability, labor economics, and workflow integration now shape purchasing and product strategy in tandem. Companies and buyers that treat these factors as linked will be better positioned to choose equipment, structure procurement, and plan for the next cycle of market development.
For organizations that need deeper segmentation detail, regional context, and customized scenario planning, the full PW Consulting research report on the scrubber-dryers market provides expanded data and targeted analysis across market size trajectories, product types, application settings, and competitive developments. It is designed to support more precise decisions in portfolio strategy, investment review, and procurement planning.
For detailed analysis of this topic, please visit the official page: Scrubber-Dryers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
FT Wax Market 2026: Why a 6.2% CAGR Reshapes Industry Competition Through 2032
By pmarketresearch, 2026-09-21
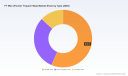
The Fischer-Tropsch Wax Market: Strategic Trends and Commercial Opportunities Through 2032
The Fischer-Tropsch wax market has entered a phase of structural maturation, driven by a convergence of sustainability mandates, feedstock advantage, and application-specific performance requirements. Valued at approximately USD 920.0 million in 2025, the market is projected to expand to USD 1,409.8 million by 2032, reflecting a compound annual growth rate of 6.2 percent. This trajectory signals more than steady expansion; it indicates a market shifting from commodity substitution toward engineered performance materials. For executives, strategic planners, and investors, the window for positioning around FT wax is narrowing as supply chains reorganize, regulatory pressure intensifies, and downstream formulators demand verifiable sustainability credentials alongside technical superiority.
Market Landscape and Structural Challenges
The FT wax segment occupies a distinct niche within the broader hydrocarbon and specialty wax ecosystem. Unlike traditional paraffin or fully synthetic alternatives, FT waxes benefit from a gas-to-liquid synthesis route that yields tightly controlled molecular weight distributions, low impurity profiles, and customizable crystal structures. These characteristics have enabled FT waxes to penetrate performance-sensitive applications where consistency, hardness, and thermal behavior are non-negotiable. The market's size and growth path reflect this positioning, with demand accumulating steadily across multiple industrial and consumer-facing categories.
Microcrystalline Wax Market
Despite the favorable growth backdrop, three structural challenges are reshaping how participants compete and how end-users evaluate supply options.
First, feedstock geography and supply chain concentration create inherent vulnerability. Production capacity remains clustered in regions with proximate natural gas availability and established GTL infrastructure, including North America, Southern Africa, and parts of East Asia. While this concentration reflects the underlying chemistry and economics of FT synthesis, it also introduces logistics friction. Customers located far from production hubs face elevated freight exposure and lead-time variability, which can compress margins and complicate just-in-time formulations. Strategic sourcing now requires balancing technical grade availability with geographic risk, a consideration that was secondary when wax was treated as a low-cost inert additive.
Second, regulatory and sustainability expectations are redefining procurement criteria. Coatings, packaging, adhesives, and personal care formulators are under mounting pressure to reduce volatile organic compound emissions, improve product carbon footprints, and demonstrate responsible sourcing. FT waxes offer a structurally cleaner profile relative to some conventional routes, particularly when produced via natural gas-based GTL pathways. However, market adoption now hinges on documented lifecycle advantages, grade-level consistency, and the ability to integrate into low-VOC or solvent-reduced systems without sacrificing performance. Specifications that once emphasized melting point and hardness are increasingly paired with carbon intensity, traceability, and regulatory compliance documentation.
PW Consulting
Third, the market is navigating a differentiation dilemma across wax categories. FT-derived waxes span hard paraffin-like grades, microcrystalline variants, and oxidized or micronized specialty formats, each optimized for distinct end-use behaviors. At the same time, customers increasingly seek hybrid solutions that combine FT performance with cost-effective processing and compatibility with existing production lines. Suppliers that can articulate a clear grade-to-application mapping and provide formulation support are gaining advantage, while undifferentiated product listings struggle to justify premium positioning.
Key Demand Drivers
Technology Innovation and Grade Engineering
Technological progress in FT wax production is shifting the conversation from availability to precision. Advances in catalyst selectivity, fractionation control, and particle engineering have expanded the range of achievable hardness, melt behavior, and dispersion characteristics. Micronized and oxidized grades now enable formulators to fine-tune abrasion resistance, slip properties, and compatibility with polymer matrices, paints, and hot-melt systems. The availability of grades designed for spray application, low dust handling, or enhanced dispersion reduces the integration burden for downstream manufacturers and unlocks use cases where conventional waxes previously underperformed.
This trajectory matters for commercial strategy because it changes the value proposition. FT wax is no longer competing solely on price-per-ton; it is competing on total formulation efficiency, process reliability, and end-product performance. Companies that align their portfolio development with application-driven grade engineering are better positioned to capture premium segments and defend margins as volume growth accelerates.
Policy and Regulatory Tailwinds
Environmental regulation and corporate sustainability targets are accelerating substitution toward FT waxes in multiple application streams. VOC reduction mandates, packaging recyclability expectations, and coatings durability requirements are pushing formulators to seek alternatives that maintain technical performance while improving environmental profiles. In several markets, FT waxes are gaining traction as drops-in or near-drops-in solutions that support lower-emission formulations and cleaner processing conditions.
The commercial implication is twofold. First, regulatory momentum creates a durable demand pull that is less sensitive to short-term economic cycles than discretionary industrial spending. Second, it raises the bar for supplier credibility. Customers increasingly require evidence of consistent grade quality, supported sustainability claims, and the ability to navigate evolving compliance frameworks across regions. Suppliers that can deliver transparent documentation and stable specification control are better placed to convert regulatory tailwinds into long-term contracts.
Demand-Side Shifts in Coatings, Cosmetics, and Packaging
End-use behavior is changing in ways that favor FT wax's performance envelope. In coatings and related surface treatment applications, the push for durability, scratch resistance, and controlled surface appearance supports continued demand for waxes that deliver predictable hardness and dispersion. In cosmetics and personal care, formulation precision, purity, and sensory consistency are paramount, creating demand for high-purity grades with tightly controlled melting and rheological behavior. Packaging adhesives and polymer processing also benefit from FT wax's ability to improve tack control, slip, and compatibility in complex formulations.
These demand shifts are not uniform. Growth is strongest where FT wax solves a specific technical bottleneck rather than serving as a generic filler or processing aid. This observation is critical for commercial planning: the highest-value opportunities are concentrated in applications where FT wax enables formulation simplification, performance enhancement, or compliance improvement that would otherwise require more expensive or complex alternatives.
Supply-Side and Cost Structure Dynamics
The economics of FT wax synthesis remain tied to feedstock availability and GTL capacity utilization. Natural gas continues to be the dominant feedstock base, supporting a production route with comparatively low sulfur content and favorable impurity control relative to coal-based alternatives. This structural advantage reinforces FT wax's positioning in applications where cleanliness and consistency matter. At the same time, capital intensity and regional capacity distribution constrain how quickly supply can respond to localized demand surges.
Cost structure dynamics are increasingly shaped by logistics and grade specialization rather than raw feedstock price alone. Even when base feedstock economics are stable, transportation exposure and specialized handling requirements can influence delivered cost and customer economics. Participants that invest in regional supply optimization, packaging efficiency, and application support can mitigate these pressures and create a more defensible cost-to-serve profile.
Competitive Landscape and Leading Strategies
The FT wax market features a mix of global integrated producers, specialty refiners, and regionally focused manufacturers, each pursuing distinct competitive positions. The landscape is characterized by concentrated expertise in GTL-based synthesis, differentiated grade portfolios, and varying degrees of application-level support.
Sasol operates as a global reference point in GTL-derived FT wax, offering a broad range of hard, medium, micronized, and oxidized grades for coatings, inks, adhesives, polishes, and polymer additives. Its scale and integrated chemistry capability give it a strong foundation for consistent supply and portfolio breadth. Recent product activity underscores a strategy of linking grade innovation with sustainability differentiation. In mid-2024, the company introduced a new industrial wax grade for packaging adhesives designed with a materially lower cradle-to-gate carbon footprint compared with conventional alternatives. It subsequently expanded its micronized FT wax portfolio with spray-oriented grades, signaling an emphasis on application convenience, dispersion performance, and handling efficiency. This dual focus on performance and carbon intensity reflects a broader industry shift: leading players are increasingly competing on documented sustainability outcomes as well as technical grade capability.
Shell maintains a position rooted in GTL-derived materials integrated into base oils and specialty product streams, with FT wax functionality extending into additives and sustainable aviation fuel feedstock pathways. Its strategic relevance lies in the interplay between FT chemistry and broader energy transition portfolios. By connecting wax production to larger hydrocarbon and low-carbon fuel initiatives, Shell can leverage feedstock flexibility and process integration, though the wax-specific commercial strategy is shaped by how it prioritizes specialty product development versus broader energy investments.
Deurex AG competes as a specialist in micronized and oxidized FT waxes, emphasizing high hardness, abrasion resistance, and controlled particle size. Its product logic targets applications where mechanical performance and precise dispersion are decisive. This specialization enables a focused value proposition but also demands deep application expertise and close customer collaboration to justify premium positioning.
Evonik Industries AG brings FT wax capabilities into formulations for PVC lubricants, printing inks, coatings, and hot-melt systems. Its approach illustrates how FT wax can be embedded within broader specialty chemical portfolios, where wax performance is paired with formulation knowledge and downstream compatibility support. The competitive edge here is less about volume scale and more about application integration and technical service.
Nippon Seiro Co., Ltd. focuses on refining FT waxes through specialized synthesis routes to deliver high-purity, high-melting-point grades with low impurity levels, particularly relevant for cosmetics and industrial uses. In markets where purity and consistency directly affect end-product acceptance, this refined-grade positioning can command strong customer loyalty and create barriers tied to qualification and specification approval.
In China, multiple manufacturers have expanded FT paraffin and oxidized wax offerings for polymer processing, coatings, masterbatches, and filler dispersion. King Honor International, Tianshi Group, Jiangsu Faer Wax Industry Co., Ltd., and similar players reflect the region's growing capacity to serve both domestic demand and export channels. Their strategies often combine scale, grade variety, and cost competitiveness, while increasingly needing to address quality consistency and sustainability documentation as export and premium-segment requirements intensify. Paramelt operates with a sourcing and supply investment model, building global capacity access for mineral hydrocarbon and synthetic wax applications. Its positioning highlights a different route to market: rather than owning every step of FT synthesis, it focuses on distribution reach, supply reliability, and application connectivity.
The competitive evolution is moving along two parallel tracks. On one hand, scale players continue to strengthen portfolio breadth and sustainable grade development, leveraging integrated feedstock and process advantages. On the other, specialists and regional manufacturers are carving out niches through particle engineering, purity control, application-specific grades, and cost-driven flexibility. Consolidation is plausible where scale, feedstock access, and sustainability credentials matter most, while fragmentation may persist in highly application-specific segments where customer qualification cycles and technical service create local moats. New entrants will likely face steep barriers in GTL-based FT wax due to process complexity and qualification requirements, but differentiated refining, micronization, or regional distribution models can still create entry points.
Forward-Looking Trends
Sustainability-Embedded Grade Design as a Baseline Expectation
Over the next three to five years, sustainability performance is expected to become a standard component of FT wax purchasing decisions rather than a differentiating bonus. Customers in coatings, packaging, and cosmetics will increasingly require grades that support lower-carbon formulations, cleaner processing, and documented environmental claims. This trend creates commercial opportunities for suppliers that invest early in lifecycle transparency, grade-level carbon differentiation, and regulatory-ready documentation. It also introduces risk for participants that treat sustainability as a communications exercise rather than an integrated product development priority.
Application-Driven Specialization and Formulation Integration
Growth is likely to concentrate where FT wax enables measurable formulation gains. Micronized dispersion, spray-ready handling, oxidation control, and compatibility with polymer and coating systems will remain decisive in capturing premium demand. Companies that pair grade development with formulation guidance, trial support, and process integration advice will be better positioned to secure long-term relationships and reduce price sensitivity. The risk here is overgeneralization: portfolios that expand without clear application logic may dilute focus and weaken commercial positioning.
Supply Chain Reconfiguration and Regional Sourcing
Geographic concentration will continue to influence sourcing strategy. As customers seek to reduce logistics exposure and improve supply resilience, regional partnerships, localized inventory models, and grade availability in closer proximity to demand centers will become more valuable. This trend opens opportunities for producers and distributors that can offer reliable regional supply, flexible packaging, and responsive technical support. The uncertainty lies in how rapidly new capacity can be economically justified and how demand patterns evolve across regions with different regulatory and cost environments.
Strategic Actions for Decision-Makers
For manufacturers and formulators, the priority is to align FT wax adoption with application economics rather than treating wax selection as a generic commodity decision. Evaluate grades against total formulation impact, including dispersion behavior, processing reliability, VOC-compatible performance, and sustainability documentation. Where FT wax can simplify a formulation, improve end-product quality, or support compliance goals, the value case often extends beyond unit price. Build qualification pathways early for grades that meet both technical and sustainability criteria, and develop internal benchmarks that compare FT wax not only with conventional waxes but also with alternative additives that may appear cheaper on paper yet incur higher processing or performance costs.
For investors, the attractive exposure is in companies that combine process capability with application-level differentiation and credible sustainability positioning. Scale alone is not sufficient; the most resilient business cases are emerging where feedstock advantage, grade engineering, and customer support reinforce one another. Pay attention to how producers are expanding into lower-carbon grades, micronized and oxidized specialties, and regional supply improvements, as these signals indicate where future margin and retention may come from. Also monitor logistics exposure and capacity location, since geographic concentration can create both cost risk and opportunity for suppliers that address proximity and reliability needs.
Car Wax Market
For procurement and sourcing leaders, the strategic task is to reduce vulnerability without sacrificing performance. Diversify grade sources where possible, prioritize suppliers with consistent specification control and transparent documentation, and evaluate total delivered cost rather than ex-works price alone. Where application sensitivity is high, consider longer-term supply agreements that secure grade availability and technical support, especially for specialized micronized or oxidized formats. In parallel, use FT wax adoption as a lever to support internal sustainability targets, provided the selected grades can substantiate the claimed advantages and integrate cleanly into existing processes.
The FT wax market is entering a period in which technical performance, supply reliability, and sustainability evidence must be evaluated together. The most consequential decisions will be made by organizations that can distinguish between generic wax purchasing and application-specific value creation. For executives and strategic teams seeking deeper segmentation data, grade-level demand mapping, regional supply assessments, and customized scenario analysis, a detailed commercial research report can provide the granularity needed to translate these market-wide trends into precise sourcing, investment, and product development choices.
For detailed analysis of this topic, please visit the official page: FT Wax (Fischer Tropsch Wax) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Classical Swine Fever Vaccines Market: How Asia Pacific Leads the 5.62% CAGR Shift
By pmarketresearch, 2026-09-21
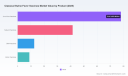
Classical Swine Fever Vaccines Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for Classical Swine Fever (CSF) vaccines is entering a phase of structural transformation. Absolute revenue has expanded from $118.45 million in 2020 to $141.12 million by 2025, with a projected trajectory toward $208.81 million by 2032. This growth trajectory, supported by a 5.62% compound annual growth rate over the 2026–2032 forecast window, reflects more than incremental demand expansion; it signals a market recalibrating around technology differentiation, regulatory pragmatism, and regional risk profiles. For executives and investors, the opportunity lies not simply in volume growth but in capturing value at the intersection of DIVA-compatible vaccine design, supply chain resilience, and policy-driven adoption shifts.
Understanding the CSF vaccine landscape requires looking beyond headline figures. The market is fragmented, with top-three competitors holding less than a quarter of total revenue and the top five collectively accounting for just over 31%. This fragmentation is not accidental. It reflects heterogeneous regional disease pressures, divergent regulatory philosophies, and the technical complexity of matching vaccine platforms to specific outbreak-control or endemic-prevention strategies. Growth is being pulled from distinct directions simultaneously, and the winners will be those who align product portfolios, manufacturing footprints, and partnerships with regional risk realities rather than pursuing a one-size-fits-all global play.
Resilience in a Fragmented, Risk-Aware Market
Despite steady revenue expansion, the CSF vaccine market faces a set of interlocking challenges that will define competitive positioning over the next several years. The first is the tension between emergency outbreak response and routine prophylactic use. In regions where CSF remains endemic or where disease incursions remain a constant threat, vaccine deployment is often triggered by policy directives or outbreak events rather than organic commercial demand cycles. This creates revenue patterns that are sensitive to political decision-making, trade restrictions, and compensation schemes for stamping-out versus vaccination strategies. Companies operating in this space must build forecasting models that account for policy volatility as much as biological demand.
Avian Influenza Vaccines Market
A second challenge lies in the diversity of vaccine technologies and the operational trade-offs they entail. Traditional modified live virus (MLV) vaccines dominate current revenue, supported by long-standing manufacturing know-how and established field efficacy. Yet these platforms carry inherent complexities in seed-lot validation, batch consistency, and in some cases regulatory scrutiny related to residual virulence or differentiation challenges. Alternative platforms such as subunit, DNA, and vector vaccines represent a smaller but strategically significant share of the market. They promise improved safety profiles and, in certain designs, compatibility with companion diagnostic tests that distinguish vaccinated from infected animals. The challenge for manufacturers is that these alternatives often require different production infrastructure, distinct regulatory submissions, and new commercial partnerships with diagnostic developers to unlock their full field value.
A third structural pressure relates to cost economics and regional procurement behavior. Labor cost patterns, raw material sourcing, and the validation burden associated with conventional production methods all influence the economics of vaccine supply. In price-sensitive markets, procurement decisions can tilt toward lowest-cost options that are still accepted by national veterinary authorities. In higher-regulation regions, procurement decisions weigh differentiation capability, emergency-readiness status, and alignment with regional surveillance frameworks. The result is a market where value capture depends as much on regulatory navigation and technical messaging as on product performance alone.
The Forces Reshaping Demand and Supply Dynamics
Four drivers are currently exerting the strongest influence on the CSF vaccine market's evolution, and each carries a distinct commercial implication.
Technological innovation and differentiation capability. The push toward DIVA-compatible vaccines has become a defining theme. Vaccines that enable differentiation between infected and vaccinated animals reduce a fundamental barrier to vaccination adoption in regions where trade restrictions and surveillance protocols traditionally discourage routine immunization. Recent commercial development activity illustrates this direction. In December 2024, DABACO Vietnam Group Joint Stock Company initiated a commercial development agreement for a FlagT4Gv live attenuated DIVA-compatible marker CSF vaccine alongside an associated ELISA test, working in coordination with USDA ARS. This type of partnership signals a shift from vaccine-only commercial models toward integrated solutions that pair immunization with companion diagnostics. For manufacturers, this creates two paths to value: developing or licensing DIVA-compatible candidates, and building the diagnostic ecosystem relationships necessary for field adoption.
Regulatory environment and emergency-use frameworks. Regulatory decisions are shaping competitive access as much as product science. The CP7_E2alf chimeric pestivirus vaccine was licensed by the European Medicines Agency for emergency vaccination under a specific marketing authorization, a decision that institutionalized emergency vaccination as a realistic option within EU frameworks rather than a theoretical contingency. This kind of authorization does not simply expand the addressable market; it changes procurement planning, stockpiling expectations, and the commercial logic of regional supply commitments. At the same time, production platforms continue to evolve under guidance frameworks such as WOAH terrestrial animal health standards, which outline requirements for conventional MLV production methods as well as insect-cell baculovirus systems used in certain marker vaccine production. The practical implication is that regulatory alignment is becoming a competitive moat. Companies that can demonstrate consistent compliance, clear differentiation pathways, and emergency-use readiness will gain preferential access in policy-sensitive procurement cycles.
Demand-side changes in animal protein systems. The pandemic-era stress on global protein supply chains accelerated a broader recognition of livestock health as a strategic input rather than a peripheral operational concern. Biosecurity investment, surveillance expansion, and vaccination readiness are increasingly treated as integral to supply assurance. This shift supports steady demand growth for CSF vaccines, especially in regions where production intensification is increasing the economic cost of disease outbreaks. Importantly, demand is not homogenous. In some markets, producers and government buyers are prioritizing vaccines that minimize trade disruption risk; in others, the priority is cost-effective routine protection. Manufacturers that segment their go-to-market strategy by risk profile rather than treating the market as a single demand pool will extract more value from the same growth curve.
Supply chain and cost-structure evolution. Manufacturing economics for CSF vaccines span a spectrum from traditional cell-culture or passage-based methods to more modern recombinant systems. Conventional MLV production involves variable seed-lot validation and processes that can create batch-to-batch consistency challenges and cost variability. Meanwhile, insect-cell baculovirus vector platforms, while technically more complex to establish, can reduce certain contamination risks and support more scalable production for specific recombinant antigens. The cost implications are not simply about unit price. They encompass validation overhead, regulatory documentation, raw material security, and the ability to respond to surge demand during outbreak events. Companies that invest in flexible manufacturing strategies and secure key inputs are better positioned to protect margins during demand spikes and avoid supply disruptions that erode customer confidence.
Competitive Positioning and Market Evolution
The competitive landscape for CSF vaccines is characterized by a small set of established players with distinct technological and geographic positioning, alongside emerging regional participants seeking to strengthen local supply security and differentiation capabilities.
Zoetis holds a recognizable commercial position through its production of Suvaxyn CSF Marker, a CP7_E2alf chimeric pestivirus vaccine designed for emergency vaccination use. The strategic significance of this offering lies in its alignment with regulatory authorization for emergency contexts and its marker-vaccine logic, which supports differentiation objectives. Zoetis's positioning suggests a commercial approach built around readiness, regulatory credibility, and integration with broader livestock health portfolios. In markets where emergency vaccination frameworks exist or are being evaluated, this type of product architecture provides a natural entry point for procurement discussions and stockpiling commitments.
Boehringer Ingelheim is associated with Ingelvac CSF MLV, a C-strain modified live virus vaccine aimed at use in endemic regions. This reflects a different strategic logic: durable, field-tested protection for areas where CSF pressure is persistent rather than episodic. The C-strain lineage has historical credibility, and its application in endemic settings positions the company in a demand environment driven by routine prevention and regional disease baselines. For competitors, this highlights the importance of understanding whether a given market's primary pull comes from emergency preparedness or endemic control, since the purchasing criteria, salesforce engagement model, and inventory planning requirements differ substantially between them.
DABACO Vietnam Group Joint Stock Company illustrates the rise of regional players pursuing differentiation through DIVA-compatible technology and international R&D collaboration. The December 2024 commercial development agreement for FlagT4Gv and its associated ELISA test, initiated with USDA ARS, reflects a strategy that blends local manufacturing or commercialization presence with scientifically credible external partnerships. Regional players can compete not only on price but on proximity to local disease ecology, faster response cycles, and alignment with national veterinary strategies. This creates pressure on global incumbents to reinforce the local relevance of their offerings, whether through localized production, tailored registration strategies, or partnerships that enhance surveillance and differentiation support.
The broader market trajectory appears to be moving toward selective consolidation on the commercial side alongside fragmentation in technology development. Registered, emergency-approved, or DIVA-compatible products provide clearer competitive differentiation than undifferentiated conventional vaccines in many procurement contexts. At the same time, new entrants and regional manufacturers can gain ground where local policy support, cost structure advantages, or collaboration with research institutions create a credible technical narrative. The likely outcome is not a single dominant technology standard but a layered market in which emergency-use marker vaccines, endemic MLV products, and next-generation recombinant or vector-based candidates each capture distinct segments of demand. Competition will increasingly revolve around ecosystem readiness: registration status, diagnostic compatibility, supply reliability, and the ability to respond to outbreak-driven procurement surges.
Where the Market Is Heading Over the Next 3–5 Years
Several forward-looking trends are emerging from the current data and development activity, each with clear commercial implications.
DIVA-compatible and diagnostic-integrated solutions will become more central to procurement decisions. As more regions explore or expand vaccination programs that must coexist with trade considerations and surveillance integrity, vaccines paired with validated companion diagnostics will carry an advantage. The commercial opportunity is twofold: vaccine suppliers can capture higher-value engagements by offering integrated solutions, and diagnostic partners can secure embedded demand through technology co-development. The risk is that adoption depends on regulatory endorsement of specific test-vaccine combinations, which can slow rollout if approvals are staggered or if validation requirements differ across markets. Companies should anticipate longer commercial launch cycles tied to paired validation rather than single-product registration alone.
Regional demand will increasingly be shaped by policy posture as much as disease prevalence. Markets where vaccination is formally integrated into contingency planning or endemic control schemes will exhibit steadier demand profiles and greater willingness to invest in differentiation-capable products. Conversely, markets that rely predominantly on stamping-out policies may experience more episodic, emergency-driven demand. Over the next few years, the commercial task is to monitor policy evolution closely and position supply commitments accordingly. The upside is that policy shifts toward vaccination acceptance can rapidly expand the addressable market in a given region; the downside is that procurement can be abrupt and volume commitments can fluctuate if policy is revised in response to outbreak outcomes or political pressures.
Manufacturing platform diversity will become a strategic differentiator rather than a technical detail. As procurement authorities place greater weight on supply reliability, batch consistency, and readiness for surge demand, platforms that can balance safety, scalability, and validation efficiency will be valued more highly. Insect-cell and other recombinant approaches may gain share where they align with differentiation objectives and regulatory expectations, while conventional platforms will continue to play a role in endemic settings where cost efficiency and historical acceptance remain paramount. The strategic risk here is investment timing: committing to a platform transition without clear regulatory or market pull can create stranded capability, while waiting too long can cede credibility in markets that increasingly reward modernized production narratives.
New regional entrants and partnership-based commercialization will intensify competitive pressure. The combination of local manufacturing ambitions, research institution collaboration, and regional disease expertise creates a pathway for credible competitors outside the established global tier. This does not necessarily imply global displacement of incumbents; more likely, it means regional share erosion in specific geographies unless incumbents reinforce local relevance, pricing architecture, and differentiation support. The commercial opportunity is for incumbents to complement global registration and portfolio strength with regional execution depth, and for newer entrants to use partnerships and differentiated product logic to build defensible positions.
Strategic Implications for Decision Makers
For vaccine manufacturers, the priority is to align product architecture with the differentiated demand the market is creating. This means evaluating whether current portfolios are sufficiently positioned for both emergency-use contexts and endemic routine protection, and whether the company has credible pathways to DIVA-compatible designs where that aligns with target markets. Manufacturers should also review manufacturing strategy through the lens of surge readiness and validation efficiency, since these factors increasingly influence procurement preference beyond unit cost alone. Where appropriate, diagnostic partnerships or co-development arrangements can strengthen the commercial proposition and open access to procurement processes that value integrated solutions.
For investors, the most relevant signals are regulatory authorization milestones, DIVA-compatible development activity, and regional policy shifts that change vaccination adoption posture. Revenue growth in this market is real, but it is unevenly distributed across technologies and regions, and it is sensitive to policy catalysts. Due diligence should therefore focus less on aggregate market size alone and more on which product categories and geographies are likely to capture disproportionate value in the forecast period. Particular attention should be paid to companies with credible differentiation capability, emergency-use alignment, and manufacturing strategies that can withstand demand volatility without compromising continuity.
Worldwide Waterfowl Vaccines Market
For procurement authorities and production operators, the strategic emphasis should be on matching vaccine selection to the operational and trade objectives of the region. Where differentiation capability and emergency readiness matter, marker or DIVA-compatible options and their associated diagnostic support should be evaluated alongside traditional MLV products. Where endemic control and cost efficiency dominate, conventional products may remain appropriate, but procurement planning should still account for validation requirements, supply reliability, and the possibility of policy shifts that change the relative attractiveness of different vaccine types. Long-term contracts, stockpiling considerations, and supplier diversification should be shaped by the region's expected disease and policy trajectory rather than short-term price comparisons alone.
PW Consulting
The CSF vaccine market is expanding, but the value within that expansion is unevenly distributed across technologies, regulatory contexts, and regional demand profiles. Companies and investors that treat the market as a set of differentiated opportunity pockets—rather than a uniform growth story—will be better positioned to act on the right opportunities with the right timing. For decision makers seeking a deeper breakdown of segment dynamics, regional variation, and company-level strategic positioning, the full PW Consulting report provides the detailed segmentation data and customized scenario analysis needed to translate these trends into executable plans.
For detailed analysis of this topic, please visit the official page: Classical Swine Fever Vaccines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Chemical Polishing Slurry Market: Why 7.2% CAGR and Asia Pacific Drive 2032 Expansion
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Chemical Polishing Slurry Market
1. Market Landscape and Core Challenges
The global chemical polishing slurry market has demonstrated consistent expansion, growing from $1,580.0 million in 2020 to an estimated $2,048.0 million in 2025. This trajectory reflects a compound annual growth rate of 7.2% over the historical period, with projections indicating the market will reach $3,331.0 million by 2032. The compound annual growth rate remains stable through the forecast horizon, signaling that demand drivers are structural rather than cyclical.
Regional distribution reveals a clear concentration of activity in Asia Pacific, which accounts for the largest share of market value, followed by North America and Europe. The remaining regions—Latin America and the Middle East and Africa—represent smaller but steadily growing pockets of demand. By material composition, silica-based formulations dominate the product mix, with alumina-based and ceria-based slurries occupying meaningful but secondary positions. Application segments are heavily anchored in integrated circuits, which represent the largest end-use category, while memory devices and advanced packaging follow as substantial secondary demand centers.
This broad expansion masks several structural friction points that market participants must navigate. First, the industry operates under a highly concentrated competitive structure, with the top three players controlling roughly 65% of total revenue and the top five commanding approximately 78%. This concentration creates high barriers to entry and limits the ability of smaller firms to compete on scale or pricing alone. Second, the sector sits at a technological inflection point where traditional slurry formulations must adapt to ever-smaller feature sizes, new dielectric materials, and tighter defectivity tolerances. Legacy recipes that performed adequately at earlier technology nodes often fail to meet the selectivity, uniformity, and removal rate requirements of modern fabrication lines. Third, the supply chain remains vulnerable to raw material volatility and regulatory shifts, which can compress margins or force abrupt reformulation cycles.
2. Key Drivers of Market Change
Technological Innovation and Process Evolution
The push toward more advanced semiconductor architectures continues to reshape slurry requirements. As device manufacturers transition to finer patterning and multi-layer integration, polishing solutions must balance aggressive material removal with minimal subsurface damage and low defect counts. This has spurred development in monodispersed colloidal silica formulations, tighter particle size distributions, and engineered surface chemistries that improve selectivity between different film stacks. Entegris, Inc. expanded its CMP slurry production capacity in Taiwan in October 2025 to position closer to leading foundries, a move that reflects the broader industry emphasis on co-locating chemical supply with high-volume fabrication hubs to accelerate development cycles and reduce logistical friction.
CMP Slurries Market
Beyond node scaling, the rise of advanced packaging and heterogeneous integration has introduced new material interfaces that require tailored planarization behavior. Slurry suppliers are increasingly expected to provide formulations that work across oxide, tungsten, polysilicon, and barrier layers without compromising downstream yield. This demand for versatility is pushing R&D teams toward modular formulation platforms rather than single-purpose products, enabling faster adaptation when fab processes change.
Regulatory and Compliance Pressures
Regulatory requirements are becoming a more visible force in slurry development and distribution. Chemical mechanical planarization slurries that contain hazardous components must be accompanied by comprehensive safety documentation, and recent alignment with GHS standards and China GB/T 16483 requirements has raised the compliance burden for cross-border trade. In China, CMP slurry products fall under State Council Order 591 for the safety management of hazardous chemicals, which influences storage, handling, transportation, and import procedures. These regulatory layers do not merely add paperwork; they affect time-to-market, distribution logistics, and the cost structure of serving certain geographies. Firms that build robust compliance frameworks early gain an advantage in securing long-term supply agreements with fabs that face their own audit and risk management obligations.
Demand-Side Shifts in Semiconductor Manufacturing
Semiconductor demand continues to be shaped by the growth of high-performance computing, memory expansion, and the broadening use of integrated sensors and connectivity modules. These applications drive wafer starts and, by extension, the volume of planarization steps required across design nodes. At the same time, fabrication strategies are shifting toward higher-mix, higher-margin production, which increases the importance of chemical suppliers that can support multiple process flows and respond quickly to recipe adjustments. Beijing Grish Hitech Co., Ltd. updated its CMP slurry product catalog in March 2025, introducing new particle size grades in the 50–110 nm range for semiconductor and LED applications. This kind of incremental product broadening illustrates how suppliers are aligning their offerings with the precision demands of current device fabrication while keeping pace with adjacent markets such as optoelectronics and optical glass.
Worldwide Polishing Slurry Market
Supply Chain and Cost Structure Dynamics
Input cost volatility remains a recurring theme. Cerium oxide prices rose 45% in March 2025 following a 10% increase in China-origin imports, according to industry reporting. Because ceria-based slurries are important for certain oxide removal applications, price spikes in foundational raw materials can compress supplier margins and, if passed through to customers, affect procurement budgets. This environment encourages several responses: dual sourcing for critical minerals, longer-term supply contracts, formulation adjustments that reduce dependence on the most volatile inputs, and vertical integration where feasible. The cost structure of slurry manufacturing is therefore becoming more strategic, with procurement, logistics, and regulatory compliance increasingly treated as core capabilities rather than support functions.
3. Competitive Landscape and Leading Strategies
Differentiation Among Established Players
The competitive field features a mix of global specialty chemical suppliers and regionally focused manufacturers, each pursuing distinct strategic positions. Cabot Microelectronics Corporation operates as a leading global supplier of high-purity fumed silica dispersions and custom CMP slurries for semiconductor wafer planarization, with a strong emphasis on process reliability and close collaboration with major device makers. Fujimi Incorporated is known for its PLANERLITE series, which addresses ILD/STI, tungsten, polysilicon, barrier, and oxide applications, positioning the company around a broad application catalog and established customer relationships in Japan and beyond. Entegris, Inc. focuses on dielectric and specialty CMP slurries, including ceria formulations designed for advanced nodes, and its recent capacity expansion underscores a strategy tied to geographic proximity and service responsiveness.
Asian manufacturers bring complementary strengths. Beijing Grish Hitech Co., Ltd. supplies colloidal silica-based CMP slurries for semiconductor, LED, optical glass, and metal polishing, leveraging a diversified end-use base that can buffer volatility in any single segment. JSR Corporation develops mono-dispersed colloidal silica CMP slurries aimed at selective layer polishing and low defectivity, aligning its product logic with the precision requirements of next-generation processes. Ace Nanochem Co., Ltd., based in South Korea, specializes in oxide CMP slurries, silicon wafer stock slurries, edge and backside polishing slurries, and colloidal silica for semiconductors, an offering set that spans both front-end and ancillary polishing needs. Jizhi Electronic Technology Co., Ltd. serves as a specialist supplier of oxide CMP slurries for STI and metal applications, with local technical support focused on the Yangtze Delta fab cluster, an approach that prioritizes proximity, responsiveness, and regional knowledge.
Strategic Themes in the Competitive Field
Several strategic themes emerge across these players. Proximity to major fabrication centers is increasingly treated as a competitive asset, both for faster development cycles and for more reliable supply. Product breadth is being balanced against deep specialization, with companies maintaining a core of high-value formulations while selectively broadening into adjacent applications. Regulatory readiness and documentation quality are becoming differentiators in markets where hazardous chemical management is tightly controlled. At the same time, customers are pushing suppliers toward greater transparency in particle characteristics, removal behavior, and defect performance, which raises the bar for quality systems and technical support.
Market Structure Evolution
The competitive structure appears likely to continue along a path of consolidation among scale players and selective inroads by specialized entrants. Large suppliers benefit from established qualification pipelines, broad formulation libraries, and the ability to absorb raw material fluctuations more readily. Smaller or regional suppliers can compete by offering rapid technical support, customized grades, and lower-friction engagement with local fab ecosystems. Entrants that are purely cost-driven face steep qualification hurdles and limited pricing power, while entrants that combine material science expertise with strong service and compliance capabilities have a more viable path. The overall trend points to a market where differentiation increasingly rests on process support, reliability, and the ability to co-develop with customers rather than on price alone.
4. Future Trends and Commercial Implications
Trend One: Precision-Driven Formulation and Application-Specific Solutions
Over the next three to five years, slurry development is expected to tilt further toward application-specific performance, with tighter control over particle size distribution, surface chemistry, and slurry stability. As device complexity grows, fabs will continue to favor suppliers who can deliver formulations tuned to particular film stacks and process windows. Commercial opportunities will accrue to organizations that can shorten development cycles, provide robust technical engagement, and demonstrate consistent results across multiple lots and tool environments.
The associated risk is that over-engineering for one process window can limit flexibility. Suppliers must balance specialization with enough platform modularity to adapt when process recipes change, otherwise they risk stranded development effort and reduced addressable demand.
PW Consulting
Trend Two: Regional Supply Shoring and Service Proximity
Geographic alignment between chemical supply and fabrication hubs is likely to deepen. The move to expand production or support capacity closer to key foundry and memory clusters reflects the value placed on shorter feedback loops, faster problem resolution, and improved supply continuity. For manufacturers, this suggests that regional service capability will weigh more heavily in supplier selection, particularly in areas with dense fab concentrations. For investors, it indicates that asset deployment decisions will increasingly factor in proximity to demand rather than cost-minimal siting alone.
A related uncertainty is the uneven pace of fab expansion across regions and the possibility that capacity builds could be moderated by demand timing or broader macro conditions. Suppliers that plan for flexibility—through staged capacity additions, multi-geography support, and adaptable logistics—will be better positioned if expansion timelines shift.
Trend Three: Cost and Compliance as Strategic Capabilities
Raw material volatility and regulatory requirements are expected to remain central considerations rather than occasional disruptions. The ceria oxide price surge in early 2025 and the continuing alignment of hazardous chemical documentation with GHS and China GB/T 16483 illustrate how input costs and compliance obligations can influence both sourcing strategy and market access. Organizations that build strong supplier relationships, diversify critical inputs, and maintain rigorous safety and documentation practices will be better equipped to preserve margins and sustain customer confidence.
The commercial opportunity lies in turning these constraints into trust signals. A supplier that can reliably demonstrate compliance readiness, transparent sourcing, and predictable quality can differentiate in negotiations and long-term agreements. The risk is that any lapse in documentation, handling, or input continuity can quickly erode that trust, particularly in a market where qualification cycles are long and switching costs are high.
5. Strategic Recommendations for Decision Makers
For Manufacturers and Chemical Suppliers
- Prioritize formulation platforms that support rapid adaptation across oxide, tungsten, polysilicon, and barrier applications, reducing time-to-qualification when fab processes change.
- Invest in regional technical support and, where feasible, production or blending capacity that places operational teams closer to major fab clusters to improve responsiveness and continuity.
- Strengthen compliance and safety documentation processes to meet GHS, China GB/T 16483, and related hazardous chemical management expectations, treating these as market access enablers rather than administrative overhead.
For Investors
- Evaluate suppliers based on their ability to combine material science depth with service proximity, as these attributes increasingly determine customer retention and pricing resilience.
- Monitor raw material exposure and sourcing strategy, particularly for ceria-dependent formulations, and weigh companies that show realistic mitigation plans through dual sourcing, contract structures, or formulation flexibility.
- Consider the differentiation potential of specialized regional players that can offer tailored grades and responsive support, while recognizing the qualification and scale advantages held by established global suppliers.
For Procurement and Fab Operations Teams
- Build supplier qualification criteria that weigh defect performance, selectivity, and process support alongside unit cost, given the long-term impact of slurry behavior on yield and line stability.
- Incorporate compliance readiness and documentation quality into supplier evaluation to reduce the risk of delays or access constraints in regions with stringent hazardous chemical management requirements.
- Maintain visibility into raw material price trends and sourcing concentration to anticipate cost pressure and support more resilient contracting decisions.
The strategic picture in the chemical polishing slurry market points to durable growth underpinned by semiconductor demand, but sustained success will depend on how well participants navigate concentration dynamics, precision requirements, regulatory expectations, and input cost volatility. Detailed segment-level sizing, competitive benchmarking, and tailored scenario analysis can sharpen execution decisions and reduce uncertainty across product, geography, and application choices. For decision makers seeking a fuller view of the data and customized implications for their operating context, the complete PW Consulting research report on the chemical polishing slurry market provides expanded segmentation detail, company-level profiles, and deeper scenario analysis.
For detailed analysis of this topic, please visit the official page: Chemical Polishing Slurry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The LED Glass Market: Strategic Trends and Commercial Opportunities in a High-Growth Segment
Market Landscape and Core Challenges
The LED glass market has transitioned from a niche architectural curiosity to a structurally significant component of modern display and facade systems. Over the historical period from 2020 to 2025, the sector expanded steadily, moving from a base of roughly $163 million to approximately $215 million. This trajectory reflects more than cyclical demand; it signals a foundational shift in how lighting, transparency, and digital content are integrated into built environments. Looking ahead through the forecast period extending to 2032, the market is projected to reach approximately $345 million, supported by a compound annual growth rate of 9.58 percent. The growth profile suggests a segment that is maturing in capability while still expanding in addressable use cases.
Beneath the headline numbers, the market is defined by a relatively fragmented structure. The top three players hold a combined share of roughly 24.6 percent, while the top five account for approximately 26.2 percent. This concentration pattern indicates that leadership is earned through application-specific expertise, integration capability, and regional distribution strength rather than through unchecked scale. For decision-makers, the implication is clear: market share is contested at the edges, and competitive advantage increasingly depends on engineering reliability, certification readiness, and the ability to pair glass solutions with compelling content ecosystems.
Despite the favorable growth outlook, the industry is navigating a set of challenges that will determine which participants capture disproportionate value over the next several years. Two to three structural friction points stand out. First, safety and compliance requirements continue to complicate thin-glass adoption, particularly in the United States, where glazing systems must satisfy rigorous testing protocols such as ANSI Z97.1 for lites used in building applications. This regulatory layer creates a barrier to entry for lightweight, high-transparency solutions and raises the cost of validation for new product lines. Second, the supply chain for raw materials remains sensitive to commodity dynamics, which directly affects unit economics and margin stability. Third, the market is undergoing a qualitative shift in how transparency and display performance are balanced, forcing manufacturers to reconcile aesthetic expectations with technical constraints. These challenges are not merely operational; they shape the pace of adoption, the viability of new form factors, and the strategic positioning of leading firms.
LED Lighting Market
Key Growth Drivers: Technology, Policy, Demand, and Cost Structure
The expansion of LED glass is being propelled by a convergence of forces that reinforce one another. Understanding these drivers is essential because they define where investment, product development, and commercial partnerships are likely to yield the highest returns.
Technology innovation remains the most visible catalyst. The integration of high-resolution LEDs directly into architectural-grade safety glass has progressed from experimental prototypes to commercially viable configurations, including laminated, surface-applied, and ceiling-hung solutions. This evolution is not just about embedding light sources; it is about engineering transparent digital displays that maintain clarity, durability, and visual fidelity in real-world environments. Recent industry activity underscores this shift. In early 2026, Ganglustr, a transparent glass LED specialist, published a piece highlighting switchable glass innovations and positioned transparent LED glass as a defining trend for modern retail and commercial facades. The emphasis on facade applications reflects a broader move toward using glass not only as a display surface but as a dynamic architectural element that communicates brand identity and adapts to context. Meanwhile, multi-year partnerships are emerging that extend LED glass beyond traditional screen installations. A notable example is the collaboration between the Big 12 Conference and ASB GlassFloor, which designated LED glass floors as official tournament courts for men’s and women’s basketball events. This move validates the durability and performance requirements of LED glass in high-traffic, high-visibility settings and signals a pathway for sports and entertainment venues to become early adopters of specialized glass-based surfaces.
Policy and regulatory environments are shaping adoption curves in both constraining and enabling ways. On one hand, safety glazing certification remains a practical hurdle. The need to demonstrate compliance with recognized testing standards introduces time and cost into product development, particularly for thin glass formats that must still meet structural and safety expectations. On the other hand, standardization efforts are beginning to reduce friction. The global harmonization of smart glass standards and the refinement of thin-film specifications for building applications are creating a more predictable compliance landscape. When standards converge across regions, manufacturers can scale with greater confidence, and specifiers can evaluate solutions against consistent criteria. Over time, this should lower the barrier to wider deployment and improve the comparability of competing offerings.
Demand-side behavior is changing as well. Commercial building owners, retailers, and event operators are increasingly seeking surfaces that do more than enclose or illuminate a space; they want architecture that communicates, adapts, and engages. Transparent LED glass meets this expectation by allowing displays to coexist with daylight, views, and spatial openness. In retail and commercial facades, the value proposition extends beyond signage: it encompasses brand presence, wayfinding, and the ability to refresh content without replacing physical infrastructure. In decorative contexts, the appeal lies in the combination of lighting quality and transparency, enabling designers to create immersive interior environments that feel both modern and integrated. The demand pattern is therefore not limited to a single application; it spans decorative, informational, and experiential uses, each with its own performance requirements and procurement rhythms.
Cost structure and supply chain dynamics also play a decisive role. The raw material environment has shown meaningful movement. Soda ash prices declined during 2025 due to oversupply and softer demand from key industries, and by mid-2026 the commodity was trading flat with declines measured over both the month and the year. For LED glass producers, commodity movements matter because they influence input costs, pricing flexibility, and the economics of scaling production. When material costs ease, there is more room to invest in process improvements, certification, and application development. Conversely, sustained volatility can compress margins and sharpen the focus on yield, material efficiency, and supplier relationships. The current environment suggests a favorable but not guaranteed window for cost optimization, making disciplined sourcing and transparent cost modeling important strategic priorities.
Competitive Landscape and Leadership Strategies
The competitive map in LED glass is shaped by firms that have chosen distinct paths to differentiation. Rather than competing solely on price, leading participants are building advantage through configuration expertise, application focus, and the ability to deliver transparent digital displays that perform reliably in architectural settings.
Clear Motion Glass, based in York, Pennsylvania, has positioned itself around cvLED transparent LED glass solutions that integrate high-resolution LEDs directly into architectural-grade safety glass. Its portfolio spans laminated, surface-applied, and ceiling-hung configurations, which indicates a strategy centered on flexibility of installation and adaptability to different project constraints. By emphasizing transparent digital displays that maintain architectural integrity, the company addresses a core specifier concern: how to introduce digital content without sacrificing the visual and structural qualities of glass. This approach suggests a focus on integration quality, safety compliance, and the ability to work within existing building systems rather than requiring wholesale redesigns.
Glasstronn, headquartered in Bangalore, India, has built its identity around transparent glass LED solutions that combine glass with LED technology for vibrant, ultra-transparent digital displays. Its emphasis on retail, commercial, and architectural applications points to a strategy oriented toward high-visibility environments where display quality and transparency are equally important. By focusing on the intersection of aesthetics and performance, the company aligns itself with the growing demand for facades and interior surfaces that serve both functional and brand-communication roles. The publication of industry-facing content on switchable glass innovations further signals a commitment to thought leadership and to shaping specifier expectations around transparent LED glass as a mainstream architectural choice.
The market structure suggests a landscape that is neither fully consolidated nor purely fragmented. With the top three and top five players holding modest combined shares, there is room for specialization, regional expansion, and application-led growth. At the same time, the presence of recognizable players with clear configuration strategies indicates that differentiation is achievable through engineering depth and application expertise. The evolution of the competitive field is likely to follow one of two complementary paths. First, integration and partnership models may become more important as LED glass moves into complex environments such as sports venues, retail facades, and decorative interiors. In these settings, success depends not only on the glass itself but on the ability to coordinate with media networks, installation teams, and building systems. Second, new entrants may target specific niches where transparency, form factor, or cost profiles create openings that broader players do not fully address. The result could be a market that remains diverse at the product level while consolidating around a smaller set of trusted integration partners in high-value applications.
For buyers and competitors alike, the strategic lesson is that leadership is increasingly defined by reliability in real-world deployments, the ability to navigate safety and certification requirements, and the capacity to pair hardware with content and installation expertise. Price competition exists, but it is unlikely to be the primary separator over the forecast horizon. Instead, the firms that stand out will be those that can demonstrate repeatable performance across configurations, maintain compliance readiness, and align their product roadmaps with where demand is moving, particularly in facade, decorative, and specialized venue applications.
Future Trends and Commercial Implications (2026–2032)
Looking forward, several trends are likely to shape the LED glass market over the next three to five years. These trends are not abstract; they carry direct implications for product strategy, partnership choices, and investment timing.
One important trend is the deeper integration of LED glass into architectural and venue systems as a standard option rather than a special-occasion solution. The extension of LED glass into tournament courts and the growing attention to retail and commercial facades indicate that the technology is moving toward repeatable deployment models. As more projects demonstrate durability and maintenance feasibility, specifiers will become more comfortable specifying transparent LED glass in new builds and retrofits. The commercial opportunity here lies in building application-ready portfolios that address installation logistics, content integration, and post-installation support, rather than selling glass as a standalone component.
A second trend is the continued push toward thinner, more transparent, and more seamlessly integrated forms. Standardization activity and certification pathways are gradually reducing uncertainty, which should encourage experimentation with lighter configurations and new integration methods. Thinner glass can improve aesthetics and reduce perceived visual weight, but it must still satisfy safety expectations and performance requirements. The firms that can balance these priorities through material science, lamination expertise, and testing discipline will be well positioned to capture demand from designers and architects who want digital functionality without compromising spatial quality. The risk is that thin-glass adoption may progress unevenly across regions, especially where safety glazing certification remains a practical hurdle.
A third trend is cost and supply chain normalization influencing product economics and pricing strategies. Commodity movements in inputs such as soda ash have the potential to improve unit economics when they move favorably, and the recent easing in prices has created a more supportive backdrop. However, commodity markets are cyclical, and reliance on temporary cost relief can be risky. The more durable advantage will come from process efficiency, yield improvement, and supplier diversification. Companies that treat cost structure as a strategic variable, rather than a passive outcome, will be better equipped to maintain margins through market cycles and to invest in the application development that drives long-term growth.
These trends connect to tangible commercial opportunities. For product developers, the opportunity is to build configurable platforms that can be adapted across decorative, facade, and venue applications without compromising safety or transparency. For integration and systems players, the opportunity is to offer end-to-end solutions that reduce specification risk and accelerate project timelines. For investors, the opportunity lies in identifying participants with credible certification readiness, application traction, and disciplined cost management, rather than those relying on short-term commodity tailwinds. The principal risks include regulatory variability across jurisdictions, the possibility that thin-glass adoption slows if certification costs remain high, and exposure to raw material volatility that could compress margins if not managed proactively.
Actionable Guidance for Decision-Makers
The strategic choices facing manufacturers, investors, and buyers are distinct, but they share a common need: clarity on where value is being created and where risk is concentrated. The following guidance is intended to support decision-making in the near term while keeping longer-term positioning in view.
PW Consulting
For manufacturers and product developers, the priority is to align product roadmaps with the applications that are demonstrating the strongest momentum while maintaining rigorous attention to safety, transparency, and installation practicality. Building a portfolio that spans laminated, surface-applied, and ceiling-hung configurations can broaden market access, but differentiation will come from proving repeatable performance in the environments that matter most to specifiers. It is equally important to treat certification and compliance not as a final hurdle but as a design constraint from the outset. Early alignment with recognized testing requirements reduces rework, shortens time to market, and strengthens credibility with building professionals. Finally, disciplined sourcing and cost modeling should be treated as core capabilities, not administrative functions, so that material cost fluctuations do not derail margin plans or investment in application development.
For investors and strategic partners, due diligence should focus on evidence of application traction, integration capability, and regulatory readiness rather than on headline technology claims alone. The market’s moderate concentration suggests that value can be captured by participants with clear differentiation, but it also means that not every player is positioned for sustained advantage. Evaluating a company’s ability to navigate safety glazing requirements, its track record in real-world installations, and its relationships with content, installation, and building-system partners can provide a more reliable view of durability than product narratives in isolation. Timing matters as well: the current environment offers a window in which cost structures are relatively supportive, but that window is not permanent, so investment theses should account for both near-term economics and the longer trajectory of standardization and adoption.
For buyers and procurement teams, the emphasis should be on reducing total project risk rather than minimizing unit price. Transparent LED glass is most valuable when it is specified as part of a coherent system that includes content strategy, installation planning, and maintenance considerations. Evaluating suppliers on configuration flexibility, compliance documentation, and post-installation support can prevent costly mismatches between expectation and performance. It is also prudent to assess how a supplier handles variability across regions and applications, since the same glass solution may face different certification expectations and performance demands depending on whether it is used in an interior decorative setting, a commercial facade, or a high-traffic venue. Procurement decisions that account for lifecycle cost and specification confidence are more likely to deliver durable value than those focused narrowly on initial price.
Optical Glass Market
Across all of these perspectives, the recurring theme is that detailed, current intelligence is a strategic asset. Market structure, regulatory dynamics, raw material conditions, and application momentum are all evolving, and the companies that act on the most accurate picture of these changes are best positioned to allocate capital, prioritize product development, and negotiate from strength. A complete, segmented view of the market—covering regional patterns, type and application splits, competitive positioning, and forward indicators—can sharpen these decisions and reduce the uncertainty that comes from relying on partial information. For those seeking a deeper dive with granular segmentation and tailored scenarios, the broader research resource that supports this analysis provides a more detailed foundation for planning and execution.
For detailed analysis of this topic, please visit the official page: LED Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com