

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
FT Wax Market 2026: Why a 6.2% CAGR Reshapes Industry Competition Through 2032

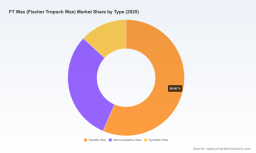
The Fischer-Tropsch Wax Market: Strategic Trends and Commercial Opportunities Through 2032
The Fischer-Tropsch wax market has entered a phase of structural maturation, driven by a convergence of sustainability mandates, feedstock advantage, and application-specific performance requirements. Valued at approximately USD 920.0 million in 2025, the market is projected to expand to USD 1,409.8 million by 2032, reflecting a compound annual growth rate of 6.2 percent. This trajectory signals more than steady expansion; it indicates a market shifting from commodity substitution toward engineered performance materials. For executives, strategic planners, and investors, the window for positioning around FT wax is narrowing as supply chains reorganize, regulatory pressure intensifies, and downstream formulators demand verifiable sustainability credentials alongside technical superiority.
Market Landscape and Structural Challenges
The FT wax segment occupies a distinct niche within the broader hydrocarbon and specialty wax ecosystem. Unlike traditional paraffin or fully synthetic alternatives, FT waxes benefit from a gas-to-liquid synthesis route that yields tightly controlled molecular weight distributions, low impurity profiles, and customizable crystal structures. These characteristics have enabled FT waxes to penetrate performance-sensitive applications where consistency, hardness, and thermal behavior are non-negotiable. The market's size and growth path reflect this positioning, with demand accumulating steadily across multiple industrial and consumer-facing categories.
Microcrystalline Wax Market
Despite the favorable growth backdrop, three structural challenges are reshaping how participants compete and how end-users evaluate supply options.
First, feedstock geography and supply chain concentration create inherent vulnerability. Production capacity remains clustered in regions with proximate natural gas availability and established GTL infrastructure, including North America, Southern Africa, and parts of East Asia. While this concentration reflects the underlying chemistry and economics of FT synthesis, it also introduces logistics friction. Customers located far from production hubs face elevated freight exposure and lead-time variability, which can compress margins and complicate just-in-time formulations. Strategic sourcing now requires balancing technical grade availability with geographic risk, a consideration that was secondary when wax was treated as a low-cost inert additive.
Second, regulatory and sustainability expectations are redefining procurement criteria. Coatings, packaging, adhesives, and personal care formulators are under mounting pressure to reduce volatile organic compound emissions, improve product carbon footprints, and demonstrate responsible sourcing. FT waxes offer a structurally cleaner profile relative to some conventional routes, particularly when produced via natural gas-based GTL pathways. However, market adoption now hinges on documented lifecycle advantages, grade-level consistency, and the ability to integrate into low-VOC or solvent-reduced systems without sacrificing performance. Specifications that once emphasized melting point and hardness are increasingly paired with carbon intensity, traceability, and regulatory compliance documentation.
PW Consulting
Third, the market is navigating a differentiation dilemma across wax categories. FT-derived waxes span hard paraffin-like grades, microcrystalline variants, and oxidized or micronized specialty formats, each optimized for distinct end-use behaviors. At the same time, customers increasingly seek hybrid solutions that combine FT performance with cost-effective processing and compatibility with existing production lines. Suppliers that can articulate a clear grade-to-application mapping and provide formulation support are gaining advantage, while undifferentiated product listings struggle to justify premium positioning.
Key Demand Drivers
Technology Innovation and Grade Engineering
Technological progress in FT wax production is shifting the conversation from availability to precision. Advances in catalyst selectivity, fractionation control, and particle engineering have expanded the range of achievable hardness, melt behavior, and dispersion characteristics. Micronized and oxidized grades now enable formulators to fine-tune abrasion resistance, slip properties, and compatibility with polymer matrices, paints, and hot-melt systems. The availability of grades designed for spray application, low dust handling, or enhanced dispersion reduces the integration burden for downstream manufacturers and unlocks use cases where conventional waxes previously underperformed.
This trajectory matters for commercial strategy because it changes the value proposition. FT wax is no longer competing solely on price-per-ton; it is competing on total formulation efficiency, process reliability, and end-product performance. Companies that align their portfolio development with application-driven grade engineering are better positioned to capture premium segments and defend margins as volume growth accelerates.
Policy and Regulatory Tailwinds
Environmental regulation and corporate sustainability targets are accelerating substitution toward FT waxes in multiple application streams. VOC reduction mandates, packaging recyclability expectations, and coatings durability requirements are pushing formulators to seek alternatives that maintain technical performance while improving environmental profiles. In several markets, FT waxes are gaining traction as drops-in or near-drops-in solutions that support lower-emission formulations and cleaner processing conditions.
The commercial implication is twofold. First, regulatory momentum creates a durable demand pull that is less sensitive to short-term economic cycles than discretionary industrial spending. Second, it raises the bar for supplier credibility. Customers increasingly require evidence of consistent grade quality, supported sustainability claims, and the ability to navigate evolving compliance frameworks across regions. Suppliers that can deliver transparent documentation and stable specification control are better placed to convert regulatory tailwinds into long-term contracts.
Demand-Side Shifts in Coatings, Cosmetics, and Packaging
End-use behavior is changing in ways that favor FT wax's performance envelope. In coatings and related surface treatment applications, the push for durability, scratch resistance, and controlled surface appearance supports continued demand for waxes that deliver predictable hardness and dispersion. In cosmetics and personal care, formulation precision, purity, and sensory consistency are paramount, creating demand for high-purity grades with tightly controlled melting and rheological behavior. Packaging adhesives and polymer processing also benefit from FT wax's ability to improve tack control, slip, and compatibility in complex formulations.
These demand shifts are not uniform. Growth is strongest where FT wax solves a specific technical bottleneck rather than serving as a generic filler or processing aid. This observation is critical for commercial planning: the highest-value opportunities are concentrated in applications where FT wax enables formulation simplification, performance enhancement, or compliance improvement that would otherwise require more expensive or complex alternatives.
Supply-Side and Cost Structure Dynamics
The economics of FT wax synthesis remain tied to feedstock availability and GTL capacity utilization. Natural gas continues to be the dominant feedstock base, supporting a production route with comparatively low sulfur content and favorable impurity control relative to coal-based alternatives. This structural advantage reinforces FT wax's positioning in applications where cleanliness and consistency matter. At the same time, capital intensity and regional capacity distribution constrain how quickly supply can respond to localized demand surges.
Cost structure dynamics are increasingly shaped by logistics and grade specialization rather than raw feedstock price alone. Even when base feedstock economics are stable, transportation exposure and specialized handling requirements can influence delivered cost and customer economics. Participants that invest in regional supply optimization, packaging efficiency, and application support can mitigate these pressures and create a more defensible cost-to-serve profile.
Competitive Landscape and Leading Strategies
The FT wax market features a mix of global integrated producers, specialty refiners, and regionally focused manufacturers, each pursuing distinct competitive positions. The landscape is characterized by concentrated expertise in GTL-based synthesis, differentiated grade portfolios, and varying degrees of application-level support.
Sasol operates as a global reference point in GTL-derived FT wax, offering a broad range of hard, medium, micronized, and oxidized grades for coatings, inks, adhesives, polishes, and polymer additives. Its scale and integrated chemistry capability give it a strong foundation for consistent supply and portfolio breadth. Recent product activity underscores a strategy of linking grade innovation with sustainability differentiation. In mid-2024, the company introduced a new industrial wax grade for packaging adhesives designed with a materially lower cradle-to-gate carbon footprint compared with conventional alternatives. It subsequently expanded its micronized FT wax portfolio with spray-oriented grades, signaling an emphasis on application convenience, dispersion performance, and handling efficiency. This dual focus on performance and carbon intensity reflects a broader industry shift: leading players are increasingly competing on documented sustainability outcomes as well as technical grade capability.
Shell maintains a position rooted in GTL-derived materials integrated into base oils and specialty product streams, with FT wax functionality extending into additives and sustainable aviation fuel feedstock pathways. Its strategic relevance lies in the interplay between FT chemistry and broader energy transition portfolios. By connecting wax production to larger hydrocarbon and low-carbon fuel initiatives, Shell can leverage feedstock flexibility and process integration, though the wax-specific commercial strategy is shaped by how it prioritizes specialty product development versus broader energy investments.
Deurex AG competes as a specialist in micronized and oxidized FT waxes, emphasizing high hardness, abrasion resistance, and controlled particle size. Its product logic targets applications where mechanical performance and precise dispersion are decisive. This specialization enables a focused value proposition but also demands deep application expertise and close customer collaboration to justify premium positioning.
Evonik Industries AG brings FT wax capabilities into formulations for PVC lubricants, printing inks, coatings, and hot-melt systems. Its approach illustrates how FT wax can be embedded within broader specialty chemical portfolios, where wax performance is paired with formulation knowledge and downstream compatibility support. The competitive edge here is less about volume scale and more about application integration and technical service.
Nippon Seiro Co., Ltd. focuses on refining FT waxes through specialized synthesis routes to deliver high-purity, high-melting-point grades with low impurity levels, particularly relevant for cosmetics and industrial uses. In markets where purity and consistency directly affect end-product acceptance, this refined-grade positioning can command strong customer loyalty and create barriers tied to qualification and specification approval.
In China, multiple manufacturers have expanded FT paraffin and oxidized wax offerings for polymer processing, coatings, masterbatches, and filler dispersion. King Honor International, Tianshi Group, Jiangsu Faer Wax Industry Co., Ltd., and similar players reflect the region's growing capacity to serve both domestic demand and export channels. Their strategies often combine scale, grade variety, and cost competitiveness, while increasingly needing to address quality consistency and sustainability documentation as export and premium-segment requirements intensify. Paramelt operates with a sourcing and supply investment model, building global capacity access for mineral hydrocarbon and synthetic wax applications. Its positioning highlights a different route to market: rather than owning every step of FT synthesis, it focuses on distribution reach, supply reliability, and application connectivity.
The competitive evolution is moving along two parallel tracks. On one hand, scale players continue to strengthen portfolio breadth and sustainable grade development, leveraging integrated feedstock and process advantages. On the other, specialists and regional manufacturers are carving out niches through particle engineering, purity control, application-specific grades, and cost-driven flexibility. Consolidation is plausible where scale, feedstock access, and sustainability credentials matter most, while fragmentation may persist in highly application-specific segments where customer qualification cycles and technical service create local moats. New entrants will likely face steep barriers in GTL-based FT wax due to process complexity and qualification requirements, but differentiated refining, micronization, or regional distribution models can still create entry points.
Forward-Looking Trends
Sustainability-Embedded Grade Design as a Baseline Expectation
Over the next three to five years, sustainability performance is expected to become a standard component of FT wax purchasing decisions rather than a differentiating bonus. Customers in coatings, packaging, and cosmetics will increasingly require grades that support lower-carbon formulations, cleaner processing, and documented environmental claims. This trend creates commercial opportunities for suppliers that invest early in lifecycle transparency, grade-level carbon differentiation, and regulatory-ready documentation. It also introduces risk for participants that treat sustainability as a communications exercise rather than an integrated product development priority.
Application-Driven Specialization and Formulation Integration
Growth is likely to concentrate where FT wax enables measurable formulation gains. Micronized dispersion, spray-ready handling, oxidation control, and compatibility with polymer and coating systems will remain decisive in capturing premium demand. Companies that pair grade development with formulation guidance, trial support, and process integration advice will be better positioned to secure long-term relationships and reduce price sensitivity. The risk here is overgeneralization: portfolios that expand without clear application logic may dilute focus and weaken commercial positioning.
Supply Chain Reconfiguration and Regional Sourcing
Geographic concentration will continue to influence sourcing strategy. As customers seek to reduce logistics exposure and improve supply resilience, regional partnerships, localized inventory models, and grade availability in closer proximity to demand centers will become more valuable. This trend opens opportunities for producers and distributors that can offer reliable regional supply, flexible packaging, and responsive technical support. The uncertainty lies in how rapidly new capacity can be economically justified and how demand patterns evolve across regions with different regulatory and cost environments.
Strategic Actions for Decision-Makers
For manufacturers and formulators, the priority is to align FT wax adoption with application economics rather than treating wax selection as a generic commodity decision. Evaluate grades against total formulation impact, including dispersion behavior, processing reliability, VOC-compatible performance, and sustainability documentation. Where FT wax can simplify a formulation, improve end-product quality, or support compliance goals, the value case often extends beyond unit price. Build qualification pathways early for grades that meet both technical and sustainability criteria, and develop internal benchmarks that compare FT wax not only with conventional waxes but also with alternative additives that may appear cheaper on paper yet incur higher processing or performance costs.
For investors, the attractive exposure is in companies that combine process capability with application-level differentiation and credible sustainability positioning. Scale alone is not sufficient; the most resilient business cases are emerging where feedstock advantage, grade engineering, and customer support reinforce one another. Pay attention to how producers are expanding into lower-carbon grades, micronized and oxidized specialties, and regional supply improvements, as these signals indicate where future margin and retention may come from. Also monitor logistics exposure and capacity location, since geographic concentration can create both cost risk and opportunity for suppliers that address proximity and reliability needs.
Car Wax Market
For procurement and sourcing leaders, the strategic task is to reduce vulnerability without sacrificing performance. Diversify grade sources where possible, prioritize suppliers with consistent specification control and transparent documentation, and evaluate total delivered cost rather than ex-works price alone. Where application sensitivity is high, consider longer-term supply agreements that secure grade availability and technical support, especially for specialized micronized or oxidized formats. In parallel, use FT wax adoption as a lever to support internal sustainability targets, provided the selected grades can substantiate the claimed advantages and integrate cleanly into existing processes.
The FT wax market is entering a period in which technical performance, supply reliability, and sustainability evidence must be evaluated together. The most consequential decisions will be made by organizations that can distinguish between generic wax purchasing and application-specific value creation. For executives and strategic teams seeking deeper segmentation data, grade-level demand mapping, regional supply assessments, and customized scenario analysis, a detailed commercial research report can provide the granularity needed to translate these market-wide trends into precise sourcing, investment, and product development choices.
For detailed analysis of this topic, please visit the official page: FT Wax (Fischer Tropsch Wax) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com