

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Triazine Market CAGR of 6.46%: Real Drivers Behind the $995 Million Growth by 2032

Navigating the Triazine Market: Strategic Trends and Commercial Opportunities Through 2032
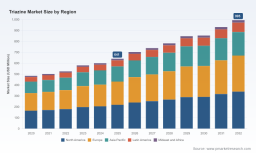
The triazine market has entered a phase of steady, structurally supported expansion. Valued at approximately 641.0 million USD in 2025, the sector is projected to reach 995.0 million USD by 2032, reflecting a compound annual growth rate of 6.46 percent across the 2026–2032 forecast window. This trajectory is anchored in consistent historical momentum, with revenues climbing from 484.2 million USD in 2020 through incremental annual gains that accelerated noticeably after 2022. The growth profile is not merely a function of volume expansion; it signals a market undergoing structural recalibration, where application diversification, regulatory navigation, and supply chain discipline are reshaping competitive advantage.
For executives and capital allocators, the central question is no longer whether triazine-derived products will continue to grow, but how value will be captured amid tightening environmental scrutiny, feedstock volatility, and shifting end-user expectations. The market’s evolution demands a clear view of the forces currently dictating margin profiles, capacity allocation, and strategic positioning.
Market Snapshot and Structural Headwinds
The triazine landscape in 2025 is defined by a mature yet still expanding revenue base, with growth increasingly concentrated in high-value applications and regions demonstrating strong agricultural productivity or industrial demand. The compound annual growth rate of 6.46 percent underscores a market that is outpacing broader chemical sector averages, yet this expansion is not uniformly distributed across all segments. Pricing dynamics, regulatory compliance costs, and regional feedstock availability are creating a bifurcated environment where well-positioned players capture disproportionate value while others face margin compression.
A first critical challenge lies in regulatory persistence and environmental scrutiny. Triazine-class herbicides have long operated under strict monitoring frameworks, and the continued enforcement of legacy agreements means that compliance is not a periodic hurdle but a permanent operational overhead. Companies that treat regulatory engagement as a reactive exercise increasingly find themselves constrained in formulation flexibility, geographic expansion, and product lifecycle management. The second challenge is supply chain fragility tied to feedstock and intermediate pricing. Fluctuations in melamine, cyanuric acid, and cyanuric chloride markets directly compress or expand manufacturing margins, and recent price behavior in these inputs has introduced greater unpredictability into cost planning. The third challenge is the tension between volume growth and formulation sustainability. End-users in agriculture are demanding higher efficacy with lower environmental residue, while industrial buyers seek reliable performance in gas treatment and water management applications. Balancing these expectations without compromising cost structure requires capabilities that many mid-tier producers have not yet fully developed.
These headwinds are not insurmountable barriers; rather, they function as filters that reward operational discipline, regulatory fluency, and application-specific innovation. The market is gradually rewarding players who can integrate compliance, cost control, and differentiated performance into a single strategic narrative.
Core Drivers Shaping Market Trajectory
Technological Innovation and Formulation Precision
Innovation in triazine chemistry is increasingly oriented toward precision, selectivity, and application efficiency rather than broad commodity volume. Recent developments illustrate this shift clearly. In late 2025, a major industry participant launched a new line of triazine-based herbicides explicitly engineered for precision agriculture, reflecting a broader move toward formulations that align with variable-rate application, crop-specific tolerance profiles, and reduced off-target exposure. Simultaneously, research expansions in Brazil have focused on tailoring triazine herbicides to local crop varieties, highlighting how regional agronomic conditions are driving customized product development rather than one-size-fits-all offerings.
Beyond agriculture, technological progress in triazine-based H2S scavenging and desulfurization is expanding the industrial application envelope. Capacity expansions for triazine-based scavengers in 2025 demonstrate how oil and gas operators are increasingly relying on tailored chemistries to manage sulfur challenges in production streams. The release of updated product catalogs offering MEA triazine grades in concentrated ranges further indicates that suppliers are refining performance consistency and handling characteristics to meet demanding industrial specifications. For manufacturers, the strategic implication is clear: incremental formulation improvements, application-specific packaging, and performance reliability are becoming more valuable than pure volume scaling.
Policy and Regulatory Environment as a Strategic Variable
Regulatory frameworks continue to shape market behavior more than any single pricing or demand variable. Ongoing monitoring programs for triazine herbicides remain in force under longstanding reregistration eligibility decisions and associated memoranda of agreement, meaning compliance documentation, environmental monitoring, and residue management are integral to market access rather than optional enhancements. This regulatory continuity creates a high barrier for informal or under-resourced market entry, consolidating advantage for companies with established compliance infrastructure and transparent reporting practices.
Mma Triazine H2S Scavengers Market
At the same time, broader trade and export dynamics are influencing input availability and cost structures. Export controls on certain medium and heavy rare earth items introduced in 2025 illustrate how regulatory actions in adjacent material categories can cascade into chemical supply planning, particularly for producers dependent on complex intermediate streams or specialized processing routes. While triazine manufacturing does not directly rely on rare earths, the broader message is that policy volatility is becoming a structural feature of chemical markets. Firms that proactively map regulatory exposure across jurisdictions, maintain flexibility in sourcing, and invest in compliance-ahead product design are better positioned to avoid disruption and protect margin integrity.
Demand-Side Shifts in Agriculture and Industrial Use
Demand patterns are shifting on both the agricultural and industrial fronts, though for different reasons. In agriculture, the continued emphasis on corn and sugarcane cultivation sustains core demand for triazine herbicides, but the nature of that demand is becoming more performance-driven. Growers and agronomic advisors are prioritizing weed control solutions that integrate with precision application technologies, offer consistent efficacy under variable field conditions, and align with resistance management strategies. This shift is encouraging suppliers to emphasize formulation reliability, crop-specific compatibility, and supportive technical service rather than competing solely on price.
On the industrial side, demand for triazine-based solutions in gas treatment, desulfurization, and water management is gaining traction as operational environments become more complex. Production chemicals portfolios are increasingly integrating triazine H2S scavengers as operators seek reliable methods to manage sulfur-related challenges in extraction and processing. This diversification of end-use is important because it reduces overreliance on a single agricultural cycle and creates demand streams that are less seasonal and more tied to ongoing industrial operational requirements. For commercial strategists, the opportunity lies in recognizing that triazine demand is expanding beyond traditional herbicide channels into specialized industrial applications where performance consistency and technical support command premium positioning.
PW Consulting
Supply Chain and Cost Structure Realignment
Cost dynamics are being reshaped by feedstock behavior and production geography. Melamine pricing in Asia weakened in 2025 amid resumed production capacity, creating a narrow price range that alters input cost expectations for downstream triazine producers. In parallel, cyanuric acid prices rose during the third quarter of 2025 as higher urea feedstock costs and elevated energy expenses flowed through the value chain. Cyanuric chloride prices, by contrast, held relatively stable in late 2024 on balanced supply and steady chlorine costs. This mixed input environment means that cost leadership is no longer solely about scale; it is increasingly about feedstock agility, regional sourcing optimization, and the ability to pass through or absorb cost variation without sacrificing customer relationships.
Producers that maintain diversified input channels, invest in process efficiency, and align capacity with demand hotspots are better equipped to navigate these fluctuations. The market is also seeing renewed attention to regional production footprints, as exemplified by research and capacity investments in key agricultural markets. This suggests that supply chain resilience and local relevance are becoming competitive differentiators alongside traditional cost metrics.
Competitive Landscape and Strategic Positioning
The triazine market features a concentrated group of leading participants alongside a broader base of registered producers and specialty suppliers. Concentration metrics indicate that a relatively small number of firms command a substantial share of revenue, while the remainder compete through regional focus, formulation specialization, or application-specific niches. This structure creates a market where scale, brand trust, regulatory compliance, and technical service all contribute to durable positioning.
Large multinational players maintain advantage through integrated portfolios, global distribution networks, and the ability to invest in formulation research across multiple crop systems and industrial uses. Their strategic positioning typically centers on offering triazine-class herbicides and derivatives with consistent quality, broad geographic reach, and application support that spans agricultural and industrial channels. In the agricultural segment, some of these participants are particularly strong in corn and sorghum weed control, while others emphasize triazine-tolerant formulations and mixed-herbicide approaches that address resistance management and broader crop compatibility.
Triacetin Market
Specialized and regional players are carving out distinct roles by focusing on local crop varieties, precision agriculture alignment, and industrial application expertise. Capacity investments in triazine-based H2S scavengers, updated product grade offerings, and region-specific research expansions all point to a landscape where differentiation is increasingly tied to application performance rather than commodity availability. For industrial applications, suppliers that can deliver reliable scavenging performance, handle concentrated grades consistently, and integrate with production chemicals portfolios are gaining relevance as operators look for dependable chemical solutions in demanding environments.
Market evolution is shaped by both consolidation and fragmentation tendencies. On one side, larger players continue to strengthen their positions through portfolio breadth, global reach, and selective investments in research and capacity. On the other side, new and mid-tier entrants are finding opportunities in specialized formulations, regional crop customization, and industrial niche applications where agility and technical service can offset scale disadvantages. Acquisition activity in adjacent production chemicals and digital technology segments further signals that companies are seeking to broaden their capabilities beyond single-product offerings, integrating chemistry, application know-how, and service delivery into more comprehensive value propositions.
The competitive implication for decision-makers is that market share alone does not guarantee resilience. Firms that can combine regulatory readiness, feedstock cost discipline, application-specific innovation, and strong technical support are better positioned to defend margins and expand into higher-value channels. The landscape is gradually shifting from pure product availability toward solution-oriented positioning, where performance consistency and channel expertise matter as much as volume.
Forward View: Trends and Commercial Implications for 2026–2032
Precision-Oriented Formulation and Application Integration
Over the next three to five years, one of the most consequential trends will be the continued move toward precision-oriented triazine formulations and their integration with application technologies. As precision agriculture expands and growers demand more targeted weed control with reduced environmental exposure, suppliers that can deliver crop-specific, site-adaptive, and performance-consistent products will capture disproportionate demand. This trend creates commercial opportunities for manufacturers to strengthen technical service, develop regional formulation variants, and align product portfolios with variable-rate and data-driven application practices. It also introduces the risk that companies unable to support precision application requirements may face gradual erosion in relevance, particularly in higher-value crop systems.
Industrial Demand Diversification as a Stabilization Channel
A second trend is the gradual diversification of triazine demand beyond traditional herbicide channels into industrial applications such as gas treatment, desulfurization, and water management. This shift is likely to provide a stabilizing effect on demand profiles by reducing sensitivity to any single agricultural cycle or regional crop outcome. Commercial opportunities here include expanding production chemicals portfolios, improving grade consistency for scavenger applications, and building application support capabilities that address operational reliability in oil, gas, and industrial water contexts. The associated risk is that industrial demand can be cyclical and closely tied to capital expenditure patterns in energy and processing sectors, meaning suppliers must manage capacity and inventory with a clear view of end-user investment cycles.
Regulatory Continuity and Input Cost Volatility as Persistent Variables
The third trend is the likelihood that regulatory oversight and input cost variability will remain central strategic variables rather than transient disruptions. Continued monitoring requirements for triazine herbicides and broader policy actions affecting chemical trade and material availability will require ongoing compliance investment and supply chain flexibility. At the same time, feedstock and energy cost fluctuations will continue to influence margin outcomes. The commercial opportunity lies in building operational models that treat compliance and cost agility as core capabilities, enabling faster response to regulatory updates and input price shifts. The risk is that firms with rigid sourcing, limited compliance infrastructure, or weak regional adaptability may experience recurring margin pressure and market access constraints.
Strategic Actions for Decision-Makers
For manufacturers and product leaders, the priority is to align formulation development and capacity planning with the market’s precision and application-diversification trajectory. This means investing in crop-specific and region-specific formulations, strengthening technical service around precision application and resistance management, and ensuring that industrial-grade triazine products meet the consistency and handling expectations of gas and water treatment operators. It also means building feedstock flexibility and process efficiency to absorb input cost variability without eroding competitive positioning. Companies that can demonstrate reliable performance, regulatory readiness, and application support will be better placed to defend share and expand into higher-margin channels.
For investors and capital allocators, the market’s growth profile offers attractive exposure, but returns will increasingly depend on which participants can convert scale into differentiated value. Due diligence should focus on regulatory compliance infrastructure, feedstock cost management, regional demand alignment, and the ability to serve both agricultural and industrial applications with credible technical support. Attention to recent capacity expansions, research investments, and portfolio integration moves can provide early signals about which companies are building durable advantages versus competing primarily on price. In a market where concentration is meaningful but specialization is gaining value, identifying firms with both scale and application-relevant capabilities is a prudent approach.
For procurement and supply chain leaders, the immediate imperative is to manage input volatility and compliance risk through diversified sourcing and clear performance specifications. Engaging suppliers with transparent monitoring practices, consistent grade quality, and the ability to support regional application requirements can reduce disruption risk and improve operational reliability. In industrial procurement, prioritizing suppliers with proven scavenger performance, reliable delivery, and supportive technical service will help maintain process stability in demanding operating environments. In agricultural procurement, aligning product selection with precision application capabilities and crop-specific needs can improve efficacy outcomes while supporting compliance objectives.
The triazine market is moving from a volume-centric phase into a value-centric phase where precision, compliance, and application diversification define competitive advantage. For organizations seeking deeper segmentation data, regional demand breakdowns, and customized strategic recommendations, a comprehensive research report provides the detailed frameworks needed to translate these trends into actionable planning. Accessing that level of detail enables decision-makers to calibrate capacity, portfolio, and sourcing strategies with greater confidence as the market advances toward 2032.
For detailed analysis of this topic, please visit the official page: Triazine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com