

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
L-Cysteine Market 5.85% CAGR Trajectory: What Asia Pacific and Fermentation Demand Reveal

Strategic Trends and Commercial Opportunities in the L-Cysteine Market: A 2032 Outlook
The global L-Cysteine market has entered a phase of steady expansion, driven by structural shifts in production methods, evolving regulatory frameworks, and sustained demand across multiple end-use sectors. Over the historical period from 2020 to 2025, the market demonstrated resilience amid supply chain volatility and cost pressures, reaching a base valuation that sets the foundation for the forecast window through 2032. With a projected compound annual growth rate of 5.85 percent, the trajectory points toward incremental but meaningful scaling, particularly as fermentation-based production gains share over traditional synthetic routes. For decision-makers operating in amino acid sourcing, formulation, or downstream applications, the market is transitioning from a commodity-adjacent space into a more differentiated, quality-sensitive arena where certification, sustainability positioning, and supply reliability increasingly influence procurement and partnership decisions.
Market Overview and Core Challenges
The revenue scale of the L-Cysteine market reflects consistent upward movement, with total valuation climbing from the low 135 million range in 2020 to approximately 172 million by 2025. The forecast period extends this pattern, projecting sequential gains that push the market toward the mid-250 million range by 2032. Growth is not uniform across geographies or application areas, but the aggregate trajectory underscores a market that is expanding through both volume increases and a gradual shift toward higher-value grades. The moderate level of market concentration, with the top three players accounting for roughly a quarter of share and the top five holding closer to a third, signals a fragmented but competitive landscape where scale, regional presence, and product specialization shape positioning more than outright dominance.
Key Challenges Shaping the Market
Several structural pressures are defining the near-term operating environment for L-Cysteine producers and buyers. First, production economics remain a persistent constraint. Fermentation-based processes, while increasingly preferred for their alignment with cleaner labeling and sustainability expectations, carry higher process complexity and compliance costs. These elevated production expenses continue to act as a restraint, particularly for manufacturers balancing yield optimization, quality control, and regulatory requirements across food, pharmaceutical, and feed grades. Second, regulatory differentiation across end markets creates fragmented compliance burdens. L-Cysteine benefits from recognized food additive status in major markets, including its GRAS designation and permission as an E920 additive under U.S. food regulations for dough strengthening and flavor enhancement. At the same time, pharmaceutical and cell culture applications impose stricter purity, documentation, and traceability expectations. This dual reality means that suppliers must maintain distinct quality systems and certification pathways, which can limit the ability to move inventory fluidly across segments. Third, supply chain stability is increasingly tied to facility capability and certification credibility rather than price alone. Recent investments in certified fermentation capacity signal that buyers are prioritizing auditable food safety systems and consistent quality over short-term cost advantages. This shift places pressure on smaller or less-resourced producers to either upgrade capabilities or risk erosion in procurement preference.
Key Drivers of Market Change
The market’s growth path is being shaped by a combination of technological, regulatory, demand-side, and supply-side forces that interact more strongly than in prior cycles. Rather than a single dominant catalyst, the current environment favors players who can align process innovation with specification reliability and end-market demand patterns.
Technological Innovation and Process Shifts
Fermentation continues to be the defining technical transition in L-Cysteine production. The migration toward bio-based routes is not merely a response to sustainability narratives; it is a practical means of achieving consistent purity, reducing reliance on petrochemical feedstocks, and meeting the increasingly strict documentation expectations of food and pharmaceutical customers. Suppliers investing in fermentation platforms are positioning themselves to serve multiple grades from shared infrastructure, while also differentiating through certification and traceability. Recent product catalog updates and facility expansions highlight how leading producers are embedding food safety and quality management systems directly into fermentation operations, strengthening their ability to supply bakery, food, and animal feed markets with auditable credentials. This process orientation is becoming a competitive asset, especially where buyers need assurance that ingredients meet both performance and regulatory standards.
Policy and Regulatory Environment
Regulatory clarity in key end markets provides a supportive backdrop, but it also raises the bar for compliance execution. Recognition of L-Cysteine as a permitted food additive in the United States, along with its established role as a dough strengthener and flavor enhancer, reinforces demand stability in the food and beverage segment. In parallel, pharmaceutical and healthcare applications demand tighter control over impurity profiles, documentation, and manufacturing consistency. The result is a market where regulatory acceptance is necessary but not sufficient; the practical differentiator is the ability to demonstrate repeatable quality across audits and batches. Suppliers with certified facilities and clearly defined grade portfolios are better placed to navigate this environment, while those without robust quality systems face higher barriers to entry in specification-driven segments.
Demand-Side Evolution
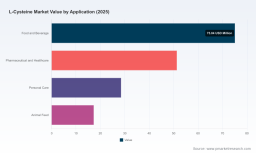
End-user demand is expanding across food, pharmaceutical, personal care, and animal feed applications, but with different growth drivers in each. In food and beverage, the appeal of L-Cysteine lies in functional performance and formulation stability, particularly in bakery and processed food categories where dough handling and shelf-quality considerations matter. In pharmaceutical and healthcare settings, demand is tied to applications requiring high-purity amino acid inputs and specialized derivatives, where consistency and regulatory alignment are central to procurement decisions. Personal care and animal feed applications add further volume potential, though they often emphasize cost efficiency and supply reliability. A notable trend is the increasing preference for plant-based and fermentation-derived inputs in categories where ingredient origin and labeling clarity influence customer acceptance. This demand shift is encouraging suppliers to structure product lines around vegan, natural, Kosher, and Halal attributes, broadening their addressable market while also requiring stronger documentation and certification management.
Supply Chain and Cost Structure Dynamics
Cost structures remain a defining consideration, especially as fermentation-based routes become more prominent. The process demands precise control, quality assurance, and regulatory compliance, which together contribute to elevated production costs. Rather than treating these costs as a fixed disadvantage, market participants are increasingly viewing them through the lens of value capture: higher-quality grades, certified production, and reliable supply can support pricing resilience in segments where performance and trust matter more than lowest-cost sourcing. At the same time, geographic diversification of fermentation capacity is becoming a practical hedge against localized disruption. The expansion of certified facilities in new locations reflects a broader supply chain logic that favors redundancy, audit readiness, and proximity to end-user expectations over simple volume consolidation. For buyers, this means the supply base is slowly shifting from a price-first model to a reliability-and-qualification-first model.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of established multinational producers and specialized regional manufacturers, each pursuing distinct positioning strategies. Market share remains distributed rather than concentrated, giving room for differentiation through grade portfolios, certification strength, and application-specific support. Several companies illustrate the strategic directions shaping the market.
Strategic Positioning Among Core Players
Wacker Chemie AG has emphasized a plant-based, fermentation-derived L-Cysteine offering under its FERMOPURE® brand, spanning food, pharma, and free base grades. The company’s recent catalog updates and participation in food and nutrition trade events underscore a deliberate push to communicate vegan L-Cysteine solutions for bakery and animal feed applications. The opening of a new fermentation facility in León, Spain, with FSSC 22000 and ISO 9001:2015 certifications reflects a strategy centered on certified quality infrastructure and regional supply capability.
Ajinomoto Co., Inc. continues to leverage its fermentation expertise to supply pharmaceutical- and food-grade L-Cysteine derivatives. Its positioning aligns with customers that require advanced process capability and consistent derivative production, particularly where formulation specificity and regulatory alignment are important.
Merck KGaA provides L-Cysteine and derivatives across chemical, pharmaceutical, and food applications, supporting a broad specification range. Its relevance in the market stems from the ability to connect amino acid supply with higher-specification use cases where documentation and grade control are critical.
Evonik Industries AG has focused on L-Cysteine in cell culture media and supplements, including peptide-related offerings under its cQrex® platform. This positions the company closer to life-science and bioprocessing demand, where purity, consistency, and technical support can be more valuable than volume pricing alone.
In the regional and specialized segment, Shine Star (Hubei) Biological Engineering Co., Ltd. produces L-Cysteine HCl Monohydrate across multiple pharmacopeial and food-grade standards using biological fermentation. NIPPON RIKA Co., Ltd. supplies L-Cysteine that meets international standards for amino acid and culture media applications, emphasizing specification compliance for technical and bioprocessing customers. Penta Manufacturing Company manufactures and supplies L-Cysteine HCl Anhydrous in Natural, Kosher, Halal, and FCC grades, illustrating a grade-diversification approach that addresses food, regulatory, and cultural market requirements.
How Leading Strategies Are Differencing
Across these players, several strategic threads emerge. First, certification and quality infrastructure are increasingly used as market access tools, not just compliance checkboxes. Facilities designed around recognized food safety and quality standards can enter or expand in specification-sensitive segments more readily than those relying on less documented processes. Second, portfolio breadth by grade and application is becoming a way to capture demand across food, pharma, personal care, and feed without forcing customers to accept a one-size approach. Third, the vegan and fermentation narrative is being converted into tangible product architectures, particularly where bakery, food, and feed buyers value plant-based positioning and clear documentation. Fourth, geographic expansion of fermentation capacity is being used to strengthen supply resilience and alignment with regional customer expectations.
PW Consulting
Market Structure Evolution
The market is likely to continue evolving along two parallel paths. On one side, consolidation pressure may build among smaller producers who struggle to fund certified fermentation capacity, multi-grade portfolios, and audit-ready quality systems. On the other, specialization will remain attractive, especially where companies can serve pharma, cell culture, or culturally specific food requirements with differentiated grades and documentation. New entrants will face a higher threshold than in the past, because credibility in food safety, specification consistency, and certification is now part of the commercial equation. The net effect is a landscape that is neither fully consolidated nor purely commoditized, but increasingly shaped by capability, compliance, and application alignment.
Future Trends and Commercial Implications
Looking toward the 2026 to 2032 window, several trends are likely to influence how value is created and captured in the L-Cysteine market. These trends do not guarantee uniform growth, but they point to where commercial opportunities are most likely to materialize.
Lysine Market
Fermentation-Based Supply Will Continue Gaining Relevance
Fermentation is expected to maintain its upward trajectory as the preferred production route for a growing share of demand. The combination of cleaner ingredient positioning, stronger alignment with food safety expectations, and the ability to support multiple grades from a single platform makes fermentation a strategic foundation rather than a niche alternative. Commercially, this favors suppliers that can demonstrate certified processes, stable batch quality, and clear grade segmentation. For buyers, it means sourcing strategies will increasingly weigh fermentation capability and certification as core criteria, especially when ingredient origin and quality assurance affect downstream customer acceptance.
Demand Growth Will Remain Broad but Uneven
The overall market expansion is supported by demand across food, pharmaceutical, personal care, and animal feed applications, but growth rates and value capture will differ by segment. Food and beverage applications benefit from functional use cases and regulatory acceptance, while pharmaceutical and healthcare applications prioritize purity and documentation. Personal care and animal feed add volume potential, often with a stronger emphasis on cost and reliability. The commercial implication is that portfolio strategy matters: companies able to serve multiple demand profiles with appropriate grades and certifications are better positioned to capture growth without overrelying on any single end market.
Certification and Supply Reliability Will Become More Valuable Than Price Alone
As certified fermentation capacity expands and buyers become more accustomed to auditable quality systems, the relative importance of price-only competition is likely to diminish in specification-sensitive segments. This does not mean price becomes irrelevant, but it does suggest that reliability, traceability, and certification readiness will increasingly support premium positioning or at least protect share against lower-cost but less-qualified alternatives. The risk side of this trend is that any lapse in quality documentation or facility certification can quickly erode buyer confidence, particularly in food and pharma channels. Companies that treat compliance and quality systems as strategic assets rather than overhead will be better placed to sustain relationships through demand fluctuations.
Potential Risks and Uncertainties
Despite the constructive outlook, several uncertainties deserve attention. Production cost pressure from fermentation complexity and regulatory compliance can cap margin expansion if not offset by grade differentiation or efficient scale. Regulatory divergence across regions and applications may increase operational complexity, especially for suppliers serving both food and pharmaceutical customers from shared infrastructure. Demand growth may also vary more than expected if economic conditions affect discretionary food and personal care spending or if feed demand responds to broader agricultural and livestock cycles. Finally, the expanding importance of certified capacity could intensify competition for audit-ready facilities and skilled process talent, creating bottlenecks for companies trying to scale quickly without compromising quality standards.
Actionable Guidance for Decision-Makers
The L-Cysteine market is moving toward a structure where capability, certification, and application alignment matter as much as volume and cost. The following considerations can help different stakeholder groups translate the market direction into practical decisions.
For Manufacturers and Producers
Evaluate whether production strategy is aligned with the shift toward fermentation-based, certification-ready supply. Where feasible, invest in auditable quality systems and grade segmentation that allows the same core capability to serve food, pharma, and feed requirements without compromising documentation standards. Differentiation through vegan, natural, Kosher, and Halal attributes can widen addressable demand, but only if supported by verifiable processes and clear grade definitions. Avoid overexposure to price-only competition in segments where buyers increasingly value reliability and compliance.
NAC (Acetylcisteine) Market
For Investors and Strategic Partners
Focus on companies that demonstrate a credible link between fermentation capability, certified facilities, and application-specific grade portfolios. The most resilient positioning is likely to come from producers that can expand across multiple end-use sectors while maintaining specification integrity. Geographic diversification of production capacity and a clear plan for food safety and quality certification are indicators of supply resilience that can matter during disruption. In addition, pay attention to the balance between scale and specialization, since both models can succeed if matched to the right end markets and grade requirements.
For Procurement and Supply Chain Leaders
Treat certification, traceability, and production method as core sourcing criteria alongside price. Where downstream customers care about ingredient origin, labeling clarity, or application-specific performance, supplier qualification should include facility certifications, grade documentation, and consistency evidence rather than relying on spot-market pricing alone. Diversifying the supplier base across regions and fermentation capabilities can reduce exposure to localized disruption while preserving access to the grade profiles needed for food, pharma, personal care, or feed use cases.
The strategic picture for the L-Cysteine market is one of steady expansion shaped by process transition, regulatory acceptance, and demand diversification. The companies and buyers that benefit most will be those who treat quality systems, certification, and application alignment as central to commercial strategy rather than secondary to volume. For decision-makers seeking deeper segmentation data, regional granularity, and customized assessments of supply, pricing, and competitive positioning, the full research report provides more detailed coverage to support planning and benchmarking across the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: L-Cysteine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com