

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
LED Glass Market 2026: Beyond the 9.58% CAGR Story

The LED Glass Market: Strategic Trends and Commercial Opportunities in a High-Growth Segment
Market Landscape and Core Challenges
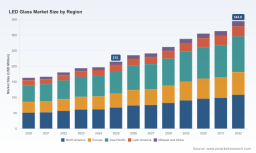
The LED glass market has transitioned from a niche architectural curiosity to a structurally significant component of modern display and facade systems. Over the historical period from 2020 to 2025, the sector expanded steadily, moving from a base of roughly $163 million to approximately $215 million. This trajectory reflects more than cyclical demand; it signals a foundational shift in how lighting, transparency, and digital content are integrated into built environments. Looking ahead through the forecast period extending to 2032, the market is projected to reach approximately $345 million, supported by a compound annual growth rate of 9.58 percent. The growth profile suggests a segment that is maturing in capability while still expanding in addressable use cases.
Beneath the headline numbers, the market is defined by a relatively fragmented structure. The top three players hold a combined share of roughly 24.6 percent, while the top five account for approximately 26.2 percent. This concentration pattern indicates that leadership is earned through application-specific expertise, integration capability, and regional distribution strength rather than through unchecked scale. For decision-makers, the implication is clear: market share is contested at the edges, and competitive advantage increasingly depends on engineering reliability, certification readiness, and the ability to pair glass solutions with compelling content ecosystems.
Despite the favorable growth outlook, the industry is navigating a set of challenges that will determine which participants capture disproportionate value over the next several years. Two to three structural friction points stand out. First, safety and compliance requirements continue to complicate thin-glass adoption, particularly in the United States, where glazing systems must satisfy rigorous testing protocols such as ANSI Z97.1 for lites used in building applications. This regulatory layer creates a barrier to entry for lightweight, high-transparency solutions and raises the cost of validation for new product lines. Second, the supply chain for raw materials remains sensitive to commodity dynamics, which directly affects unit economics and margin stability. Third, the market is undergoing a qualitative shift in how transparency and display performance are balanced, forcing manufacturers to reconcile aesthetic expectations with technical constraints. These challenges are not merely operational; they shape the pace of adoption, the viability of new form factors, and the strategic positioning of leading firms.
LED Lighting Market
Key Growth Drivers: Technology, Policy, Demand, and Cost Structure
The expansion of LED glass is being propelled by a convergence of forces that reinforce one another. Understanding these drivers is essential because they define where investment, product development, and commercial partnerships are likely to yield the highest returns.
Technology innovation remains the most visible catalyst. The integration of high-resolution LEDs directly into architectural-grade safety glass has progressed from experimental prototypes to commercially viable configurations, including laminated, surface-applied, and ceiling-hung solutions. This evolution is not just about embedding light sources; it is about engineering transparent digital displays that maintain clarity, durability, and visual fidelity in real-world environments. Recent industry activity underscores this shift. In early 2026, Ganglustr, a transparent glass LED specialist, published a piece highlighting switchable glass innovations and positioned transparent LED glass as a defining trend for modern retail and commercial facades. The emphasis on facade applications reflects a broader move toward using glass not only as a display surface but as a dynamic architectural element that communicates brand identity and adapts to context. Meanwhile, multi-year partnerships are emerging that extend LED glass beyond traditional screen installations. A notable example is the collaboration between the Big 12 Conference and ASB GlassFloor, which designated LED glass floors as official tournament courts for men’s and women’s basketball events. This move validates the durability and performance requirements of LED glass in high-traffic, high-visibility settings and signals a pathway for sports and entertainment venues to become early adopters of specialized glass-based surfaces.
Policy and regulatory environments are shaping adoption curves in both constraining and enabling ways. On one hand, safety glazing certification remains a practical hurdle. The need to demonstrate compliance with recognized testing standards introduces time and cost into product development, particularly for thin glass formats that must still meet structural and safety expectations. On the other hand, standardization efforts are beginning to reduce friction. The global harmonization of smart glass standards and the refinement of thin-film specifications for building applications are creating a more predictable compliance landscape. When standards converge across regions, manufacturers can scale with greater confidence, and specifiers can evaluate solutions against consistent criteria. Over time, this should lower the barrier to wider deployment and improve the comparability of competing offerings.
Demand-side behavior is changing as well. Commercial building owners, retailers, and event operators are increasingly seeking surfaces that do more than enclose or illuminate a space; they want architecture that communicates, adapts, and engages. Transparent LED glass meets this expectation by allowing displays to coexist with daylight, views, and spatial openness. In retail and commercial facades, the value proposition extends beyond signage: it encompasses brand presence, wayfinding, and the ability to refresh content without replacing physical infrastructure. In decorative contexts, the appeal lies in the combination of lighting quality and transparency, enabling designers to create immersive interior environments that feel both modern and integrated. The demand pattern is therefore not limited to a single application; it spans decorative, informational, and experiential uses, each with its own performance requirements and procurement rhythms.
Cost structure and supply chain dynamics also play a decisive role. The raw material environment has shown meaningful movement. Soda ash prices declined during 2025 due to oversupply and softer demand from key industries, and by mid-2026 the commodity was trading flat with declines measured over both the month and the year. For LED glass producers, commodity movements matter because they influence input costs, pricing flexibility, and the economics of scaling production. When material costs ease, there is more room to invest in process improvements, certification, and application development. Conversely, sustained volatility can compress margins and sharpen the focus on yield, material efficiency, and supplier relationships. The current environment suggests a favorable but not guaranteed window for cost optimization, making disciplined sourcing and transparent cost modeling important strategic priorities.
Competitive Landscape and Leadership Strategies
The competitive map in LED glass is shaped by firms that have chosen distinct paths to differentiation. Rather than competing solely on price, leading participants are building advantage through configuration expertise, application focus, and the ability to deliver transparent digital displays that perform reliably in architectural settings.
Clear Motion Glass, based in York, Pennsylvania, has positioned itself around cvLED transparent LED glass solutions that integrate high-resolution LEDs directly into architectural-grade safety glass. Its portfolio spans laminated, surface-applied, and ceiling-hung configurations, which indicates a strategy centered on flexibility of installation and adaptability to different project constraints. By emphasizing transparent digital displays that maintain architectural integrity, the company addresses a core specifier concern: how to introduce digital content without sacrificing the visual and structural qualities of glass. This approach suggests a focus on integration quality, safety compliance, and the ability to work within existing building systems rather than requiring wholesale redesigns.
Glasstronn, headquartered in Bangalore, India, has built its identity around transparent glass LED solutions that combine glass with LED technology for vibrant, ultra-transparent digital displays. Its emphasis on retail, commercial, and architectural applications points to a strategy oriented toward high-visibility environments where display quality and transparency are equally important. By focusing on the intersection of aesthetics and performance, the company aligns itself with the growing demand for facades and interior surfaces that serve both functional and brand-communication roles. The publication of industry-facing content on switchable glass innovations further signals a commitment to thought leadership and to shaping specifier expectations around transparent LED glass as a mainstream architectural choice.
The market structure suggests a landscape that is neither fully consolidated nor purely fragmented. With the top three and top five players holding modest combined shares, there is room for specialization, regional expansion, and application-led growth. At the same time, the presence of recognizable players with clear configuration strategies indicates that differentiation is achievable through engineering depth and application expertise. The evolution of the competitive field is likely to follow one of two complementary paths. First, integration and partnership models may become more important as LED glass moves into complex environments such as sports venues, retail facades, and decorative interiors. In these settings, success depends not only on the glass itself but on the ability to coordinate with media networks, installation teams, and building systems. Second, new entrants may target specific niches where transparency, form factor, or cost profiles create openings that broader players do not fully address. The result could be a market that remains diverse at the product level while consolidating around a smaller set of trusted integration partners in high-value applications.
For buyers and competitors alike, the strategic lesson is that leadership is increasingly defined by reliability in real-world deployments, the ability to navigate safety and certification requirements, and the capacity to pair hardware with content and installation expertise. Price competition exists, but it is unlikely to be the primary separator over the forecast horizon. Instead, the firms that stand out will be those that can demonstrate repeatable performance across configurations, maintain compliance readiness, and align their product roadmaps with where demand is moving, particularly in facade, decorative, and specialized venue applications.
Future Trends and Commercial Implications (2026–2032)
Looking forward, several trends are likely to shape the LED glass market over the next three to five years. These trends are not abstract; they carry direct implications for product strategy, partnership choices, and investment timing.
One important trend is the deeper integration of LED glass into architectural and venue systems as a standard option rather than a special-occasion solution. The extension of LED glass into tournament courts and the growing attention to retail and commercial facades indicate that the technology is moving toward repeatable deployment models. As more projects demonstrate durability and maintenance feasibility, specifiers will become more comfortable specifying transparent LED glass in new builds and retrofits. The commercial opportunity here lies in building application-ready portfolios that address installation logistics, content integration, and post-installation support, rather than selling glass as a standalone component.
A second trend is the continued push toward thinner, more transparent, and more seamlessly integrated forms. Standardization activity and certification pathways are gradually reducing uncertainty, which should encourage experimentation with lighter configurations and new integration methods. Thinner glass can improve aesthetics and reduce perceived visual weight, but it must still satisfy safety expectations and performance requirements. The firms that can balance these priorities through material science, lamination expertise, and testing discipline will be well positioned to capture demand from designers and architects who want digital functionality without compromising spatial quality. The risk is that thin-glass adoption may progress unevenly across regions, especially where safety glazing certification remains a practical hurdle.
A third trend is cost and supply chain normalization influencing product economics and pricing strategies. Commodity movements in inputs such as soda ash have the potential to improve unit economics when they move favorably, and the recent easing in prices has created a more supportive backdrop. However, commodity markets are cyclical, and reliance on temporary cost relief can be risky. The more durable advantage will come from process efficiency, yield improvement, and supplier diversification. Companies that treat cost structure as a strategic variable, rather than a passive outcome, will be better equipped to maintain margins through market cycles and to invest in the application development that drives long-term growth.
These trends connect to tangible commercial opportunities. For product developers, the opportunity is to build configurable platforms that can be adapted across decorative, facade, and venue applications without compromising safety or transparency. For integration and systems players, the opportunity is to offer end-to-end solutions that reduce specification risk and accelerate project timelines. For investors, the opportunity lies in identifying participants with credible certification readiness, application traction, and disciplined cost management, rather than those relying on short-term commodity tailwinds. The principal risks include regulatory variability across jurisdictions, the possibility that thin-glass adoption slows if certification costs remain high, and exposure to raw material volatility that could compress margins if not managed proactively.
Actionable Guidance for Decision-Makers
The strategic choices facing manufacturers, investors, and buyers are distinct, but they share a common need: clarity on where value is being created and where risk is concentrated. The following guidance is intended to support decision-making in the near term while keeping longer-term positioning in view.
PW Consulting
For manufacturers and product developers, the priority is to align product roadmaps with the applications that are demonstrating the strongest momentum while maintaining rigorous attention to safety, transparency, and installation practicality. Building a portfolio that spans laminated, surface-applied, and ceiling-hung configurations can broaden market access, but differentiation will come from proving repeatable performance in the environments that matter most to specifiers. It is equally important to treat certification and compliance not as a final hurdle but as a design constraint from the outset. Early alignment with recognized testing requirements reduces rework, shortens time to market, and strengthens credibility with building professionals. Finally, disciplined sourcing and cost modeling should be treated as core capabilities, not administrative functions, so that material cost fluctuations do not derail margin plans or investment in application development.
For investors and strategic partners, due diligence should focus on evidence of application traction, integration capability, and regulatory readiness rather than on headline technology claims alone. The market’s moderate concentration suggests that value can be captured by participants with clear differentiation, but it also means that not every player is positioned for sustained advantage. Evaluating a company’s ability to navigate safety glazing requirements, its track record in real-world installations, and its relationships with content, installation, and building-system partners can provide a more reliable view of durability than product narratives in isolation. Timing matters as well: the current environment offers a window in which cost structures are relatively supportive, but that window is not permanent, so investment theses should account for both near-term economics and the longer trajectory of standardization and adoption.
For buyers and procurement teams, the emphasis should be on reducing total project risk rather than minimizing unit price. Transparent LED glass is most valuable when it is specified as part of a coherent system that includes content strategy, installation planning, and maintenance considerations. Evaluating suppliers on configuration flexibility, compliance documentation, and post-installation support can prevent costly mismatches between expectation and performance. It is also prudent to assess how a supplier handles variability across regions and applications, since the same glass solution may face different certification expectations and performance demands depending on whether it is used in an interior decorative setting, a commercial facade, or a high-traffic venue. Procurement decisions that account for lifecycle cost and specification confidence are more likely to deliver durable value than those focused narrowly on initial price.
Optical Glass Market
Across all of these perspectives, the recurring theme is that detailed, current intelligence is a strategic asset. Market structure, regulatory dynamics, raw material conditions, and application momentum are all evolving, and the companies that act on the most accurate picture of these changes are best positioned to allocate capital, prioritize product development, and negotiate from strength. A complete, segmented view of the market—covering regional patterns, type and application splits, competitive positioning, and forward indicators—can sharpen these decisions and reduce the uncertainty that comes from relying on partial information. For those seeking a deeper dive with granular segmentation and tailored scenarios, the broader research resource that supports this analysis provides a more detailed foundation for planning and execution.
For detailed analysis of this topic, please visit the official page: LED Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com