

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Sports Turf Market 2026: What a 7.45% CAGR Said About Polyethylene's 182.8M Dominance

Sports Turf Market: Strategic Shifts and Commercial Opportunities in a Rapidly Evolving Landscape
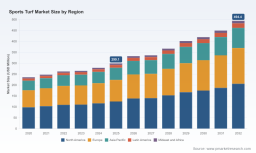
The global sports turf market has entered a phase of measurable expansion, driven by sustained investment in athletic infrastructure, advances in turf maintenance technology, and shifting demands from end users. From 2020 through 2025, the market grew from approximately 235.5 million to 299.1 million in annual revenue. Forward projections indicate continued traction, with revenue expected to climb toward 332.3 million by 2026 and continue expanding through 2032. The implied compound annual growth rate across the forecast window sits at roughly 7.45 percent, signaling a market that is moving beyond cyclical recovery into a structurally healthier trajectory. This expansion is not uniform across categories or geographies, and the companies that will capture disproportionate value are those that align product development, service models, and go-to-market strategies with where capital and operational priorities are actually shifting.
Artificial Grass Turf Market
For executives evaluating exposure to this space, the central question is less about whether the market is growing and more about which segments will compound faster, which cost pressures will reshape margins, and where competitive moats are being built or eroded. The following sections outline the current market context, the forces reshaping demand and supply, the competitive posture of leading players, and the strategic implications for manufacturers, investors, and procurement teams.
Market Context and Core Challenges
Revenue growth in the sports turf market reflects a combination of new field installations, replacement cycles, and higher spending on maintenance equipment that improves consistency and reduces downtime. Demand is anchored in football, baseball, hockey, golf, tennis, and rugby facilities, with broader discretionary sports and recreational applications contributing additional volume. The mix of product types continues to lean heavily toward polyethylene-based solutions, while polypropylene, nylon, hybrid constructions, and other materials serve more specialized performance or durability requirements. Regionally, North America and Europe account for the largest shares of activity, followed by the Asia Pacific region, with Latin America and the Middle East and Africa representing smaller but growing bases.
Despite the positive trajectory, the market faces a handful of structural challenges that will determine which operators thrive over the next several years.
Cost Pressures on Key Inputs
Steel and lithium-ion battery cells are among the components experiencing near-term inflationary pressure in sports turf equipment. For manufacturers, this translates into tighter margin management, more deliberate bill-of-materials engineering, and potentially longer development cycles as teams balance performance targets against total cost of ownership. For buyers, the same dynamics raise questions about whether newer electric or robotic platforms will deliver net savings over the full lifecycle, especially when factoring in charging infrastructure, servicing, and replacement part pricing. The implication is that equipment roadmaps will need to be evaluated not only by feature sets but by sensitivity to input cost volatility and the ability to pass through or absorb those costs across regions.
Labor Economics and Automation Adoption
Ride-on robotic mowers and related autonomous platforms are compressing labor costs for stadium operators and golf course superintendents managing sports turf. This is a meaningful shift because labor availability, wage inflation, and skill scarcity have become persistent constraints in field maintenance. Automation is no longer a niche experiment; it is increasingly positioned as a solution to scheduling reliability, consistency of cut, and reduced reliance on specialized crews. The challenge for adoption is not only capital expenditure but also integration with existing workflows, training requirements, and the need to validate performance under varying field conditions, weather exposure, and usage intensity.
Standards, Certification, and Operational Expectations
The regulatory and standards environment is becoming more consequential as facility owners, municipalities, and sports organizations seek to formalize best practices. ISO/TC 83 develops standards for sports and recreational facilities and equipment, including operational, maintenance, and safety requirements. In parallel, the Sports Turf Managers Association publishes Best Management Practices covering environmental facility certification and maintenance for sports turf. These frameworks do not simply impose compliance costs; they reshape procurement criteria, influence specifications, and create a reference point for product validation. Manufacturers and service providers that align early with recognized standards and provide documentation or performance evidence can reduce friction at the point of sale, while slower followers may face longer evaluation cycles and more demanding proof points.
Key Drivers Reshaping the Market
Technology Innovation and Performance Differentiation
The most visible driver is the pace of innovation in turf care equipment, particularly around electrification, autonomy, and precision maintenance. Recent product introductions illustrate how vendors are moving from incremental improvements to differentiated offerings with clear operational benefits. For example, in early 2026 Toro introduced the GreensPro e1700 all-electric greens roller designed for smooth, consistent golf greens and sports turf while boosting operator efficiency. This type of launch signals a broader direction: equipment is increasingly being designed for repeatability, reduced operator fatigue, and tighter control over surface conditions.
For the market, this matters because performance thresholds are rising. Field managers are not only looking for machines that can cut or roll; they are looking for tools that support consistent play quality, predictable maintenance windows, and lower operating disruption. As electric and robotic platforms mature, the competitive conversation is shifting from raw power to system-level value, including battery management, navigation reliability, service access, and integration with turf monitoring workflows. Companies that can package these capabilities into dependable, easy-to-deploy solutions are likely to see stronger pull from professional facilities and higher-tier recreational markets.
Policy and Standards as a Procurement Filter
Regulatory and standards activity is influencing market behavior by changing how facilities justify purchases and how vendors substantiate claims. ISO/TC 83's work on operational, maintenance, and safety requirements for sports and recreational facilities provides a reference structure that procurement teams can use to evaluate equipment and practices. At the same time, the Sports Turf Managers Association's Best Management Practices create an ongoing benchmark for environmental and maintenance standards. Together, these frameworks encourage a more disciplined purchasing environment where consistency, documentation, and adherence to recognized practices carry additional weight.
This does not mean regulation is a constraint in the traditional sense; it also creates a pathway for differentiation. Vendors that provide evidence of alignment with maintenance standards, that design for easier compliance, or that partner with facility managers on certification pathways can reduce uncertainty for buyers. In practice, this can shorten evaluation timelines and increase the likelihood that equipment is specified in tenders where standards are part of the scoring criteria.
Demand-Side Shifts in Facility Operations
On the demand side, facility operators are facing pressure to do more with constrained labor and tighter operating budgets. Stadiums, college campuses, high school programs, and golf operations are all managing higher expectations for surface quality while contending with scheduling intensity and maintenance cost control. This environment favors equipment and service models that improve throughput, reduce variability, and enable fewer skilled hours to cover more area without sacrificing quality.
The result is an incremental but durable shift toward solutions that address total cost of ownership rather than purchase price alone. Buyers are increasingly interested in whether a mower, roller, sprayer, or sweeper can reduce passes, improve consistency, lower fuel or charging overhead, and simplify maintenance. This dynamic also supports growth in replacement and refresh activity: as existing fleets age or fail to meet evolving performance expectations, operators reassess whether to continue with legacy equipment or transition to more automated or electrified alternatives.
Supply Chain and Cost Structure Realignment
Supply chain realities are influencing both product design and commercial strategy. Input cost volatility, particularly around steel and battery cells, is forcing more deliberate sourcing decisions and encouraging manufacturers to evaluate regional supply options, component standardization, and serviceability. At the same time, the growing interest in electric and robotic equipment introduces new dependencies on battery supply, power electronics, and software-enabled subsystems, which can change the shape of lead times and after-sales support requirements.
For the broader market, this realignment creates a split incentive. One path is toward more consolidated, engineered platforms with predictable support networks and stronger lifecycle value propositions. Another is toward specialized, application-focused tools that address discrete maintenance tasks where performance and reliability matter most. How companies navigate these two directions, and how they manage cost exposure while preserving differentiation, will be a defining factor in margin outcomes over the forecast period.
Competitive Landscape and Leading Strategies
The market features a mix of established equipment manufacturers, focused turf specialists, and distribution-oriented players. The competitive field is not defined solely by scale; it is increasingly shaped by how well companies tailor their offerings to professional sports turf use cases, from maintenance machinery to specialized construction and field-support equipment. A review of recent activity and company positioning shows several distinct strategic stances.
Strategic Postures Among Leading Players
The Toro Company, headquartered in Bloomington, Minnesota, focuses on sports turf maintenance through mowers, greens rollers, utility vehicles, and autonomous solutions tailored for athletic fields and sports turf. Its recent introduction of the GreensPro e1700 all-electric greens roller highlights a push into electrification and operator efficiency for precision surfaces. Deere & Company, based in Moline, Illinois, maintains a presence in golf and sports turf equipment, including mowers, sprayers, and maintenance machinery for athletic fields, with an emphasis on breadth across turf care and application equipment.
Playground Artificial Grass Turf Market
Husqvarna Group, headquartered in Stockholm, Sweden, offers commercial turf care equipment, CEORA robotic platforms, and ride-on mowers for professional sports field operations, placing it in a strong position around automation and robotic maintenance. STIHL, based in Waiblingen, Germany, contributes backpack and handheld equipment for turf and sports field maintenance, serving more targeted operator needs where maneuverability and access matter. Smithco, in Wayne, Pennsylvania, provides rollers, sweepers, sprayers, and GPS-enabled turf management machinery for athletic fields, reinforcing the trend toward data-enabled maintenance and more precise field conditioning.
Smaller but strategically relevant specialists round out the landscape. Progressive Turf Equipment offers rotary finishing mowers and autonomous mowing systems for natural grass and sports turf maintenance. Sportsfield Specialties focuses on sports construction and maintenance equipment for high school, college, and professional fields. MTD Products supplies lawn and garden equipment, including mowers and sprayers used in sports turf applications. Kubota Corporation, based in Osaka, Japan, provides compact tractors and turf care machinery for sports field management. Turf Equipment and Supply Company operates as a distributor and seller of Toro consumer and landscape contractor equipment for sports and turf maintenance, illustrating how distribution partnerships can extend reach and service coverage.
Differentiation and Emerging Trends in Competitive Positioning
Several patterns are visible across this group. First, differentiation is moving toward application-specific performance and operational efficiency rather than generic equipment capabilities. Companies are increasingly expected to demonstrate that their products handle the demands of repeated use on football pitches, baseball fields, hockey surfaces, golf areas, tennis courts, and rugby pitches, each with different wear patterns and maintenance priorities.
Second, autonomy and electrification are becoming strategic wedges. Robotic platforms and electric rollers or mowers are not just product categories; they are signals that a company is addressing labor constraints, consistency goals, and operating cost sensitivity. This creates a competitive dynamic in which vendors that can deliver dependable automation, strong service support, and a credible total-cost narrative may gain preference over those offering lower upfront price but weaker lifecycle economics.
Third, distribution and service reach remain critical. Equipment in this market is only as valuable as its availability, maintenance pathway, and local expertise. This gives distributors and service-oriented partners a meaningful role in shaping customer experience, especially in regions where facility managers depend on responsive support and parts access. The presence of dedicated distributors and regional specialists suggests that competitive advantage will continue to depend heavily on execution at the local level, not just product engineering at the corporate level.
The overall market concentration underscores the importance of both scale and specialization. With a moderately concentrated structure at the top, larger players have room to leverage breadth, brand recognition, and installed-base relationships, while focused specialists can compete by addressing niche performance requirements, specific sports, or particular maintenance workflows. Over time, this may lead to selective consolidation among companies seeking broader portfolios or regional coverage, alongside continued entry of specialized solutions in automation, precision maintenance, and field construction support.
Forward-Looking Trends and Commercial Implications
Accelerated Adoption of Electrified and Autonomous Maintenance Tools
Over the next three to five years, electrified rollers, mowers, and robotic platforms are likely to move from differentiated offerings to more mainstream considerations for a broader set of facilities. The driver is not only sustainability positioning; it is the operational case around labor savings, consistency, and reduced exposure to fuel management and engine maintenance. As these systems become more common, the market will likely see increased demand for charging infrastructure, service training, parts availability, and lifecycle support. Commercial opportunities will emerge for companies that can bundle equipment with deployment assistance, monitoring capabilities, or service agreements that reduce adoption risk.
Standards-Aligned Procurement as a Competitive Filter
As standards and best-practice frameworks become more embedded in facility decision-making, procurement processes are likely to place greater weight on documented compliance, maintainability, and safety performance. This trend favors vendors that can provide clear evidence of alignment and that design equipment to make compliance and maintenance more straightforward. It also creates a risk for companies that rely on less formal purchasing environments and are unprepared for increasing documentation and specification requirements. The opportunity lies in turning standards alignment into a sales enabler rather than treating it as a back-office requirement.
Regional Divergence in Investment Priorities
While North America and Europe remain pivotal, regional growth patterns will likely diverge based on sport development, public investment, and the pace of facility modernization. Areas with expanding sports infrastructure and growing interest in field quality may see faster uptake of newer equipment categories, while more mature markets may focus on replacement cycles, automation retrofits, and efficiency improvements. This divergence means that product portfolios, pricing strategies, and service models may need to be tuned to regional operating realities rather than delivered as one-size-fits-all solutions. Companies that understand local procurement behavior, service expectations, and field-use intensity will be better positioned to convert interest into installed equipment.
Risks and Uncertainties to Watch
Input cost volatility remains a key uncertainty, particularly for equipment dependent on steel and battery cells. If cost pressures persist or spike, pricing dynamics and margin expectations could shift quickly, affecting both manufacturers and buyers. Adoption of autonomous and electric systems may also face practical friction if field conditions, maintenance requirements, or support networks do not meet expectations in real-world use. In addition, standards-driven procurement can create short-term complexity if specifications evolve faster than product documentation or certification processes. Companies should monitor these variables as leading indicators of where demand may accelerate, slow, or redirect.
PW Consulting
Strategic Actions for Decision Makers
For manufacturers, the priority is to align product roadmaps with where operational value is being created. That means evaluating not just feature additions but the full lifecycle economics of electrification, autonomy, and precision maintenance. Designing for serviceability, predictable parts availability, and clear documentation of standards alignment can strengthen commercial positioning as procurement becomes more structured. It also pays to assess exposure to input cost volatility and to model how cost changes affect both pricing strategy and margin resilience across the forecast period.
For investors, the market suggests value in companies that have credible answers to labor constraints and operational consistency. Interest is likely to persist for platforms that combine dependable performance with serviceability and a believable total-cost proposition, especially where automation or electrification is central to the offering. Equally important is the quality of distribution and service reach, since equipment adoption in sports turf depends heavily on local support and repeat purchasing behavior. Monitoring regulatory and standards activity, as well as input cost trends, can provide early signals about which business models are more durable.
For procurement teams and facility operators, the practical task is to evaluate equipment against real operating conditions rather than headline specifications. Total cost of ownership, integration with existing workflows, service responsiveness, and alignment with recognized maintenance practices should carry significant weight. Piloting or phased adoption of robotic and electric solutions can help validate performance and labor savings before broader rollout. In addition, engaging early with vendors that can support documentation and standards-related requirements may reduce friction in future procurement cycles.
As the sports turf market continues to expand and its competitive dynamics become more performance- and operations-driven, the organizations that act early on these shifts will have a clearer path to capturing durable value. For readers seeking a more granular view of segment dynamics, regional patterns, and customized strategic options, the full PW Consulting market analysis provides deeper segmentation detail, updated company benchmarking, and scenario-based guidance tailored to specific business objectives.
For detailed analysis of this topic, please visit the official page: Sports Turf Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com