

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Chemical Polishing Slurry Market: Why 7.2% CAGR and Asia Pacific Drive 2032 Expansion

Strategic Trends and Commercial Opportunities in the Chemical Polishing Slurry Market
1. Market Landscape and Core Challenges
The global chemical polishing slurry market has demonstrated consistent expansion, growing from $1,580.0 million in 2020 to an estimated $2,048.0 million in 2025. This trajectory reflects a compound annual growth rate of 7.2% over the historical period, with projections indicating the market will reach $3,331.0 million by 2032. The compound annual growth rate remains stable through the forecast horizon, signaling that demand drivers are structural rather than cyclical.
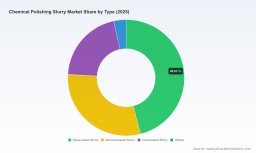
Regional distribution reveals a clear concentration of activity in Asia Pacific, which accounts for the largest share of market value, followed by North America and Europe. The remaining regions—Latin America and the Middle East and Africa—represent smaller but steadily growing pockets of demand. By material composition, silica-based formulations dominate the product mix, with alumina-based and ceria-based slurries occupying meaningful but secondary positions. Application segments are heavily anchored in integrated circuits, which represent the largest end-use category, while memory devices and advanced packaging follow as substantial secondary demand centers.
This broad expansion masks several structural friction points that market participants must navigate. First, the industry operates under a highly concentrated competitive structure, with the top three players controlling roughly 65% of total revenue and the top five commanding approximately 78%. This concentration creates high barriers to entry and limits the ability of smaller firms to compete on scale or pricing alone. Second, the sector sits at a technological inflection point where traditional slurry formulations must adapt to ever-smaller feature sizes, new dielectric materials, and tighter defectivity tolerances. Legacy recipes that performed adequately at earlier technology nodes often fail to meet the selectivity, uniformity, and removal rate requirements of modern fabrication lines. Third, the supply chain remains vulnerable to raw material volatility and regulatory shifts, which can compress margins or force abrupt reformulation cycles.
2. Key Drivers of Market Change
Technological Innovation and Process Evolution
The push toward more advanced semiconductor architectures continues to reshape slurry requirements. As device manufacturers transition to finer patterning and multi-layer integration, polishing solutions must balance aggressive material removal with minimal subsurface damage and low defect counts. This has spurred development in monodispersed colloidal silica formulations, tighter particle size distributions, and engineered surface chemistries that improve selectivity between different film stacks. Entegris, Inc. expanded its CMP slurry production capacity in Taiwan in October 2025 to position closer to leading foundries, a move that reflects the broader industry emphasis on co-locating chemical supply with high-volume fabrication hubs to accelerate development cycles and reduce logistical friction.
CMP Slurries Market
Beyond node scaling, the rise of advanced packaging and heterogeneous integration has introduced new material interfaces that require tailored planarization behavior. Slurry suppliers are increasingly expected to provide formulations that work across oxide, tungsten, polysilicon, and barrier layers without compromising downstream yield. This demand for versatility is pushing R&D teams toward modular formulation platforms rather than single-purpose products, enabling faster adaptation when fab processes change.
Regulatory and Compliance Pressures
Regulatory requirements are becoming a more visible force in slurry development and distribution. Chemical mechanical planarization slurries that contain hazardous components must be accompanied by comprehensive safety documentation, and recent alignment with GHS standards and China GB/T 16483 requirements has raised the compliance burden for cross-border trade. In China, CMP slurry products fall under State Council Order 591 for the safety management of hazardous chemicals, which influences storage, handling, transportation, and import procedures. These regulatory layers do not merely add paperwork; they affect time-to-market, distribution logistics, and the cost structure of serving certain geographies. Firms that build robust compliance frameworks early gain an advantage in securing long-term supply agreements with fabs that face their own audit and risk management obligations.
Demand-Side Shifts in Semiconductor Manufacturing
Semiconductor demand continues to be shaped by the growth of high-performance computing, memory expansion, and the broadening use of integrated sensors and connectivity modules. These applications drive wafer starts and, by extension, the volume of planarization steps required across design nodes. At the same time, fabrication strategies are shifting toward higher-mix, higher-margin production, which increases the importance of chemical suppliers that can support multiple process flows and respond quickly to recipe adjustments. Beijing Grish Hitech Co., Ltd. updated its CMP slurry product catalog in March 2025, introducing new particle size grades in the 50–110 nm range for semiconductor and LED applications. This kind of incremental product broadening illustrates how suppliers are aligning their offerings with the precision demands of current device fabrication while keeping pace with adjacent markets such as optoelectronics and optical glass.
Worldwide Polishing Slurry Market
Supply Chain and Cost Structure Dynamics
Input cost volatility remains a recurring theme. Cerium oxide prices rose 45% in March 2025 following a 10% increase in China-origin imports, according to industry reporting. Because ceria-based slurries are important for certain oxide removal applications, price spikes in foundational raw materials can compress supplier margins and, if passed through to customers, affect procurement budgets. This environment encourages several responses: dual sourcing for critical minerals, longer-term supply contracts, formulation adjustments that reduce dependence on the most volatile inputs, and vertical integration where feasible. The cost structure of slurry manufacturing is therefore becoming more strategic, with procurement, logistics, and regulatory compliance increasingly treated as core capabilities rather than support functions.
3. Competitive Landscape and Leading Strategies
Differentiation Among Established Players
The competitive field features a mix of global specialty chemical suppliers and regionally focused manufacturers, each pursuing distinct strategic positions. Cabot Microelectronics Corporation operates as a leading global supplier of high-purity fumed silica dispersions and custom CMP slurries for semiconductor wafer planarization, with a strong emphasis on process reliability and close collaboration with major device makers. Fujimi Incorporated is known for its PLANERLITE series, which addresses ILD/STI, tungsten, polysilicon, barrier, and oxide applications, positioning the company around a broad application catalog and established customer relationships in Japan and beyond. Entegris, Inc. focuses on dielectric and specialty CMP slurries, including ceria formulations designed for advanced nodes, and its recent capacity expansion underscores a strategy tied to geographic proximity and service responsiveness.
Asian manufacturers bring complementary strengths. Beijing Grish Hitech Co., Ltd. supplies colloidal silica-based CMP slurries for semiconductor, LED, optical glass, and metal polishing, leveraging a diversified end-use base that can buffer volatility in any single segment. JSR Corporation develops mono-dispersed colloidal silica CMP slurries aimed at selective layer polishing and low defectivity, aligning its product logic with the precision requirements of next-generation processes. Ace Nanochem Co., Ltd., based in South Korea, specializes in oxide CMP slurries, silicon wafer stock slurries, edge and backside polishing slurries, and colloidal silica for semiconductors, an offering set that spans both front-end and ancillary polishing needs. Jizhi Electronic Technology Co., Ltd. serves as a specialist supplier of oxide CMP slurries for STI and metal applications, with local technical support focused on the Yangtze Delta fab cluster, an approach that prioritizes proximity, responsiveness, and regional knowledge.
Strategic Themes in the Competitive Field
Several strategic themes emerge across these players. Proximity to major fabrication centers is increasingly treated as a competitive asset, both for faster development cycles and for more reliable supply. Product breadth is being balanced against deep specialization, with companies maintaining a core of high-value formulations while selectively broadening into adjacent applications. Regulatory readiness and documentation quality are becoming differentiators in markets where hazardous chemical management is tightly controlled. At the same time, customers are pushing suppliers toward greater transparency in particle characteristics, removal behavior, and defect performance, which raises the bar for quality systems and technical support.
Market Structure Evolution
The competitive structure appears likely to continue along a path of consolidation among scale players and selective inroads by specialized entrants. Large suppliers benefit from established qualification pipelines, broad formulation libraries, and the ability to absorb raw material fluctuations more readily. Smaller or regional suppliers can compete by offering rapid technical support, customized grades, and lower-friction engagement with local fab ecosystems. Entrants that are purely cost-driven face steep qualification hurdles and limited pricing power, while entrants that combine material science expertise with strong service and compliance capabilities have a more viable path. The overall trend points to a market where differentiation increasingly rests on process support, reliability, and the ability to co-develop with customers rather than on price alone.
4. Future Trends and Commercial Implications
Trend One: Precision-Driven Formulation and Application-Specific Solutions
Over the next three to five years, slurry development is expected to tilt further toward application-specific performance, with tighter control over particle size distribution, surface chemistry, and slurry stability. As device complexity grows, fabs will continue to favor suppliers who can deliver formulations tuned to particular film stacks and process windows. Commercial opportunities will accrue to organizations that can shorten development cycles, provide robust technical engagement, and demonstrate consistent results across multiple lots and tool environments.
The associated risk is that over-engineering for one process window can limit flexibility. Suppliers must balance specialization with enough platform modularity to adapt when process recipes change, otherwise they risk stranded development effort and reduced addressable demand.
PW Consulting
Trend Two: Regional Supply Shoring and Service Proximity
Geographic alignment between chemical supply and fabrication hubs is likely to deepen. The move to expand production or support capacity closer to key foundry and memory clusters reflects the value placed on shorter feedback loops, faster problem resolution, and improved supply continuity. For manufacturers, this suggests that regional service capability will weigh more heavily in supplier selection, particularly in areas with dense fab concentrations. For investors, it indicates that asset deployment decisions will increasingly factor in proximity to demand rather than cost-minimal siting alone.
A related uncertainty is the uneven pace of fab expansion across regions and the possibility that capacity builds could be moderated by demand timing or broader macro conditions. Suppliers that plan for flexibility—through staged capacity additions, multi-geography support, and adaptable logistics—will be better positioned if expansion timelines shift.
Trend Three: Cost and Compliance as Strategic Capabilities
Raw material volatility and regulatory requirements are expected to remain central considerations rather than occasional disruptions. The ceria oxide price surge in early 2025 and the continuing alignment of hazardous chemical documentation with GHS and China GB/T 16483 illustrate how input costs and compliance obligations can influence both sourcing strategy and market access. Organizations that build strong supplier relationships, diversify critical inputs, and maintain rigorous safety and documentation practices will be better equipped to preserve margins and sustain customer confidence.
The commercial opportunity lies in turning these constraints into trust signals. A supplier that can reliably demonstrate compliance readiness, transparent sourcing, and predictable quality can differentiate in negotiations and long-term agreements. The risk is that any lapse in documentation, handling, or input continuity can quickly erode that trust, particularly in a market where qualification cycles are long and switching costs are high.
5. Strategic Recommendations for Decision Makers
For Manufacturers and Chemical Suppliers
- Prioritize formulation platforms that support rapid adaptation across oxide, tungsten, polysilicon, and barrier applications, reducing time-to-qualification when fab processes change.
- Invest in regional technical support and, where feasible, production or blending capacity that places operational teams closer to major fab clusters to improve responsiveness and continuity.
- Strengthen compliance and safety documentation processes to meet GHS, China GB/T 16483, and related hazardous chemical management expectations, treating these as market access enablers rather than administrative overhead.
For Investors
- Evaluate suppliers based on their ability to combine material science depth with service proximity, as these attributes increasingly determine customer retention and pricing resilience.
- Monitor raw material exposure and sourcing strategy, particularly for ceria-dependent formulations, and weigh companies that show realistic mitigation plans through dual sourcing, contract structures, or formulation flexibility.
- Consider the differentiation potential of specialized regional players that can offer tailored grades and responsive support, while recognizing the qualification and scale advantages held by established global suppliers.
For Procurement and Fab Operations Teams
- Build supplier qualification criteria that weigh defect performance, selectivity, and process support alongside unit cost, given the long-term impact of slurry behavior on yield and line stability.
- Incorporate compliance readiness and documentation quality into supplier evaluation to reduce the risk of delays or access constraints in regions with stringent hazardous chemical management requirements.
- Maintain visibility into raw material price trends and sourcing concentration to anticipate cost pressure and support more resilient contracting decisions.
The strategic picture in the chemical polishing slurry market points to durable growth underpinned by semiconductor demand, but sustained success will depend on how well participants navigate concentration dynamics, precision requirements, regulatory expectations, and input cost volatility. Detailed segment-level sizing, competitive benchmarking, and tailored scenario analysis can sharpen execution decisions and reduce uncertainty across product, geography, and application choices. For decision makers seeking a fuller view of the data and customized implications for their operating context, the complete PW Consulting research report on the chemical polishing slurry market provides expanded segmentation detail, company-level profiles, and deeper scenario analysis.
For detailed analysis of this topic, please visit the official page: Chemical Polishing Slurry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com