

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Fuel Cell Membranes Market: Why 17.4% CAGR and APAC Shift Redefine Growth

Fuel Cell Membranes Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
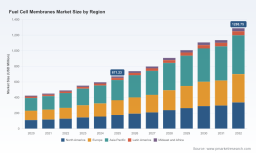
The fuel cell membranes market has evolved from a niche component sector into a critical enabler of the broader hydrogen economy. Measured by global revenue, the industry generated approximately 671.23 USD Million in 2025, up from 423.74 USD Million in 2020. This trajectory reflects a compound annual growth rate of 17.4 percent through 2032, with revenue projected to surpass 1.2 billion USD Million by the end of the forecast period. The growth is not uniform. Demand is spreading across stationary power, transportation, and portable applications, while regional momentum is shifting toward Asia Pacific, followed by Europe and North America.
Behind these headline figures, the industry is navigating a series of structural tensions. First, membrane performance must keep pace with increasingly stringent operational requirements. Fuel cell stacks are being pushed toward higher power densities, lower operating temperatures in some configurations, and longer lifetimes in harsh environments. Meeting these demands requires membranes that balance proton conductivity, mechanical durability, and chemical stability, a combination that remains technically demanding even as material science advances.
Second, cost and supply chain resilience are becoming decisive competitive factors. The membranes segment relies on specialized polymers, ionomers, and precise manufacturing processes that have historically been concentrated among a small number of suppliers. As scale increases, manufacturers are under pressure to reduce bill-of-materials costs while maintaining quality consistency. Any disruption in raw material availability or production capacity can ripple through downstream stack assembly and system deployment timelines.
Third, the market is experiencing a policy-driven inflection point. Public support for hydrogen technologies is expanding, but the pace and shape of that support vary widely across jurisdictions. Incentive structures, emissions criteria, and technical targets are reshaping what qualifies as commercially viable. Companies that cannot align their product roadmaps with evolving regulatory expectations risk being sidelined, even if their technology is technically sound.
Key Drivers of Market Change
Technology Innovation and Material Breakthroughs
Material innovation is the most direct lever for expanding the addressable market for fuel cell membranes. Researchers and manufacturers are pursuing thinner membranes with higher proton conductivity, improved thermal and mechanical robustness, and reduced reliance on scarce or costly inputs. These improvements matter because they influence stack efficiency, system size, and lifetime performance. A membrane that conducts more effectively at lower thickness can enable more compact stacks, which in turn opens new design possibilities for vehicles, stationary units, and portable devices.
Recent technical targets from the U.S. Department of Energy illustrate the direction of travel. The department has articulated performance expectations for PEM fuel cell components that include membranes with less than 10 micrometer thickness and proton conductivity around 0.2 S/cm at 80 degrees Celsius. These benchmarks are not merely laboratory aspirations; they signal the performance threshold that commercialization efforts increasingly need to meet. Companies that can deliver membranes consistently at or near these specifications are better positioned to win contracts in mobility and stationary applications where efficiency and packaging constraints are tight.
Policy and Regulatory Environment
Policy support is reshaping both demand and economics. In the United States, the Inflation Reduction Act provides a Clean Hydrogen Production Tax Credit of up to 3 USD per kilogram for hydrogen with well-to-gate emissions below 0.45 kg CO2e per kg H2. This incentive changes the economics of hydrogen supply, which in turn affects the attractiveness of fuel cell deployments that depend on affordable, low-carbon hydrogen. When hydrogen production becomes more cost-competitive, downstream applications become more viable, and membrane demand follows.
Alongside production incentives, technical targets and cost-roadmap goals are influencing procurement and product development. U.S. Department of Energy multi-year plans outline hydrogen production cost targets of 2 USD per kilogram by 2026 and 1 USD per kilogram by 2031. These targets frame the cost structure that fuel cell systems, including membrane-based components, need to support. The implication is clear: membrane suppliers and system integrators must anticipate not just performance requirements, but the cost trajectory that policy and public investment are pushing the industry toward.
PW Consulting
Demand-Side Behavior and Application Expansion
Demand is broadening beyond early adopters and demonstration projects. Stationary applications continue to represent a substantial share of membrane demand, driven by power generation, backup power, and distributed energy needs. Transportation remains a strong growth vector, particularly where electrification alternatives face range, payload, or refueling time constraints. Portable applications add another layer of diversification, though at a smaller scale.
A telling example of how demand can pivot comes from the stationary power segment. In November 2025, Ceres Power signed a manufacturing licence agreement with Weichai Power for production of Ceres-designed fuel cells and stacks targeting stationary power markets, including AI data centres. This agreement highlights how fuel cell technology is being positioned for high-value, continuous-power applications where reliability and footprint matter. For membrane suppliers, such partnerships expand the pool of potential manufacturing and deployment partners, while also signaling that data centre and critical infrastructure power needs are becoming a strategic demand source.
Supply Chain and Cost Structure Shifts
Cost reduction is increasingly tied to vertical integration, manufacturing scale, and material strategy. Several companies are expanding in-house capacity for membrane-related components, including membrane electrode assemblies, to gain control over quality, lead times, and unit economics. Roll-to-roll manufacturing and other continuous production methods are being explored to improve throughput and consistency. At the same time, supply chain resilience has become a priority, with U.S. Department of Energy project work identifying membrane and ionomer materials as critical components for both supply chain resilience and cost reduction in fuel cell manufacturing.
For commercial strategy, this means that membranes are no longer just a performance component; they are a strategic supply chain asset. Companies that can secure reliable material inputs, optimize manufacturing processes, and reduce dependency on a narrow supplier base are gaining an advantage. Conversely, organizations that rely on fragmented sourcing or lack visibility into material availability may face cost volatility and deployment delays.
Competitive Landscape and Leading Strategies
The competitive field is defined by a mix of system integrators, component specialists, and manufacturers pursuing in-house production of membrane-related assemblies. Market concentration remains notable, with the top three companies accounting for roughly 61 percent of market revenue and the top five reaching about 67 percent. This concentration suggests that scale, brand recognition, and established customer relationships still matter greatly, even as innovation and niche differentiation create openings for new entrants.
Ballard Power Systems, based in Burnaby, British Columbia, Canada, is one of the most recognized names in PEM fuel cell systems. Its profile centers on designing, developing, manufacturing, and selling fuel cell systems for mobility, stationary, and marine applications. Proprietary membrane electrode assemblies, including membranes, form a core part of its fuel cell stacks. Ballard’s strategic positioning is built on broad application coverage and long-standing system-level expertise, which gives it visibility across multiple end markets and a platform for iterative membrane and MEA improvements tied to real-world stack performance.
Plug Power Inc., headquartered in Latham, New York, USA, operates as a manufacturer and supplier of PEM fuel cell systems and MEAs, with in-house production of membranes for its GenDrive mobility and GenSure stationary products. This in-house capability is strategically significant. By controlling more of the membrane and MEA supply chain, Plug Power can better align component production with its system roadmap, reduce dependency on external suppliers, and respond more quickly to volume changes. Its commercial focus on both mobility and stationary applications also diversifies revenue exposure.
Hyzon Motors Inc., based in Bolingbrook, Illinois, USA, develops and manufactures high-performance hydrogen fuel cell systems and operates an in-house roll-to-roll membrane electrode assembly manufacturing line for proprietary components. This manufacturing approach points to a strategy centered on performance customization and production control. For Hyzon, the ability to produce proprietary membrane-related components in-house supports differentiation in the commercial vehicle and heavy-duty segments, where performance, durability, and system integration are central buying criteria.
Freudenberg e-Power Systems, located in Weinheim, Germany, supplies fuel cell components including membranes and seals for PEM and other fuel cell technologies. Its role illustrates a different competitive posture: component supply and engineering partnership rather than full system branding. Freudenberg’s strengths lie in material expertise, precision component supply, and the ability to serve multiple customers and applications through a focused components business. This model can be attractive in a market where some system builders prefer to source advanced membranes and related parts from specialized suppliers rather than internalize all production.
The recent Ceres Power and Weichai Power agreement also illustrates a broader competitive trend: licensing and partnership models are becoming more prominent alongside direct manufacturing. In this case, the agreement targets stationary power markets including AI data centres, signaling that intellectual property and licensed manufacturing can be a viable route to scale, especially when paired with a strong local manufacturing partner. This pattern suggests the competitive landscape is not only about who makes membranes, but also about who controls the design, licensing, and deployment pathways that turn membrane technology into deployed systems.
Strategic Evolution: Consolidation, Fragmentation, and New Entry
The market is showing signs of both consolidation and fragmentation, depending on the segment. In established system-level applications, scale advantages and customer qualification cycles favor larger players with proven track records. At the same time, new entry remains possible in component supply, specialized membrane formulations, and licensed manufacturing. The presence of in-house MEA production among several leading companies indicates that vertical integration is becoming a more common response to cost, quality, and supply chain concerns.
At the same time, end-use diversification is fragmenting demand patterns. Stationary, transportation, and portable applications each impose different technical and commercial requirements, which means a single membrane strategy is rarely sufficient. Companies that can tailor products to application-specific needs, or that can supply a broad range of customers through component Sales, are better positioned to capture growth across multiple demand pockets. The strategic question is whether to compete as a system-level brand, a high-value component supplier, or a licensed technology partner. Each path carries a different risk-return profile.
Future Trends and Commercial Implications
Trend 1: Performance-Barrier Reduction and Wider Adoption
As membrane technology advances toward thinner, more conductive, and more durable formulations, the performance barriers that have limited adoption in certain applications are likely to ease. This trend should support broader use in transportation and stationary deployments where efficiency, packaging, and operating lifetime are decisive. Commercially, this creates opportunities for suppliers that can reliably meet higher performance expectations while maintaining cost discipline. It also raises the stakes for producers that fail to keep pace with evolving specifications.
Ceramic Membrane Market
Trend 2: Policy-Aligned Economics Becoming a Purchasing Criterion
Hydrogen production incentives, emissions thresholds, and cost targets are increasingly shaping procurement decisions. Buyers are not just evaluating membrane performance; they are evaluating how component choices fit into a broader system that must meet policy-driven cost and emissions expectations. This trend favors suppliers and integrators that can articulate the link between membrane selection, stack efficiency, hydrogen utilization, and total cost of ownership. It also means that regulatory developments in major markets can quickly alter demand patterns, making policy monitoring a core business function rather than a peripheral activity.
Worldwide Breathable Membranes Market
Trend 3: Manufacturing Control and Supply Chain Resilience as Competitive Moats
As volumes grow, manufacturing capability and material security will become more important differentiators. Companies with in-house MEA production, continuous manufacturing processes, and diversified material sourcing are likely to be better positioned to manage cost, quality, and lead-time risk. This trend could accelerate partnership, licensing, and selective vertical integration across the value chain. It also introduces a cautionary note: over-investment in fixed manufacturing capacity without aligned demand can create financial strain, especially if deployment timelines shift or policy support changes.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Policy support may change in pace or design, affecting hydrogen economics and demand timing. Technical targets may prove difficult to meet consistently at scale, especially under real-world operating conditions. Raw material availability and pricing can affect margin stability, particularly for specialized polymers and ionomers. Finally, competition from alternative power technologies, including advances in batteries and hybrid systems, continues to shape the commercial context in which fuel cell membranes are evaluated. These risks do not negate the growth outlook, but they do suggest that strategy should be built around flexibility, scenario planning, and close monitoring of both technology and policy developments.
Actionable Recommendations for Decision-Makers
For Manufacturers and Component Suppliers
- Align membrane development with application-specific performance targets rather than pursuing a single universal specification. Stationary, transportation, and portable uses impose different durability, conductivity, and packaging needs, and product portfolios should reflect that reality.
- Evaluate selective vertical integration or partnership models for membrane electrode assemblies and related components. In-house capability can improve quality control and responsiveness, but it should be weighed against capital intensity and demand uncertainty.
- Treat material security and manufacturing resilience as strategic priorities. Diversify sourcing where possible, monitor critical material dependencies, and build production processes that can support consistent quality at higher volumes.
For Investors
- Focus on companies with clear pathways to scale, whether through in-house manufacturing, licensing, or strong system-level customer relationships. Revenue concentration in the market means that competitive positioning and customer access are especially important.
- Assess exposure to policy-driven economics, particularly hydrogen production incentives and technical targets that influence downstream demand. Companies that can connect their component or system offerings to these macroeconomic drivers may have stronger commercial momentum.
- Watch for partnerships and licensing agreements that expand reach into high-value stationary applications, such as data centre power and critical infrastructure, where reliability and continuous operation can support premium positioning.
For Procurement and Strategic Buyers
- Evaluate membrane and MEA suppliers not only on performance specifications, but also on manufacturing reliability, supply chain transparency, and the ability to support long-term volume needs. Qualification cycles are often long, so supplier stability matters.
- Consider total system economics, including how membrane choices affect stack efficiency, lifetime, and hydrogen utilization. In policy-supported markets, these factors can be as important as upfront component cost.
- Plan for evolving technical targets and regulatory expectations. Procurement strategies should remain flexible enough to accommodate performance improvements and cost changes as the market matures.
Conclusion
The fuel cell membranes market is entering a phase where performance, cost, policy, and supply chain strategy are tightly intertwined. Growth is supported by expanding demand across stationary, transportation, and portable applications, while technical targets and hydrogen economics are sharpening the requirements that suppliers must meet. Market concentration indicates that scale and established relationships remain powerful advantages, but the rise of in-house manufacturing, licensing models, and application-specific differentiation shows that the competitive field is still evolving.
For organizations operating in or adjacent to this market, the most valuable next step is to convert broad trends into specific decisions about product positioning, manufacturing strategy, supplier selection, and investment timing. Detailed segmentation data, regional breakdowns, and company-level assessments can make those decisions more precise and less dependent on generalization. The full research report provides that deeper view, with granular market splits, competitive profiling, and structured scenarios designed to support planning across manufacturing, investment, and procurement teams.
For detailed analysis of this topic, please visit the official page: Fuel Cell Membranes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com