

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Classical Swine Fever Vaccines Market: How Asia Pacific Leads the 5.62% CAGR Shift

Classical Swine Fever Vaccines Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for Classical Swine Fever (CSF) vaccines is entering a phase of structural transformation. Absolute revenue has expanded from $118.45 million in 2020 to $141.12 million by 2025, with a projected trajectory toward $208.81 million by 2032. This growth trajectory, supported by a 5.62% compound annual growth rate over the 2026–2032 forecast window, reflects more than incremental demand expansion; it signals a market recalibrating around technology differentiation, regulatory pragmatism, and regional risk profiles. For executives and investors, the opportunity lies not simply in volume growth but in capturing value at the intersection of DIVA-compatible vaccine design, supply chain resilience, and policy-driven adoption shifts.
Understanding the CSF vaccine landscape requires looking beyond headline figures. The market is fragmented, with top-three competitors holding less than a quarter of total revenue and the top five collectively accounting for just over 31%. This fragmentation is not accidental. It reflects heterogeneous regional disease pressures, divergent regulatory philosophies, and the technical complexity of matching vaccine platforms to specific outbreak-control or endemic-prevention strategies. Growth is being pulled from distinct directions simultaneously, and the winners will be those who align product portfolios, manufacturing footprints, and partnerships with regional risk realities rather than pursuing a one-size-fits-all global play.
Resilience in a Fragmented, Risk-Aware Market
Despite steady revenue expansion, the CSF vaccine market faces a set of interlocking challenges that will define competitive positioning over the next several years. The first is the tension between emergency outbreak response and routine prophylactic use. In regions where CSF remains endemic or where disease incursions remain a constant threat, vaccine deployment is often triggered by policy directives or outbreak events rather than organic commercial demand cycles. This creates revenue patterns that are sensitive to political decision-making, trade restrictions, and compensation schemes for stamping-out versus vaccination strategies. Companies operating in this space must build forecasting models that account for policy volatility as much as biological demand.
Avian Influenza Vaccines Market
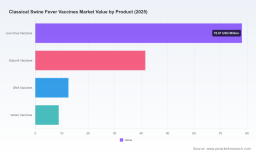
A second challenge lies in the diversity of vaccine technologies and the operational trade-offs they entail. Traditional modified live virus (MLV) vaccines dominate current revenue, supported by long-standing manufacturing know-how and established field efficacy. Yet these platforms carry inherent complexities in seed-lot validation, batch consistency, and in some cases regulatory scrutiny related to residual virulence or differentiation challenges. Alternative platforms such as subunit, DNA, and vector vaccines represent a smaller but strategically significant share of the market. They promise improved safety profiles and, in certain designs, compatibility with companion diagnostic tests that distinguish vaccinated from infected animals. The challenge for manufacturers is that these alternatives often require different production infrastructure, distinct regulatory submissions, and new commercial partnerships with diagnostic developers to unlock their full field value.
A third structural pressure relates to cost economics and regional procurement behavior. Labor cost patterns, raw material sourcing, and the validation burden associated with conventional production methods all influence the economics of vaccine supply. In price-sensitive markets, procurement decisions can tilt toward lowest-cost options that are still accepted by national veterinary authorities. In higher-regulation regions, procurement decisions weigh differentiation capability, emergency-readiness status, and alignment with regional surveillance frameworks. The result is a market where value capture depends as much on regulatory navigation and technical messaging as on product performance alone.
The Forces Reshaping Demand and Supply Dynamics
Four drivers are currently exerting the strongest influence on the CSF vaccine market's evolution, and each carries a distinct commercial implication.
Technological innovation and differentiation capability. The push toward DIVA-compatible vaccines has become a defining theme. Vaccines that enable differentiation between infected and vaccinated animals reduce a fundamental barrier to vaccination adoption in regions where trade restrictions and surveillance protocols traditionally discourage routine immunization. Recent commercial development activity illustrates this direction. In December 2024, DABACO Vietnam Group Joint Stock Company initiated a commercial development agreement for a FlagT4Gv live attenuated DIVA-compatible marker CSF vaccine alongside an associated ELISA test, working in coordination with USDA ARS. This type of partnership signals a shift from vaccine-only commercial models toward integrated solutions that pair immunization with companion diagnostics. For manufacturers, this creates two paths to value: developing or licensing DIVA-compatible candidates, and building the diagnostic ecosystem relationships necessary for field adoption.
Regulatory environment and emergency-use frameworks. Regulatory decisions are shaping competitive access as much as product science. The CP7_E2alf chimeric pestivirus vaccine was licensed by the European Medicines Agency for emergency vaccination under a specific marketing authorization, a decision that institutionalized emergency vaccination as a realistic option within EU frameworks rather than a theoretical contingency. This kind of authorization does not simply expand the addressable market; it changes procurement planning, stockpiling expectations, and the commercial logic of regional supply commitments. At the same time, production platforms continue to evolve under guidance frameworks such as WOAH terrestrial animal health standards, which outline requirements for conventional MLV production methods as well as insect-cell baculovirus systems used in certain marker vaccine production. The practical implication is that regulatory alignment is becoming a competitive moat. Companies that can demonstrate consistent compliance, clear differentiation pathways, and emergency-use readiness will gain preferential access in policy-sensitive procurement cycles.
Demand-side changes in animal protein systems. The pandemic-era stress on global protein supply chains accelerated a broader recognition of livestock health as a strategic input rather than a peripheral operational concern. Biosecurity investment, surveillance expansion, and vaccination readiness are increasingly treated as integral to supply assurance. This shift supports steady demand growth for CSF vaccines, especially in regions where production intensification is increasing the economic cost of disease outbreaks. Importantly, demand is not homogenous. In some markets, producers and government buyers are prioritizing vaccines that minimize trade disruption risk; in others, the priority is cost-effective routine protection. Manufacturers that segment their go-to-market strategy by risk profile rather than treating the market as a single demand pool will extract more value from the same growth curve.
Supply chain and cost-structure evolution. Manufacturing economics for CSF vaccines span a spectrum from traditional cell-culture or passage-based methods to more modern recombinant systems. Conventional MLV production involves variable seed-lot validation and processes that can create batch-to-batch consistency challenges and cost variability. Meanwhile, insect-cell baculovirus vector platforms, while technically more complex to establish, can reduce certain contamination risks and support more scalable production for specific recombinant antigens. The cost implications are not simply about unit price. They encompass validation overhead, regulatory documentation, raw material security, and the ability to respond to surge demand during outbreak events. Companies that invest in flexible manufacturing strategies and secure key inputs are better positioned to protect margins during demand spikes and avoid supply disruptions that erode customer confidence.
Competitive Positioning and Market Evolution
The competitive landscape for CSF vaccines is characterized by a small set of established players with distinct technological and geographic positioning, alongside emerging regional participants seeking to strengthen local supply security and differentiation capabilities.
Zoetis holds a recognizable commercial position through its production of Suvaxyn CSF Marker, a CP7_E2alf chimeric pestivirus vaccine designed for emergency vaccination use. The strategic significance of this offering lies in its alignment with regulatory authorization for emergency contexts and its marker-vaccine logic, which supports differentiation objectives. Zoetis's positioning suggests a commercial approach built around readiness, regulatory credibility, and integration with broader livestock health portfolios. In markets where emergency vaccination frameworks exist or are being evaluated, this type of product architecture provides a natural entry point for procurement discussions and stockpiling commitments.
Boehringer Ingelheim is associated with Ingelvac CSF MLV, a C-strain modified live virus vaccine aimed at use in endemic regions. This reflects a different strategic logic: durable, field-tested protection for areas where CSF pressure is persistent rather than episodic. The C-strain lineage has historical credibility, and its application in endemic settings positions the company in a demand environment driven by routine prevention and regional disease baselines. For competitors, this highlights the importance of understanding whether a given market's primary pull comes from emergency preparedness or endemic control, since the purchasing criteria, salesforce engagement model, and inventory planning requirements differ substantially between them.
DABACO Vietnam Group Joint Stock Company illustrates the rise of regional players pursuing differentiation through DIVA-compatible technology and international R&D collaboration. The December 2024 commercial development agreement for FlagT4Gv and its associated ELISA test, initiated with USDA ARS, reflects a strategy that blends local manufacturing or commercialization presence with scientifically credible external partnerships. Regional players can compete not only on price but on proximity to local disease ecology, faster response cycles, and alignment with national veterinary strategies. This creates pressure on global incumbents to reinforce the local relevance of their offerings, whether through localized production, tailored registration strategies, or partnerships that enhance surveillance and differentiation support.
The broader market trajectory appears to be moving toward selective consolidation on the commercial side alongside fragmentation in technology development. Registered, emergency-approved, or DIVA-compatible products provide clearer competitive differentiation than undifferentiated conventional vaccines in many procurement contexts. At the same time, new entrants and regional manufacturers can gain ground where local policy support, cost structure advantages, or collaboration with research institutions create a credible technical narrative. The likely outcome is not a single dominant technology standard but a layered market in which emergency-use marker vaccines, endemic MLV products, and next-generation recombinant or vector-based candidates each capture distinct segments of demand. Competition will increasingly revolve around ecosystem readiness: registration status, diagnostic compatibility, supply reliability, and the ability to respond to outbreak-driven procurement surges.
Where the Market Is Heading Over the Next 3–5 Years
Several forward-looking trends are emerging from the current data and development activity, each with clear commercial implications.
DIVA-compatible and diagnostic-integrated solutions will become more central to procurement decisions. As more regions explore or expand vaccination programs that must coexist with trade considerations and surveillance integrity, vaccines paired with validated companion diagnostics will carry an advantage. The commercial opportunity is twofold: vaccine suppliers can capture higher-value engagements by offering integrated solutions, and diagnostic partners can secure embedded demand through technology co-development. The risk is that adoption depends on regulatory endorsement of specific test-vaccine combinations, which can slow rollout if approvals are staggered or if validation requirements differ across markets. Companies should anticipate longer commercial launch cycles tied to paired validation rather than single-product registration alone.
Regional demand will increasingly be shaped by policy posture as much as disease prevalence. Markets where vaccination is formally integrated into contingency planning or endemic control schemes will exhibit steadier demand profiles and greater willingness to invest in differentiation-capable products. Conversely, markets that rely predominantly on stamping-out policies may experience more episodic, emergency-driven demand. Over the next few years, the commercial task is to monitor policy evolution closely and position supply commitments accordingly. The upside is that policy shifts toward vaccination acceptance can rapidly expand the addressable market in a given region; the downside is that procurement can be abrupt and volume commitments can fluctuate if policy is revised in response to outbreak outcomes or political pressures.
Manufacturing platform diversity will become a strategic differentiator rather than a technical detail. As procurement authorities place greater weight on supply reliability, batch consistency, and readiness for surge demand, platforms that can balance safety, scalability, and validation efficiency will be valued more highly. Insect-cell and other recombinant approaches may gain share where they align with differentiation objectives and regulatory expectations, while conventional platforms will continue to play a role in endemic settings where cost efficiency and historical acceptance remain paramount. The strategic risk here is investment timing: committing to a platform transition without clear regulatory or market pull can create stranded capability, while waiting too long can cede credibility in markets that increasingly reward modernized production narratives.
New regional entrants and partnership-based commercialization will intensify competitive pressure. The combination of local manufacturing ambitions, research institution collaboration, and regional disease expertise creates a pathway for credible competitors outside the established global tier. This does not necessarily imply global displacement of incumbents; more likely, it means regional share erosion in specific geographies unless incumbents reinforce local relevance, pricing architecture, and differentiation support. The commercial opportunity is for incumbents to complement global registration and portfolio strength with regional execution depth, and for newer entrants to use partnerships and differentiated product logic to build defensible positions.
Strategic Implications for Decision Makers
For vaccine manufacturers, the priority is to align product architecture with the differentiated demand the market is creating. This means evaluating whether current portfolios are sufficiently positioned for both emergency-use contexts and endemic routine protection, and whether the company has credible pathways to DIVA-compatible designs where that aligns with target markets. Manufacturers should also review manufacturing strategy through the lens of surge readiness and validation efficiency, since these factors increasingly influence procurement preference beyond unit cost alone. Where appropriate, diagnostic partnerships or co-development arrangements can strengthen the commercial proposition and open access to procurement processes that value integrated solutions.
For investors, the most relevant signals are regulatory authorization milestones, DIVA-compatible development activity, and regional policy shifts that change vaccination adoption posture. Revenue growth in this market is real, but it is unevenly distributed across technologies and regions, and it is sensitive to policy catalysts. Due diligence should therefore focus less on aggregate market size alone and more on which product categories and geographies are likely to capture disproportionate value in the forecast period. Particular attention should be paid to companies with credible differentiation capability, emergency-use alignment, and manufacturing strategies that can withstand demand volatility without compromising continuity.
Worldwide Waterfowl Vaccines Market
For procurement authorities and production operators, the strategic emphasis should be on matching vaccine selection to the operational and trade objectives of the region. Where differentiation capability and emergency readiness matter, marker or DIVA-compatible options and their associated diagnostic support should be evaluated alongside traditional MLV products. Where endemic control and cost efficiency dominate, conventional products may remain appropriate, but procurement planning should still account for validation requirements, supply reliability, and the possibility of policy shifts that change the relative attractiveness of different vaccine types. Long-term contracts, stockpiling considerations, and supplier diversification should be shaped by the region's expected disease and policy trajectory rather than short-term price comparisons alone.
PW Consulting
The CSF vaccine market is expanding, but the value within that expansion is unevenly distributed across technologies, regulatory contexts, and regional demand profiles. Companies and investors that treat the market as a set of differentiated opportunity pockets—rather than a uniform growth story—will be better positioned to act on the right opportunities with the right timing. For decision makers seeking a deeper breakdown of segment dynamics, regional variation, and company-level strategic positioning, the full PW Consulting report provides the detailed segmentation data and customized scenario analysis needed to translate these trends into executable plans.
For detailed analysis of this topic, please visit the official page: Classical Swine Fever Vaccines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com