

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Automotive Power Liftgate Market: Why 7.6% CAGR Reshapes Competition by 2032

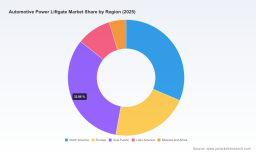
Strategic Trends & Commercial Opportunities in the Automotive Power Liftgate Market
Market Trajectory: Growth, Structure, and Inflection Points
The automotive power liftgate market has entered a sustained expansion phase, transitioning from a premium convenience feature to a mainstream closure solution across multiple vehicle segments. Between 2020 and 2025, global market revenue climbed from approximately $163.15 million to $215.0 million, reflecting a compound annual growth rate (CAGR) of 7.6% projected through 2032. By the end of the forecast window, revenue is expected to surpass $344.8 million, signaling that power liftgate adoption is no longer confined to high-end SUV or crossover trims. The growth trajectory underscores a structural shift in how automakers approach rear and tailgate closure architectures: electrification of actuation, tighter integration with body electronics, and a growing emphasis on weight reduction and packaging efficiency.
Despite the positive trajectory, the market faces several critical challenges that will shape competitive outcomes over the next three to five years. First, supply chain volatility for critical raw materials introduces cost and production risk. Rare-earth magnet supply concentration in China affects permanent-magnet motor production used in power liftgate actuators, while copper price volatility directly impacts motor winding costs in brushless DC motor-driven spindle actuators. These input cost pressures compress margins for suppliers who lack multi-source strategies or material substitution capabilities. Second, regulatory and safety expectations are tightening. Safety regulations for power liftgate systems emphasize anti-pinch protection and integrated sensors for reliable operation across temperature ranges, and EU and global vehicle safety standards drive demand for energy-efficient electric actuation compatible with 48V/12V platforms. Compliance is no longer a baseline checkbox; it is becoming a differentiator that influences OEM platform decisions. Third, the market remains moderately fragmented, with a CR3 of 24.6% and CR5 of 26.2%, indicating that scale alone does not guarantee leadership. Suppliers that win are those offering validated system-level integration, not just discrete components.
PW Consulting
Key Drivers Reshaping the Power Liftgate Market
Electrification and actuator efficiency. The shift toward electrified closure systems is a primary growth engine. Brushless DC motor designs with high torque-density and position-controlled architectures are replacing simpler DC solutions in premium and high-volume applications. These designs improve reliability, reduce noise, and enable finer control over closing speed and pinch mitigation. At the same time, the market is seeing a move toward lightweight thermoplastic and composite solutions that reduce mass relative to conventional metal architectures. For EV programs, even modest weight savings at the rear closure contribute to range and packaging objectives, making liftgate design part of a broader vehicle efficiency equation rather than an isolated convenience feature.
Automotive Power Window Motor Market
Safety regulation and functional integration. Regulatory pressure is accelerating the convergence of actuation, sensing, and body electronics. Anti-pinch protection, occupant detection, and reliable operation across temperature extremes are increasingly expected as standard capabilities. This creates a demand pull for suppliers that can deliver integrated control electronics, proximity sensing, and fail-safe motor control within a single validated module. The practical effect is a move away from decentralized, component-level sourcing toward system-level partnerships where the supplier takes greater responsibility for functional safety, diagnostics, and calibration.
Consumer expectations and commercial use cases. On the demand side, power liftgates have become a decisive purchase attribute for passenger cars, particularly in segments where cargo utility and hands-free operation matter. In commercial vehicles, the value proposition shifts toward durability, repeated cycle reliability, and integration with fleet telematics or access control. The combined effect is broader demand across both passenger cars and commercial vehicles, with passenger car applications driving volume growth and commercial applications reinforcing the need for ruggedized designs and higher duty-cycle validation.
Supply chain reconfiguration and cost structure. Cost and resilience are increasingly intertwined. Suppliers are responding to raw material exposure by diversifying magnet sourcing, optimizing winding designs, and increasing the share of applications using composite or thermoplastic structures that reduce reliance on heavier metal stampings. At the same time, regional manufacturing footprints and local content expectations are reshaping sourcing strategies. The companies best positioned to protect margins are those that combine design flexibility with disciplined procurement and the ability to offer platform-sharing architectures across multiple OEM programs.
Competitive Landscape: Differentiation, Positioning, and Evolution
The competitive environment is defined by specialists and system integrators operating at different levels of the value chain. Brose Fahrzeugteile SE & Co. KG has reinforced its system-level positioning through concepts that combine ultra-wideband positioning and radar for automatic tailgate activation and occupant detection, illustrating a move toward contactless, context-aware closure experiences. Aisin Corporation continues to emphasize actuator and control electronics optimized for body closure in Asian OEM programs, where proximity sensors and integrated control strategies support high-volume, cost-sensitive applications. Magna International Inc. is advancing lightweight thermoplastic liftgate solutions that are materially lighter than conventional steel components, directly addressing EV efficiency and packaging constraints while offering a broader system module including electric actuators, hands-free detection, and integrated ECU.
Continental AG focuses on power closure systems, actuators, and anti-pinch motor control integrated with body electronics, aligning with the regulatory and functional safety trend. Huf Hulsbeck & Fürst GmbH & Co. KG brings strength in tailgate latches, actuators, and strikers with integrated closing functions and external actuator variants for reliable operation, which is especially relevant where latch integrity and serviceability are priorities. Stabilus GmbH differentiates through electric liftgate drive systems that combine gas-spring assistance with electromechanical actuation and position control, a hybrid approach that can balance force, stroke, and packaging demands. HI-LEX Corporation contributes power liftgate actuators and related electromechanical components for vehicle tailgates, often supporting suppliers and OEMs that require component-level flexibility. Strattec Security Corporation extends into power access systems including actuators, latches, and security modules integrated with vehicle access, opening adjacency opportunities where closure and access control converge. Johnson Electric Holdings Limited offers brushless DC motor and actuator assemblies with high torque-density and position-controlled designs, reinforcing the broader industry shift toward efficient, controllable actuation.
The market is evolving along two simultaneous paths: consolidation at the system level and specialization at the component level. Larger suppliers are expanding from actuation into full closure modules that span mechanics, electronics, sensing, and software integration. At the same time, smaller entrants and component specialists remain relevant where OEMs seek cost-optimized elements, regional supply support, or alternative architectural approaches. The strategic implication is that positioning matters more than scale alone. Suppliers that can articulate a clear system architecture, demonstrate validation rigor, and reduce integration risk for OEMs are gaining disproportionate influence in platform decisions.
Forward-Looking Trends and Commercial Implications
Trend 1: From liftgate actuation to intelligent closure experiences. Over the next three to five years, power liftgates will increasingly be evaluated as part of a broader closure and access experience rather than as a standalone motorized mechanism. Contactless activation, occupant detection, adaptive closing behavior, and integration with vehicle access ecosystems will move from premium niches toward broader deployment. The commercial opportunity lies in suppliers and OEMs that can bundle actuation with sensing, control software, and validation support, reducing the integration burden for vehicle programs. The main risk is that feature creep raises cost and complexity faster than consumers are willing to pay, especially in price-sensitive segments.
Trend 2: Lightweighting as a strategic necessity, not an option. Weight reduction will continue to gain priority as EV range, packaging, and platform sharing become more central to vehicle economics. Thermoplastic and composite liftgate solutions, along with refined metal architectures, will compete on a program-by-program basis. Suppliers that can deliver repeatable weight savings without compromising durability, safety, or repairability will find expanded relevance across both passenger and commercial platforms. The uncertainty here is material cost and long-term durability validation, particularly where novel structures interact with crash, latch, and environmental requirements.
Trend 3: Supply resilience and material strategy as competitive levers. Input cost exposure will remain a central management challenge. Rare-earth magnet concentration and copper volatility will continue to influence actuator cost structures, making material strategy, multi-source procurement, and design flexibility critical capabilities. Companies that can offer design variants, alternative magnet strategies, or architectures that reduce sensitivity to a single commodity will enjoy stronger negotiating position and more stable margin profiles. The risk is that supply disruptions or trade dynamics compress available options and lengthen qualification cycles for alternative materials.
Strategic Implications for Decision Makers
For component and system suppliers. Positioning should emphasize validated integration rather than discrete component performance alone. The most defensible value proposition combines actuator efficiency, anti-pinch and sensor integration, lightweight material options, and platform-sharing architectures that reduce OEM engineering burden. Suppliers should also treat raw material exposure as a design problem, not only a procurement problem, by developing actuator and latch variants that can adapt to magnet and copper cost dynamics without sacrificing functional performance.
Electric Tailgate Radar Market
For investors. The market’s 7.6% CAGR through 2032 suggests durable growth, but returns will likely accrue to companies with differentiated system capabilities, cost-resilient supply chains, and exposure to both passenger and commercial demand. Investment theses should weigh not only revenue momentum but also the ability to capture value from lightweighting, functional integration, and access-control adjacencies. Companies that remain dependent on a single commodity-intensive actuator architecture or a narrow OEM base carry higher sensitivity to input costs and program concentration.
For procurement and OEM strategy teams. Sourcing decisions should balance short-term cost against integration risk and compliance readiness. As safety expectations around anti-pinch protection, sensor reliability across temperature ranges, and energy-efficient actuation increase, qualification speed and documentation rigor become as important as unit pricing. Multi-source strategies, where feasible, and clear material substitution pathways can reduce exposure to magnet and copper volatility while preserving program timing.
The broader opportunity is to treat the power liftgate not as a late-stage convenience add-on, but as an integrated closure system that contributes to vehicle efficiency, safety compliance, and user experience. Achieving that shift requires timely insight into where material strategies, regulatory expectations, and OEM platform priorities are converging. For leaders who need deeper segment-level data, regional demand patterns, and customized scenario planning, PW Consulting’s full Automotive Power Liftgate Market research report provides the granular breakdowns and strategic frameworks needed to translate market momentum into concrete program and investment decisions.
For detailed analysis of this topic, please visit the official page: Automotive Power Liftgate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com