

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
QSR IT Market to Hit $72.96B by 2032: 9% CAGR Reveals What||=0.0

The Quick Service Restaurant IT Market: Strategic Shifts and Commercial Opportunities in a High-Growth Landscape
The Quick Service Restaurant (QSR) IT market has evolved from a back-office support function into a central growth engine. Between 2020 and 2025, the segment expanded from a 25.94 billion valuation to approximately 39.91 billion, reflecting a compound annual growth rate of 9.0 percent through the 2026–2032 forecast horizon. By 2032, the market is projected to surpass 72.96 billion, signaling sustained momentum rather than a cyclical peak. This trajectory is not driven by uniform expansion across all players. Instead, it reflects a structural realignment where technology, operational efficiency, and consumer expectations converge to redefine how QSR brands operate, compete, and scale.
At its core, the market sits at a transition point. Legacy point-of-sale systems are giving way to cloud-native architectures, fragmented toolchains are being consolidated into integrated platforms, and data is shifting from a reporting artifact to a real-time decision utility. The growth rate itself tells a story: it is fast enough to attract serious capital and competitor attention, but nuanced enough that success depends on execution quality, not merely market timing. For executives and investors, the imperative is to understand where the value is being created, who is capturing it, and what forces will shape the next phase of expansion.
The current landscape is characterized by a relatively open competitive field. Concentration metrics indicate that the top three players account for roughly 20.0 percent of total revenue, while the top five represent approximately 25.0 percent. This suggests a market that is still diversifying rather than ossified around a few dominant incumbents. The implication is straightforward: scale advantages exist, but they are not insurmountable. Companies that can deliver differentiated functionality, reliable integration, and clear total cost of ownership are finding room to grow. The question for decision-makers is no longer whether to invest in QSR IT, but how to align investments with the operational realities of high-volume, speed-driven environments.
Market Snapshot: Scale, Trajectory, and What the Numbers Mean
Macro Growth and Structural Momentum
The market’s expansion from 2020 through 2025 was not a straight line. Growth accelerated during periods of digital adoption pressure and moderated when operational budgets tightened. The 9.0 percent compound annual growth rate projected through 2032 reflects a market that has internalized technology adoption as a baseline expectation rather than a discretionary upgrade. This pace is meaningful because it compresses planning cycles. Manufacturers, software vendors, and service providers must anticipate demand shifts faster, while operators face shorter windows to evaluate, deploy, and derive value from new systems before the next wave of innovation arrives.
Revenue composition across hardware, software, and services indicates that no single component dominates the value pool. Hardware remains a substantial portion of the market, reflecting the continued need for terminals, kiosks, and display infrastructure. Software represents a comparably large share, underscoring the shift toward licensing, analytics, and integrated management capabilities. Services, while smaller in relative terms, play a critical role in implementation, customization, and ongoing optimization. The balance among these categories matters because it signals where margin profiles, renewal dynamics, and customer retention pressures differ. Hardware deployments often anchor long-term relationships, software introduces recurring revenue and upgrade cycles, and services tie value to operational outcomes rather than transactional sales.
Fast-casual Dining Market
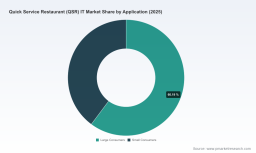
Application-level demand also reveals a bifurcated but balanced base. Large-scale consumers represent a significant share of market activity, reflecting the needs of multi-unit brands that prioritize standardization, centralized reporting, and cross-location scalability. Smaller consumers account for a substantial portion as well, driven by independent operators and emerging chains that seek affordable, modular solutions without sacrificing core functionality. This split is strategically important. It means the market is not a single use case waiting for a uniform solution. Instead, it demands flexible architectures that can serve enterprise standardization and small-operator agility without forcing either segment into an ill-fitting model.
Core Challenges and Inflection Points
Integration Complexity and Operational Friction
One of the most persistent challenges in the QSR IT market is integration complexity. Many operators still rely on a patchwork of systems for ordering, payments, kitchen display, inventory, labor scheduling, and analytics. The promise of a unified platform is compelling, but the reality of deployment often introduces friction: data reconciliation between legacy and new systems, workflow redesign for staff, and change management across locations with varying levels of digital maturity. The operational risk is not just technical downtime. It is degraded throughput during transition periods, inconsistent customer experiences, and uncertainty about whether new tools will actually reduce labor intensity or simply add administrative overhead.
This challenge creates a clear inflection point. Vendors that can reduce deployment risk, provide proven migration paths, and demonstrate measurable improvements in throughput and error rates are positioned to win more decisive adoption. Conversely, solutions that overpromise on seamless unification without accounting for real-world operational variability face higher resistance from operators who cannot afford prolonged disruption. For decision-makers, the practical question is how to balance ambition with execution certainty: which capabilities can be standardized immediately, which require phased rollout, and how to measure success beyond go-live dates.
Cost Pressure and Margin Discipline
Operational cost pressure is another defining constraint. Labor availability, wage dynamics, and throughput expectations continue to shape how QSR brands think about technology investments. At the same time, upstream cost dynamics can affect suppliers and ultimately influence menu pricing and margin structures. Industry commentary has highlighted that tariff exposure on imported goods could raise input costs for QSR suppliers, prompting supply-chain adaptations and, in some cases, potential price adjustments passed through to customers. These pressures do not diminish the case for technology. They sharpen it. When margins are tight, the value of technology shifts from convenience to efficiency: reducing waste, improving order accuracy, optimizing labor allocation, and enabling faster decision cycles.
The inflection here is subtle but important. Technology is increasingly evaluated not as a separate line item but as a lever within a broader cost and throughput strategy. Solutions that can tie directly to labor productivity, inventory accuracy, or order velocity are more defensible in budget conversations than abstract digital transformation narratives. For investors and operators alike, this means the most durable demand is likely to come from tools that demonstrate measurable operational impact rather than incremental feature enhancement.
Skill Gaps and Change Management
A third challenge is the human dimension of technology adoption. Even well-designed systems depend on staff proficiency, manager oversight, and consistent usage patterns. QSR environments are high-pressure, turnover-prone, and operationally intense. Systems that require extensive training, complex manual steps, or frequent troubleshooting can underperform in practice regardless of their technical sophistication. This reality places a premium on usability, role-based design, and support models that extend beyond initial installation.
The strategic implication is that vendors and operators must treat change management as part of the product experience. Deployment success increasingly depends on how well a solution fits frontline workflows, how quickly staff can reach competence, and how effectively managers can interpret system outputs without adding administrative burden. In this sense, the market is rewarding solutions that reduce cognitive load and operational ambiguity, not just those that add capability.
Key Drivers Shaping the Market
Technological Innovation and AI-Enabled Operations
Technology innovation remains the most visible driver of market growth, with artificial intelligence emerging as a central theme. AI adoption in the QSR segment is expected to accelerate, driven by needs around order accuracy, voice-based ordering, demand forecasting, and operational automation. The appeal is straightforward: in high-volume environments, small improvements in order handling and throughput compound quickly into meaningful gains in revenue protection and labor efficiency. AI voice ordering, for example, can help manage demand spikes, reduce missed or misheard orders, and free staff to focus on fulfillment and service quality. Analytics and operational intelligence can improve inventory planning, labor scheduling, and menu performance tracking, giving managers more precise inputs for day-to-day decisions.
A concrete example of this trajectory is the recent launch by Toast of a unified enterprise drive-thru platform that integrates POS, kitchen display, digital menu boards, and AI voice ordering with the aim of optimizing QSR throughput. This type of release matters because it reflects a shift from isolated tools to coordinated workflows. The strategic value is not simply the presence of AI. It is the integration of AI into a system where order capture, kitchen execution, and customer-facing display operate as one flow. For operators, this reduces handoff friction. For vendors, it raises the bar on platform coherence and real-world performance.
Demand-Side Changes and Consumer Expectations
Consumer expectations continue to reshape QSR operations. Speed, convenience, and consistency are baseline demands, but they are increasingly supplemented by expectations around personalization, mobile engagement, and frictionless payment. Digital ordering, curbside pickup, and self-service options are no longer niche offerings. They are part of the service architecture that determines perceived value and repeat behavior. As these channels expand, the IT stack must support order routing, inventory visibility, payment flexibility, and loyalty integration without creating inconsistency across channels.
This demand-side shift also influences how brands think about data. When ordering happens across multiple touchpoints, the opportunity is not just to process transactions but to connect them into a coherent view of customer behavior and operational performance. That connection enables better promotion targeting, more accurate demand signals, and tighter alignment between sales channels and kitchen capacity. The commercial implication is that QSR IT is becoming a differentiation layer, not just a transaction layer. Brands that can orchestrate channels efficiently while maintaining speed and consistency are better positioned to defend share in competitive corridors.
Supply Chain, Cost Structure, and Regulatory Context
Supply chain and cost structure dynamics are increasingly intertwined with technology decisions. Tariff-related pressures on imported goods have been noted as a factor that could increase operational costs for QSR suppliers and contribute to broader input cost challenges. While the direct impact varies by supplier and product category, the broader signal is that cost volatility is a persistent consideration. In that environment, technology investments are evaluated for their ability to offset pressure through efficiency, waste reduction, and more precise inventory and labor management.
Regulatory and industry context also contributes to the pace of change. Expert commentary from the restaurant sector indicates that AI adoption in QSR is expected to accelerate, reflecting both competitive pressure and operational necessity. At the same time, the environment is not static. Cost inputs, labor conditions, and consumer behavior all create uncertainty that makes flexibility and scalability important purchase criteria. This reinforces a broader trend: the market is rewarding solutions that are adaptable across locations and resilient to changing cost and demand conditions, rather than solutions optimized for a single idealized operating model.
Competitive Landscape and Leading Strategies
Positioning Among Core Participants
The competitive field includes a mix of platform-focused vendors, hardware specialists, and enterprise-oriented providers. Toast stands out for its all-in-one cloud-based POS and restaurant management orientation, with capabilities that span drive-thru, AI voice ordering, and analytics tailored to high-volume QSR operations. Its recent enterprise drive-thru launch highlights a strategy centered on throughput optimization and integrated order flow. Square approaches the market with a cloud-native restaurant POS built around mobile ordering, inventory management, and curbside solutions, emphasizing speed and multi-location scalability. This positions Square around flexibility and growth-oriented deployment, particularly for operators that value rapid expansion and modular functionality.
Elo Touch Solutions takes a hardware-focused angle, offering customizable QSR POS systems, kiosks, and digital menu boards that connect order processing with inventory integration. Its relevance lies in the physical interaction layer: terminals, kiosks, and displays remain essential in many QSR environments, and hardware differentiation can influence throughput, durability, and customer experience. PAR Technology Corporation operates with an enterprise hospitality orientation, bringing together POS, scheduling, and operational intelligence for multi-unit QSR brands. Its value proposition centers on unification across locations and operational oversight, which appeals to brands managing complex field operations. Oracle brings a broader hospitality and food-and-beverage footprint, with POS capabilities that include mobile order and pay, analytics, and back-office integration. Its positioning reflects the ability to serve QSR and wider hospitality needs within a more extensive technology ecosystem. NCR Voyix focuses on unified-commerce POS for restaurants, including self-checkout and payments, with an emphasis on QSR efficiency and growth. Its strategy aligns with the broader movement toward combined ordering, payment, and service flows that reduce friction at the point of interaction.
Differentiation and Strategic Themes
Across these participants, several strategic themes emerge. One is integration depth. The most compelling offerings are those that reduce the number of disconnected systems an operator must manage and make data flow more naturally between front-of-house, back-of-house, and management functions. Another is scalability. Multi-unit brands need solutions that can standardize operations without eliminating local flexibility, and they need reporting and control mechanisms that work across locations without excessive customization. A third theme is operational intelligence. Analytics and management insights are increasingly expected to be part of the platform rather than a separate add-on, because they connect technology investment to measurable performance outcomes.
Differentiation also comes from deployment and support models. In a market where integration complexity and change management are real risks, vendors that provide smoother onboarding, clearer operational fit, and reliable ongoing support can create meaningful distance from competitors with similar feature sets. This is especially true for high-volume QSR environments, where even small usability issues can affect throughput and staff adoption. The strategic lesson is that functionality alone does not determine winner status. Execution quality, integration reliability, and total cost of ownership often matter more in sustained adoption.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market structure suggests continued evolution rather than early consolidation. With top-three and top-five concentration levels still moderate, there is room for both consolidation and specialization. Larger platforms may pursue breadth by adding capabilities across ordering, payments, kitchen operations, and analytics. Smaller or niche players may pursue depth in specific workflows, hardware categories, or regional deployment models. New entrants can still gain traction by addressing underserved needs, such as particular hardware configurations, vertical-specific workflows, or more affordable entry points for smaller operators.
At the same time, the risk of fragmentation is real. If operators accumulate overlapping tools in pursuit of best-of-breed functionality, they may face higher integration costs and weaker data coherence. This creates pressure for platforms that can balance breadth with usability. The likely outcome is a competitive environment where success depends on the ability to deliver a coherent experience across the stack, while still allowing flexibility for local operational needs. For executives evaluating vendors, the key is to assess not only what a platform can do in isolation, but how well it reduces complexity across the broader system of operations.
Future Outlook: Trends and Commercial Implications
Trend One: Unified, Throughput-Oriented Platforms
Over the next three to five years, one of the clearest trends is likely to be the continued shift toward unified platforms designed around throughput and order flow. In QSR, speed and accuracy are not marginal improvements; they are core to revenue protection and customer satisfaction. Platforms that coordinate ordering, kitchen execution, display, payments, and basic analytics within a connected workflow will have a structural advantage because they reduce handoffs and operational ambiguity. The commercial opportunity here is for vendors that can prove end-to-end impact rather than isolated feature value, and for operators that can standardize high-impact workflows without over-customizing to the point of fragility.
PW Consulting
The associated risk is over-engineering. Not every location needs the same level of automation or the same integration depth. If platforms become too rigid, they may struggle with diverse store formats, varying labor models, and local market differences. The winners will likely be those that offer strong core workflows while allowing controlled adaptation at the edges.
Trend Two: AI and Operational Intelligence as Standard Capabilities
AI and operational intelligence are likely to become standard expectations rather than differentiators in every category. Voice ordering, demand forecasting, labor optimization, and anomaly detection can improve throughput and reduce costly errors when applied well. As adoption accelerates, the differentiator will shift from whether a system includes AI to how reliably it performs in live conditions and how usable its outputs are for managers and staff. The commercial implication is that vendors will need to demonstrate robustness, transparency, and practical value, while operators will need to build internal capability to act on system-generated insights.
A key uncertainty is the pace and shape of AI value realization. Adoption may outpace the ability to integrate AI outputs into daily workflows, leading to underutilization or skepticism if results are inconsistent. In that scenario, the market may reward pragmatic deployments that solve specific operational problems over broad promises of intelligence. Decision-makers should therefore treat AI as an operational tool with measurable endpoints, not as a blanket upgrade.
Trend Three: Cost-Efficiency-Led Adoption and Flexible Architectures
Cost pressure and input volatility are likely to reinforce efficiency-led adoption. Technology purchases will increasingly be justified through labor productivity, waste reduction, order accuracy, and inventory control. This trend favors flexible architectures that can be deployed in phases, scaled across locations, and aligned with operational priorities instead of requiring full transformation upfront. The commercial opportunity is for solutions that can show a clear path from installation to measurable efficiency gains, and for buyers who structure deployments around high-return workflows first.
The related risk is that cost pressure may also delay adoption if returns are unclear or if implementation disruption is perceived as too high. In that environment, vendor credibility, referenceable outcomes, and low-friction rollout become critical. The market may divided between players who can evidence value quickly and those who rely on longer, less certain transformation narratives.
Strategic Implications for Decision-Makers
For Manufacturers and Technology Providers
Focus on workflow coherence and deployment confidence. In a market where integration complexity and change management are persistent barriers, the most defensible position is a solution that fits frontline operations, supports smooth migration, and delivers measurable throughput or efficiency gains. Product roadmaps should prioritize integration depth, role-based usability, and support models that reduce post-deployment friction. Where AI is involved, emphasize reliability, clear use cases, and manager-friendly outputs rather than broad claims of intelligence. Pricing and packaging should reflect the reality that operators evaluate total cost of ownership, not just upfront capability.
Worldwide Information Technology Market
For Investors
Evaluate market positions through the lens of scale, repeatability, and operational proof. The moderate concentration structure suggests room for differentiation, but durable advantage will likely come from platforms that can standardize across locations while maintaining flexibility, and from vendors that can evidence efficiency outcomes in high-volume environments. Pay attention to recurring revenue quality, renewal dynamics, and the ability to expand within existing accounts through additional modules or locations. Also consider exposure to cost and supply-chain volatility, since margin pressure can influence both adoption timing and vendor selection. The strongest investment theses are likely to be tied to platforms that reduce operational risk and demonstrate clear payback paths.
For Procurement and Operator Decision-Makers
Prioritize solutions that align with the highest-impact operational constraints in your environment. Start with workflows where technology can directly improve speed, accuracy, labor utilization, or inventory control, and sequence rollouts to limit disruption. Evaluate vendors on integration reliability, support responsiveness, and the usability of their systems for frontline staff and managers, not just on feature count. Where possible, structure deployments to generate visible operational improvements early, because early wins build internal confidence and support broader adoption. Given the pace of change and the range of vendor strategies, timely access to detailed segmentation data, vendor comparisons, and deployment benchmarks can materially improve decision quality. Detailed research that breaks down sub-segment dynamics and tailored implementation considerations can help ensure that procurement choices match both immediate operational needs and longer-term scalability goals.
The QSR IT market is expanding at a pace that rewards focused strategy. The winners in the next phase will likely be those who treat technology as an integrated operating capability, align investments with measurable efficiency outcomes, and build for flexibility in a cost-conscious, speed-driven environment. For organizations navigating this landscape, the most valuable next step is to ground decisions in detailed, segment-specific intelligence that connects market dynamics to concrete operational choices.
For detailed analysis of this topic, please visit the official page: Quick Service Restaurant (QSR) IT Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com