

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Embolization Particle Market: Why 9.8% CAGR and the Oncology Shift Redefine Growth to 2032

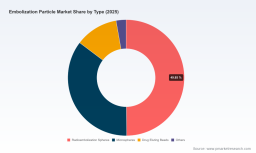
The Embolization Particle Market: Strategic Trends and Commercial Opportunities Through 2032
The embolization particle market has entered a phase of sustained expansion, transitioning from a niche interventional toolkit component to a core growth vector within the broader medical device economy. Between 2020 and 2025, global revenue climbed from approximately 1.83 billion USD to 2.88 billion USD, reflecting consistent year-over-year gains driven by procedural volume growth, product refinement, and expanding clinical indications. The trajectory is expected to continue through 2032, with the market projected to reach roughly 5.51 billion USD. This growth path translates to a compound annual growth rate of 9.8 percent across the 2026–2032 forecast window. Such momentum is not accidental; it reflects converging forces in oncology procedural adoption, interventional radiology workflow optimization, and gradual geographic penetration beyond mature markets. For decision makers evaluating capital allocation, product strategy, or procurement roadmaps, the market now rewards those who understand where innovation is compounding, which segments are maturing, and where regulatory and reimbursement dynamics are shifting the competitive edge.
Behind the headline numbers lies a market with notable structural complexity. Revenue distribution is not uniform across procedures or geographies. Oncology applications command the largest share of demand, supported by the increasing use of embolotherapy as a bridge to surgery, a primary treatment in unresectable cases, and a complementary modality in combination regimens. Uterine fibroid embolization and peripheral vascular disease applications continue to anchor steady procedural volumes, while newer indications remain in earlier stages of clinical and commercial validation. Regionally, established markets with mature interventional infrastructure and favorable reimbursement pathways account for the largest revenue pools, while faster-growing regions are expanding capacity through training programs, device localization, and increasing procedural throughput. The overall market concentration also signals that scale, clinical evidence, and regulatory execution remain decisive advantages for leading players, even as specialized entrants find room to compete in differentiated niches.
Key Structural Challenges and Inflection Points
Despite strong growth momentum, the market faces several challenges that can reshape competitive advantage over the next few years. First, clinical evidence requirements are intensifying. Purchasing committees and hospital formulary teams increasingly expect durable outcomes data, not just procedural feasibility. This shifts the basis of competition from device availability alone toward therapeutic performance, reproducibility, and post-market evidence accumulation. Manufacturers that can generate and communicate robust real-world outcomes are better positioned to defend pricing and expand share, while those relying on generic claims face growing scrutiny.
Second, regulatory and reimbursement alignment remains uneven across regions. A product that secures clearance or approval in one jurisdiction may still encounter prolonged adoption timelines elsewhere if reimbursement coding, coverage policy, or procurement rules do not keep pace. The gap between regulatory authorization and economic access can weaken commercial velocity, particularly for products entering smaller or cost-sensitive markets. For this reason, the most effective product strategies now integrate reimbursement planning early, rather than treating it as a downstream activity.
Third, the industry is seeing a shift in supply chain expectations around sterilization, biocompatibility, and consistency. Embolization particles must meet rigorous standards for safe delivery, predictable behavior, and reliable manufacturing quality. Because these products are used in high-stakes vascular procedures, even small inconsistencies can affect procedural confidence and hospital adoption. This elevates the importance of process control, documentation discipline, and regulatory readiness across the manufacturing footprint. Companies that treat these as strategic capabilities rather than operational overhead gain resilience in a market where trust is a core purchasing factor.
A further inflection point lies in the expanding role of embolotherapy in combination treatment pathways. As interventional and oncology teams coordinate care more closely, embolization particles are increasingly evaluated not only as standalone embolic tools but as components within broader treatment strategies. This creates both opportunity and complexity: product selection becomes more procedure- and patient-specific, and competitive differentiation increasingly depends on how well a device supports clinical workflow, imaging compatibility, and procedural flexibility.
Key Growth Drivers Reshaping the Market
Technology Innovation and Product Differentiation
Technology development continues to be one of the most visible drivers of market change. Embolization particles are evolving along several directions at once, including material composition, size distribution precision, delivery characteristics, and functional added value. Spherical embolic microspheres have gained prominence because their consistency can support more predictable occlusion and procedural control compared with irregular particle formats. At the same time, non-spherical polyvinyl alcohol-based options remain relevant where specific embolic behaviors are desired, particularly in arteriovenous malformations and certain hypervascular tumor applications. This diversity of product architecture means the market is not converging on a single format; instead, it is becoming more application-defined.
A second layer of innovation lies in drug-eluting and functionalized platforms. These systems are designed to combine local embolic effect with sustained therapeutic delivery, broadening their relevance in oncology and other targeted indications. Their adoption depends not only on device performance but also on the availability of supporting clinical evidence and procedural protocols. As clinicians gain more experience with these platforms, products that demonstrate reliable delivery, manageable handling, and consistent outcomes are likely to earn stronger preference in complex cases.
Worldwide Intracranial Embolization Coil Market
The third technology trend is the continuous refinement of resorbable and hydrogel-based materials. Fast-resorbable gelatin-based hydrophilic microspheres, for example, reflect an interest in temporary embolic effects for specific procedures such as musculoskeletal pain embolization. Such products illustrate a broader move toward matching material behavior to clinical intent rather than applying one embolic solution across all use cases. For manufacturers, this means product roadmaps increasingly need to balance material science, clinical use cases, and procedural ergonomics.
Policy and Regulatory Dynamics
Regulatory developments are acting as both gatekeepers and enablers. Approvals and clearances can unlock large demand pools quickly when they address high-impact indications. For example, recent authorization activity around Y-90 resin microspheres for unresectable hepatocellular carcinoma has highlighted the commercial importance of strong trial-supported indications in oncology. Similarly, 510(k) clearances for polyvinyl alcohol embolization microspheres used in arteriovenous malformations and hypervascular tumors demonstrate that incremental regulatory progress in conventional embolic categories still matters, particularly when it reinforces procedural versatility and hospital purchasing confidence.
At the same time, compliance expectations around sterilization, packaging, and labeling are increasingly scrutinized across jurisdictions. Products that are packaged dry and designed to meet recognized sterilization standards benefit from manufacturing predictability and regulatory clarity. This may appear technical, but it matters commercially because regulators, procurement teams, and hospital quality departments all rely on consistent documentation when evaluating suppliers for long-term use. In practice, regulatory readiness is becoming a differentiator that affects speed to market, cross-border expansion, and institutional trust.
Reimbursement and market access policies further shape adoption. Even when a device is clinically appropriate, hospitals and interventional centers move faster when reimbursement pathways are clear and aligned with the product’s intended use. Support resources tied to specific product applications can help shorten education and implementation cycles, especially for centers scaling up embolization procedures. As a result, companies that integrate reimbursement support, clinical education, and procedural training into their commercial model tend to achieve more dependable uptake than those that rely on product features alone.
Demand-Side Shifts in Clinical and Institutional Behavior
Demand is being reshaped by changes in how hospitals and procedural teams think about intervention. Interventional radiology and endovascular practices are increasingly focused on minimizing procedural variability, improving turnover, and maintaining consistent outcomes across operators. In that environment, products that provide predictable handling and repeatable performance become more valuable. The emphasis is moving from availability toward reliability and fit-for-purpose performance in specific procedures.
Procurement behavior is also evolving. Hospitals are paying closer attention to total procedural cost, not just device unit price. This includes factors such as preparation time, compatibility with existing delivery systems, waste reduction, and the breadth of procedures a product can support. Where a single product family can serve multiple use cases without compromising performance, it can simplify inventory management and reduce training burden. These operational considerations increasingly influence purchasing decisions alongside clinical factors.
Oncology demand remains a dominant driver, but it is changing in character. Embolization particles are being incorporated into more nuanced treatment pathways, including scenarios where local control is essential and where patient eligibility for surgery or systemic therapy is limited. That shift supports sustained growth in oncology volumes, but it also raises expectations for evidence, safety, and procedural integration. Similarly, uterine fibroid embolization and peripheral vascular disease applications continue to benefit from growing recognition of minimally invasive options, though growth in those areas depends on local clinical adoption patterns and reimbursement conditions.
Supply Chain and Cost Structure Pressures
Cost structure and supply chain resilience are increasingly important as the market expands. Manufacturing consistency, raw material availability, and sterilization logistics directly affect product reliability and commercial continuity. In a market where clinical trust depends on uniformity and quality, supply disruptions can have outsized consequences. This has raised interest in supply models that reduce risk through stable production processes, clear documentation, and well-managed distribution pathways.
Pricing dynamics are also shifting. In mature markets, hospitals are more likely to challenge recurring device spend, especially when multiple products appear clinically similar. In response, manufacturers can defend positions through clinical differentiation, service quality, and procedural support rather than broad price competition. In faster-growing regions, the pricing conversation may be more about access and scalability than about marginal cost reduction. Companies that manage both ends of this spectrum effectively are better positioned to capture regional growth without compromising margin integrity.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Key Players
The competitive field is anchored by a group of established manufacturers with strong product portfolios, regulatory assets, and procedural credibility. These companies compete on more than product features; they compete on evidence base, indication coverage, delivery system compatibility, and commercial support. Their strategies tend to emphasize one or more of the following: breadth across embolic formats, depth in a specialized indication, or capability in drug-eluting and functionalized platforms.
Merit Medical Systems, Inc. maintains a diversified embolization particle portfolio spanning irregularly shaped non-resorbable polyvinyl alcohol particles, sodium acrylate alcohol copolymer microspheres, spherical embolic microspheres positioned as a market leader in that category, and resorbable porcine gelatin for hypervascular tumors and bleeding control. This breadth allows the company to serve a wide procedural range, from arteriovenous malformations to hypervascular tumors, with multiple material options. Their profile suggests a strategy built on format flexibility and cross-application coverage, which can be attractive to centers seeking to standardize on fewer suppliers while still matching products to specific clinical scenarios.
Boston Scientific Corporation competes with a portfolio that includes polyvinyl alcohol embolization particles, hydrogel-based microspheres with Polyzene-F, and Y-90 resin microspheres for radioembolization. This combination supports both conventional embolic applications and specialized oncology radioembolization use cases. A notable advantage lies in combining procedural product lines with reimbursement-related educational resources that can support adoption in peripheral hepatic vascular tumor and uterine fibroid applications. For competitors and customers alike, this illustrates how commercial execution can hinge on pairing device capability with access support and procedural education.
Terumo Corporation emphasizes microspheres and drug-eluting platforms, with offerings that include PEG drug-eluting microspheres and hydrogel-based microspheres cleared in certain regions for hypervascular tumors and uterine fibroids. The strategic logic here is clear: by covering both standard embolic microspheres and drug-eluting options, the company can position for current procedural demand while participating in higher-complexity applications. In markets where clinicians are expanding indications and refining treatment pathways, such product alignment can translate into stronger institutional relationships and repeat usage.
Sirtex Medical Limited focuses strongly on radioembolization, particularly with Y-90 resin microspheres used in unresectable hepatocellular carcinoma. The company’s recent regulatory milestones illustrate the commercial power of indication-specific leadership. A recent FDA approval for unresectable HCC, supported by trial results showing high local tumor control and durable response duration, reinforces the value of evidence-led positioning in oncology. Alongside EU medical device regulation certification for delivery systems, this shows a strategy centered on regulatory and clinical credibility in a high-value therapeutic niche rather than broad product spread.
BTG plc, now integrated with the Boston Scientific portfolio, contributes legacy relevance through sulphonate-modified hydrogel microspheres. The broader trajectory here suggests that portfolio consolidation can strengthen commercialization while preserving specialized technology lines. Integration can streamline distribution, expand customer access, and reinforce clinical messaging, though it also requires careful management of brand continuity and procedural familiarity.
NextBioMedical Co., Ltd. represents a newer competitive presence with fast-resorbable gelatin-based hydrophilic microspheres. Recent Health Canada approval for musculoskeletal pain embolization shows how targeted regulatory success can open commercial entry in specific applications. For smaller or regionally focused players, the strategic play is often to compete where a well-defined clinical niche, clear regulatory pathway, and strong procedural alignment can outweigh the advantages of larger global portfolios.
Market Structure Evolution: Consolidation, Fragmentation, and New Entrants
The market is simultaneously experiencing consolidation benefits and niche fragmentation. Larger portfolios and integrated commercial models can reduce complexity for hospital buyers and improve access to broader procedural support. That favors incumbents with scale and established relationships. At the same time, fragmentation persists because embolization is not a single-use category with one optimal solution. Different applications, anatomical targets, and procedural preferences sustain demand for multiple embolic formats and material types. This creates openings for specialized entrants that can solve a specific clinical problem exceptionally well.
PW Consulting
New entrants are most likely to succeed when they pursue disciplined differentiation rather than broad me-too coverage. The recent approvals and clearances in both conventional PVA microspheres and Y-90 resin microspheres show that incremental innovation can still unlock commercial momentum if it addresses an unmet procedural need or strengthens evidence in a valuable indication. For the overall market, this means competitive intensity will likely remain high, but the winners will be those who combine product performance with regulatory clarity, reimbursement readiness, and credible procedural support.
Forward-Looking Trends and Commercial Implications (2026–2032)
Trend 1: Broader Oncology Integration and Evidence-Led Adoption
Oncology applications are expected to remain the largest demand anchor, but their commercial character will continue to shift. As embolotherapy becomes more embedded in combination treatment pathways, products will be evaluated more closely for local control capability, procedural compatibility, and durability of outcome. This trend favors companies that can support clinicians with evidence, training, and procedural guidance, not just device supply. For investors and manufacturers, it means that oncology growth will increasingly reward those who can translate trial strength and real-world performance into confident purchasing decisions. A risk here is that adoption may advance unevenly across regions if evidence expectations or reimbursement alignment lag.
Trend 2: Expanded Indications in Interventional Pain and Peripheral Applications
Beyond oncology, growth is likely to come from incremental indication expansion in areas such as uterine fibroid embolization, peripheral vascular disease, and musculoskeletal pain embolization. These applications can broaden addressable volume without requiring a complete overhaul of procedural infrastructure. The commercial opportunity lies in product-line extensions and application-specific positioning that match material behavior to clinical intent. For companies, the key is to avoid overextending into indications where clinical evidence or reimbursement support is premature. A realistic expansion strategy should prioritize indications with clear procedural fit and existing institutional demand. The uncertainty is that some newer applications may develop more slowly than anticipated if clinical adoption or payment pathways remain limited.
Trend 3: Regional Expansion with Increasingly Localized Competition
Revenue growth will continue to be supported by regional expansion, especially in markets where interventional capacity is increasing and procedural training is strengthening. However, the pattern of growth is expected to become more localized. As regional players secure approvals, build manufacturing and distribution capability, and tailor commercial support to local procurement realities, competition in emerging markets may intensify beyond the global incumbents. This suggests a future where global portfolio strength and local execution both matter. Manufacturers that can adapt reimbursement engagement, education, and supply strategy to regional conditions will have an advantage. The principal risk is that regional adoption curves may be slower or more policy-dependent than top-line growth projections imply, particularly where purchasing systems prioritize cost containment.
Commercial Opportunity Summary
- Products that align material behavior with clearly defined clinical use cases are likely to gain preference in complex or high-stakes procedures.
- Evidence generation and procedural education will increasingly influence share gains, especially in oncology.
- Reimbursement support and market access readiness will shape commercial velocity as much as regulatory clearance.
- Regional expansion will favor players who can combine global product credibility with localized commercial execution.
- Portfolio breadth can be valuable, but differentiation by application is becoming more important than undifferentiated coverage.
Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
Manufacturers should prioritize product strategy that connects material performance to procedural outcomes. Rather than expanding purely for breadth, companies should evaluate which indications offer the strongest combination of clinical demand, reimbursement feasibility, and differentiation potential. Investment in evidence generation, sterilization and quality documentation, and procedural training can strengthen competitive positions in ways that last longer than short-term promotional activity. For portfolios already spanning multiple embolic formats, the opportunity is to make each product’s clinical rationale explicit and defensible. For newer or narrower portfolios, the opportunity is to win in a specific application with clear regulatory and reimbursement alignment.
For Investors and Corporate Development Teams
Investors should assess both market momentum and competitive defensibility. The projected trajectory suggests continued value creation, but share will likely accrue to businesses that can sustain regulatory confidence, clinical credibility, and commercial support in high-value applications. M&A and partnership opportunities may emerge around specialized technology lines, regional access capabilities, or complementary product formats. Due diligence should focus on indication-level adoption dynamics, evidence readiness, supply resilience, and the extent to which a company’s strategy relies on broad coverage versus focused differentiation. Valuation scenarios should also account for the possibility that regional growth and reimbursement timelines are more variable than aggregate market growth implies.
For Procurement and Clinical Program Leaders
Procurement and clinical leaders should evaluate embolization products through a total-procedure lens. This includes not only unit cost but also consistency of performance, handling characteristics, compatibility with existing delivery workflows, and the breadth of procedures a product can reliably support. Supplier selection should weigh clinical evidence, regulatory status, sterilization and quality documentation, and the availability of procedural support resources. In programs where embolization volume is growing, standardization on products that reduce variability and training burden can improve operational efficiency. At the same time, maintaining flexibility for application-specific needs may be prudent where procedural diversity is high.
Why Detailed Intelligence Matters Now
The embolization particle market is expanding, but the forces shaping that expansion differ significantly by application, region, and product format. Aggregate growth figures provide direction, yet the operational and commercial decisions that determine success depend on more granular insight: which indications are gaining procedural traction fastest, where reimbursement alignment is accelerating adoption, how regulatory milestones are changing competitive positioning, and which product formats are becoming more or less differentiated over time. Decision makers who operate with detailed segmentation data, company-level competitive mapping, and indication-specific outlooks are better equipped to time investments, prioritize portfolios, and manage procurement risk.
Expandable Microspheres Market
For those seeking a more complete view, the full research report provides deeper segmentation detail, company-level competitive profiles, regional and application-level revenue estimates, and tailored strategic scenarios. The additional depth is especially useful for teams that need to evaluate entry timing, portfolio fit, pricing strategy, or regional expansion with more precision than a market overview can support.
For detailed analysis of this topic, please visit the official page: Embolization Particle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com