

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
MRAM Market Reaches $45B by 2032: The 38.97% CAGR Trajectory Explained

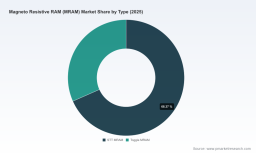
Magneto Resistive RAM (MRAM) Market: Strategic Trends and Commercial Opportunities
The global memory landscape is entering a decisive inflection point. Magnetic Resistive Random Access Memory (MRAM) has moved beyond niche experimentation to become a strategically critical non-volatile memory technology for applications demanding speed, endurance, and retention under harsh conditions. Revenue trajectories over the past half-decade tell a story of accelerating adoption: the market expanded from under one billion dollars in 2020 to approximately 4.49 billion dollars in 2025, and forward projections indicate sustained double-digit expansion through the end of the decade. The compound annual growth rate across the forecast horizon stands at roughly 38.97 percent, a pace that reflects both genuine technological maturation and broadening demand across mission-critical sectors. By 2032, market value is expected to approach 45 billion dollars, signaling a structural shift in how system architects balance performance, power, and reliability.
PW Consulting
Such growth is not merely a function of semiconductor cycle dynamics. MRAM occupies a unique position in the memory hierarchy, bridging gaps left by traditional flash, DRAM, and SRAM in specific use cases. The technology's ability to deliver non-volatility with near-SRAM speeds, combined with exceptional write endurance and temperature tolerance, has made it increasingly attractive for environments where data integrity cannot be compromised. Yet the path from rapid revenue expansion to sustained commercial dominance is neither linear nor guaranteed. Understanding the forces shaping this trajectory requires looking past headline numbers to the underlying technological, regulatory, and competitive dynamics that will determine which players capture value and which segments scale profitably.
Market Context and Structural Challenges
The current market environment reflects a technology transitioning from specialized deployment to broader architectural integration. Historically, MRAM found footholds in industrial, aerospace, and defense applications where radiation hardness, extreme temperature operation, and long-term data retention justified higher unit costs. That foundation remains intact, but the growth profile now reflects incremental penetration into adjacent markets where system designers are re-evaluating memory choices amid increasing performance and power constraints. The revenue curve's steepening over recent years indicates that design wins are compounding, manufacturing yields are improving, and integration pathways with existing semiconductor process flows are becoming more defined.
This momentum coexists with several structural challenges that will shape competitive outcomes over the next five years. First, the tension between density scaling and manufacturing complexity remains acute. MRAM fabrication relies on specialized magnetic materials, additional deposition and patterning steps, and tighter process tolerances than many conventional memory technologies. As manufacturers push toward higher-density arrays, maintaining uniform magnetic tunnel junction characteristics across large wafers becomes increasingly difficult, creating trade-offs between capacity, yield, and cost that cannot be solved through process optimization alone.
Second, qualification and reliability requirements continue to act as both a market enabler and a barrier. High-reliability applications demand documented performance under extreme thermal cycling, long-term retention guarantees, and adherence to automotive-grade qualification frameworks. These standards protect end customers but extend development timelines and raise the cost of market entry. The result is a market where incumbents with established qualification portfolios and application-specific reference designs hold meaningful advantages, while new entrants must navigate a multi-year pathway to prove suitability for safety-critical deployments.
Third, the market's current structure reflects a moderately consolidated landscape. A relatively small group of firms accounts for a substantial share of revenue, while the remainder is distributed across specialized players and emerging participants. This concentration creates both stability and friction: established players benefit from ongoing design wins and customer relationships, but the same dynamic can slow the diffusion of disruptive process innovations if incumbent architectures are optimized for existing product families rather than next-generation scaling pathways.
Key Drivers Shaping the Market Trajectory
The acceleration observed in recent years is not the product of a single catalyst. It emerges from the convergence of technological breakthroughs, evolving demand-side requirements, and shifting supply-side economics that together expand the addressable opportunity for MRAM.
Technical Innovation and Process Maturation form the foundation of current growth. Advances in magnetic tunnel junction design, particularly the transition toward perpendicular MTJ configurations and improvements in spin-transfer torque efficiency, have increased the feasibility of higher-density arrays while preserving the retention and endurance characteristics that define MRAM's value proposition. Incremental improvements in integration compatibility with standard CMOS flows reduce the friction of adoption for system manufacturers who cannot absorb highly customized fabrication requirements. Recent technical milestones illustrate this trajectory: one leading manufacturer achieved a Phase One milestone under a U.S. government-funded program by scaling magnetic cell geometry to enable higher-density space-grade MRAM, demonstrating that process innovation is increasingly oriented toward expanding density envelopes without abandoning reliability requirements.
Policy and Regulatory Environments are reshaping demand patterns in ways that directly favor non-volatile memory technologies with proven reliability profiles. National security priorities, industrial base resilience initiatives, and export control frameworks have heightened interest in domestic or allied supply chains for specialized semiconductor technologies. MRAM's relevance to defense, aerospace, and mission-critical infrastructure aligns with policy directions that emphasize secure, high-reliability components. This is visible in recent contract activity: a major MRAM developer secured a substantial subcontract with a U.S. prime contractor to support Toggle MRAM process technology and engineering services for Defense Industrial Base customers, reflecting how national security initiatives are translating into concrete demand signals for specialized memory capabilities.
Demand-Side Shifts in Application Architecture are expanding the contexts in which MRAM competes. In automotive systems, increasing electrification, advanced driver-assistance functionality, and connectivity requirements are pushing designers toward memory solutions that can operate reliably across wide temperature ranges while maintaining fast read/write performance. Validation activity underscores this momentum: MRAM products have been validated across multiple FPGA families for high-reliability configuration memory in industrial, aerospace, military, and automotive contexts, indicating that MRAM is being positioned not only as a standalone memory component but as an enabling element within broader system architectures. In aerospace and defense, the combination of radiation tolerance, extreme environment performance, and long data retention continues to drive adoption where alternative technologies struggle to meet qualification thresholds.
Supply Chain and Cost Structure Evolution remains a critical shaping force. The specialized materials and additional fabrication steps inherent to MRAM create cost structures that differ from mainstream memory categories. At lower volumes, these costs can limit price competitiveness in cost-sensitive markets. However, as process recipes mature, design wins accumulate, and manufacturing scale improves, the economic balance shifts. The challenge for manufacturers is to manage the intersection of yield, density, and qualification requirements in a way that preserves margin while expanding addressable volume. For customers, the decision increasingly comes down to total cost of ownership over the product lifecycle: MRAM's endurance, reduced risk of data loss, and suitability for harsh environments can offset higher upfront component costs in applications where failure is expensive or dangerous.
Static Random Access Memory (SRAM) Market
Competitive Landscape and Strategic Positioning
The MRAM market's competitive architecture reflects a blend of specialized incumbents, application-focused players, and selective government-driven demand that rewards proven reliability. Rather than competing solely on density or price, leading firms have built differentiation around process expertise, qualification track records, and deep integration with specific end-market requirements.
Everspin Technologies has established a prominent position as a developer and manufacturer of both discrete and embedded MRAM products, with a portfolio spanning Toggle MRAM, STT-MRAM, and advanced perpendicular MTJ-based variants. Its strategic emphasis on industrial IoT, data centers, automotive, aerospace, and mission-critical applications reflects a deliberate focus on markets where reliability and endurance justify the technology's adoption. The company's recent validation of its MRAM across FPGA families for high-reliability configuration memory, alongside a significant subcontract supporting U.S. Defense Industrial Base customers, illustrates how incumbents translate technical capability into commercial and programmatic momentum. The combination of design-in relationships, qualification documentation, and alignment with defense and industrial priorities gives such players a defensible position in segments where certification and trust matter as much as raw performance.
NVE Corporation occupies a more specialized niche, developing and licensing MRAM technology with emphasis on anti-tamper applications and spintronics-based solutions for low-bit-density, tamper-prevention use cases. This positioning reflects a different competitive logic: rather than competing in high-volume mainstream memory, the company focuses on specialized security-oriented applications where its technology's characteristics align with narrow but valuable requirements. In a market where many players chase density and volume, specialized security applications represent a reminder that differentiation can arise from application specificity as much as from process scale.
Avalanche Technology has focused on high-density STT-MRAM with spin-programmable perpendicular MTJ technology, targeting space-grade and industrial products for aerospace and defense. Its recent achievement of a Phase One milestone in a government-funded program, scaling magnetic cell geometry for higher-density space-grade MRAM, highlights a strategy centered on expanding density capability within stringent reliability envelopes. For customers in aerospace and defense, this type of progress signals a pathway toward more capacious memory solutions that still meet the qualification and environmental demands of mission-critical deployment.
The broader competitive trajectory is likely to be shaped by three overlapping dynamics. Integration will continue as system manufacturers seek memory solutions that reduce architectural complexity, particularly where non-volatility, speed, and endurance can be combined in a single element. At the same time, differentiation will persist: the market is not uniform, and the requirements of automotive, aerospace, industrial, and enterprise applications differ enough that specialized expertise, qualification portfolios, and application-specific reference designs will remain valuable. New entry will be selective rather than broad-based, given the barriers posed by fabrication complexity, qualification timelines, and the need for customer trust in high-reliability contexts. Incumbents with established design wins and process knowledge will have an advantage, but targeted entrants addressing narrow, high-value niches may find room to build sustainable positions.
Future Trends and Commercial Implications
Looking ahead across the next three to five years, the MRAM market's evolution will be defined by how effectively the industry resolves the tension between scaling ambition and manufacturing reality, how broadly qualification frameworks expand beyond traditional high-reliability niches, and how policy and supply chain dynamics shape demand concentration.
One clear trend is the continued push toward higher-density MRAM within reliability-constrained environments. As magnetic cell geometry and MTJ stack designs advance, the feasibility of denser arrays for aerospace, defense, and industrial applications improves. The commercial implication is straightforward: customers in these segments will gain access to memory solutions with greater capacity without sacrificing the environmental and retention characteristics that drove initial adoption. This creates opportunities for system architects to consolidate memory functions, reduce component count, and simplify designs in contexts where reliability is non-negotiable. The associated risk is that density gains may lag expectations if process uniformity challenges prove harder to overcome at scale, creating uneven product ramps and potential disappointment in roadmaps that assume linear scaling.
Giant Magneto Resistive (GMR) Sensors Market
A second trend is the broadening of qualification and integration pathways beyond the most demanding defense and aerospace niches. Validation activity across FPGA ecosystems and growing attention to automotive-grade qualification indicate that MRAM is being positioned for design wins in adjacent markets where reliability requirements are significant but not necessarily at the extreme end of the spectrum. The commercial opportunity lies in capturing design-in momentum early in product lifecycles, building reference architectures, and establishing supply confidence before competitors lock in alternative memory choices. The uncertainty here is regulatory and standards-driven: qualification frameworks are rigorous by design, and any shift in requirement interpretation, testing expectations, or supply chain scrutiny can alter timing and cost for both manufacturers and end customers.
A third trend is the growing intersection of memory technology strategy with national security and supply chain resilience priorities. Demand signals tied to defense industrial base initiatives, secure component sourcing, and allied supply chain preferences are likely to remain relevant, particularly for manufacturers positioned to support government and prime-contractor programs. For commercial players, this creates opportunities to align product roadmaps with policy-relevant applications and to build relationships that extend beyond traditional commercial cycles. The risk is concentration: reliance on policy-driven demand can be rewarding but also exposes manufacturers to shifts in program funding, procurement priorities, and export control environments. Diversification across industrial, automotive, and commercial high-reliability segments remains a prudent hedge.
Strategic Considerations for Decision-Makers
For manufacturers and technology developers, the near-term priority is to manage the density-versus-yield tension with explicit roadmaps that account for qualification requirements and customer qualification timelines. Investments in process control, magnetic material optimization, and integration compatibility with standard CMOS flows will determine whether higher-density products can reach volume without eroding margins. Equally important is the development of application-specific reference designs and qualification documentation that shorten customer evaluation cycles. In markets where reliability is paramount, the ability to demonstrate tested performance under representative conditions often matters more than headline specifications. Manufacturers should also consider how to balance defense-adjacent demand with broader industrial and automotive opportunities, ensuring that roadmaps are not overly dependent on any single demand stream.
For investors, the market presents a profile of high growth potential paired with technology execution risk and qualification-driven adoption timelines. The headline growth rate and forward market size trajectory reflect genuine expansion, but returns will depend on which companies can translate technical milestones into volume production, secure recurring design wins, and maintain cost discipline as densities increase. Evaluation should focus on process maturity indicators, qualification progress in target end markets, the durability of customer relationships in high-reliability segments, and the extent to which revenue is tied to policy-sensitive programs versus commercially diversified demand. The specialized nature of MRAM means that leadership in a narrow application area can be more valuable than broad but shallow market presence.
For procurement teams and system architects, MRAM should be evaluated as part of a total cost of ownership framework rather than solely on unit price. In applications where data retention, endurance, temperature tolerance, and fast non-volatile operation reduce downstream risk, MRAM's value can outweigh higher initial component costs. Early engagement with suppliers during the design-in phase, clear alignment on qualification expectations, and review of validation evidence across relevant FPGA or system ecosystems can reduce integration risk. Procurement strategies should also account for supply continuity in high-reliability contexts, where qualification lead times and specialized manufacturing requirements make supply chain resilience a meaningful consideration.
The strategic picture is clear: MRAM is moving from a specialized memory technology to a more broadly relevant element in system architectures where reliability, endurance, and non-volatility intersect with performance requirements. The growth trajectory is strong, but the market's future shape will be determined by how effectively participants navigate manufacturing complexity, qualification rigor, and the selective but meaningful influence of policy-driven demand. Detailed segmentation data, company-level competitive positioning, and application-specific adoption pathways can sharpen these strategic choices further. For decision-makers seeking a fuller picture of market size by segment, regional dynamics, and forward scenario analysis, the complete PW Consulting market report provides the granular intelligence needed to translate high-level trends into concrete commercial action.
For detailed analysis of this topic, please visit the official page: Magneto Resistive RAM (MRAM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com