

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: Large Power Transformers Market Hits USD 25,050 Million in 2025, Poised for Further Growth
By pmarketresearch, 2026-07-01
Large Power Transformers Market 2026 Strategic Brief: Navigating Long Lead Times, Localization Pressures, and a Rising Supply-Cost Environment
PW Consulting — As the global energy transition accelerates and electrification demands intensify across utilities, renewables, data centers and heavy industry, decision-makers in 2026 face a singular procurement reality: large power transformers (LPTs) sit at the intersection of strategic grid resilience and complex industrial supply chains. Our new Large Power Transformers Market report (base year 2025; forecast 2026–2032) synthesizes five years of historical dynamics (2020–2025) and provides scenario-driven guidance to inform capital planning, supplier strategy and risk mitigation for the next investment cycle.
Large Power Transformers Market
Why this report matters for 2026 corporate decisions
-
Macro clarity at a decisive moment — The global LPT market, which expanded through the early 2020s and reached an estimated USD 25,050 million in 2025, is forecast to continue growing through 2032. Our model projects a compound annual growth rate (CAGR) of 4.85% across the forecast window, reflecting sustained demand for transmission and distribution assets driven by renewables integration, grid modernization, and industrial electrification.
Large Power Transformers Market -
Operational urgency driven by lead times — Industry data show average LPT lead times near 128 weeks, with some orders stretching well beyond 210 weeks. For procurement and project planning teams this is not an abstract metric; it directly impacts project kickoffs, contingency allowances, and supplier contracting strategies for equipment that often represents a single-point-of-failure in mission-critical networks.
Large Power Transformers Market -
Supply-side concentration plus import dependencies — The market exhibits meaningful aggregation: the top three suppliers control a substantial share, and the top five approach a majority position. Coupled with high reliance on imported components and limited domestic GOES capacity in several major markets, buyer leverage is evolving into bargaining complexity rather than simple price competition.
-
Price and materials pressure — Since 2019 the sector has seen sharp upstream price movements (notably a ~77% increase in power transformer unit price metrics and material pressures on copper and GOES). These dynamics demand active procurement hedging, long-lead contract structuring, and closer supplier collaboration to manage total cost of ownership.
What PW Consulting’s report delivers — the practical toolkit
-
Forward-looking market sizing and scenarios: A transparent, auditable market model that extends from our 2025 baseline through 2032, combining top‑down drivers (demand centers such as transmission expansion and data center growth) with bottom-up supplier capacity overlays. We include best-, base- and downside scenarios to stress-test capex plans.
-
Procurement playbooks for long lead items: Actionable contract templates, risk allocation matrices and timing playbooks that translate a 128+ week average lead time into milestone-driven procurement timelines — from RFQ to factory acceptance testing and site commissioning.
-
Supplier scorecards and “fit-for-purpose” selection frameworks: Operational and strategic KPIs for evaluating global and regional OEMs, including capability on EHV/HVDC designs, domestic manufacturing footprints, service & maintenance networks, and warranty & spare-parts ecosystems.
-
Supply-chain resilience analytics: Stress tests showing sensitivity to GOES and copper price shocks, single-supplier risk, and cross-border logistics disruptions. We provide recommended mitigations — dual sourcing thresholds, strategic inventory buffering, and partnership vs. vertical-integration decision trees.
-
M&A and partnership watchlist: Identification of acquisition targets, JV candidates and capacity‑build partners across regions most likely to accelerate localization efforts or broaden technical capabilities.
-
Regulatory and policy implications: Assessment of localization incentives, domestic content regimes and strategic procurement policy that are reshaping sourcing decisions, with practical guidance for government-engaged procurement teams.
Competitive landscape — synthesis and implications
The LPT supplier universe is active on multiple fronts: capacity expansion in North America, strategic investments in HVDC and EHV capability, and renewed focus on domestic production. Key incumbent and challenger OEMs reviewed in the report include Hitachi Energy, Siemens Energy, GE Vernova (including Prolec GE operations), Hyundai Electric, Virginia Transformer Corporation, WEG, Delta Star, Pennsylvania Transformer Technology, SPX Transformer Solutions and Eaton. Our analysis combines public announcements, facility footprints, product roadmaps and service-network depth to deliver supplier-by-supplier implications for buyers.
-
Hitachi Energy (Zurich) — Investing heavily in North America with a significant new U.S. facility announced in 2025 and capacity expansion programs in Canada. The firm’s strength in HVDC and grid-integration technologies makes it a strategic partner for utilities pursuing long-distance renewable transmission and converter stations.
-
Siemens Energy (Munich) — Entering domestic U.S. LPT manufacturing with a planned Charlotte, NC plant. Siemens’ local production, targeted for ramp-up in the 2026–2027 window, will be an important option for buyers prioritizing near-sourcing and reduced logistics exposure.
-
GE Vernova (Cambridge) — Through Prolec GE partnerships and U.S. operations, GE brings scale for utility-scale projects and grid modernization programs, supported by deep engineering capabilities and project execution experience.
-
Regional and specialized suppliers — A cohort of North American manufacturers (including Virginia Transformer Corporation, Delta Star, Pennsylvania Transformer Technology, SPX, and Eaton) continues to provide custom solutions, rapid-service networks and tailored lifecycle services that matter for time-critical replacements and OEM-backed refurbishments.
-
Global challengers with U.S. commitments — Hyundai Electric and WEG are increasing North American manufacturing footprints, reflecting a broader industry pivot: OEMs are responding to procurement preferences and policy incentives with local capacity investments.
Importantly, recent developments underscore this strategic shift: Hitachi Energy’s September 2025 investment announcements included a major U.S. facility commitment and a near‑tripling of production capacity in Canada; Siemens Energy signaled large-scale hiring at its Charlotte plant in February 2026 as part of an expanded investment program. These moves materially alter supply options for U.S. and regional buyers over the medium term — but they will not erase lead-time constraints overnight.
Market dynamics and structural constraints
-
Material bottlenecks — Domestic GOES (grain‑oriented electrical steel) production in the U.S. remains constrained; U.S. production historically supplies a minority share of demand with a single active domestic producer in recent years. The report quantifies the systemic exposure that results when an essential material has limited onshore supply and long replenishment timelines.
-
Price inflation and pass-through risks — The sector has experienced significant unit price increases since 2019, reflecting upstream cost pressures and capacity tightness. For capex planners, this means tender timing and escalation clauses must be reassessed; fixed-price procurement can carry material risk if not hedged appropriately.
-
Demand drivers compressing supply — Rapid data center deployment, renewable interconnection queues and grid-reliability upgrades coincide, creating demand clustering that exacerbates existing production bottlenecks and extends lead times.
Strategic recommendations for 2026 decision-makers
-
Lock in supply early for critical-path transformers: For projects with non-flexible commissioning dates, initiate procurement 24–36 months before the earliest deliverable milestone and incorporate staged payments tied to factory acceptance.
-
Adopt a layered sourcing strategy: Combine domestic suppliers for critical spares and short‑cycle replacements with global OEMs for large, custom HV/EHV units. Build contractual mechanisms for capacity reservation where feasible.
-
Pursue collaborative supplier investments selectively: Consider equity‑light capacity commitments, capacity reservation agreements or co‑funded tooling to accelerate near‑term delivery and reduce price volatility exposure.
-
Revise TCO models to include lead‑time risk and materials exposure: Traditional TCO approaches underweight operational availability and replacement risk; our recommended models embed price scenarios, lead-time variability and failure‑mode probabilities.
-
Engage on policy and industry coordination: For national grids and large consortium buyers, lobbying for strategic reserves of GOES, incentives for domestic production and coordination of procurement windows can smooth demand peaks and shorten effective lead times.
What remains behind the curtain — and where to find it
Consistent with the “trailer” principle, this release outlines the strategic contours and core takeaways of PW Consulting’s Large Power Transformers report while preserving proprietary segmentation and granular supplier scorecards that underpin our recommendations. Detailed regional demand splits, unit‑type trajectories, application-level forecasts and supplier-level capacity tables are intentionally excluded here to preserve the analytic value of the full report.
Clients who require the full dataset — including detailed geography-by-application forecasts, unit-size mix, supplier capacity by factory and a downloadable procurement playbook — should consult the complete report and accompanying Excel model available through PW Consulting’s market intelligence portal.
Concluding perspective
As the 2026 investment cycle unfolds, large power transformers will remain a strategic chokepoint for grid resilience and electrification programs. The sector’s combination of long lead times, material concentration and accelerating demand requires buyers to rethink procurement cadence, supplier partnerships and risk allocation mechanisms. PW Consulting’s report aims to convert uncertainty into a disciplined set of actions — enabling executives to prioritize investments, align procurement timelines with project delivery, and make defensible choices about localization, inventory and strategic partnerships.
To explore how these insights apply to your capital program, supply-chain strategy or M&A roadmap, request the full Large Power Transformers Market report and model from PW Consulting’s research desk.
For detailed analysis of this topic, please visit the official page: Large Power Transformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive DSP Amplifier Market Set for 8.75% CAGR (2026–2032) as Asia Pacific Commands USD 1,800.45 Million Share
By pmarketresearch, 2026-07-01
Automotive DSP Amplifier Market — Strategic Outlook for 2026: PW Consulting Market Brief
PW Consulting today releases a strategic preview of our forthcoming Automotive DSP Amplifier Market report (base year 2025, forecast period 2026–2032). The market has demonstrated resilient growth through the first half of the decade and is now entering an inflection phase where software-defined audio, high-efficiency power stages and OEM-level integration are reshaping value chains. Our modeling pegs the 2025 market at USD 2,980.6 million and projects a compound annual growth rate (CAGR) of 8.75% over the forecast horizon, taking the market to a multi-billion-dollar opportunity by 2032. This brief outlines the report’s strategic value for corporate executives planning for 2026 while intentionally withholding the granular segmentation tables and proprietary screenings that are available in the full report.
Automotive Dsp Amplifier Market
Why this matters for 2026 decision-making
-
Timing: Suppliers and OEMs must decide in 2026 whether to accelerate investments in DSP-enabled architectures or to optimize legacy analog pathways. The window to position for premium cabin experiences and EV-tailored audio is narrow; choices this year set product roadmaps and supply commitments for the next generation of vehicles.
Automotive Dsp Amplifier Market -
Technology convergence: Advances in Class‑D efficiency, high-resolution DSP cores and AI/ML-enabled audio processing are creating differentiation that is increasingly software-driven. Companies that can marry silicon advantages with system-level tuning will capture a disproportionate share of aftermarket and OEM wallet.
Automotive Dsp Amplifier Market -
Supply-side constraints: Semiconductor node availability, power-IC lead times and raw-material pressures (including rare-earth challenges) are altering procurement strategies—making near-term supplier qualification and multi-sourcing essential actions for 2026.
What PW Consulting’s full report delivers (practical, executable content)
-
Proprietary market sizing and forward-looking financial scenarios: A bottom-up model that captures unit and ASP dynamics across the entire value chain, providing executable inputs for strategic planning and budgeting.
-
Technology readiness and adoption maps: Comparative assessments of Class‑D topologies, integrated DSP amplifier platforms and multi-channel architectures, with guidance on speed-to-market and IP risks.
-
Competitive playbooks: Company-level capability matrices, product positioning analyses, and channel/partnership opportunity maps to inform go-to-market and OEM negotiation strategies.
-
Supply-chain stress tests and mitigation frameworks: Scenario-based analyses quantifying the impact of semiconductor volatility and rare-earth shortages, with recommended sourcing and inventory levers to preserve launch timelines.
-
Commercial models and pricing sensitivities: Tactics for balancing margin recovery with value-based pricing in OEM replacement cycles and aftermarket segments.
-
M&A and partnership screening tools: A tranche-based approach to assess acquisition targets and strategic partnerships across product, software and silicon layers.
-
Regulatory and qualification checklist: Actionable steps to align development programs with AEC‑Q100 and functional-safety expectations so product validations do not become launch blockers.
Market trajectory and strategic implications
The path from 2020 to 2025 reflects steady expansion in installed units and value-addition per vehicle as audio systems evolved from commodity amplifiers to integrated DSP-powered audio experiences. Our forecast sees that trajectory accelerating as vehicles—especially those positioned as premium or electric—embed higher levels of signal processing, personalized sound profiles and cloud-enabled tuning. The reported CAGR of 8.75% is not simply a volume story: it captures rising average selling prices driven by software-layer monetization, higher channel counts for immersive audio, and the premiumization of in-cabin experiences.
For executives this means three immediate strategic implications for 2026:
-
Product roadmaps must be defined as software-first. Hardware decisions should enable lifecycle monetization through OTA updates, app-based personalization, and analytics.
-
Partnerships with semiconductor vendors and audio-software specialists will be the primary lever to accelerate feature deployment while controlling BOM and certification timelines.
-
Commercial models should shift from transactional hardware margins to recurring revenue streams and value-based pricing tied to perceived user experience improvements.
Competitive landscape — who to watch and why
The market exhibits a mix of specialist audio brands and large semiconductor OEMs. Market concentration is meaningful but not insurmountable: the top three suppliers account for a substantive portion of revenues, and the top five increase that share further—creating a landscape where scale and systems expertise matter.
-
Audiotec Fischer (Germany): A leader in high-end aftermarket and premium OEM audio, the company’s HELIX and BRAX lines—bolstered by recent awards—signal continued traction in differentiated DSP tuning and consumer-facing premium positioning.
-
Audison (Italy): With strong D‑Class power expertise and OEM-focused integrations, Audison is positioned to capitalize on both replacement market demand and niche OEM programs that value tuned audio signatures.
-
Alpine Electronics (Japan): Alpine’s Status and Hi-Res offerings underscore an approach that blends performance hardware with system-level integration—an attractive blueprint for suppliers seeking OEM certification pathways.
-
AudioControl and ARC Audio (USA): These vendors are notable for their signal-processing depth and pro-level tuning tools, which remain highly attractive in aftermarket and specialty OEM fitments.
-
Mosconi (Italy): Compact integrated DSP platforms that target high-fidelity automotive installations; their product strategy highlights the continuing demand for space-efficient solutions in modern cabins.
-
STMicroelectronics, Texas Instruments, Analog Devices, NXP (Semiconductor vendors): These companies are the backbone of the transformation—supplying automotive-grade Class‑D amplifiers, high-performance DSP cores and peripheral silicon. Recent product launches and announcements indicate a clear push to enable smart-cockpit audio features and AI-enabled sound processing at scale.
Recent industry moves—awards for high-end DSP systems, new Class‑D launches, and major processor announcements—are accelerating competitive differentiation along software capability, thermal and electrical efficiency, and ease of OEM integration. For 2026, monitoring which vendors can pair silicon roadmaps with robust automotive qualification and supply commitments will be decisive.
Risks, regulation and supply-chain dynamics to factor into 2026 plans
-
Regulatory/qualification burden: Automotive audio components must meet stringent AEC‑Q100 and functional-safety expectations. These qualification cycles add months to launch timelines and must be embedded in program plans early.
-
Semiconductor and raw-material risk: Mature-node MCU and power-IC volatility—plus rare-earth availability—remain material constraints. Procurement strategies should include long‑lead contracts, dual-sourcing, and design-for-availability to avoid launch slippages.
-
Market consolidation and margin pressure: As silicon suppliers exert pricing pressure and tier-1s demand system-level solutions, supply-side players will face margin compression unless they capture software and services revenue or secure scale advantages.
How PW Consulting’s report accelerates practical decisions in 2026
Our report is structured to convert analysis into executable decisions. It provides scenario-tested financial models you can adapt to internal inputs, supplier risk heatmaps that feed procurement scorecards, and a decision tree for platform vs. bespoke product investment. Importantly, while this preview highlights market direction and competitive forces, the full report contains the granular segmentation, supplier scoring and unit-level assumptions that buyers and strategists require to finalize budgets and supplier selections. We have intentionally omitted those tables here to preserve the integrity of proprietary client frameworks—access to those sections is available on the report page and via direct PW Consulting briefings.
Recommended immediate actions for executives in 2026
-
Reassess product roadmaps against a software-first timeline: prioritize architectures that enable OTA tuning and analytics capture.
-
Secure semiconductor capacity: initiate multi-year supply agreements for key power ICs and DSP cores, and include clauses for supply continuity under elevated raw-material risk.
-
Accelerate supplier qualification: begin AEC‑Q100 and functional-safety validation now to avoid certification-driven delays.
-
Pursue modularization: adopt modular amplifier/DSP assemblies to shorten variant development and reduce inventory risk.
-
Explore partnerships for software monetization: negotiate revenue-sharing or licensing arrangements with audio-software specialists to capture post-sale value.
-
Use the PW Consulting heatmaps for M&A prioritization: target acquisitions that fill gaps in system tuning, cloud connectivity, or silicon partnerships.
PW Consulting’s Automotive DSP Amplifier Market report is designed to be the strategic playbook for 2026: it translates market growth, supplier dynamics and technology shifts into an operational roadmap that executives can act on this year. For full access to the segmentation, company scorecards, unit economics, and proprietary scenario models, please visit our report page or contact PW Consulting for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Automotive Dsp Amplifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Fuel & Oil Filters Market Set to Expand at a 5.25% CAGR Through 2032, Led by North America
By pmarketresearch, 2026-07-01
Fuel, Fuel Oil & Aircraft Aerospace Filters Market — Strategic Outlook for 2026: PW Consulting Industry Brief
Executive summary
As airlines, OEMs, MROs and tier‑1 suppliers plan capital and product roadmaps for 2026, the aircraft fuel and fuel‑oil filtration market presents a mix of steady demand and accelerating technology and regulatory pressures. PW Consulting’s latest market model shows the global market reached approximately USD 179.7 million in 2025 and is forecast to grow at a 5.25% CAGR through the 2026–2032 horizon, culminating in a market size approaching USD 258 million by 2032. That trajectory reflects predictable replacement cycles, modest fleet growth, and an overlay of structural change driven by alternative fuels, new contamination vectors, and supplier consolidation.
Fuel Fuel Oil Aircraft Aerospace Filters Market
Why this matters for 2026 decision‑makers
-
Investment prioritization: Product development and capex cycles in filtration are long‑lead; decisions made in 2026 will determine technology portfolios for the next decade.
Fuel Fuel Oil Aircraft Aerospace Filters Market -
Regulatory compliance and risk mitigation: Operators and suppliers must reconcile filtration performance with evolving SAF blends and standards that mandate water separation and particle control.
Fuel Fuel Oil Aircraft Aerospace Filters Market -
Supply‑chain resilience: Consolidation and targeted acquisitions are reshaping supplier choices, with implications for availability, aftermarket margins and captive sourcing strategies.
Market trajectory and the practical implications
Our topline model blends historical shipment and aftermarket data (2020–2025) with forward scenarios (2026–2032). The near‑term market shows continued replacement demand supported by fleet utilization and MRO cycles; beyond that, incremental growth is driven by retrofits, upgraded two‑stage filtration systems and expanded aftermarket services. The steady 5.25% CAGR masks important inflection points: regulatory phases that increase SAF blending and technology transitions away from legacy water detection/monitoring technologies. For procurement and product strategy teams this means balancing short‑term service continuity with targeted investment in SAF‑compatible, higher‑efficiency filtration and separation systems.
Key dynamics shaping the market in 2026
-
Regulatory push for SAF: Policies such as the EU’s progressive SAF blend requirements are forcing airport fuel supply chains and airframe/engine integrators to validate filter performance across new chemistries and contaminants. Filtration systems that were designed for conventional Jet A/A1 may underperform with higher oxygenate content or different particulate profiles.
-
Standards and performance expectations: Industry standards — including those that define two‑stage water/particle separation requirements — are increasingly prescriptive. Compliance is not optional; it becomes a procurement gate for airlines and integrators.
-
Contamination vectors: Operational incidents such as DEF contamination and crystallization remain a material safety and reliability risk. Filters serve as the last line of defense — but they must be specified, tested and maintained differently where new contamination types are present.
-
Technology migration and product phase‑outs: Recent industry moves highlight rapid technology turnover. The announced phase‑out of certain legacy EI‑qualified water monitoring products accelerates adoption of a next generation of water‑barrier and sensing technologies. OEMs and MROs need transition plans to avoid obsolescence and supply disruptions.
-
Consolidation and M&A: Strategic deals show suppliers expanding vertically and horizontally to capture aftermarket, cartridge and systems revenue. M&A is reducing the pool of independent specialists but also creating larger suppliers with broader product portfolios.
Competitive landscape — reading between the lines
The market exhibits a moderate concentration: a small set of global engineering majors and specialized filtration houses command a meaningful share of system supply and aftermarket contracts, while niche vendors serve tailored military, GA and PMA segments. Firms such as Parker Hannifin, Donaldson, Pall, Porvair, Safran and Eaton continue to be pivotal — supplying systems, cartridges and integration services across OEM and aftermarket channels. Meanwhile, highly specialized firms (e.g., Tempest Aero Group, Chase Filters & Components, Global Filtration and Norman Filter) play critical roles in general aviation, defense and PMA markets where customization, certification speed and service relationships are competitive differentiators.
Recent developments illustrate strategic direction: Donaldson’s acquisition of Facet Filtration underscores a consolidation trend aimed at assembling end‑to‑end mission‑critical fluid solutions. Parker’s discontinuation of certain legacy water monitor products signals an industry pivot towards new water barrier technologies and sensor integration. Pall’s continued support of large airline fleets confirms that fleet service contracts remain a high‑value, sticky revenue stream for suppliers that can demonstrate sustained performance with SAF blends.
Where the real opportunities lie (but the granular splits are in the full report)
-
Systems & integrated solutions: Suppliers that move beyond stand‑alone cartridges to offer filtration as a systems‑level capability — including monitoring, diagnostics and service contracts — can capture higher lifetime value.
-
Aftermarket & fleet support: Long‑term service agreements and cartridge subscriptions provide predictable recurring revenue and higher margins than one‑off hardware sales.
-
SAF compatibility and retrofit kits: There is a commercial window for retrofit kits and validated filtration upgrades to support new fuel chemistries; early movers who achieve certifiable performance gain preferential access to airline procurement cycles.
-
Defense & specialty segments: Military applications and high‑reliability segments continue to favor bespoke, qualified solutions; suppliers with rapid qualification capability and traceable documentation win in these higher‑margin niches.
What PW Consulting’s full report contains (practical, execution‑oriented)
-
Top‑down market sizing and bottom‑up validation across 2020–2025, plus high‑ and low‑case forecasts for 2026–2032 with sensitivity analysis tied to SAF adoption rates.
-
Technology deep‑dive: comparative performance benchmarking of micronic filters, coalescer separators, two‑stage systems and emerging water‑barrier technologies — with guidance on lab and field test protocols needed for certification.
-
Regulatory impact mapping: scenario playbooks for different regional SAF uptake paths and corresponding compliance actions for suppliers and operators.
-
Competitive profiles and strategic scorecards for leading suppliers, including capability matrices, product roadmaps, recent M&A and likely strategic moves (detailed company profiles and web references included).
-
Procurement & supplier risk toolkit: negotiation templates, multi‑year sourcing scenarios, spare‑parts stocking models and contingency playbooks to protect fleet operations during supplier transitions.
-
MRO playbook & aftermarket monetization: step‑by‑step guidance on building service contracts, cartridge lifecycle pricing, and parts commonality strategies to maximize margin and retention.
-
Investor & M&A advisory annex: valuation comparables, consolidation scenarios and inorganic growth targets for strategic acquirers or private equity seeking exposure to high‑quality aftermarket streams.
Concrete 2026 actions by stakeholder
-
Airlines and lessors: institute an immediate audit of filtration performance across your fuel supply chain for SAF blends; require supplier test evidence and deployment timetables as part of procurement RFPs.
-
OEMs and tier‑1 suppliers: prioritize certifying filter families against SAF and perform coalescer/separator validation under worst‑case contamination scenarios; build retrofit pathways into service bulletins to capture aftermarket revenue.
-
Filter manufacturers: accelerate integration of water‑barrier and sensor technologies, build long‑term fleet support offerings and evaluate targeted acquisitions to fill capability gaps (materials, sensing, certification speed).
-
MROs and component rebuilders: develop cartridge remanufacturing and predictive replacement programs; partner with operators to bundle filtration services with fuel and tank maintenance offerings.
-
Investors: triangulate investment opportunities between durable aftermarket service streams and engineering‑led suppliers positioned to capture SAF retrofit demand; look for firms with rapid qualification capability and strong OEM relationships.
Market risk factors to monitor in 2026
-
SAF price dynamics: sustained high SAF premium slows retrofit adoption and delays supplier revenue realization.
-
Regulatory variance: uneven regional SAF mandates create patchwork demand and complicate global fleet strategies.
-
Supplier single points of failure: phase‑outs of legacy equipment without managed transitions expose operators to operational risk; contractual service continuity clauses should be enforced.
-
New contamination types: operational misuse (e.g., DEF cross‑contamination) produces failure modes unanticipated by legacy filters; incident learning must feed product design rapidly.
Conclusion — the strategic choice for 2026
2026 is a decision year: organizations that treat filtration as an operational cost center will face increasing disruption from fuel chemistry change and supplier consolidation. Conversely, stakeholders who seize the opportunity — by investing in validated SAF‑compatible systems, pursuing aftermarket service models and shoring up supplier transition plans — can capture disproportionate value as the market grows at a mid‑single‑digit CAGR and moves into a period of technology turnover.
Next steps
PW Consulting’s full Fuel, Fuel Oil & Aircraft Aerospace Filters Market report provides the granular segmentation, supplier share tables, pricing curves and downloadable models needed to operationalize the recommendations above. For executives preparing budgets, RFPs or M&A screens in 2026, the report is the practical reference that converts market intelligence into executable plans. Visit our report page to access the complete dataset, segmented forecasts and the supplier playbooks referenced in this briefing.
For detailed analysis of this topic, please visit the official page: Fuel Fuel Oil Aircraft Aerospace Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Vertical Rotary Surface Grinders Market to Expand at 5.59% CAGR, Unlocking New Opportunities Through 2032
By pmarketresearch, 2026-07-01
Vertical Rotary Surface Grinders Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s new market study on Vertical Rotary Surface Grinders offers a focused, decision‑grade intelligence package designed to steer capital, sourcing and product strategies in 2026. Grounded in five years of historical observation (2020–2025) and a seven‑year forecast horizon (2026–2032), the report synthesizes macro growth trajectories, competitive positioning and actionable playbooks for OEMs, end‑users and investors. This preview outlines why the report is strategically material for choices you will make this year, while intentionally withholding detailed subsegment tables to encourage direct access to the full dataset.
Vertical Rotary Surface Grinders Market
Market Snapshot: Macro Trajectory and Competitive Structure
The vertical rotary surface grinders market reached an estimated USD 2,580 Million in the base year (2025). Our modeling indicates steady expansion through the forecast window, with a compound annual growth rate of 5.59% from 2026 to 2032 and a projected market size approaching USD 3.78 Billion by 2032. These headline metrics reflect a combination of demand drivers: sustained investment in automotive, aerospace and toolmaking; ongoing replacement cycles in heavy industry; and selectively rising requirements for precision flatness in advanced manufacturing.
Vertical Rotary Surface Grinders Market
Concentration metrics show a market that is neither atomized nor fully consolidated: the top three players account for roughly 38.5% of market sales while the top five approach 52.7%. That mid‑fragmented structure creates both scale advantages for established OEMs and fertile ground for niche specialists, particularly in remanufacturing, aftermarket service and application‑specific turnkey solutions.
Vertical Rotary Surface Grinders Market
Why This Matters for 2026 Decisions
- Capital Allocation: With predictable mid‑single‑digit growth, major capital expenditures should be gated by clear payback expectations. The report supplies modeled ROI scenarios under differing utilization, pricing and material‑cost assumptions to assist board‑level approvals.
- Sourcing & Supply Chain: Volatility in steel and specialty material pricing, along with ongoing trade investigations, materially affect BOM costs and lead times. The study provides scenario stress‑tests for sourcing strategies (near‑shoring, dual‑sourcing, contractual hedging) to be executed in 2026.
- Product Roadmaps: Technology choices (e.g., hydrostatic turntables, high‑powered vertical spindles, remanufactured Blanchard lines) should be prioritized against end‑market demand elasticity. We map technology adoption sequences to price bands and buyer personas to help product and engineering teams set 18–36 month development cadences.
- M&A and Partnership Screening: The mid‑concentrated nature of the market makes strategic acquisitions or capacity partnerships attractive for both OEMs seeking share and private equity looking for consolidation plays. The report includes a shortlist framework for target screening and valuation levers.
Actionable Contents of the Full Report
The published report is structured for operational use. Highlights include:
- Executive dashboards with topline growth scenarios and sensitivity to steel price and tariff shocks.
- Buyer personas and procurement playbooks—how to evaluate TCO for one‑head vs multi‑head machines, retrofit vs new purchase, and when remanufactured assets make sense.
- Technology horizon maps detailing adoption curves for hydrostatic tables, high‑HP spindle platforms and control/automation upgrades.
- Profitability models for aftermarket services (spares, rebuilds, field servicing) and a build‑out playbook for service organizations.
- Regulatory and trade risk matrix with mitigation options—procurement clauses, inventory buffers, and tariff pass‑through modeling.
- M&A playbooks and a prioritized target list based on strategic fit, manufacturing footprint and aftermarket overlap.
- Benchmarked supplier scorecards and negotiation checklists to shorten vendor qualification cycles.
To preserve the report’s commercial integrity, granular regional and application breakdowns are not reproduced in this preview. The full downloadable dataset contains the complete segmented tables and time‑series that underpin our recommendations.
Competitive Landscape — Who Matters and Why
We examined a cross‑section of OEMs and regional specialists to form a layered view of competition, capability and go‑to‑market approaches.
- Bourn & Koch, Inc. (Rockford, Illinois, USA) — Known as the OEM for Blanchard vertical rotary grinders, Bourn & Koch’s portfolio emphasizes both new and remanufactured models with very large chuck capacities and high‑horsepower spindles. Their strength lies in heavy‑stock removal and purpose‑built installations for large workpieces.
- DCM Tech (Winona, Minnesota, USA) — Offers the IG series of American‑made rotary grinders with a range of capacities. DCM targets precision grinding for industrial and aerospace applications, balancing compact footprints with serviceability emphasis.
- Chevalier Machinery (Taiwan / USA) — The FRG series highlights hydrostatic turntable designs and high rigidity. Chevalier is notable for product refreshes that push precision at competitive price points and for expanding aftermarket capabilities.
- Okamoto Corporation (Japan) — The VRG‑DX line focuses on high‑power spindles and accuracy in rotary table models, positioning Okamoto against premium accuracy demands in aerospace and optical component manufacturing.
- Tong Yi Machinery / Dowell (Taiwan) — Markets VR series machines that stress reliability across metalworking segments, often chosen where predictable uptime and ease of maintenance are procurement priorities.
- Alex Machine Tools, Synergy Machine Tools, ABL Machine Tools, Kent USA — These regional manufacturers offer a spectrum of vertical rotary platforms, from high‑volume die & mold machines to specialty units for valves, bearings and hard/brittle material work.
Competitive dynamics are evolving: premium accuracy and aftercare are moving from differentiators to table stakes, while remanufacturing and service models (where margins are typically higher than OEM equipment sales) are becoming profit centers for firms that can execute nationwide field networks.
Recent Industry Signals and Their Strategic Implications
- Trade show activity and product launches (for example, Alex Machine Tools’ participation at Die Mould India 2026 and Chevalier’s recent FRG series introduction) signal renewed OEM emphasis on capturing die & mold and custom applications—opportunities for localized manufacturing partnerships.
- Notable installations and product upgrades (illustrated by Bourn & Koch’s placements in 2025) show that existing demand is still driven by replacement and capacity expansion in regional metalworking hubs.
- Input‑cost noise—steel coil prices rose meaningfully in 2025—along with ongoing national trade investigations and tariff proposals on machine tools and specialty materials, create risk for global sourcing models and warrant explicit procurement hedging strategies in 2026.
Strategic Recommendations for 2026 Execution
- Lock in modular sourcing: Pursue dual‑source agreements for key castings and spindle components, and qualify regional sub‑assemblies to reduce tariff exposure and lead time volatility.
- Prioritize the aftermarket: Build spare parts inventory strategies, subscription‑style maintenance, and remote diagnostics offerings to increase recurring revenue and reduce price sensitivity.
- Invest selectively in high‑value tech: Target hydrostatic turntables and high‑HP spindle platforms for customers where productivity gains justify price premiums; standardize controls for easier service and upgrades.
- Hedge material cost exposure: Use indexed contracts or multi‑year supply agreements where possible; model scenarios for up to 50% tariff shocks in procurement planning exercises.
- Consider bolt‑on consolidation: For mid‑sized OEMs and financial sponsors, pursue tuck‑ins that strengthen service footprints or add remanufacturing capabilities—those assets accelerate margin expansion.
- Engage on policy: Coordinate with industry associations to influence trade policy implementation timelines and secure carve‑outs for critical capital equipment components.
Methodology, Confidence and Next Steps
Our analysis synthesizes primary interviews, vendor and end‑user surveys, company disclosures and price‑sensitive input‑cost models. Base year is 2025; forecasts run 2026–2032. We assign medium‑high confidence to headline growth and concentration metrics, with scenario banding around material price and tariff trajectories to reflect elevated policy risk.
This preview is intentionally selective—core segmented tables, regional/application splits, and detailed company financials are only available in the full report package and accompanying data workbook. For procurement teams, strategy committees, or investors preparing decisions in 2026, those granular datasets are the difference between directional understanding and executable strategy.
Access the Full Intelligence
PW Consulting’s full Vertical Rotary Surface Grinders Market report provides the datasets, slide decks and implementation tools required to convert insight into action. Contact our market research desk or visit the report page to download the executive summary, review the methodology appendix and access the client portal for custom queries and model extracts.
For detailed analysis of this topic, please visit the official page: Vertical Rotary Surface Grinders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Emergency Rescue Drone Market to Soar at a 12.45% CAGR Through 2032
By pmarketresearch, 2026-07-01
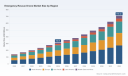
Emergency Rescue Drone Market 2026: Strategic Imperatives for Corporate Decision‑Makers
PW Consulting’s latest market research — Emergency Rescue Drone Market: 2026 Strategic Brief — synthesizes seven years of market evolution and a detailed seven‑year forecast to deliver a compact, decision‑grade intelligence package for executives planning 2026 investments. Built on historical observations (2020–2025) and a forecast horizon through 2032, the analysis identifies the structural forces reshaping emergency response capabilities and quantifies the market’s acceleration: a compound annual growth rate (CAGR) of 12.45%, with total market value moving from roughly USD 142 million in 2020 to USD 312.5 million in 2025 and projected to exceed USD 700 million by 2032. This release summarizes the strategic takeaway for corporates while intentionally reserving granular segmentation and vendor matrices for the full report.
Emergency Rescue Drone Market
Why this brief matters for 2026 planning
Emergency rescue drones have moved beyond proof‑of‑concept deployments into mission‑critical roles across public safety, disaster response, and medical logistics. For 2026 planning cycles, buyers, OEMs, integrators, and investors need a tightly focused understanding of three things:
Emergency Rescue Drone Market
- How regulatory and procurement realities (e.g., supply‑chain compliance and DFR program approvals) will gate adoption timelines;
- Which technology choices materially change total cost of ownership and operational effectiveness (autonomy, thermal and sensor stacks, VTOL vs. multirotor tradeoffs); and
- Where consolidation and competitive concentration create acquisition or partnership opportunities.
This brief translates those questions into board‑level recommendations and executable next steps — without disclosing the full granular charts and segmented revenue tables that appear in the full dossier.
Emergency Rescue Drone Market
Key market dynamics shaping 2026 decisions
Regulatory and procurement environment: Two regulatory signals are decisive. First, mandatory supply‑chain compliance for many government and public safety adopters — notably NDAA compliance — is now a prerequisite for meaningful contract eligibility. Second, aviation authorities have accelerated administrative pathways for Drone as First Responder (DFR) programs, reducing time‑to‑operational‑status when agencies use prepositioned systems. For purchasing officers and program managers, this means supplier selection must balance technical capability with verifiable compliance credentials and program‑specific approvals.
Technology and operational drivers: Advancements in onboard autonomy, high‑resolution thermal imaging, encrypted real‑time telemetry, and hybrid VTOL endurance are combining to change operational doctrines. Autonomous pathing, robust obstacle avoidance, and machine‑assisted search patterns materially increase the value of a deployed drone beyond raw flight time. Equally important are sensor modularity and communications resilience: payload ecosystems and hardened data links determine whether a platform becomes an operational asset or a temporary experiment.
Supply chain and component constraints: As defense and government programs require NDAA‑compliant batteries and parts, sourcing strategies must adapt. Our analysis highlights the strategic tradeoffs in locking into compliant supply streams versus pursuing cost‑optimized components. For procurement teams, mapping supplier certification timelines against planned deployments is now mission critical.
Market structure and competitive dynamics: The sector is moving toward a moderately concentrated topology. The top three players account for a significant share of revenue, and the top five approach parity with a substantial portion of market value — a pattern that favors specialist incumbents with public‑safety pedigree and scaled manufacturing. This structure has implications for pricing power, aftermarket service economics, and M&A activity.
What’s in the full report (practical, operational content)
Our 150+ page report is intentionally designed for users who need to act in 2026. Key practical assets included are:
- Decision frameworks for procurement: vendor scorecards, NDAA compliance checklist, and contract templates tailored for public‑safety and municipal procurement cycles;
- Operational deployment playbooks: step‑by‑step DFR station planning, maintenance cadence, and crew training matrices that convert a pilot project into a 24/7 operational capability;
- Financial tools: TCO models, scenario‑based ROI calculators, and risk‑adjusted investment timelines aligned to the market CAGR and adoption curves;
- Technology assessment rubrics: standardized test procedures for autonomy, sensor fusion, and communications resilience (including evaluation criteria for thermal imaging, two‑way communications, and glass‑breach capabilities);
- Supply‑chain and compliance mapping: supplier due‑diligence templates and alternative sourcing strategies for NDAA‑sensitive components such as batteries;
- Scenario planning: three plausible adoption trajectories (base, accelerated, and constrained) with associated budgetary implications and suggested operating cadences for each scenario;
- Implementation roadmaps: 6–18 month and 18–36 month playbooks that identify fast wins and medium‑term investments for municipal agencies and private operators.
We intentionally withhold the detailed segmentation tables and regional/application breakouts in this press brief to protect the commercial sensitivity of that analysis. Those datasets and vendor scorecards are available in the full report.
Competitive landscape—who matters and why
Our analysis profiles a compact set of specialist and system providers whose technology portfolios and go‑to‑market motions will shape 2026 outcomes:
- BRINC Drones — a public‑safety specialist notable for purpose‑built systems including indoor/dense‑urban tactical solutions, two‑way communications, and field‑proven breaching capabilities. Recent developments: in March 2026 BRINC announced a significant production expansion and launched a next‑generation response drone aimed at 24/7 DFR operations.
- Skydio — leading in autonomy and robust obstacle avoidance for complex environments; its AI‑driven platforms are increasingly deployed in hands‑off search and rescue missions where reliable navigation matters more than raw endurance.
- AeroVironment — historically defense‑oriented, providing tactical UAS and VTOL systems with proven rapid‑deployment characteristics, attractive to governmental programs requiring hardened logistics and ISR integration.
- Draganfly — a North American manufacturer focused on public safety payloads and domestic production footprints, which helps satisfy procurement preferences for localized manufacturing.
- ZenaDrone — a growth‑stage vendor offering long‑range, mission‑specific platforms built around robust telemetry and real‑time data transmission for remote search operations.
- Ascent Aerosystems — supplier of resilient coaxial designs optimized for compact operations in constrained environments and integration with defense/public‑safety systems.
Market concentration metrics reinforce the importance of these players: the top three firms hold a material portion of market revenues, and the top five capture over half of industry value — a structure that creates both competitive barriers and clear acquisition targets for strategic buyers.
Strategic recommendations for 2026
We advise corporate and public‑sector leaders to take four concurrent actions this year to convert market growth into competitive advantage:
- Prioritize compliance as a core capability. NDAA credentials and documented supply‑chain provenance are now as important as performance specifications. For manufacturers, this should be integrated into product roadmaps and supplier contracts; for buyers, certification should be a gated procurement milestone.
- Invest in autonomy and systems integration. Platforms with higher levels of autonomy reduce operator overhead and scale more cost‑effectively as programs move from pilot to continuous operations.
- Design modular service and payload ecosystems. The winning commercial models will combine hardware sales with subscription‑grade software, payload leasing, and field service — turning one‑off deployments into recurring revenue streams and reliable public‑safety capabilities.
- Use scenario‑based budgeting tied to adoption curves. With a 12.45% CAGR and clear upside under accelerated DFR adoption, procurement timelines should be staged: near‑term investments to secure interoperability and compliance, mid‑term capital for scaled deployments, and longer‑term R&D for next‑gen endurance and autonomy.
How to use this research in executive decision making
PW Consulting’s report is designed to be directly actionable for four audiences in 2026:
- CEOs and corporate strategy teams evaluating M&A or partnership plays — use our competitive concentration analysis and M&A scenarios to prioritize targets;
- Procurement and operations leaders at municipalities, utilities, and large enterprises — apply our procurement checklists and TCO models to replace pilots with scalable programs;
- R&D and product teams at OEMs — benchmark autonomy, payload interfaces, and compliance investments against the technology assessment rubrics;
- Investors and PE sponsors — use our market‑level forecasts, concentration metrics, and scenario returns to size investment tickets and staging requirements.
Each user group can adopt the report’s tools directly into board packets, procurement RFPs, or product investment cases. The deliverables were built to reduce time‑to‑decision while preserving the analytical rigor executives require.
Next steps
The executive brief you are reading condenses the core strategic implications of PW Consulting’s full Emergency Rescue Drone Market report. For procurement matrices, regional and application segmentation, granular vendor scores, and downloadable financial models, please consult the full report on our website. Those datasets are essential for teams building specific procurement packages, investment memos, or R&D roadmaps in 2026.
PW Consulting stands ready to help translate this research into a tailored implementation plan, whether you are evaluating a first DFR deployment, planning a national roll‑out, or considering M&A to capture aftermarket service value. Contact our Public Safety & Unmanned Systems practice to schedule a briefing and scenario workshop.
For detailed analysis of this topic, please visit the official page: Emergency Rescue Drone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Light Commercial Vehicle Transmission Market Poised for 5.71% CAGR Through 2032
By pmarketresearch, 2026-07-01
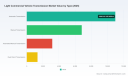
Light Commercial Vehicle Transmission Market: A Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market study on Light Commercial Vehicle (LCV) transmissions equips senior executives and strategy teams with the forward-looking intelligence needed to make confident 2026 investments. The global LCV transmission market is standing at an inflection point: after expanding to approximately USD 22,320 Million in 2025, our modeling projects continued expansion through the forecast window (2026–2032) at a compound annual growth rate (CAGR) of 5.71%, culminating in a market above USD 32,900 Million by 2032. These headline numbers frame a market that is neither commoditized nor closed—competition and consolidation coexist, and the right strategic moves in 2026 will materially change competitive trajectories through the end of the decade.
Light Commercial Vehicle Transmission Market
Why this report matters for 2026
-
Timing: 2026 is the year when regulatory pressure, tariff shifts and the first wave of compact electrified powertrain rollouts converge with fleet replacement cycles. Decisions taken now on R&D prioritization, supply chain reconfiguration, and partner selection will determine market share through 2030.
Light Commercial Vehicle Transmission Market -
Actionability: Beyond forecasts, the report delivers executable playbooks—product roadmaps, supplier risk matrices, and pricing sensitivity models—built to be used by product, purchasing and M&A teams during budget cycles and board discussions.
Light Commercial Vehicle Transmission Market -
Clarity: We synthesize historical trends (2020–2025) and scenario-tested forecasts (2026–2032) in USD (Millions), so senior finance teams can plug findings directly into corporate planning models and investment committees.
What the report contains (practical, decision-grade content)
-
Market sizing and scenario forecasts: Base-year (2025) sizing, historical trajectory (2020–2025), and three scenario tracks to 2032 that incorporate differing EV adoption, regulatory tightening and trade-policy outcomes.
-
Technology and product roadmaps: Comparative TCO and efficiency modeling for automatic, manual, automated-manual, dual-clutch and electrified transmission solutions—presented in formats you can use to re-rank R&D and capex projects.
-
Competitive intelligence and capability mapping: A strategic profile for incumbent and challenger suppliers, including capability heatmaps (manufacturing scale, hybrid/e-drive competence, service networks) and supplier scorecards.
-
Supply chain and raw-material stress-testing: Inputs and tools to quantify margin pressure from steel and aluminum volatility, inventory hedging strategies, and alternative sourcing scenarios under tariff regimes.
-
Commercial and aftermarket playbooks: Contracting templates, channel strategies for last-mile and fleet customers, and service monetization frameworks to extend lifetime value.
-
Deal tools and screening matrices: Acquisition targets, JV partner shortlists, and integration checklists tuned for 2026 windows of opportunity.
Market structure and competitive posture
The LCV transmission arena is moderately concentrated: our concentration metrics show that the top three players control a meaningful but not dominant share of market revenue, with the top five owning a clear majority. That structure creates both competitive pressure and opportunistic whitespace for mid-sized suppliers and nimble newcomers. Strategic implications are straightforward—scale matters for OEM program wins, but well‑timed technology bets and M&A can materially change a participant’s win rate in two to three product cycles.
-
ZF Friedrichshafen AG (Friedrichshafen, Germany) — Strength: broad automatic transmission portfolio tailored to commercial applications and recent product momentum. ZF’s 8-speed PowerLine deployment on medium-duty platforms highlights its capability to convert technology investments into OEM-level wins. Strategic priority: defend core automatic segments while accelerating electrified adaptations of modular architectures.
-
Aisin Corporation (Kariya, Japan) — Strength: compact, proven automatic and dual-clutch architectures with hybrid-ready variants. Aisin’s compact dual-clutch EV transmission announcement signals intent to own a segment of electrified light-truck drivetrains. Strategic priority: productize the compact e-transmission for broader LCV platforms and lock in early EV OEM programs.
-
Allison Transmission (Indianapolis, USA) — Strength: deep installed base in delivery and service vehicles with strong brand equity in automatic transmissions. Strategic priority: leverage service and aftermarket to defend margin and expand electrified transmission modules for urban delivery segments.
-
Eaton Corporation (Dublin, Ireland) — Strength: automated-manual and dual-clutch offerings targeted at cost-sensitive applications; recent Advantor-6 introduction underlines competitiveness in light-duty trucks. Strategic priority: convert automated-manual economics into sustainable margins through manufacturing scale and software-enabled shift controls.
-
BorgWarner Inc. (Auburn Hills, USA) — Strength: hybrid and electrified modules suited to LCV powertrains. Strategic priority: integrate electrified transmission modules with e-axles and thermal-management systems to create bundled e-powertrain offers.
-
Dana Incorporated (Maumee, USA) — Strength: drivetrain component breadth and growing e-transmission capabilities. Strategic priority: push at the interface between axles and transmission to offer higher-value integrated modules for OEMs reducing supplier count.
-
Magna International (Aurora, Canada) — Strength: systems integration and DCT/e-drive units for LCVs. Strategic priority: focus on turnkey powertrain systems for start-ups and regional OEMs that prefer single‑vendor solutions.
Recent product and industry events that matter in 2026
-
Product launches: ZF’s 8-speed PowerLine implementation on medium-duty platforms (March 2026) and Eaton’s Advantor-6 automated manual introduction (Sept 2025) both illustrate OEM appetite for multi-speed and efficient automated systems in LCVs.
-
Electrification play: Key suppliers announced compact DCT and EV transmission modules in 2025, signaling a shift to platform architectures that support both conventional and electrified drivetrains.
-
Supply chain and trade: A 25% U.S. tariff on certain imported medium and heavy-duty parts effective November 2025 is reshaping sourcing economics and favoring onshore or near-shore production where volumes justify investment.
-
Materials risk: Volatility in steel and aluminum continues to pressure manufacturing margins—companies that move from reactive to hedged procurement and process efficiency will preserve pricing flexibility.
Practical strategic recommendations for 2026
-
Prioritize hybrid/electrified transmission development as a default: Allocate an explicit share of R&D roadmap budget to compact electrified modules and software-defined shift strategies to be selected by OEMs as optional packages.
-
Hedge supply chain risk with a layered approach: Implement a two‑tier sourcing strategy for critical metals, increase local content for U.S. programs exposed to tariffs, and create short-list second-source suppliers pre-approved through quality and cost gates.
-
Monetize installed base through aftermarket programs: Design service contracts and telematics-enabled maintenance offers for fleets to convert low-margin hardware to recurring revenue pools.
-
Use M&A and strategic alliances to fill capability gaps: Target bolt-on acquisitions that accelerate e-transmission know-how or strengthen local manufacturing footprints for tariff-impacted markets.
-
Adopt scenario-based portfolio allocation: Rebalance product and capital allocation across automatic, automated-manual and electrified platforms using our scenario models that stress-test demand under varying EV uptake and regulatory paths.
-
Embed cost-to-serve and TCO analysis into OEM negotiations: Present joint TCO cases for new transmission architectures to secure multi-year program commitments and avoid bidding on price alone.
The strategic value of PW Consulting’s deliverables
This deliverable is built as a tactical toolkit for 2026: ready-to-use Excel models, supplier scorecards, M&A screening matrices, and presentation-ready market narratives for executive committees. We translate market forecasts (base-year 2025, historical 2020–2025, forecast 2026–2032; currency: USD, unit: Million) into decision triggers and KPI thresholds that tell you when to accelerate, pause, or pivot. The analysis integrates regulatory scenarios, trade-policy impacts and raw-material stress tests so that procurement, product and corporate development teams can act cohesively.
Next step — why you should read the full report
This briefing intentionally highlights the strategic contours and actionable implications of our analysis while reserving the full set of segmented datasets, granular revenue splits, and detailed company benchmarking for the complete report. If you are responsible for product strategy, procurement, or M&A planning in 2026, the full report contains the segment-level exposure matrices, OEM-program maps, and downloadable financial models you will need to operationalize the recommendations described here.
Contact PW Consulting to obtain the full Light Commercial Vehicle Transmission Market report and the companion decision-support workbook. Use the intelligence now to ensure that investments and strategic moves made in 2026 position your business to capture the majority of upside through 2032.
For detailed analysis of this topic, please visit the official page: Light Commercial Vehicle Transmission Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Submarine AIP Market to Reach USD 509.21 Million by 2032 at 3.8% CAGR — Asia Pacific Tops with USD 195.75M in 2025
By pmarketresearch, 2026-07-01
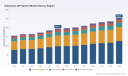
Submarine AIP System Market — Strategic Outlook for 2026: PW Consulting Report Preview
Executive snapshot
PW Consulting’s latest market study on Submarine Air-Independent Propulsion (AIP) systems provides a forward-looking intelligence product designed to inform procurement, industrial strategy, and investment decisions through 2032. The global Submarine AIP System market reached USD 392.21 Million (base year 2025) after a steady recovery from USD 312.45 Million in 2020. Our forecast shows continued expansion driven by fleet modernizations, retrofit programs and technology maturation, with a compound annual growth rate (CAGR) of 3.8% through the 2026–2032 horizon and a projected market size approaching USD 509.21 Million by 2032.
Submarine Aip System Market
Why this matters for 2026 decision-makers
- Naval planners: Choices made in 2026 about platform selection, retrofit timing and domestic capacity will lock in endurance and stealth capabilities for the next two decades.
- Prime contractors and Tier‑1 suppliers: Strategy on AIP technology bets (fuel cell topologies vs. Stirling vs. reforming solutions) and industrial partnerships will determine export competitiveness and margin pools.
- Component and materials suppliers: Supply‑chain exposure to specialty metals, hydrogen-storage media and oxygen systems requires active risk mitigation.
- Private investors and M&A teams: The market’s mid-single-digit CAGR and its concentration profile create niche consolidation and vertical-integration opportunities.
What the full PW Consulting report delivers
To support operational decision-making in 2026, the full report goes beyond headline numbers and offers hands-on tools built from primary research, supplier engagement and scenario modelling. Key deliverables include:
Submarine Aip System Market
- Proprietary market-sizing and demand curves (2020–2032) with sensitivity runs for procurement cycles and geopolitical shocks.
- A competition matrix that profiles incumbent and challenger companies by technology, integration capability, and service footprint.
- Procurement playbooks for navies and primes: specification checklists, qualification gates, and phased integration plans for new-build and retrofit pathways.
- Supplier assessment framework and TCO model: lifecycle cost drivers, retrofit cost bands, spares and sustainment models tailored to different AIP architectures.
- Supply-chain stress tests: concentration maps for critical inputs (metals, specialised hydrogen storage, oxygen systems) and mitigation levers for sourcing and stockholding.
- Regulatory and classification digest: mapping of certification paths, key testing requirements and classification society positions relevant to AIP installations.
- Strategic M&A and partnership shortlist: candidate targets and capability gaps for primes and suppliers looking to scale or diversify.
Market dynamics shaping the 2026 agenda
The AIP market sits at the intersection of naval doctrine, material science and international trade. Three dynamics will disproportionately shape 2026 decisions:
Submarine Aip System Market
- Technology diversification and hybridization: Fuel cells (PEM and evolving second-generation chemistries), Stirling engines and reforming-based solutions (including bioethanol approaches) coexist in the market. This multi-technology landscape favors modular platform integration strategies that preserve upgrade paths while controlling upfront risk.
- Supply‑chain constraints and raw‑material pressure: Specialized inputs—certain high-grade alloys, hydrogen storage media (metal hydrides and cryogenic systems) and liquid oxygen handling components—are cost and availability stress points. Western sanctions and restricted flows of strategic metals have already shifted supplier footprints and increased lead times for some propulsion components.
- Geopolitics and domestic capability drives: Several navies are accelerating indigenous AIP development to reduce strategic dependencies. Recent milestones (for example, the integration efforts reported by DRDO/Indian Navy in early 2026) validate that trend and create both domestic market demand and export-control considerations for capable suppliers.
Competitive landscape — profiles and strategic posture
The market demonstrates a moderate level of concentration: the top three suppliers account for a material share of industry revenues while the top five capture an even larger portion of market value—conditions that favor both scale and targeted niche plays. Key incumbents and their strategic positions are summarized below:
- Saab AB (Kockums) — Sweden ( https://www.saab.com): Renowned for Stirling-engine based AIP solutions, Saab’s integration heritage on classes such as Gotland and A26 positions it as a trusted partner where acoustic discretion and long-endurance submerged operations are priority requirements.
- thyssenkrupp Marine Systems (TKMS) — Germany ( https://www.thyssenkrupp-marinesystems.com): TKMS has operationalized PEM fuel-cell AIP architectures in collaboration with industrial partners; its ongoing export and domestic programs highlight the commercial traction of fuel-cell centric platforms.
- Siemens AG — Germany ( https://www.siemens.com): As a supplier of PEM modules and balance-of-plant expertise, Siemens acts as a technology multiplier for primes integrating fuel-cell AIP and is a key source of stack-level innovation and industrialization capability.
- Naval Group — France ( https://www.naval-group.com): With experience across MESMA and next‑generation fuel-cell systems and on-board reforming approaches, Naval Group exemplifies a multi-technology integrator able to tailor solutions to platform constraints.
- Hanwha Ocean — South Korea ( https://www.hanwhaocean.co.kr): An emergent exporter, Hanwha combines hybrid AIP systems with broader platform exports and recently passed notable design approvals, signaling strengthened competitiveness in the global tender pipeline.
- Navantia — Spain ( https://www.navantia.es): Developer of bioethanol processor-based approaches and active in collaborative international programs, Navantia represents alternative reforming pathways with unique logistics implications.
- China Shipbuilding Industry Corporation (CSIC) — China : A major domestic integrator producing AIP-capable submarines for its navy and export customers; its indigenization efforts are a factor in regional competition and technology diffusion dynamics.
Recent developments that change tactical priorities
- DRDO / Indian Navy reported an integration milestone for an indigenous fuel-cell AIP on a Kalvari-class platform in March 2026 — underscoring national priority for self-reliance.
- Hanwha Ocean achieved Approval in Principle for a 2,000-ton export submarine design with AIP capabilities in May 2026, following the launch of KSS‑III Batch‑II boats with hybrid AIP in late 2025 — a signal of accelerated export readiness.
- ThyssenKrupp Marine Systems secured follow‑on contracts in 2025 for PEM‑based AIP platforms, reaffirming the commercial demand for fuel-cell centric solutions across certain buyer segments.
Actionable 2026 recommendations — three strategic priorities
- De-risk supply chains now: Establish dual‑sourcing for critical alloys and long‑lead hydrogen handling components; consider strategic inventory for high‑value parts and accelerate qualification of alternative suppliers in lower‑risk jurisdictions.
- Design for modular upgradeability: Require modular AIP architecture in new contracts to enable phased insertion of next‑generation stacks or alternative energy carriers without hull redesigns, lowering retrofit costs and obsolescence risk.
- Invest in sustainment and retrofit capability: Service and refit revenue will be a growing value pool as fleets extend operational life. Build domestic refit capacity, train maintenance workforces, and establish OEM‑partnered spares frameworks to capture aftersales margins.
- Prioritize lifecycle cost, not first‑cost: Use PW Consulting’s TCO modelling to compare configurations under varied operational profiles — endurance, mission tempo and peacetime patrols influence the optimal technology mix more than headline procurement price.
- Leverage partnerships for capability gaps: Where internal R&D timelines are long, pursue joint ventures with proven integrators or licensing agreements for stack technology to shorten fielding timelines while preserving sovereign capability plans.
Methodology and confidence framework
The report synthesizes multi‑sourced evidence: procurement notices and classified tender records, OEM and supplier disclosures, primary interviews with program managers and shipyards, classification society guidelines, and proprietary supply‑chain mapping. Scenario analyses incorporate sensitivity to raw material cost shocks and geopolitical disruption. The base year is 2025 and the forecast window spans 2026–2032; topline projections are presented with probability-weighted scenarios to aid contingency planning.
Conclusion — the strategic value for 2026
For 2026 decision cycles, the Submarine AIP System market represents a modest but strategically significant arena where technology choices, supply‑chain resilience and integration capacity determine operational advantage. The sector’s steady growth and concentrated supplier base create clear chores for both incumbents and challengers: secure inputs, lock service revenues, and design platforms that can evolve. PW Consulting’s full report arms stakeholders with the quantitative forecasts, supplier intelligence and executable playbooks needed to turn 2026 decisions into sustained capability and commercial advantage.
Access the full analysis
This preview is intended to surface the strategic implications and practical levers contained in our full Submarine AIP System Market report. For the complete dataset, segmented analysis, procurement playbooks and the downloadable TCO models and scenario workbooks, please download the full report from PW Consulting’s report page or contact our defence and maritime practice leads to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Submarine Aip System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Reverse Osmosis Membranes Market to Rise from USD 7.9 Million in 2025 to USD 12.57 Million by 2032, Driven by 6.9% CAGR
By pmarketresearch, 2026-06-30
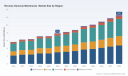
Reverse Osmosis Membranes Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
Executive preview
PW Consulting’s latest market study on Reverse Osmosis (RO) Membranes synthesizes five years of historical data (2020–2025) and provides a robust 2026–2032 forecast. The global market, measured in USD Million, expanded from approximately 5.7 in 2020 to 7.9 in 2025 and is projected to reach roughly 12.6 by 2032 at a compound annual growth rate (CAGR) of 6.9% over the forecast window. This growth context underpins a range of strategic decisions that water technology providers, system integrators, investors, and public utility planners must make in 2026. The following preview highlights how our analysis converts macro trajectory and industry dynamics into actionable choices—while reserving our full segmentation tables and granular financials for the complete report.
Reverse Osmosis Membranes Market
Why this market matters for 2026 strategic planning
-
Structural growth with pockets of acceleration: While the market shows steady compound growth, pockets of accelerated opportunity are emerging where regulatory pressure, industrial water reuse mandates, and desalination investments converge. These pockets are likely to outpace average growth and become focal points for capital deployment.
Reverse Osmosis Membranes Market -
Consolidation and concentration: Market concentration is notable—our analysis indicates that the top three suppliers control a majority of market share, and the top five extend that dominance significantly. For new entrants and niche specialists, this structure imposes strategic requirements around differentiation, channel partnerships, and scale economies.
Reverse Osmosis Membranes Market -
Technology and product evolution: Advances in thin-film composite and nanocomposite chemistries, element design (high-flux, low-fouling), and intelligent membrane monitoring are reshaping value propositions—shifting buyer emphasis from lowest-first-cost to lifecycle cost, water recovery, and regulatory compliance.
Data-driven decision levers
Three data-informed levers should drive boardroom debates in 2026:
-
Where to prioritize R&D and product roadmaps: Our historical-to-forecast trajectory demonstrates the commercial payoff of investing in salt-rejection efficiency, boron removal, and elements optimized for zero-liquid-discharge (ZLD) systems. Product programs that reduce energy intensity or enable higher recovery rates deliver measurable downstream benefits for large desalination and industrial reuse projects.
-
Supply-chain hedging and vertical integration: The 2025 period of raw-material price volatility (notably in high-grade polyester and polypropylene nonwovens) materially impacted manufacturing margins. Firms should evaluate hedging, dual-sourcing, and regional manufacturing footprints to mitigate cost oscillations.
-
Regulatory-driven demand capture: Enforceable contaminant limits and point-of-use standards are creating near-term procurement cycles in municipal and point-of-entry markets. Teams that align certification roadmaps and compliance support with sales strategies will capture outsized share as utilities accelerate upgrades.
Report practicalities: what the PW Consulting study delivers
Beyond headline forecasts, the full PW Consulting report is structured to support immediate operational decisions. Key deliverables include:
-
Actionable demand models: A bottom-up model calibrated to historical shipments and validated against company releases and procurement announcements—designed for scenario testing (base, downside, accelerated regulatory adoption).
-
Commercial playbooks: Go-to-market blueprints for suppliers targeting desalination, wastewater reuse, municipal utilities and industrial process water, including partner archetypes, channel economics and margin heat maps.
-
CapEx and manufacturing guidance: Benchmarks for unit economics across production scales, break-even analysis for greenfield lines, and a checklist for localization strategies in priority geographies.
-
Regulatory and standards tracker: A compendium of enacted and emerging regulations affecting membrane adoption—paired with recommended compliance timelines and certification priorities for manufacturers and system integrators.
-
Competitive matrix and M&A scan: Vendor positioning across technology, scale, and channel coverage, plus a readiness assessment for consolidation scenarios and potential alliance targets.
Competitive landscape: who to watch and why
The competitive field combines long-established global incumbents, specialty technology firms, and regional manufacturing leaders. Strategic takeaways from our company-level analysis:
-
DuPont Water Solutions (Wilmington, DE): A technology stalwart focused on product breadth across seawater, brackish and ZLD applications. Recent expansion of low-salt-rejection elements signals an intent to capture the high-value segment of minimal-liquid-discharge projects.
-
Toray Industries (Tokyo): Toray continues to invest in next-generation seawater desalination elements emphasizing salt and boron rejection—an investment that maps directly to large desalination EPCs and utility partners pursuing enhanced water quality targets.
-
LG Chem (Seoul): With its nanocomposite membrane portfolio and regional manufacturing partnerships, LG Chem is executing a hybrid strategy—technology differentiation plus localized production to serve fast-growing regional desalination markets.
-
SUEZ Water Technologies & Solutions (Paris): SUEZ couples high-flux membrane products with digital asset platforms for performance management—positioning itself for aftermarket and long-term service revenues.
-
Nitto Denko / Hydranautics (Osaka): Emphasizing energy-efficient removal of organics and drinking water applications, the firm is leveraging product introductions to expand into water treatment segments where regulatory detection limits are tightening.
-
Koch Separation Solutions (KSS) and AquaMem (United States): These suppliers focus on industrial and municipal spiral-wound and tubular designs and represent pragmatic partners for integration-sensitive projects.
-
Vontron (China) and Toyobo (Japan): Regional champions with automated production and high-performance offerings—relevant for companies evaluating cost-competitive sourcing or strategic joint ventures in Asia and adjacent markets.
Our report includes an objective performance matrix and a scenario-based view of how these vendors compete on technology, cost-to-serve, aftermarket services, and geographic reach.
Regulatory and market headwinds/ tailwinds
-
PFAS and contaminant regulation: Anticipated national-level rules (e.g., forthcoming PFAS limits in the U.S.) will accelerate demand for membrane-based solutions in municipal systems. Utilities facing enforceable maximum contaminant levels are likely to prioritize RO in treatment trains where activated carbon or ion exchange are insufficient.
-
Standards update: Revisions to installation and performance standards (including point-of-use certifications) increase the technical bar for manufacturers and installers—creating a competitive advantage for firms that invest in certified, turnkey solutions and third-party validation.
-
Incentives and localized policy: Targeted tax credits and installation incentives—illustrated by recent state-level measures—can materially alter project economics in underserved regions. Firms should maintain an active policy-monitoring capability to identify short-cycle procurement windows.
-
Raw material volatility: 2025 price swings for nonwoven supports underscore the need for input-cost monitoring, contractual flexibility, and potential backward integration for manufacturers with scale ambitions.
Strategic recommendations for 2026 (what boards and executive teams should do now)
Translate the market opportunity and risks into an executable roadmap with these prioritized actions:
-
Immediate (0–12 months):
-
Stress-test product portfolios for regulatory scenarios. Allocate fast-track funding to certify at-risk SKUs for updated point-of-use standards and contaminant removal requirements.
-
Secure critical supply lines and negotiate dual-sourcing contracts for nonwoven substrates and specialty polymers. Reprice product portfolios to reflect input-cost pass-throughs where contractually feasible.
-
Identify one pilot partnership with a large utility or industrial user to demonstrate lifecycle savings (energy, recovery, O&M) under new contaminant standards.
-
-
Near-term (12–36 months):
-
Invest in localized manufacturing capacity in priority regions where regional incentives and logistics economics favor onshore production. Consider brownfield upgrades before greenfield builds to shorten lead times.
-
Expand aftermarket and digital service offerings focused on predictive fouling management and performance guarantees—these services increase recurring revenue and stickiness with large buyers.
-
Pursue targeted M&A or JVs that fill technology gaps (e.g., boron removal, anti-fouling coatings) or provide immediate access to municipal sales channels.
-
-
Longer-term (3–7 years):
-
Shift R&D portfolios toward materials that deliver both energy and recovery gains while lowering life-cycle cost. Evaluate investments in hybrid membranes and integrated systems that enable higher-margin downstream services.
-
Build policy intelligence functions to influence standards and incentive programs; early involvement in standards development yields commercial advantages.
-
Develop flexible manufacturing modules that allow rapid capacity scaling to capture both steady baseline growth and episodic procurement spikes driven by regulation or large desalination awards.
-
Next steps and how PW Consulting supports execution
PW Consulting’s full Reverse Osmosis Membranes Market report provides the complete set of segmentation tables, regional demand forecasts, application-specific drivers, and vendor scorecards necessary to operationalize the recommendations above. In addition to the downloadable study, we offer tailored advisory packages—ranging from a two-week “market entry blueprint” to quarter-long capability-building engagements—that translate model outputs into executable business cases for capital allocation, partnership selection, and product roadmaps.
Closing note
The RO membrane market presents both predictable, steady expansion and high-variance pockets driven by regulation, regional policy, and technological differentiation. With global revenues approaching USD 8 Million in the base year and a mid-single-digit CAGR through 2032, 2026 is a pivotal year: companies that combine disciplined supply-chain resilience, targeted product investments, and alignment to new compliance cycles will define the competitive landscape for the remainder of the decade. For a comprehensive dataset, scenario models, and vendor-level strategic playbooks, access the full PW Consulting report and engage our advisory team to convert insight into market leadership.
For detailed analysis of this topic, please visit the official page: Reverse Osmosis Membranes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: UV Lasers Market Poised to Expand at 8.7% CAGR as Demand from Semiconductor and Medical Sectors Surges
By pmarketresearch, 2026-06-30
UV Lasers Market 2026: Strategic Signals for Executive Decision-Making
Executive snapshot
As a strategic advisor at PW Consulting, I present a high-level briefing of our latest UV Lasers Market study (base year 2025). The market has expanded from approximately USD 137.0 Million in 2020 to USD 188.0 Million in 2025 and is forecast to accelerate through the coming decade, reaching roughly USD 338.0 Million by 2032. This trajectory represents a compound annual growth rate of about 8.7% across the forecast horizon. For 2026 planning cycles, these macro dynamics convert into discrete strategic imperatives for product roadmap prioritization, capacity investment, channel strategy, and regulatory compliance.
UV Lasers Market
Why this matters for 2026 strategy
- Predictable growth envelope: Sustained mid-single-digit to high-single-digit CAGR gives boards the confidence to underwrite multi-year R&D programs targeted at UV-specific applications (deep UV lithography, micromachining, precision marking) while preserving optionality for faster pivots.
- Increasing technical differentiation: Breakthroughs in ultrafast pulses, wavelength stabilization, and compact deep-UV modules are shifting competition from commodity pricing to system performance, uptime, and application-specific integration.
- Regulatory and safety inflection: New standards and sectoral regulations are raising the bar for compliant deployment—turning what was once a cost center (safety, certification) into a market-access prerequisite and a source of competitive advantage.
What the market evolution tells us
The UV lasers market is maturing. The historical period (2020–2025) shows steady organic expansion driven by increased adoption in semiconductor microfabrication, precision medical devices, industrial marking, and advanced display processing. Looking forward to 2032, the forecast indicates both deeper penetration into existing applications and emergence of higher-value use cases—driven by ultrafast pulse capabilities and novel wavelength modules. These shifts favor suppliers that can offer end-to-end repeatability, minimal thermal load on substrates, and validated integrations for regulated industries.
UV Lasers Market
Practical, near-term actions for 2026
- Prioritize modular product architectures: OEMs and systems integrators should accelerate modularization—enabling faster wavelength swaps, plug-and-play safety enclosures, and serviceable power modules that reduce downtime and total cost of ownership.
- Embed compliance into design: Product development must incorporate regulatory testing and certification roadmaps (e.g., aerospace and medical standards). Early alignment reduces time-to-market friction and can command pricing premiums in safety-critical segments.
- De-risk supply chains: With demand rising, buyers should map critical subcomponents (nonlinear crystals, UV-grade fibers, diode pumps), identify single-source risks, and establish dual-sourcing or vertical partnerships before capacity shortages drive spot price volatility.
- Shift go-to-market toward solutions: Vendors should bundle lasers with validated process recipes, fixtures, and software analytics to move up the value chain—from component supplier to process partner.
- Invest selectively in photonics IP and service ecosystems: For strategics and financial sponsors, targeted M&A in laser control electronics, ultrafast pulse shaping, or specialized optics offers disproportionate leverage on product roadmaps.
Report highlights — what’s inside (practical, operational content)
Our full study is structured to support fast, board-level and operational decision-making. Key elements include:
UV Lasers Market
- Market sizing and trajectory models: A transparent, auditable topline model covering historical (2020–2025) and forecast (2026–2032) performance, with scenario variants for conservative, base, and accelerated adoption cases.
- Technology readiness and TRL mapping: Comparative assessment of major UV technologies (solid-state, fiber, excimer, diode-pumped solutions, ultrafast vs. nanosecond regimes) against performance, cost, and manufacturability metrics. This is presented as decision matrices and go/no-go thresholds for product roadmaps.
- Commercial playbooks: Channel strategies, pricing archetypes, MQL-to-deal conversion benchmarks, and service revenue levers for suppliers seeking to capture aftermarket and license revenues.
- Regulatory and standards compendium: Practical checklists and test protocols required for aerospace, medical, and industrial deployments—linking standards to certification steps and expected timelines.
- Supply chain heatmaps and sourcing playbooks: Component concentration analyses, supplier scorecards, and recommended strategies for redundancy and nearshoring where warranted.
- Financial scenarios and investment cases: Capex/Opex modeling templates, NPV sensitivity runs, and break-even timelines for common investment archetypes (capacity expansion, new wavelength lines, service network rollouts).
- Actionable use-case dossiers: End-user process validation guides for semiconductor, medical, marking, and other prioritized segments—complete with expected yield improvements, cycle-time impact estimates, and key integration risks.
Because this publication follows a “trailer” design, the full segmented revenue tables, geographic and application splits, and the granular unit economics are available exclusively in the paid report and through our client portal.
Competitive landscape — who’s shaping the next wave
The market structure is moderately concentrated: the top three suppliers capture approximately two-thirds of market revenues, while the top five approach three-quarters of the market—indicating strong incumbents with meaningful scale advantages. Competitive dynamics are now defined less by raw output and more by system-level performance, service availability, and validated application expertise.
- Coherent Corp. — A leader in high-energy deep-UV systems tailored to semiconductor lithography and display processing. Recent launches demonstrate a push toward wavelength-stabilized, high-power platforms that aim to reduce variability in critical process windows.
- TRUMPF — Focused on precision short-pulse UV sources for marking and sensitive substrates; their architecture emphasizes gentle, air-cooled operations suited for high-throughput production lines.
- IPG Photonics — Investing in ultrafast and deep-UV fiber solutions with a clear slant toward reliability and uptime—critical for micro-machining and inspection markets. Their showings at recent industry events signal readiness to scale module-level offerings.
- Han’s Laser — Maintaining strong presence in industrial marking and engraving with broad product accessibility, including handheld solutions. Their trade-show activity underlines continued focus on intelligent, factory-ready systems.
- Lumentum — Concentrating on nanosecond Q-switched platforms for micromachining and high-stability industrial applications; recent product showcases underline throughput and micro-processing performance improvements.
- Amplitude Laser, MKS (Spectra-Physics), DPSS/Laserax — These firms advance specialized niches—ultrafast femtosecond offerings, high-speed marking, and certified workstations respectively—each providing potential partnership or acquisition targets based on corporate strategy.
Recent industry developments to watch (implications for 2026)
- IPG Photonics and Lumentum showcased new high-precision deep UV and ultrafast platforms at SPIE Photonics West 2026—signaling accelerated commercialization of higher-power, application-ready modules. Buyers should expect availability of more compact, higher-throughput units in 2026–2027.
- Coherent’s March 2026 launch of a wavelength-stabilized deep UV system highlights vendor competition at the lithography and display processing frontier. This raises the bar for suppliers addressing sub-micron process windows.
- Han’s Laser and other assembly-line-focused vendors are positioning smarter, more connected marking systems at major trade shows—indicating a shift toward integrated factory deployments where laser performance is coupled with process analytics.
- Standards activity (e.g., aerospace wiring marking requirements and safer Class 1 workstation certifications) is increasing the compliance burden—but also creating opportunities for “compliant-by-design” products that simplify customer procurement and audit trails.
Risk map and mitigation priorities
- Technology obsolescence risk: Shorten development cycles via modular platforms and incremental upgrades rather than monolithic single-version releases.
- Supply concentration: Source critical optics and pump diodes from multiple qualified suppliers; consider component stockpiles for planned ramp phases.
- Regulatory delay: Build certification timelines into go-to-market plans; pursue joint validation pilots with anchor customers to accelerate approvals.
- Customer adoption lag: Offer pilot-as-a-service programs to demonstrate value and reduce procurement friction.
How PW Consulting helps
Our report is designed to be immediately actionable for CFOs, CTOs, VP Product, and corporate development teams. We combine quantitative market models, legal/regulatory mapping, competitive benchmarking, and executable commercial playbooks. For organizations preparing capital budgets or strategic roadmaps for 2026, the study provides tailored scenario outputs and a suite of templates that compress decision cycles from months to weeks.
Next step — where to go for full intelligence
This briefing intentionally presents the strategic contours and executable implications while omitting detailed subsegment tables and proprietary financial matrices. For the full dataset—region and application splits, wavelength and technology revenue breakdowns, unit economics, and downloadable modeling files—please visit our report landing page. Engaging with the full report will equip your leadership team with the granular inputs required to finalize 2026 capital allocations, product launch sequencing, and M&A screening criteria.
For tailored briefings, model walkthroughs, or scenario workshops focused on your role in the UV lasers ecosystem, PW Consulting offers executive workshops and bespoke modeling services to turn this market intelligence into immediate competitive advantage.
For detailed analysis of this topic, please visit the official page: UV Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Lab Balance Market to Reach USD 3.25 Billion by 2032
By pmarketresearch, 2026-06-30
Lab Balance Market 2026: Strategic Imperatives from PW Consulting’s Lab Balance Market Report
PW Consulting today releases a focused preview of its Lab Balance Market report, offering senior executives, procurement leaders, and R&D heads a high-confidence strategic compass for decisions in 2026. The global lab balance market—anchored in a detailed 2020–2025 historical analysis and a 2026–2032 forecast—has moved from USD 1.85 Billion in 2020 to USD 2.36 Billion in 2025 and is projected to reach approximately USD 3.25 Billion by 2032, representing a forecast compound annual growth rate (CAGR) of roughly 4.7% across the outlook period. This release highlights the practical implications of those trends while intentionally withholding the granular segment-level data to encourage direct engagement with the full report and underlying models.
Lab Balance Market
Why this matters for 2026 decision-making
2026 is an uncommon inflection year for laboratory measurement equipment. Regulatory changes, accelerating digital workflows, and concentrated vendor dynamics combine to transform procurement, validation, and service economics. Organizations that treat lab balances as transactional consumables risk non-compliance, downtime, and surprise capital requirements. By contrast, teams that align procurement strategy with site-specific measurement uncertainty, lifecycle service models, and data integrity expectations will unlock lower total cost of ownership and faster regulatory acceptance.
Lab Balance Market
Market trajectory and what drives it
-
Measured, resilient expansion: The market has exhibited steady recovery and growth since 2020, reflected in the rise from USD 1.85 Billion to USD 2.36 Billion by 2025, and a forecast path to roughly USD 3.25 Billion by 2032. Underneath this topline increase are two durable forces: regulatory-driven equipment refresh cycles in regulated industries, and modernization investments in research and manufacturing labs.
Lab Balance Market -
Regulation as a demand accelerator: Revised pharmacopeial and regulatory expectations have created a near-term compliance wave that affects purchase timing, specification stringency, and qualification budgets.
-
Technology and services convergence: Advances in sensor design, electromagnetic compensation technologies, connectivity, and on-board diagnostics are shifting vendor competition away from price-only strategies toward integrated hardware + software + services offerings.
Regulatory inflection points and operational impact
-
USP and regional pharmacopeias: The revisions to USP Chapters 41 and 1251—finalized in mid‑2025 and effective February 1, 2026—redefine minimum sample weight determination by tying it to site-specific repeatability rather than manufacturer catalog claims. European Pharmacopoeia Chapter 2.1.7 remains an active compliance baseline in Europe. These changes have immediate consequences for qualification protocols, acceptance testing, and supplier claims validation.
-
Enforcement and traceability: Regulatory bodies, including the FDA under existing statutes, are treating the revised chapters as required for drug manufacturing and quality control processes. At the same time, ISO/IEC 17025-accredited calibration certificates and recognized procedures (EURAMET cg-18, ASTM E898) remain the operational standard for traceability and estimating measurement uncertainty.
-
Practical consequences: Expect increased spend on site-specific repeatability studies, expanded qualification packs, more frequent accredited calibrations, and heightened scrutiny of vendor documentation and software audit trails.
Competitive landscape: concentration and vendor positioning
The lab balance market is moderately concentrated: the three largest vendors account for a significant share of market revenue, and the top five firms represent an even larger portion, creating structural advantages around scale, distribution reach, and service networks. That concentration changes negotiation dynamics for mid‑market buyers and elevates the importance of supplier risk management for large enterprises.
-
Sartorius (Göttingen, Germany) — Sartorius has positioned its Cubis II modular platform as a compliance-first solution. The company emphasizes configurability and pharma‑grade qualification support, aligning product development to the revised USP and pharmacopoeial demands. Recent product and regulatory milestones underscore a push to integrate validation workflows directly with hardware capabilities.
-
Mettler‑Toledo (Columbus, Ohio, USA) — Mettler‑Toledo’s XPR, MS‑TS, and MR series focus on electromagnetic force compensation and robust internal adjustment features, with recent portfolio consolidation and upgrades emphasizing connectivity and sensor improvements. Their product strategy targets laboratories that prioritize repeatability, automated adjustment, and compatibility with updated pharmacopeial requirements.
-
OHAUS Corporation (Pine Brook, New Jersey, USA) — OHAUS emphasizes operational ergonomics—motorized leveling, touchless sensors, static mitigation features—and automated calibration to streamline high‑precision workflows in teaching and industrial environments.
-
RADWAG (Poland) — RADWAG’s recognition in independent awards for moisture analyzers and industrial scales signals a reputation for performance and value in both lab and industrial contexts. Awards and product recognition serve as a trust signal for procurement teams weighing non‑legacy suppliers.
-
A&D Company (Tokyo, Japan) — A&D focuses on precision balances with integrated ionization and fanless designs to control static in demanding environments, aligning products to labs where environmental control is limited or variable.
Together, these vendor strategies reveal two competing architectures: highly configurable, compliance-oriented platforms designed for regulated pharmaceutical and biopharma customers versus streamlined, cost‑efficient balances optimized for academic, environmental, and food testing labs. Both types will coexist; the choice depends on site risk profile, regulatory exposure, and lifecycle cost tolerance.
Actionable recommendations for 2026
-
Run site‑level repeatability audits now: Because minimum sample weight and acceptance criteria are now tied to site performance, procurement should not rely on catalog specifications alone. Conduct rapid repeatability studies across representative bench locations to inform acceptance thresholds and MZW calculations.
-
Reframe procurement as lifecycle procurement: Prioritize vendor ecosystems that include qualification documentation, secure connectivity, and predictable calibration schedules with ISO/IEC 17025 traceability. Short‑term capex savings can be eclipsed by the cost of re‑qualification and compliance failures.
-
Segment investment by risk profile: Reserve premium, configurable units for processes with the highest regulatory exposure and sample criticality; deploy validated, high‑value economy units in low‑risk applications. Our full report models multiple buy‑mix scenarios and TCO outcomes to inform this phasing—detailed tables and supplier scorecards are available in the complete dataset.
-
Strengthen calibration and service partnerships: Build formal SLAs with accredited calibration providers and ensure calibration certificates and uncertainty budgets are ingested into asset management systems for audit readiness.
-
Prepare for integration and data governance: As balances gain connectivity, include them in cybersecurity and data integrity assessments. Look for vendor support for electronic records, audit trails, and secure transfer protocols to meet 21 CFR Part 11 expectations where applicable.
-
Stress‑test supplier continuity: Given market concentration, include alternate‑supplier strategies and evaluate cross‑qualification paths to avoid lengthy qualification cycles in the event of supplier disruption.
What the PW Consulting report delivers (operational highlight)
The full Lab Balance Market report offers the toolkit senior leaders need to translate macro trends into executable plans. Key practical deliverables include:
-
Comprehensive market sizing and a seven‑year forecast with sensitivity scenarios aligned to regulatory and tech adoption inflection points;
-
Vendor scorecards that assess product features, compliance readiness, service footprint, and integration maturity;
-
Procurement playbooks and TCO models for phased replacement versus opportunistic upgrades;
-
Calibration and qualification cost models that map to ISO/IEC 17025, EURAMET, and ASTM best practices;
-
Decision matrices for lab managers to select balances by risk class, including sample‑weight driven acceptance criteria templates;
-
Market concentration analysis and supplier risk frameworks that inform sourcing and M&A diligence.
How to use this preview
Consider this release a strategic preview: it outlines the regulatory, competitive, and operational contours that will shape vendor selection and capital planning in 2026. We intentionally withhold detailed segment share tables, regional and application‑level splits, and granular price curves to preserve the integrated, model‑driven value of the full report. Those datasets are essential when constructing procurement RFIs, calibrating qualification budgets, or designing an MRO plan tied to site‑specific uncertainty metrics.
Next steps for leaders
-
Schedule a PW Consulting briefing to run your site‑level repeatability assessment against our models;
-
Request the full report and dataset to access supplier scorecards, regional channel maps, and the downloadable qualification templates required for regulatory submissions;
-
Engage with our advisory team for bespoke procurement roadmaps or to stress‑test vendor contracts under revised pharmacopeial requirements.
PW Consulting’s Lab Balance Market report is designed to convert market intelligence into executable actions. For compliance‑driven organizations and methodically run research labs alike, the right balance decision in 2026 will reduce audit risk, lower lifetime costs, and accelerate time‑to‑value. Visit our website to access the full report, proprietary models, and vendor datasets. Detailed segment and pricing data are available exclusively in the full report to support procurement and validation teams with audited inputs necessary for regulatory filings and capital planning.
For detailed analysis of this topic, please visit the official page: Lab Balance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com