

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Large Power Transformers Market Hits USD 25,050 Million in 2025, Poised for Further Growth

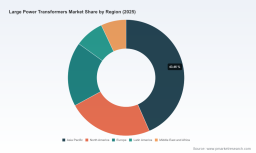
Large Power Transformers Market 2026 Strategic Brief: Navigating Long Lead Times, Localization Pressures, and a Rising Supply-Cost Environment
PW Consulting — As the global energy transition accelerates and electrification demands intensify across utilities, renewables, data centers and heavy industry, decision-makers in 2026 face a singular procurement reality: large power transformers (LPTs) sit at the intersection of strategic grid resilience and complex industrial supply chains. Our new Large Power Transformers Market report (base year 2025; forecast 2026–2032) synthesizes five years of historical dynamics (2020–2025) and provides scenario-driven guidance to inform capital planning, supplier strategy and risk mitigation for the next investment cycle.
Large Power Transformers Market
Why this report matters for 2026 corporate decisions
-
Macro clarity at a decisive moment — The global LPT market, which expanded through the early 2020s and reached an estimated USD 25,050 million in 2025, is forecast to continue growing through 2032. Our model projects a compound annual growth rate (CAGR) of 4.85% across the forecast window, reflecting sustained demand for transmission and distribution assets driven by renewables integration, grid modernization, and industrial electrification.
Large Power Transformers Market -
Operational urgency driven by lead times — Industry data show average LPT lead times near 128 weeks, with some orders stretching well beyond 210 weeks. For procurement and project planning teams this is not an abstract metric; it directly impacts project kickoffs, contingency allowances, and supplier contracting strategies for equipment that often represents a single-point-of-failure in mission-critical networks.
Large Power Transformers Market -
Supply-side concentration plus import dependencies — The market exhibits meaningful aggregation: the top three suppliers control a substantial share, and the top five approach a majority position. Coupled with high reliance on imported components and limited domestic GOES capacity in several major markets, buyer leverage is evolving into bargaining complexity rather than simple price competition.
-
Price and materials pressure — Since 2019 the sector has seen sharp upstream price movements (notably a ~77% increase in power transformer unit price metrics and material pressures on copper and GOES). These dynamics demand active procurement hedging, long-lead contract structuring, and closer supplier collaboration to manage total cost of ownership.
What PW Consulting’s report delivers — the practical toolkit
-
Forward-looking market sizing and scenarios: A transparent, auditable market model that extends from our 2025 baseline through 2032, combining top‑down drivers (demand centers such as transmission expansion and data center growth) with bottom-up supplier capacity overlays. We include best-, base- and downside scenarios to stress-test capex plans.
-
Procurement playbooks for long lead items: Actionable contract templates, risk allocation matrices and timing playbooks that translate a 128+ week average lead time into milestone-driven procurement timelines — from RFQ to factory acceptance testing and site commissioning.
-
Supplier scorecards and “fit-for-purpose” selection frameworks: Operational and strategic KPIs for evaluating global and regional OEMs, including capability on EHV/HVDC designs, domestic manufacturing footprints, service & maintenance networks, and warranty & spare-parts ecosystems.
-
Supply-chain resilience analytics: Stress tests showing sensitivity to GOES and copper price shocks, single-supplier risk, and cross-border logistics disruptions. We provide recommended mitigations — dual sourcing thresholds, strategic inventory buffering, and partnership vs. vertical-integration decision trees.
-
M&A and partnership watchlist: Identification of acquisition targets, JV candidates and capacity‑build partners across regions most likely to accelerate localization efforts or broaden technical capabilities.
-
Regulatory and policy implications: Assessment of localization incentives, domestic content regimes and strategic procurement policy that are reshaping sourcing decisions, with practical guidance for government-engaged procurement teams.
Competitive landscape — synthesis and implications
The LPT supplier universe is active on multiple fronts: capacity expansion in North America, strategic investments in HVDC and EHV capability, and renewed focus on domestic production. Key incumbent and challenger OEMs reviewed in the report include Hitachi Energy, Siemens Energy, GE Vernova (including Prolec GE operations), Hyundai Electric, Virginia Transformer Corporation, WEG, Delta Star, Pennsylvania Transformer Technology, SPX Transformer Solutions and Eaton. Our analysis combines public announcements, facility footprints, product roadmaps and service-network depth to deliver supplier-by-supplier implications for buyers.
-
Hitachi Energy (Zurich) — Investing heavily in North America with a significant new U.S. facility announced in 2025 and capacity expansion programs in Canada. The firm’s strength in HVDC and grid-integration technologies makes it a strategic partner for utilities pursuing long-distance renewable transmission and converter stations.
-
Siemens Energy (Munich) — Entering domestic U.S. LPT manufacturing with a planned Charlotte, NC plant. Siemens’ local production, targeted for ramp-up in the 2026–2027 window, will be an important option for buyers prioritizing near-sourcing and reduced logistics exposure.
-
GE Vernova (Cambridge) — Through Prolec GE partnerships and U.S. operations, GE brings scale for utility-scale projects and grid modernization programs, supported by deep engineering capabilities and project execution experience.
-
Regional and specialized suppliers — A cohort of North American manufacturers (including Virginia Transformer Corporation, Delta Star, Pennsylvania Transformer Technology, SPX, and Eaton) continues to provide custom solutions, rapid-service networks and tailored lifecycle services that matter for time-critical replacements and OEM-backed refurbishments.
-
Global challengers with U.S. commitments — Hyundai Electric and WEG are increasing North American manufacturing footprints, reflecting a broader industry pivot: OEMs are responding to procurement preferences and policy incentives with local capacity investments.
Importantly, recent developments underscore this strategic shift: Hitachi Energy’s September 2025 investment announcements included a major U.S. facility commitment and a near‑tripling of production capacity in Canada; Siemens Energy signaled large-scale hiring at its Charlotte plant in February 2026 as part of an expanded investment program. These moves materially alter supply options for U.S. and regional buyers over the medium term — but they will not erase lead-time constraints overnight.
Market dynamics and structural constraints
-
Material bottlenecks — Domestic GOES (grain‑oriented electrical steel) production in the U.S. remains constrained; U.S. production historically supplies a minority share of demand with a single active domestic producer in recent years. The report quantifies the systemic exposure that results when an essential material has limited onshore supply and long replenishment timelines.
-
Price inflation and pass-through risks — The sector has experienced significant unit price increases since 2019, reflecting upstream cost pressures and capacity tightness. For capex planners, this means tender timing and escalation clauses must be reassessed; fixed-price procurement can carry material risk if not hedged appropriately.
-
Demand drivers compressing supply — Rapid data center deployment, renewable interconnection queues and grid-reliability upgrades coincide, creating demand clustering that exacerbates existing production bottlenecks and extends lead times.
Strategic recommendations for 2026 decision-makers
-
Lock in supply early for critical-path transformers: For projects with non-flexible commissioning dates, initiate procurement 24–36 months before the earliest deliverable milestone and incorporate staged payments tied to factory acceptance.
-
Adopt a layered sourcing strategy: Combine domestic suppliers for critical spares and short‑cycle replacements with global OEMs for large, custom HV/EHV units. Build contractual mechanisms for capacity reservation where feasible.
-
Pursue collaborative supplier investments selectively: Consider equity‑light capacity commitments, capacity reservation agreements or co‑funded tooling to accelerate near‑term delivery and reduce price volatility exposure.
-
Revise TCO models to include lead‑time risk and materials exposure: Traditional TCO approaches underweight operational availability and replacement risk; our recommended models embed price scenarios, lead-time variability and failure‑mode probabilities.
-
Engage on policy and industry coordination: For national grids and large consortium buyers, lobbying for strategic reserves of GOES, incentives for domestic production and coordination of procurement windows can smooth demand peaks and shorten effective lead times.
What remains behind the curtain — and where to find it
Consistent with the “trailer” principle, this release outlines the strategic contours and core takeaways of PW Consulting’s Large Power Transformers report while preserving proprietary segmentation and granular supplier scorecards that underpin our recommendations. Detailed regional demand splits, unit‑type trajectories, application-level forecasts and supplier-level capacity tables are intentionally excluded here to preserve the analytic value of the full report.
Clients who require the full dataset — including detailed geography-by-application forecasts, unit-size mix, supplier capacity by factory and a downloadable procurement playbook — should consult the complete report and accompanying Excel model available through PW Consulting’s market intelligence portal.
Concluding perspective
As the 2026 investment cycle unfolds, large power transformers will remain a strategic chokepoint for grid resilience and electrification programs. The sector’s combination of long lead times, material concentration and accelerating demand requires buyers to rethink procurement cadence, supplier partnerships and risk allocation mechanisms. PW Consulting’s report aims to convert uncertainty into a disciplined set of actions — enabling executives to prioritize investments, align procurement timelines with project delivery, and make defensible choices about localization, inventory and strategic partnerships.
To explore how these insights apply to your capital program, supply-chain strategy or M&A roadmap, request the full Large Power Transformers Market report and model from PW Consulting’s research desk.
For detailed analysis of this topic, please visit the official page: Large Power Transformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com