

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Reverse Osmosis Membranes Market to Rise from USD 7.9 Million in 2025 to USD 12.57 Million by 2032, Driven by 6.9% CAGR

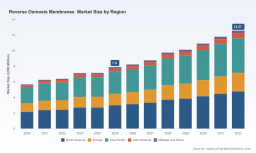
Reverse Osmosis Membranes Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
Executive preview
PW Consulting’s latest market study on Reverse Osmosis (RO) Membranes synthesizes five years of historical data (2020–2025) and provides a robust 2026–2032 forecast. The global market, measured in USD Million, expanded from approximately 5.7 in 2020 to 7.9 in 2025 and is projected to reach roughly 12.6 by 2032 at a compound annual growth rate (CAGR) of 6.9% over the forecast window. This growth context underpins a range of strategic decisions that water technology providers, system integrators, investors, and public utility planners must make in 2026. The following preview highlights how our analysis converts macro trajectory and industry dynamics into actionable choices—while reserving our full segmentation tables and granular financials for the complete report.
Reverse Osmosis Membranes Market
Why this market matters for 2026 strategic planning
-
Structural growth with pockets of acceleration: While the market shows steady compound growth, pockets of accelerated opportunity are emerging where regulatory pressure, industrial water reuse mandates, and desalination investments converge. These pockets are likely to outpace average growth and become focal points for capital deployment.
Reverse Osmosis Membranes Market -
Consolidation and concentration: Market concentration is notable—our analysis indicates that the top three suppliers control a majority of market share, and the top five extend that dominance significantly. For new entrants and niche specialists, this structure imposes strategic requirements around differentiation, channel partnerships, and scale economies.
Reverse Osmosis Membranes Market -
Technology and product evolution: Advances in thin-film composite and nanocomposite chemistries, element design (high-flux, low-fouling), and intelligent membrane monitoring are reshaping value propositions—shifting buyer emphasis from lowest-first-cost to lifecycle cost, water recovery, and regulatory compliance.
Data-driven decision levers
Three data-informed levers should drive boardroom debates in 2026:
-
Where to prioritize R&D and product roadmaps: Our historical-to-forecast trajectory demonstrates the commercial payoff of investing in salt-rejection efficiency, boron removal, and elements optimized for zero-liquid-discharge (ZLD) systems. Product programs that reduce energy intensity or enable higher recovery rates deliver measurable downstream benefits for large desalination and industrial reuse projects.
-
Supply-chain hedging and vertical integration: The 2025 period of raw-material price volatility (notably in high-grade polyester and polypropylene nonwovens) materially impacted manufacturing margins. Firms should evaluate hedging, dual-sourcing, and regional manufacturing footprints to mitigate cost oscillations.
-
Regulatory-driven demand capture: Enforceable contaminant limits and point-of-use standards are creating near-term procurement cycles in municipal and point-of-entry markets. Teams that align certification roadmaps and compliance support with sales strategies will capture outsized share as utilities accelerate upgrades.
Report practicalities: what the PW Consulting study delivers
Beyond headline forecasts, the full PW Consulting report is structured to support immediate operational decisions. Key deliverables include:
-
Actionable demand models: A bottom-up model calibrated to historical shipments and validated against company releases and procurement announcements—designed for scenario testing (base, downside, accelerated regulatory adoption).
-
Commercial playbooks: Go-to-market blueprints for suppliers targeting desalination, wastewater reuse, municipal utilities and industrial process water, including partner archetypes, channel economics and margin heat maps.
-
CapEx and manufacturing guidance: Benchmarks for unit economics across production scales, break-even analysis for greenfield lines, and a checklist for localization strategies in priority geographies.
-
Regulatory and standards tracker: A compendium of enacted and emerging regulations affecting membrane adoption—paired with recommended compliance timelines and certification priorities for manufacturers and system integrators.
-
Competitive matrix and M&A scan: Vendor positioning across technology, scale, and channel coverage, plus a readiness assessment for consolidation scenarios and potential alliance targets.
Competitive landscape: who to watch and why
The competitive field combines long-established global incumbents, specialty technology firms, and regional manufacturing leaders. Strategic takeaways from our company-level analysis:
-
DuPont Water Solutions (Wilmington, DE): A technology stalwart focused on product breadth across seawater, brackish and ZLD applications. Recent expansion of low-salt-rejection elements signals an intent to capture the high-value segment of minimal-liquid-discharge projects.
-
Toray Industries (Tokyo): Toray continues to invest in next-generation seawater desalination elements emphasizing salt and boron rejection—an investment that maps directly to large desalination EPCs and utility partners pursuing enhanced water quality targets.
-
LG Chem (Seoul): With its nanocomposite membrane portfolio and regional manufacturing partnerships, LG Chem is executing a hybrid strategy—technology differentiation plus localized production to serve fast-growing regional desalination markets.
-
SUEZ Water Technologies & Solutions (Paris): SUEZ couples high-flux membrane products with digital asset platforms for performance management—positioning itself for aftermarket and long-term service revenues.
-
Nitto Denko / Hydranautics (Osaka): Emphasizing energy-efficient removal of organics and drinking water applications, the firm is leveraging product introductions to expand into water treatment segments where regulatory detection limits are tightening.
-
Koch Separation Solutions (KSS) and AquaMem (United States): These suppliers focus on industrial and municipal spiral-wound and tubular designs and represent pragmatic partners for integration-sensitive projects.
-
Vontron (China) and Toyobo (Japan): Regional champions with automated production and high-performance offerings—relevant for companies evaluating cost-competitive sourcing or strategic joint ventures in Asia and adjacent markets.
Our report includes an objective performance matrix and a scenario-based view of how these vendors compete on technology, cost-to-serve, aftermarket services, and geographic reach.
Regulatory and market headwinds/ tailwinds
-
PFAS and contaminant regulation: Anticipated national-level rules (e.g., forthcoming PFAS limits in the U.S.) will accelerate demand for membrane-based solutions in municipal systems. Utilities facing enforceable maximum contaminant levels are likely to prioritize RO in treatment trains where activated carbon or ion exchange are insufficient.
-
Standards update: Revisions to installation and performance standards (including point-of-use certifications) increase the technical bar for manufacturers and installers—creating a competitive advantage for firms that invest in certified, turnkey solutions and third-party validation.
-
Incentives and localized policy: Targeted tax credits and installation incentives—illustrated by recent state-level measures—can materially alter project economics in underserved regions. Firms should maintain an active policy-monitoring capability to identify short-cycle procurement windows.
-
Raw material volatility: 2025 price swings for nonwoven supports underscore the need for input-cost monitoring, contractual flexibility, and potential backward integration for manufacturers with scale ambitions.
Strategic recommendations for 2026 (what boards and executive teams should do now)
Translate the market opportunity and risks into an executable roadmap with these prioritized actions:
-
Immediate (0–12 months):
-
Stress-test product portfolios for regulatory scenarios. Allocate fast-track funding to certify at-risk SKUs for updated point-of-use standards and contaminant removal requirements.
-
Secure critical supply lines and negotiate dual-sourcing contracts for nonwoven substrates and specialty polymers. Reprice product portfolios to reflect input-cost pass-throughs where contractually feasible.
-
Identify one pilot partnership with a large utility or industrial user to demonstrate lifecycle savings (energy, recovery, O&M) under new contaminant standards.
-
-
Near-term (12–36 months):
-
Invest in localized manufacturing capacity in priority regions where regional incentives and logistics economics favor onshore production. Consider brownfield upgrades before greenfield builds to shorten lead times.
-
Expand aftermarket and digital service offerings focused on predictive fouling management and performance guarantees—these services increase recurring revenue and stickiness with large buyers.
-
Pursue targeted M&A or JVs that fill technology gaps (e.g., boron removal, anti-fouling coatings) or provide immediate access to municipal sales channels.
-
-
Longer-term (3–7 years):
-
Shift R&D portfolios toward materials that deliver both energy and recovery gains while lowering life-cycle cost. Evaluate investments in hybrid membranes and integrated systems that enable higher-margin downstream services.
-
Build policy intelligence functions to influence standards and incentive programs; early involvement in standards development yields commercial advantages.
-
Develop flexible manufacturing modules that allow rapid capacity scaling to capture both steady baseline growth and episodic procurement spikes driven by regulation or large desalination awards.
-
Next steps and how PW Consulting supports execution
PW Consulting’s full Reverse Osmosis Membranes Market report provides the complete set of segmentation tables, regional demand forecasts, application-specific drivers, and vendor scorecards necessary to operationalize the recommendations above. In addition to the downloadable study, we offer tailored advisory packages—ranging from a two-week “market entry blueprint” to quarter-long capability-building engagements—that translate model outputs into executable business cases for capital allocation, partnership selection, and product roadmaps.
Closing note
The RO membrane market presents both predictable, steady expansion and high-variance pockets driven by regulation, regional policy, and technological differentiation. With global revenues approaching USD 8 Million in the base year and a mid-single-digit CAGR through 2032, 2026 is a pivotal year: companies that combine disciplined supply-chain resilience, targeted product investments, and alignment to new compliance cycles will define the competitive landscape for the remainder of the decade. For a comprehensive dataset, scenario models, and vendor-level strategic playbooks, access the full PW Consulting report and engage our advisory team to convert insight into market leadership.
For detailed analysis of this topic, please visit the official page: Reverse Osmosis Membranes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com