

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Light Commercial Vehicle Transmission Market Poised for 5.71% CAGR Through 2032

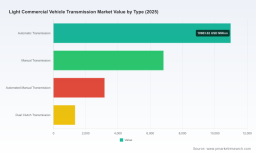
Light Commercial Vehicle Transmission Market: A Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market study on Light Commercial Vehicle (LCV) transmissions equips senior executives and strategy teams with the forward-looking intelligence needed to make confident 2026 investments. The global LCV transmission market is standing at an inflection point: after expanding to approximately USD 22,320 Million in 2025, our modeling projects continued expansion through the forecast window (2026–2032) at a compound annual growth rate (CAGR) of 5.71%, culminating in a market above USD 32,900 Million by 2032. These headline numbers frame a market that is neither commoditized nor closed—competition and consolidation coexist, and the right strategic moves in 2026 will materially change competitive trajectories through the end of the decade.
Light Commercial Vehicle Transmission Market
Why this report matters for 2026
-
Timing: 2026 is the year when regulatory pressure, tariff shifts and the first wave of compact electrified powertrain rollouts converge with fleet replacement cycles. Decisions taken now on R&D prioritization, supply chain reconfiguration, and partner selection will determine market share through 2030.
Light Commercial Vehicle Transmission Market -
Actionability: Beyond forecasts, the report delivers executable playbooks—product roadmaps, supplier risk matrices, and pricing sensitivity models—built to be used by product, purchasing and M&A teams during budget cycles and board discussions.
Light Commercial Vehicle Transmission Market -
Clarity: We synthesize historical trends (2020–2025) and scenario-tested forecasts (2026–2032) in USD (Millions), so senior finance teams can plug findings directly into corporate planning models and investment committees.
What the report contains (practical, decision-grade content)
-
Market sizing and scenario forecasts: Base-year (2025) sizing, historical trajectory (2020–2025), and three scenario tracks to 2032 that incorporate differing EV adoption, regulatory tightening and trade-policy outcomes.
-
Technology and product roadmaps: Comparative TCO and efficiency modeling for automatic, manual, automated-manual, dual-clutch and electrified transmission solutions—presented in formats you can use to re-rank R&D and capex projects.
-
Competitive intelligence and capability mapping: A strategic profile for incumbent and challenger suppliers, including capability heatmaps (manufacturing scale, hybrid/e-drive competence, service networks) and supplier scorecards.
-
Supply chain and raw-material stress-testing: Inputs and tools to quantify margin pressure from steel and aluminum volatility, inventory hedging strategies, and alternative sourcing scenarios under tariff regimes.
-
Commercial and aftermarket playbooks: Contracting templates, channel strategies for last-mile and fleet customers, and service monetization frameworks to extend lifetime value.
-
Deal tools and screening matrices: Acquisition targets, JV partner shortlists, and integration checklists tuned for 2026 windows of opportunity.
Market structure and competitive posture
The LCV transmission arena is moderately concentrated: our concentration metrics show that the top three players control a meaningful but not dominant share of market revenue, with the top five owning a clear majority. That structure creates both competitive pressure and opportunistic whitespace for mid-sized suppliers and nimble newcomers. Strategic implications are straightforward—scale matters for OEM program wins, but well‑timed technology bets and M&A can materially change a participant’s win rate in two to three product cycles.
-
ZF Friedrichshafen AG (Friedrichshafen, Germany) — Strength: broad automatic transmission portfolio tailored to commercial applications and recent product momentum. ZF’s 8-speed PowerLine deployment on medium-duty platforms highlights its capability to convert technology investments into OEM-level wins. Strategic priority: defend core automatic segments while accelerating electrified adaptations of modular architectures.
-
Aisin Corporation (Kariya, Japan) — Strength: compact, proven automatic and dual-clutch architectures with hybrid-ready variants. Aisin’s compact dual-clutch EV transmission announcement signals intent to own a segment of electrified light-truck drivetrains. Strategic priority: productize the compact e-transmission for broader LCV platforms and lock in early EV OEM programs.
-
Allison Transmission (Indianapolis, USA) — Strength: deep installed base in delivery and service vehicles with strong brand equity in automatic transmissions. Strategic priority: leverage service and aftermarket to defend margin and expand electrified transmission modules for urban delivery segments.
-
Eaton Corporation (Dublin, Ireland) — Strength: automated-manual and dual-clutch offerings targeted at cost-sensitive applications; recent Advantor-6 introduction underlines competitiveness in light-duty trucks. Strategic priority: convert automated-manual economics into sustainable margins through manufacturing scale and software-enabled shift controls.
-
BorgWarner Inc. (Auburn Hills, USA) — Strength: hybrid and electrified modules suited to LCV powertrains. Strategic priority: integrate electrified transmission modules with e-axles and thermal-management systems to create bundled e-powertrain offers.
-
Dana Incorporated (Maumee, USA) — Strength: drivetrain component breadth and growing e-transmission capabilities. Strategic priority: push at the interface between axles and transmission to offer higher-value integrated modules for OEMs reducing supplier count.
-
Magna International (Aurora, Canada) — Strength: systems integration and DCT/e-drive units for LCVs. Strategic priority: focus on turnkey powertrain systems for start-ups and regional OEMs that prefer single‑vendor solutions.
Recent product and industry events that matter in 2026
-
Product launches: ZF’s 8-speed PowerLine implementation on medium-duty platforms (March 2026) and Eaton’s Advantor-6 automated manual introduction (Sept 2025) both illustrate OEM appetite for multi-speed and efficient automated systems in LCVs.
-
Electrification play: Key suppliers announced compact DCT and EV transmission modules in 2025, signaling a shift to platform architectures that support both conventional and electrified drivetrains.
-
Supply chain and trade: A 25% U.S. tariff on certain imported medium and heavy-duty parts effective November 2025 is reshaping sourcing economics and favoring onshore or near-shore production where volumes justify investment.
-
Materials risk: Volatility in steel and aluminum continues to pressure manufacturing margins—companies that move from reactive to hedged procurement and process efficiency will preserve pricing flexibility.
Practical strategic recommendations for 2026
-
Prioritize hybrid/electrified transmission development as a default: Allocate an explicit share of R&D roadmap budget to compact electrified modules and software-defined shift strategies to be selected by OEMs as optional packages.
-
Hedge supply chain risk with a layered approach: Implement a two‑tier sourcing strategy for critical metals, increase local content for U.S. programs exposed to tariffs, and create short-list second-source suppliers pre-approved through quality and cost gates.
-
Monetize installed base through aftermarket programs: Design service contracts and telematics-enabled maintenance offers for fleets to convert low-margin hardware to recurring revenue pools.
-
Use M&A and strategic alliances to fill capability gaps: Target bolt-on acquisitions that accelerate e-transmission know-how or strengthen local manufacturing footprints for tariff-impacted markets.
-
Adopt scenario-based portfolio allocation: Rebalance product and capital allocation across automatic, automated-manual and electrified platforms using our scenario models that stress-test demand under varying EV uptake and regulatory paths.
-
Embed cost-to-serve and TCO analysis into OEM negotiations: Present joint TCO cases for new transmission architectures to secure multi-year program commitments and avoid bidding on price alone.
The strategic value of PW Consulting’s deliverables
This deliverable is built as a tactical toolkit for 2026: ready-to-use Excel models, supplier scorecards, M&A screening matrices, and presentation-ready market narratives for executive committees. We translate market forecasts (base-year 2025, historical 2020–2025, forecast 2026–2032; currency: USD, unit: Million) into decision triggers and KPI thresholds that tell you when to accelerate, pause, or pivot. The analysis integrates regulatory scenarios, trade-policy impacts and raw-material stress tests so that procurement, product and corporate development teams can act cohesively.
Next step — why you should read the full report
This briefing intentionally highlights the strategic contours and actionable implications of our analysis while reserving the full set of segmented datasets, granular revenue splits, and detailed company benchmarking for the complete report. If you are responsible for product strategy, procurement, or M&A planning in 2026, the full report contains the segment-level exposure matrices, OEM-program maps, and downloadable financial models you will need to operationalize the recommendations described here.
Contact PW Consulting to obtain the full Light Commercial Vehicle Transmission Market report and the companion decision-support workbook. Use the intelligence now to ensure that investments and strategic moves made in 2026 position your business to capture the majority of upside through 2032.
For detailed analysis of this topic, please visit the official page: Light Commercial Vehicle Transmission Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com