

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aircraft Fuel & Oil Filters Market Set to Expand at a 5.25% CAGR Through 2032, Led by North America

Fuel, Fuel Oil & Aircraft Aerospace Filters Market — Strategic Outlook for 2026: PW Consulting Industry Brief
Executive summary
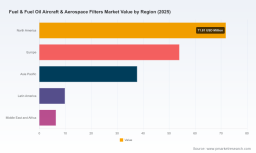
As airlines, OEMs, MROs and tier‑1 suppliers plan capital and product roadmaps for 2026, the aircraft fuel and fuel‑oil filtration market presents a mix of steady demand and accelerating technology and regulatory pressures. PW Consulting’s latest market model shows the global market reached approximately USD 179.7 million in 2025 and is forecast to grow at a 5.25% CAGR through the 2026–2032 horizon, culminating in a market size approaching USD 258 million by 2032. That trajectory reflects predictable replacement cycles, modest fleet growth, and an overlay of structural change driven by alternative fuels, new contamination vectors, and supplier consolidation.
Fuel Fuel Oil Aircraft Aerospace Filters Market
Why this matters for 2026 decision‑makers
-
Investment prioritization: Product development and capex cycles in filtration are long‑lead; decisions made in 2026 will determine technology portfolios for the next decade.
Fuel Fuel Oil Aircraft Aerospace Filters Market -
Regulatory compliance and risk mitigation: Operators and suppliers must reconcile filtration performance with evolving SAF blends and standards that mandate water separation and particle control.
Fuel Fuel Oil Aircraft Aerospace Filters Market -
Supply‑chain resilience: Consolidation and targeted acquisitions are reshaping supplier choices, with implications for availability, aftermarket margins and captive sourcing strategies.
Market trajectory and the practical implications
Our topline model blends historical shipment and aftermarket data (2020–2025) with forward scenarios (2026–2032). The near‑term market shows continued replacement demand supported by fleet utilization and MRO cycles; beyond that, incremental growth is driven by retrofits, upgraded two‑stage filtration systems and expanded aftermarket services. The steady 5.25% CAGR masks important inflection points: regulatory phases that increase SAF blending and technology transitions away from legacy water detection/monitoring technologies. For procurement and product strategy teams this means balancing short‑term service continuity with targeted investment in SAF‑compatible, higher‑efficiency filtration and separation systems.
Key dynamics shaping the market in 2026
-
Regulatory push for SAF: Policies such as the EU’s progressive SAF blend requirements are forcing airport fuel supply chains and airframe/engine integrators to validate filter performance across new chemistries and contaminants. Filtration systems that were designed for conventional Jet A/A1 may underperform with higher oxygenate content or different particulate profiles.
-
Standards and performance expectations: Industry standards — including those that define two‑stage water/particle separation requirements — are increasingly prescriptive. Compliance is not optional; it becomes a procurement gate for airlines and integrators.
-
Contamination vectors: Operational incidents such as DEF contamination and crystallization remain a material safety and reliability risk. Filters serve as the last line of defense — but they must be specified, tested and maintained differently where new contamination types are present.
-
Technology migration and product phase‑outs: Recent industry moves highlight rapid technology turnover. The announced phase‑out of certain legacy EI‑qualified water monitoring products accelerates adoption of a next generation of water‑barrier and sensing technologies. OEMs and MROs need transition plans to avoid obsolescence and supply disruptions.
-
Consolidation and M&A: Strategic deals show suppliers expanding vertically and horizontally to capture aftermarket, cartridge and systems revenue. M&A is reducing the pool of independent specialists but also creating larger suppliers with broader product portfolios.
Competitive landscape — reading between the lines
The market exhibits a moderate concentration: a small set of global engineering majors and specialized filtration houses command a meaningful share of system supply and aftermarket contracts, while niche vendors serve tailored military, GA and PMA segments. Firms such as Parker Hannifin, Donaldson, Pall, Porvair, Safran and Eaton continue to be pivotal — supplying systems, cartridges and integration services across OEM and aftermarket channels. Meanwhile, highly specialized firms (e.g., Tempest Aero Group, Chase Filters & Components, Global Filtration and Norman Filter) play critical roles in general aviation, defense and PMA markets where customization, certification speed and service relationships are competitive differentiators.
Recent developments illustrate strategic direction: Donaldson’s acquisition of Facet Filtration underscores a consolidation trend aimed at assembling end‑to‑end mission‑critical fluid solutions. Parker’s discontinuation of certain legacy water monitor products signals an industry pivot towards new water barrier technologies and sensor integration. Pall’s continued support of large airline fleets confirms that fleet service contracts remain a high‑value, sticky revenue stream for suppliers that can demonstrate sustained performance with SAF blends.
Where the real opportunities lie (but the granular splits are in the full report)
-
Systems & integrated solutions: Suppliers that move beyond stand‑alone cartridges to offer filtration as a systems‑level capability — including monitoring, diagnostics and service contracts — can capture higher lifetime value.
-
Aftermarket & fleet support: Long‑term service agreements and cartridge subscriptions provide predictable recurring revenue and higher margins than one‑off hardware sales.
-
SAF compatibility and retrofit kits: There is a commercial window for retrofit kits and validated filtration upgrades to support new fuel chemistries; early movers who achieve certifiable performance gain preferential access to airline procurement cycles.
-
Defense & specialty segments: Military applications and high‑reliability segments continue to favor bespoke, qualified solutions; suppliers with rapid qualification capability and traceable documentation win in these higher‑margin niches.
What PW Consulting’s full report contains (practical, execution‑oriented)
-
Top‑down market sizing and bottom‑up validation across 2020–2025, plus high‑ and low‑case forecasts for 2026–2032 with sensitivity analysis tied to SAF adoption rates.
-
Technology deep‑dive: comparative performance benchmarking of micronic filters, coalescer separators, two‑stage systems and emerging water‑barrier technologies — with guidance on lab and field test protocols needed for certification.
-
Regulatory impact mapping: scenario playbooks for different regional SAF uptake paths and corresponding compliance actions for suppliers and operators.
-
Competitive profiles and strategic scorecards for leading suppliers, including capability matrices, product roadmaps, recent M&A and likely strategic moves (detailed company profiles and web references included).
-
Procurement & supplier risk toolkit: negotiation templates, multi‑year sourcing scenarios, spare‑parts stocking models and contingency playbooks to protect fleet operations during supplier transitions.
-
MRO playbook & aftermarket monetization: step‑by‑step guidance on building service contracts, cartridge lifecycle pricing, and parts commonality strategies to maximize margin and retention.
-
Investor & M&A advisory annex: valuation comparables, consolidation scenarios and inorganic growth targets for strategic acquirers or private equity seeking exposure to high‑quality aftermarket streams.
Concrete 2026 actions by stakeholder
-
Airlines and lessors: institute an immediate audit of filtration performance across your fuel supply chain for SAF blends; require supplier test evidence and deployment timetables as part of procurement RFPs.
-
OEMs and tier‑1 suppliers: prioritize certifying filter families against SAF and perform coalescer/separator validation under worst‑case contamination scenarios; build retrofit pathways into service bulletins to capture aftermarket revenue.
-
Filter manufacturers: accelerate integration of water‑barrier and sensor technologies, build long‑term fleet support offerings and evaluate targeted acquisitions to fill capability gaps (materials, sensing, certification speed).
-
MROs and component rebuilders: develop cartridge remanufacturing and predictive replacement programs; partner with operators to bundle filtration services with fuel and tank maintenance offerings.
-
Investors: triangulate investment opportunities between durable aftermarket service streams and engineering‑led suppliers positioned to capture SAF retrofit demand; look for firms with rapid qualification capability and strong OEM relationships.
Market risk factors to monitor in 2026
-
SAF price dynamics: sustained high SAF premium slows retrofit adoption and delays supplier revenue realization.
-
Regulatory variance: uneven regional SAF mandates create patchwork demand and complicate global fleet strategies.
-
Supplier single points of failure: phase‑outs of legacy equipment without managed transitions expose operators to operational risk; contractual service continuity clauses should be enforced.
-
New contamination types: operational misuse (e.g., DEF cross‑contamination) produces failure modes unanticipated by legacy filters; incident learning must feed product design rapidly.
Conclusion — the strategic choice for 2026
2026 is a decision year: organizations that treat filtration as an operational cost center will face increasing disruption from fuel chemistry change and supplier consolidation. Conversely, stakeholders who seize the opportunity — by investing in validated SAF‑compatible systems, pursuing aftermarket service models and shoring up supplier transition plans — can capture disproportionate value as the market grows at a mid‑single‑digit CAGR and moves into a period of technology turnover.
Next steps
PW Consulting’s full Fuel, Fuel Oil & Aircraft Aerospace Filters Market report provides the granular segmentation, supplier share tables, pricing curves and downloadable models needed to operationalize the recommendations above. For executives preparing budgets, RFPs or M&A screens in 2026, the report is the practical reference that converts market intelligence into executable plans. Visit our report page to access the complete dataset, segmented forecasts and the supplier playbooks referenced in this briefing.
For detailed analysis of this topic, please visit the official page: Fuel Fuel Oil Aircraft Aerospace Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com