

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Submarine AIP Market to Reach USD 509.21 Million by 2032 at 3.8% CAGR — Asia Pacific Tops with USD 195.75M in 2025

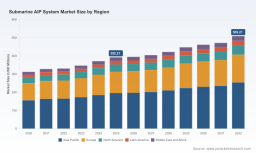
Submarine AIP System Market — Strategic Outlook for 2026: PW Consulting Report Preview
Executive snapshot
PW Consulting’s latest market study on Submarine Air-Independent Propulsion (AIP) systems provides a forward-looking intelligence product designed to inform procurement, industrial strategy, and investment decisions through 2032. The global Submarine AIP System market reached USD 392.21 Million (base year 2025) after a steady recovery from USD 312.45 Million in 2020. Our forecast shows continued expansion driven by fleet modernizations, retrofit programs and technology maturation, with a compound annual growth rate (CAGR) of 3.8% through the 2026–2032 horizon and a projected market size approaching USD 509.21 Million by 2032.
Submarine Aip System Market
Why this matters for 2026 decision-makers
- Naval planners: Choices made in 2026 about platform selection, retrofit timing and domestic capacity will lock in endurance and stealth capabilities for the next two decades.
- Prime contractors and Tier‑1 suppliers: Strategy on AIP technology bets (fuel cell topologies vs. Stirling vs. reforming solutions) and industrial partnerships will determine export competitiveness and margin pools.
- Component and materials suppliers: Supply‑chain exposure to specialty metals, hydrogen-storage media and oxygen systems requires active risk mitigation.
- Private investors and M&A teams: The market’s mid-single-digit CAGR and its concentration profile create niche consolidation and vertical-integration opportunities.
What the full PW Consulting report delivers
To support operational decision-making in 2026, the full report goes beyond headline numbers and offers hands-on tools built from primary research, supplier engagement and scenario modelling. Key deliverables include:
Submarine Aip System Market
- Proprietary market-sizing and demand curves (2020–2032) with sensitivity runs for procurement cycles and geopolitical shocks.
- A competition matrix that profiles incumbent and challenger companies by technology, integration capability, and service footprint.
- Procurement playbooks for navies and primes: specification checklists, qualification gates, and phased integration plans for new-build and retrofit pathways.
- Supplier assessment framework and TCO model: lifecycle cost drivers, retrofit cost bands, spares and sustainment models tailored to different AIP architectures.
- Supply-chain stress tests: concentration maps for critical inputs (metals, specialised hydrogen storage, oxygen systems) and mitigation levers for sourcing and stockholding.
- Regulatory and classification digest: mapping of certification paths, key testing requirements and classification society positions relevant to AIP installations.
- Strategic M&A and partnership shortlist: candidate targets and capability gaps for primes and suppliers looking to scale or diversify.
Market dynamics shaping the 2026 agenda
The AIP market sits at the intersection of naval doctrine, material science and international trade. Three dynamics will disproportionately shape 2026 decisions:
Submarine Aip System Market
- Technology diversification and hybridization: Fuel cells (PEM and evolving second-generation chemistries), Stirling engines and reforming-based solutions (including bioethanol approaches) coexist in the market. This multi-technology landscape favors modular platform integration strategies that preserve upgrade paths while controlling upfront risk.
- Supply‑chain constraints and raw‑material pressure: Specialized inputs—certain high-grade alloys, hydrogen storage media (metal hydrides and cryogenic systems) and liquid oxygen handling components—are cost and availability stress points. Western sanctions and restricted flows of strategic metals have already shifted supplier footprints and increased lead times for some propulsion components.
- Geopolitics and domestic capability drives: Several navies are accelerating indigenous AIP development to reduce strategic dependencies. Recent milestones (for example, the integration efforts reported by DRDO/Indian Navy in early 2026) validate that trend and create both domestic market demand and export-control considerations for capable suppliers.
Competitive landscape — profiles and strategic posture
The market demonstrates a moderate level of concentration: the top three suppliers account for a material share of industry revenues while the top five capture an even larger portion of market value—conditions that favor both scale and targeted niche plays. Key incumbents and their strategic positions are summarized below:
- Saab AB (Kockums) — Sweden ( https://www.saab.com): Renowned for Stirling-engine based AIP solutions, Saab’s integration heritage on classes such as Gotland and A26 positions it as a trusted partner where acoustic discretion and long-endurance submerged operations are priority requirements.
- thyssenkrupp Marine Systems (TKMS) — Germany ( https://www.thyssenkrupp-marinesystems.com): TKMS has operationalized PEM fuel-cell AIP architectures in collaboration with industrial partners; its ongoing export and domestic programs highlight the commercial traction of fuel-cell centric platforms.
- Siemens AG — Germany ( https://www.siemens.com): As a supplier of PEM modules and balance-of-plant expertise, Siemens acts as a technology multiplier for primes integrating fuel-cell AIP and is a key source of stack-level innovation and industrialization capability.
- Naval Group — France ( https://www.naval-group.com): With experience across MESMA and next‑generation fuel-cell systems and on-board reforming approaches, Naval Group exemplifies a multi-technology integrator able to tailor solutions to platform constraints.
- Hanwha Ocean — South Korea ( https://www.hanwhaocean.co.kr): An emergent exporter, Hanwha combines hybrid AIP systems with broader platform exports and recently passed notable design approvals, signaling strengthened competitiveness in the global tender pipeline.
- Navantia — Spain ( https://www.navantia.es): Developer of bioethanol processor-based approaches and active in collaborative international programs, Navantia represents alternative reforming pathways with unique logistics implications.
- China Shipbuilding Industry Corporation (CSIC) — China : A major domestic integrator producing AIP-capable submarines for its navy and export customers; its indigenization efforts are a factor in regional competition and technology diffusion dynamics.
Recent developments that change tactical priorities
- DRDO / Indian Navy reported an integration milestone for an indigenous fuel-cell AIP on a Kalvari-class platform in March 2026 — underscoring national priority for self-reliance.
- Hanwha Ocean achieved Approval in Principle for a 2,000-ton export submarine design with AIP capabilities in May 2026, following the launch of KSS‑III Batch‑II boats with hybrid AIP in late 2025 — a signal of accelerated export readiness.
- ThyssenKrupp Marine Systems secured follow‑on contracts in 2025 for PEM‑based AIP platforms, reaffirming the commercial demand for fuel-cell centric solutions across certain buyer segments.
Actionable 2026 recommendations — three strategic priorities
- De-risk supply chains now: Establish dual‑sourcing for critical alloys and long‑lead hydrogen handling components; consider strategic inventory for high‑value parts and accelerate qualification of alternative suppliers in lower‑risk jurisdictions.
- Design for modular upgradeability: Require modular AIP architecture in new contracts to enable phased insertion of next‑generation stacks or alternative energy carriers without hull redesigns, lowering retrofit costs and obsolescence risk.
- Invest in sustainment and retrofit capability: Service and refit revenue will be a growing value pool as fleets extend operational life. Build domestic refit capacity, train maintenance workforces, and establish OEM‑partnered spares frameworks to capture aftersales margins.
- Prioritize lifecycle cost, not first‑cost: Use PW Consulting’s TCO modelling to compare configurations under varied operational profiles — endurance, mission tempo and peacetime patrols influence the optimal technology mix more than headline procurement price.
- Leverage partnerships for capability gaps: Where internal R&D timelines are long, pursue joint ventures with proven integrators or licensing agreements for stack technology to shorten fielding timelines while preserving sovereign capability plans.
Methodology and confidence framework
The report synthesizes multi‑sourced evidence: procurement notices and classified tender records, OEM and supplier disclosures, primary interviews with program managers and shipyards, classification society guidelines, and proprietary supply‑chain mapping. Scenario analyses incorporate sensitivity to raw material cost shocks and geopolitical disruption. The base year is 2025 and the forecast window spans 2026–2032; topline projections are presented with probability-weighted scenarios to aid contingency planning.
Conclusion — the strategic value for 2026
For 2026 decision cycles, the Submarine AIP System market represents a modest but strategically significant arena where technology choices, supply‑chain resilience and integration capacity determine operational advantage. The sector’s steady growth and concentrated supplier base create clear chores for both incumbents and challengers: secure inputs, lock service revenues, and design platforms that can evolve. PW Consulting’s full report arms stakeholders with the quantitative forecasts, supplier intelligence and executable playbooks needed to turn 2026 decisions into sustained capability and commercial advantage.
Access the full analysis
This preview is intended to surface the strategic implications and practical levers contained in our full Submarine AIP System Market report. For the complete dataset, segmented analysis, procurement playbooks and the downloadable TCO models and scenario workbooks, please download the full report from PW Consulting’s report page or contact our defence and maritime practice leads to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Submarine Aip System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com