

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Emergency Rescue Drone Market to Soar at a 12.45% CAGR Through 2032

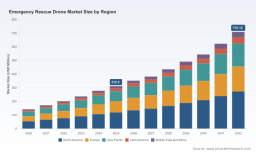
Emergency Rescue Drone Market 2026: Strategic Imperatives for Corporate Decision‑Makers
PW Consulting’s latest market research — Emergency Rescue Drone Market: 2026 Strategic Brief — synthesizes seven years of market evolution and a detailed seven‑year forecast to deliver a compact, decision‑grade intelligence package for executives planning 2026 investments. Built on historical observations (2020–2025) and a forecast horizon through 2032, the analysis identifies the structural forces reshaping emergency response capabilities and quantifies the market’s acceleration: a compound annual growth rate (CAGR) of 12.45%, with total market value moving from roughly USD 142 million in 2020 to USD 312.5 million in 2025 and projected to exceed USD 700 million by 2032. This release summarizes the strategic takeaway for corporates while intentionally reserving granular segmentation and vendor matrices for the full report.
Emergency Rescue Drone Market
Why this brief matters for 2026 planning
Emergency rescue drones have moved beyond proof‑of‑concept deployments into mission‑critical roles across public safety, disaster response, and medical logistics. For 2026 planning cycles, buyers, OEMs, integrators, and investors need a tightly focused understanding of three things:
Emergency Rescue Drone Market
- How regulatory and procurement realities (e.g., supply‑chain compliance and DFR program approvals) will gate adoption timelines;
- Which technology choices materially change total cost of ownership and operational effectiveness (autonomy, thermal and sensor stacks, VTOL vs. multirotor tradeoffs); and
- Where consolidation and competitive concentration create acquisition or partnership opportunities.
This brief translates those questions into board‑level recommendations and executable next steps — without disclosing the full granular charts and segmented revenue tables that appear in the full dossier.
Emergency Rescue Drone Market
Key market dynamics shaping 2026 decisions
Regulatory and procurement environment: Two regulatory signals are decisive. First, mandatory supply‑chain compliance for many government and public safety adopters — notably NDAA compliance — is now a prerequisite for meaningful contract eligibility. Second, aviation authorities have accelerated administrative pathways for Drone as First Responder (DFR) programs, reducing time‑to‑operational‑status when agencies use prepositioned systems. For purchasing officers and program managers, this means supplier selection must balance technical capability with verifiable compliance credentials and program‑specific approvals.
Technology and operational drivers: Advancements in onboard autonomy, high‑resolution thermal imaging, encrypted real‑time telemetry, and hybrid VTOL endurance are combining to change operational doctrines. Autonomous pathing, robust obstacle avoidance, and machine‑assisted search patterns materially increase the value of a deployed drone beyond raw flight time. Equally important are sensor modularity and communications resilience: payload ecosystems and hardened data links determine whether a platform becomes an operational asset or a temporary experiment.
Supply chain and component constraints: As defense and government programs require NDAA‑compliant batteries and parts, sourcing strategies must adapt. Our analysis highlights the strategic tradeoffs in locking into compliant supply streams versus pursuing cost‑optimized components. For procurement teams, mapping supplier certification timelines against planned deployments is now mission critical.
Market structure and competitive dynamics: The sector is moving toward a moderately concentrated topology. The top three players account for a significant share of revenue, and the top five approach parity with a substantial portion of market value — a pattern that favors specialist incumbents with public‑safety pedigree and scaled manufacturing. This structure has implications for pricing power, aftermarket service economics, and M&A activity.
What’s in the full report (practical, operational content)
Our 150+ page report is intentionally designed for users who need to act in 2026. Key practical assets included are:
- Decision frameworks for procurement: vendor scorecards, NDAA compliance checklist, and contract templates tailored for public‑safety and municipal procurement cycles;
- Operational deployment playbooks: step‑by‑step DFR station planning, maintenance cadence, and crew training matrices that convert a pilot project into a 24/7 operational capability;
- Financial tools: TCO models, scenario‑based ROI calculators, and risk‑adjusted investment timelines aligned to the market CAGR and adoption curves;
- Technology assessment rubrics: standardized test procedures for autonomy, sensor fusion, and communications resilience (including evaluation criteria for thermal imaging, two‑way communications, and glass‑breach capabilities);
- Supply‑chain and compliance mapping: supplier due‑diligence templates and alternative sourcing strategies for NDAA‑sensitive components such as batteries;
- Scenario planning: three plausible adoption trajectories (base, accelerated, and constrained) with associated budgetary implications and suggested operating cadences for each scenario;
- Implementation roadmaps: 6–18 month and 18–36 month playbooks that identify fast wins and medium‑term investments for municipal agencies and private operators.
We intentionally withhold the detailed segmentation tables and regional/application breakouts in this press brief to protect the commercial sensitivity of that analysis. Those datasets and vendor scorecards are available in the full report.
Competitive landscape—who matters and why
Our analysis profiles a compact set of specialist and system providers whose technology portfolios and go‑to‑market motions will shape 2026 outcomes:
- BRINC Drones — a public‑safety specialist notable for purpose‑built systems including indoor/dense‑urban tactical solutions, two‑way communications, and field‑proven breaching capabilities. Recent developments: in March 2026 BRINC announced a significant production expansion and launched a next‑generation response drone aimed at 24/7 DFR operations.
- Skydio — leading in autonomy and robust obstacle avoidance for complex environments; its AI‑driven platforms are increasingly deployed in hands‑off search and rescue missions where reliable navigation matters more than raw endurance.
- AeroVironment — historically defense‑oriented, providing tactical UAS and VTOL systems with proven rapid‑deployment characteristics, attractive to governmental programs requiring hardened logistics and ISR integration.
- Draganfly — a North American manufacturer focused on public safety payloads and domestic production footprints, which helps satisfy procurement preferences for localized manufacturing.
- ZenaDrone — a growth‑stage vendor offering long‑range, mission‑specific platforms built around robust telemetry and real‑time data transmission for remote search operations.
- Ascent Aerosystems — supplier of resilient coaxial designs optimized for compact operations in constrained environments and integration with defense/public‑safety systems.
Market concentration metrics reinforce the importance of these players: the top three firms hold a material portion of market revenues, and the top five capture over half of industry value — a structure that creates both competitive barriers and clear acquisition targets for strategic buyers.
Strategic recommendations for 2026
We advise corporate and public‑sector leaders to take four concurrent actions this year to convert market growth into competitive advantage:
- Prioritize compliance as a core capability. NDAA credentials and documented supply‑chain provenance are now as important as performance specifications. For manufacturers, this should be integrated into product roadmaps and supplier contracts; for buyers, certification should be a gated procurement milestone.
- Invest in autonomy and systems integration. Platforms with higher levels of autonomy reduce operator overhead and scale more cost‑effectively as programs move from pilot to continuous operations.
- Design modular service and payload ecosystems. The winning commercial models will combine hardware sales with subscription‑grade software, payload leasing, and field service — turning one‑off deployments into recurring revenue streams and reliable public‑safety capabilities.
- Use scenario‑based budgeting tied to adoption curves. With a 12.45% CAGR and clear upside under accelerated DFR adoption, procurement timelines should be staged: near‑term investments to secure interoperability and compliance, mid‑term capital for scaled deployments, and longer‑term R&D for next‑gen endurance and autonomy.
How to use this research in executive decision making
PW Consulting’s report is designed to be directly actionable for four audiences in 2026:
- CEOs and corporate strategy teams evaluating M&A or partnership plays — use our competitive concentration analysis and M&A scenarios to prioritize targets;
- Procurement and operations leaders at municipalities, utilities, and large enterprises — apply our procurement checklists and TCO models to replace pilots with scalable programs;
- R&D and product teams at OEMs — benchmark autonomy, payload interfaces, and compliance investments against the technology assessment rubrics;
- Investors and PE sponsors — use our market‑level forecasts, concentration metrics, and scenario returns to size investment tickets and staging requirements.
Each user group can adopt the report’s tools directly into board packets, procurement RFPs, or product investment cases. The deliverables were built to reduce time‑to‑decision while preserving the analytical rigor executives require.
Next steps
The executive brief you are reading condenses the core strategic implications of PW Consulting’s full Emergency Rescue Drone Market report. For procurement matrices, regional and application segmentation, granular vendor scores, and downloadable financial models, please consult the full report on our website. Those datasets are essential for teams building specific procurement packages, investment memos, or R&D roadmaps in 2026.
PW Consulting stands ready to help translate this research into a tailored implementation plan, whether you are evaluating a first DFR deployment, planning a national roll‑out, or considering M&A to capture aftermarket service value. Contact our Public Safety & Unmanned Systems practice to schedule a briefing and scenario workshop.
For detailed analysis of this topic, please visit the official page: Emergency Rescue Drone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com