

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Vertical Rotary Surface Grinders Market to Expand at 5.59% CAGR, Unlocking New Opportunities Through 2032

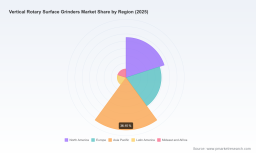
Vertical Rotary Surface Grinders Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s new market study on Vertical Rotary Surface Grinders offers a focused, decision‑grade intelligence package designed to steer capital, sourcing and product strategies in 2026. Grounded in five years of historical observation (2020–2025) and a seven‑year forecast horizon (2026–2032), the report synthesizes macro growth trajectories, competitive positioning and actionable playbooks for OEMs, end‑users and investors. This preview outlines why the report is strategically material for choices you will make this year, while intentionally withholding detailed subsegment tables to encourage direct access to the full dataset.
Vertical Rotary Surface Grinders Market
Market Snapshot: Macro Trajectory and Competitive Structure
The vertical rotary surface grinders market reached an estimated USD 2,580 Million in the base year (2025). Our modeling indicates steady expansion through the forecast window, with a compound annual growth rate of 5.59% from 2026 to 2032 and a projected market size approaching USD 3.78 Billion by 2032. These headline metrics reflect a combination of demand drivers: sustained investment in automotive, aerospace and toolmaking; ongoing replacement cycles in heavy industry; and selectively rising requirements for precision flatness in advanced manufacturing.
Vertical Rotary Surface Grinders Market
Concentration metrics show a market that is neither atomized nor fully consolidated: the top three players account for roughly 38.5% of market sales while the top five approach 52.7%. That mid‑fragmented structure creates both scale advantages for established OEMs and fertile ground for niche specialists, particularly in remanufacturing, aftermarket service and application‑specific turnkey solutions.
Vertical Rotary Surface Grinders Market
Why This Matters for 2026 Decisions
- Capital Allocation: With predictable mid‑single‑digit growth, major capital expenditures should be gated by clear payback expectations. The report supplies modeled ROI scenarios under differing utilization, pricing and material‑cost assumptions to assist board‑level approvals.
- Sourcing & Supply Chain: Volatility in steel and specialty material pricing, along with ongoing trade investigations, materially affect BOM costs and lead times. The study provides scenario stress‑tests for sourcing strategies (near‑shoring, dual‑sourcing, contractual hedging) to be executed in 2026.
- Product Roadmaps: Technology choices (e.g., hydrostatic turntables, high‑powered vertical spindles, remanufactured Blanchard lines) should be prioritized against end‑market demand elasticity. We map technology adoption sequences to price bands and buyer personas to help product and engineering teams set 18–36 month development cadences.
- M&A and Partnership Screening: The mid‑concentrated nature of the market makes strategic acquisitions or capacity partnerships attractive for both OEMs seeking share and private equity looking for consolidation plays. The report includes a shortlist framework for target screening and valuation levers.
Actionable Contents of the Full Report
The published report is structured for operational use. Highlights include:
- Executive dashboards with topline growth scenarios and sensitivity to steel price and tariff shocks.
- Buyer personas and procurement playbooks—how to evaluate TCO for one‑head vs multi‑head machines, retrofit vs new purchase, and when remanufactured assets make sense.
- Technology horizon maps detailing adoption curves for hydrostatic tables, high‑HP spindle platforms and control/automation upgrades.
- Profitability models for aftermarket services (spares, rebuilds, field servicing) and a build‑out playbook for service organizations.
- Regulatory and trade risk matrix with mitigation options—procurement clauses, inventory buffers, and tariff pass‑through modeling.
- M&A playbooks and a prioritized target list based on strategic fit, manufacturing footprint and aftermarket overlap.
- Benchmarked supplier scorecards and negotiation checklists to shorten vendor qualification cycles.
To preserve the report’s commercial integrity, granular regional and application breakdowns are not reproduced in this preview. The full downloadable dataset contains the complete segmented tables and time‑series that underpin our recommendations.
Competitive Landscape — Who Matters and Why
We examined a cross‑section of OEMs and regional specialists to form a layered view of competition, capability and go‑to‑market approaches.
- Bourn & Koch, Inc. (Rockford, Illinois, USA) — Known as the OEM for Blanchard vertical rotary grinders, Bourn & Koch’s portfolio emphasizes both new and remanufactured models with very large chuck capacities and high‑horsepower spindles. Their strength lies in heavy‑stock removal and purpose‑built installations for large workpieces.
- DCM Tech (Winona, Minnesota, USA) — Offers the IG series of American‑made rotary grinders with a range of capacities. DCM targets precision grinding for industrial and aerospace applications, balancing compact footprints with serviceability emphasis.
- Chevalier Machinery (Taiwan / USA) — The FRG series highlights hydrostatic turntable designs and high rigidity. Chevalier is notable for product refreshes that push precision at competitive price points and for expanding aftermarket capabilities.
- Okamoto Corporation (Japan) — The VRG‑DX line focuses on high‑power spindles and accuracy in rotary table models, positioning Okamoto against premium accuracy demands in aerospace and optical component manufacturing.
- Tong Yi Machinery / Dowell (Taiwan) — Markets VR series machines that stress reliability across metalworking segments, often chosen where predictable uptime and ease of maintenance are procurement priorities.
- Alex Machine Tools, Synergy Machine Tools, ABL Machine Tools, Kent USA — These regional manufacturers offer a spectrum of vertical rotary platforms, from high‑volume die & mold machines to specialty units for valves, bearings and hard/brittle material work.
Competitive dynamics are evolving: premium accuracy and aftercare are moving from differentiators to table stakes, while remanufacturing and service models (where margins are typically higher than OEM equipment sales) are becoming profit centers for firms that can execute nationwide field networks.
Recent Industry Signals and Their Strategic Implications
- Trade show activity and product launches (for example, Alex Machine Tools’ participation at Die Mould India 2026 and Chevalier’s recent FRG series introduction) signal renewed OEM emphasis on capturing die & mold and custom applications—opportunities for localized manufacturing partnerships.
- Notable installations and product upgrades (illustrated by Bourn & Koch’s placements in 2025) show that existing demand is still driven by replacement and capacity expansion in regional metalworking hubs.
- Input‑cost noise—steel coil prices rose meaningfully in 2025—along with ongoing national trade investigations and tariff proposals on machine tools and specialty materials, create risk for global sourcing models and warrant explicit procurement hedging strategies in 2026.
Strategic Recommendations for 2026 Execution
- Lock in modular sourcing: Pursue dual‑source agreements for key castings and spindle components, and qualify regional sub‑assemblies to reduce tariff exposure and lead time volatility.
- Prioritize the aftermarket: Build spare parts inventory strategies, subscription‑style maintenance, and remote diagnostics offerings to increase recurring revenue and reduce price sensitivity.
- Invest selectively in high‑value tech: Target hydrostatic turntables and high‑HP spindle platforms for customers where productivity gains justify price premiums; standardize controls for easier service and upgrades.
- Hedge material cost exposure: Use indexed contracts or multi‑year supply agreements where possible; model scenarios for up to 50% tariff shocks in procurement planning exercises.
- Consider bolt‑on consolidation: For mid‑sized OEMs and financial sponsors, pursue tuck‑ins that strengthen service footprints or add remanufacturing capabilities—those assets accelerate margin expansion.
- Engage on policy: Coordinate with industry associations to influence trade policy implementation timelines and secure carve‑outs for critical capital equipment components.
Methodology, Confidence and Next Steps
Our analysis synthesizes primary interviews, vendor and end‑user surveys, company disclosures and price‑sensitive input‑cost models. Base year is 2025; forecasts run 2026–2032. We assign medium‑high confidence to headline growth and concentration metrics, with scenario banding around material price and tariff trajectories to reflect elevated policy risk.
This preview is intentionally selective—core segmented tables, regional/application splits, and detailed company financials are only available in the full report package and accompanying data workbook. For procurement teams, strategy committees, or investors preparing decisions in 2026, those granular datasets are the difference between directional understanding and executable strategy.
Access the Full Intelligence
PW Consulting’s full Vertical Rotary Surface Grinders Market report provides the datasets, slide decks and implementation tools required to convert insight into action. Contact our market research desk or visit the report page to download the executive summary, review the methodology appendix and access the client portal for custom queries and model extracts.
For detailed analysis of this topic, please visit the official page: Vertical Rotary Surface Grinders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com