

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: One-Box Electro Hydraulic Braking Market to Expand at 12% CAGR (2026–2032), Approaching USD 5.53 Billion by 2032
By pmarketresearch, 2026-07-02
One Box Electro Hydraulic Braking System Market: Strategic Imperatives for 2026 Decision-Makers
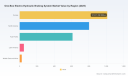
PW Consulting’s new market study on the One Box Electro Hydraulic Braking System market (base year 2025) delivers a practice-oriented roadmap for organizations planning capital, product and partnership decisions in 2026. Grounded in a seven-year forecast and rigorous primary research, the report shows the market expanding from an estimated USD 2.5 billion (2025) to more than USD 5.5 billion by 2032 — representing a compound annual growth rate (CAGR) of approximately 12% over the forecast period. This release summarizes the strategic implications of those macro dynamics, outlines competitive pressures, and previews the actionable content contained in the full report — while deliberately withholding granular segment tables to protect proprietary datasets available in the full report.
One Box Electro Hydraulic Braking System Market
Why 2026 Is a Pivotal Inflection Point
Supply chain normalization, accelerated electrification programs, and regulatory tightness around braking performance are converging to create a compressed decision window for OEMs, Tier-1 suppliers, and investors. For organizations that must translate strategic intent into executable plans in 2026, the right timing of R&D investments, production capacity deployments, and M&A or JV moves will materially affect cost-to-market, product differentiation, and long-term margins.
One Box Electro Hydraulic Braking System Market
Key implications for 2026 decision-makers:
One Box Electro Hydraulic Braking System Market
- Capital allocation choices made in 2026 will disproportionately determine competitiveness across the next product cycle because development lead times for integrated electro-hydraulic systems span multiple years.
- Supplier selection and qualification processes initiated in 2026 will shape OEM option portfolios for the 2028–2030 model years; late movers face higher integration and warranty risk.
- Strategic partnerships (technology licensing, co-development) are becoming the fastest path to shrink development timelines while preserving IP leverage.
Market Trajectory — What the Numbers Mean
The market’s projected rise from roughly USD 2.5 billion in 2025 to approximately USD 5.53 billion in 2032 (CAGR ~12%) signals a transition from niche adoption to mainstream specification across higher-volume vehicle platforms. This trajectory is not uniform: pockets of rapid adoption will emerge where drivetrain electrification, safety regulations, and vehicle architecture favor one-box designs that simplify integration and provide system-level control advantages.
Two strategic takeaways:
- Scale is becoming a competitive advantage. Market concentration metrics indicate that incumbent leaders already command a substantial share of the market, reinforcing economies of scale in procurement, validation and platform engineering.
- Value is shifting upstream and downstream: OEMs will prize systems that reduce calibration complexity and weight, while suppliers that can provide modularity, functional safety assurance, and validated software stacks will capture higher margin pools.
Competitive Landscape and Supplier Profiles
The market exhibits structural consolidation: the top three global players account for a majority share, and the top five command a large, dominant portion of sales — a configuration that strengthens incumbents’ negotiating power but also creates opportunities for specialized challengers. The full report includes detailed company scorecards, product whiteboards and win-loss analyses; below we sketch the public profiles and strategic positioning of principal players shaping market dynamics.
- Robert Bosch GmbH (Gerlingen, Germany) — A leading provider of integrated one-box electro-hydraulic braking solutions, Bosch couples high-volume systems engineering with embedded software capabilities and broad platform reach across passenger and commercial vehicle segments. Their integrated iBooster lineage gives them differentiated vertical integration advantages in actuator-control synergies. ( https://www.bosch-mobility-solutions.com)
- Continental AG (Hanover, Germany) — Continental’s one-box modules combine actuation and control in compact architectures. The firm’s strength lies in systems-level integration across vehicle dynamics and driver assistance stacks, and in leveraging global relationships with OEMs for early specification adoption. ( https://www.continental-automotive.com)
- ZF Friedrichshafen AG (Friedrichshafen, Germany) — ZF competes with integrated one-box offerings positioned to enhance vehicle dynamics and stability control functions. Its engineering depth in mechatronics and control algorithms positions the company well where performance differentiation is critical. ( https://www.zf.com)
- Hyundai Mobis (Seoul, South Korea) — As an OEM-affiliated Tier-1, Hyundai Mobis brings production scale for electric and hybrid vehicle platforms and tight OEM integration that accelerates validation cycles for one-box systems. Their route to market benefits from captive demand and platform synergies. ( https://www.mobis.co.kr)
Each of these firms brings a distinct playbook: incumbents leverage platform breadth and validation capabilities, while niche suppliers and regional specialists seek partnerships and technology licensing to overcome scale disadvantages. The market’s structure incentivizes strategic alliances that combine software IP, actuator manufacturing, and safety certification expertise.
What the PW Consulting Report Contains — Practical Tools for 2026 Execution
Beyond headline forecasts, our report is designed as an operator’s handbook for 2026 decisions. Key practical deliverables include:
- A validated market-sizing model (2020–2032) with scenario toggles to test sensitivity to electrification penetration, regulatory shifts, and semiconductor constraints.
- Technology readiness maps that align product variants to vehicle architectures, showing integration risk, expected certification timelines, and recommended guardrails for software and functional safety.
- Supplier scorecards and a buyer decision matrix to prioritize shortlists based on technical fit, cost-to-integrate, IP exposure and aftersales readiness.
- Supply chain and cost-breakdown visualizations highlighting the impact of sourcing strategies on unit economics and margin corridors.
- A playbook for M&A and JVs that outlines valuation drivers, integration checklists, and three archetypal transaction structures tailored to strategic buyers, finance sponsors and technology acquirers.
- Commercialization roadmaps with phased KPIs for pilot validation, ramp, and series production, plus sample contractual clauses for managing performance guarantees and software updates.
- Regulatory and standards appendix covering the most relevant global requirements and testing protocols that will influence design choices and certification paths.
To preserve the report’s strategic value for subscribers, we intentionally omit granular regional and application splits from this summary. The complete dataset, including granular segmentation, pricing curves and downloadable Excel models, is available in the full report package.
Risk, Scenarios and Contingency Planning
Our scenario analysis outlines three plausible market pathways and corresponding response strategies for 2026:
- Accelerated Adoption Scenario — Faster-than-expected EV penetration and regulatory mandates drive higher adoption of integrated one-box systems. Recommended responses: prioritize software-first integration partners, pre-qualify multiple suppliers, and secure long-lead electronic components.
- Staggered Adoption Scenario — Gradual uptake with patchwork regional adoption. Recommended responses: adopt a modular product strategy, maintain dual-sourcing for critical components, and employ targeted pilot programs to de-risk product-market fit.
- Consolidation Scenario — Price pressure and OEM consolidation increase churn among suppliers. Recommended responses: pursue strategic consolidation, focus on differentiated IP (control algorithms, cybersecurity) and lock-in OEM telematics interfaces.
Each scenario includes trigger metrics and recommended board-level actions tailored for 2026 decision cycles. The full report provides a decision-tree tool that translates scenario triggers into project prioritization and budget reallocation recommendations.
How PW Consulting Supports Executives in 2026
PW Consulting couples the report’s insights with bespoke advisory services that help clients move from strategy to execution. Typical engagements initiated in 2026 include:
- Supplier diligence and technical due diligence for M&A targets focused on electro-hydraulic integration IP.
- Co-development advisory and partner selection to accelerate software and actuator co-design for next-generation platforms.
- Manufacturing footprint planning and ramp-management support, including pilot line design and quality assurance protocols for system-level validation.
- Commercial and pricing strategy aligned to OEM procurement frameworks and long-term service agreements.
Concluding View — Making the 2026 Move
For executives planning investments and strategic moves in 2026, the one-box electro hydraulic braking market represents both a clear growth opportunity and a concentrated competitive battlefield. The market’s mid-term scale-up will reward players who combine engineering excellence, certification speed, and integrated software capability — but those rewards will accrue disproportionately to organizations that act early and with clear execution plans. PW Consulting’s market study is deliberately engineered to equip decision-makers with the frameworks, benchmarks and executable playbooks necessary to turn strategic intent into measurable outcomes.
To access the full dataset, detailed segmentation, company scorecards and the downloadable scenario model that underpin these findings, consult the full PW Consulting One Box Electro Hydraulic Braking System Market report. The report contains the proprietary charts and appendices that decision-makers will need to finalize 2026 capital, product and partnership plans.
For detailed analysis of this topic, please visit the official page: One Box Electro Hydraulic Braking System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insight: Front-Loaded Industrial Parts Washer Market to Rise from USD 223.45 Million in 2025 to USD 292.4 Million by 2032 at a 3.85% CAGR
By pmarketresearch, 2026-07-02
Front Loaded Industrial Parts Washer Market 2026: Strategic Imperatives for Operational Leaders
As manufacturers recalibrate capital plans and sustainability roadmaps for 2026, PW Consulting’s new Front Loaded Industrial Parts Washer Market report delivers the focused market intelligence executives need to prioritize investment, procurement, and product development decisions. Drawing on a rigorous base year of 2025 and a forecast through 2032, the study synthesizes trend signals across technology, regulation, costs, and competitive moves to reveal where front-loaded parts washing will create operational leverage — and where it will merely protect the status quo.
Front Loaded Industrial Parts Washer Market
Market snapshot: a stable base with steady, targeted growth
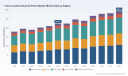
Our analysis shows the front loaded industrial parts washer market reached approximately USD 223.45 Million in 2025. From this base, the market is expected to expand at a compound annual growth rate (CAGR) of 3.85% over the 2026–2032 forecast window, reflecting measured growth driven by replacement cycles, incremental automation adoption, and regulatory pressures that favor aqueous systems. By 2032 our model projects a market trajectory consistent with these forces, underscoring the importance of timing for procurement and product rollouts.
Front Loaded Industrial Parts Washer Market
Why 2026 is a pivot year for corporate decision-makers
- Capital allocation clarity: With modest but persistent growth, 2026 is less about chasing volume peaks and more about allocating capital to solutions that reduce lifecycle costs (energy, maintenance, regulatory compliance). Firms that prioritize durability, serviceability, and energy efficiency will capture outsized ROI over a 5–10 year horizon.
- Regulatory-driven product selection: The shift to aqueous cleaners is not merely environmental virtue signaling — it’s a pragmatic response to evolving hazardous waste regulations. Purchasing teams must weigh the avoided costs and operational simplicity of aqueous front-load systems against the legacy strengths of solvent approaches.
- Consolidation and partnerships: Market concentration metrics reveal a landscape where the top three players account for roughly one third of market revenue, and the top five approach half. That structure creates opportunities for mid-sized suppliers to differentiate through service models, customization, and channel partnerships.
Operational levers that matter for 2026
- Lifecycle cost modeling: Stainless steel construction commands higher upfront spend but offers lower maintenance and longer service lives — a critical consideration for plants planning 10–20 year equipment horizons.
- Energy and thermal efficiency: Modern front-load aqueous washers incorporate insulated chambers and more efficient heating systems capable of operating up to 200°F. Energy optimization will be a decisive factor in total cost of ownership calculations, especially for high-cycle environments.
- Modularity and serviceability: Select systems provide configuration flexibility (turntables, conveyors, immersion, ultrasonic options) that reduce customization lead times and spare-parts inventories.
- Compliance and waste management: Eliminating solvent waste simplifies compliance and can lower disposal costs; procurement teams should explicitly quantify these savings in payback models.
Competitive landscape: profiles, positioning, and near-term moves
The competitive field blends legacy machine builders, specialist fabricators, and service-oriented providers. Below we synthesize the strategic positioning and recent activity of core firms featured in our report — a practical snapshot to inform vendor selection and partnership scouting.
Front Loaded Industrial Parts Washer Market
- Alliance Manufacturing, Inc. (Fond du Lac, WI) — https://www.alliancemfginc.com/
Alliance brings a broad portfolio of front/top-loading aqueous cabinets complemented by custom conveyor and rotary systems. Its presence at major trade events (scheduled exhibitions at WIMTS 2025 and IMTS 2026) signals an aggressive outreach strategy focused on OEM and heavy-industry channels. For buyers, Alliance is a candidate where configurability and demonstrated machine throughput matter.
- Better Engineering Manufacturing, Inc. (Joppa, MD) — https://www.betterengineering.com/
Better Engineering emphasizes custom solutions — turntables, conveyors, immersion and ultrasonic systems — targeting precision cleaning and high-volume manufacturing. Their strength lies in tailored engineering services and hybrid system designs that can integrate into existing lines with minimal disruption.
- Renegade Parts Washers / Service Line, Inc. (Reedsburg, WI) — https://renegadepartswashers.com/
Renegade’s I-Series and FL Series machines focus on high-load, heavy-duty cleaning. A recent website refresh in January 2026 highlights product documentation and support resources, an indicator of a company investing in buyer enablement and aftermarket service visibility.
- Cuda Cleaning Systems (Watertown, SD) — https://cudausa.com/
Cuda’s product family of front-load automatic aqueous washers targets solvent-free cleaning in the automotive and industrial maintenance sectors. Their model strategy emphasizes standardized offerings for broad OEM and aftermarket penetration, appealing to buyers who value quick procurement and repeatable performance.
- Safety-Kleen (Plano, TX) — https://www.safety-kleen.com/
Safety-Kleen leverages a service- and safety-first positioning, offering front-loading automatic spray washers with turntable systems and an emphasis on automation and compliance features. Their channel model tends to favor integrated service contracts and environmental risk mitigation.
- Graymills Corporation (Chicago, IL) — https://www.graymills.com/
Graymills builds premium front-load spray wash cabinets designed for high-pressure aqueous cleaning. The firm’s reputation centers on robust industrial specs and high-performance cleaning cycles suitable for demanding shop-floor environments.
- Alkota Cleaning Systems (Alcester, SD) — https://alkota.com/
Alkota offers front-load washers for small- to medium-sized parts, targeting maintenance shops and light manufacturing. Their value proposition is straightforward — cost-effective, compact solutions with reliable service networks.
- Niagara Systems LLC (Mentor, OH) — https://niagarasystemsllc.com/
Niagara emphasizes custom cabinets and front-load configurations, positioning itself as a flexible engineering partner for unique cleaning challenges where standard off-the-shelf units fall short.
Recent vendor activity: what it signals
- Trade show investments by established players indicate continued emphasis on OEM channels and on-floor demonstrations — a reminder that tactile evaluation remains important for higher-ticket equipment.
- Digital refreshes and expanded online support resources reflect a broader industry move to reduce buyer friction and accelerate post-sale service engagement.
Market dynamics and risk factors
Three structural dynamics should guide 2026 decision-making:
- Regulatory tailwinds: Facilities shifting from solvent to aqueous washers reduce hazardous waste liabilities. This trend is not uniform across jurisdictions, but its aggregate effect is to raise the floor on aqueous adoption over the medium term.
- Material and build economics: Choosing stainless steel versus mild steel construction is a classic tradeoff: roughly 35% higher upfront cost for stainless in many configurations, offset by lower maintenance and longer useful life. Strategic buyers should model maintenance cycles and parts inventories rather than focusing solely on capital outlay.
- Energy consumption and operating design: Thermal efficiency gains — insulated chambers and optimized heating — materially affect operating cost in high-throughput environments. Energy considerations should be treated as a first-order variable in TCO models.
What the PW Consulting report delivers — actionable elements
This report is structured for immediate application by procurement teams, plant managers, and product strategists. Key, actionable deliverables include:
- Executive decision frameworks for equipment selection, including TCO templates that incorporate energy, maintenance, and regulatory compliance variables.
- Vendor assessment matrices that map capabilities (customization, throughput, service coverage, safety features) against buyer priorities.
- Scenario-based procurement timelines aligned to the industry replacement cycle and CAPEX budgeting windows, enabling phased deployments that minimize operational disruption.
- Risk registers and mitigation strategies related to supply chain (materials for durable construction), energy pricing sensitivity, and regulatory shifts.
- Practical implementation checklists for commissioning, validation, and training to accelerate time-to-value post-installation.
How to use this analysis in boardroom and plant-floor conversations
- For CFOs and procurement leads: use the report’s TCO templates to normalize vendor proposals and to compare payback across stainless versus mild steel options, as well as different energy-efficiency tiers.
- For operations and maintenance leaders: prioritize modular designs and strong aftermarket commitments to reduce downtime risk and spare-part inventories.
- For product and R&D teams: focus on thermal efficiency, control-system integration, and serviceability features that lower lifecycle costs — these are the differentiators buyers will pay a premium for through 2032.
Concluding guidance
With a measured CAGR near 3.85% and a market base exceeding USD 220 million in 2025, the front loaded industrial parts washer market presents predictable growth anchored in compliance, efficiency, and replacement demand. However, the real performance differentiator for suppliers and buyers alike will be the ability to translate engineering features into quantifiable lifecycle savings and regulatory risk reduction. PW Consulting’s Front Loaded Industrial Parts Washer Market report provides the analytical scaffolding and practical tools to do exactly that — with deeper segmentation, scenario models, and procurement-ready templates housed in the full study.
Take the next step
This release is a strategic preview. To access the complete segmentation, full vendor scorecards, and downloadable TCO models that support procurement and capital planning in 2026, please visit the PW Consulting report portal. The full report contains the granular data and templates you will need to operationalize the insights summarized above.
For detailed analysis of this topic, please visit the official page: Front Loaded Industrial Parts Washer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: E-Beam Accelerators Market to Grow at 4.15% CAGR, Reaching USD 270 Million by 2032
By pmarketresearch, 2026-07-02
E‑Beam Accelerators Market: Strategic Insights to Guide Corporate Decisions in 2026
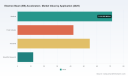
PW Consulting is pleased to publish a focused industry briefing drawn from our new E‑Beam Accelerators Market report (base year: 2025). Designed for C‑suite leaders, corporate development teams, and industrial technology investors, this briefing translates market dynamics, competitive positioning, and practical adoption roadmaps into decisive actions for 2026. The global market for electron beam (E‑beam) accelerators has demonstrated steady expansion—from the mid‑double digits in 2020 to USD 180 Million in 2025—and is forecast to continue growing through 2032 at a compound annual growth rate of 4.15%. By 2032 the market is projected to reach roughly USD 270 Million. These macro trajectories provide the context for the strategic choices that follow.
E Beam Accelerators Market
Why this report matters for 2026 decisions
-
Timing and scale: The market has moved from early‑adopter investments toward broader industrial adoption. The modest but consistent growth profile signals that 2026 is a pivotal year to shift from exploratory pilots to operational scaling for the right use cases.
E Beam Accelerators Market -
Risk‑reward clarity: Our analysis isolates the commercial and regulatory variables that most materially affect near‑term returns—enabling executive teams to prioritize capital deployment with clearer downside protection.
E Beam Accelerators Market -
Competitive intelligence: The report synthesizes vendor capabilities, recent commercial developments, and service models so buyers and potential partners can match supplier profiles to their own operating requirements.
What the PW Consulting report delivers (practical, executable content)
-
Concise market sizing and trend maps covering 2020–2025 historical data and 2026–2032 forecasts—presented with scenario paths and sensitivity analyses that isolate demand drivers and policy risk.
-
Decision frameworks for purchasers and investors—covering build vs. buy, financing and lifecycle cost models (CapEx vs. OpEx), and service contract negotiation checklists tailored to E‑beam equipment.
-
Go‑to‑market and commercialization playbooks for equipment OEMs and service providers—addressing channel design, irradiation center economics, and retrofit strategies for incumbent industrial installations.
-
Regulatory and standards mapping—identifying certification timelines, inspection regimes, and market access contingencies that materially influence procurement schedules.
-
Use‑case deep dives—with practical ROI models for high‑impact applications such as sterilization, polymer modification, and niche environmental treatments—presented without revealing proprietary segmentation detail, to protect competitive insights while enabling action.
-
M&A and partnership screening criteria—highlighting the profile of attractive targets and the likely post‑deal value capture levers (service integration, geographic reach, and technologies enabling higher throughput).
Market structure and competitive dynamics — what to watch in 2026
The E‑beam accelerator market sits in a middle‑concentration regime: a handful of established OEMs and specialized system integrators own a meaningful share of installed capacity and service revenue, yet there remains room for regional challengers and technology specialists to grow. PW Consulting measures concentration metrics that confirm a competitive landscape where the top three players account for a plurality, while the top five approach two‑thirds of market value—creating both stability and pockets of competitive opportunity.
Key player archetypes emerge from our company profiling:
-
Integrated systems OEMs with global service networks: Firms offering end‑to‑end solutions and integrated maintenance services tend to capture higher life‑time value from sterilization and industrial clients. Their strength is predictable uptime and bundled contracting.
-
Regional manufacturing leaders and irradiation center operators: These players combine localized manufacturing with irradiator operations, which helps lower logistics cost and accelerate time‑to‑market for applications such as polymer cross‑linking.
-
Specialist low‑voltage solution providers: Companies that lead in low‑voltage EB systems enjoy a competitive edge in thin‑film and flexible packaging sectors where compact footprints and low operating complexity matter.
-
Custom systems and integration houses: Smaller, highly technical firms focus on bespoke builds for wire, cable, and advanced materials—winning business where standard platforms cannot meet unique production lines.
Representative company developments in early 2025–2026 underscore the strategic thrusts shaping vendor competition. Examples include a Japan‑based systems supplier moving to commercialize a real‑time EPS monitoring solution through a production line contract with a tyre manufacturer, and a Chinese accelerator designer delivering its first EU unit—each signaling shifts in service offerings and geographic expansion. A European supplier’s multi‑accelerator deployment for industrial irradiation speaks to growing demand for higher‑throughput applications. These and other trade‑show activities reflect both product innovation and intensifying commercial engagement with key industries.
Strategic implications for buyers, investors, and OEMs
-
Buyers — prioritize operational resilience and service economics: For manufacturing and sterilization customers, procurement decisions should be driven as much by the service and monitoring propositions as by headline equipment specifications. Contracts that include predictive maintenance, spare‑parts pipelines, and uptime guarantees materially shorten payback windows.
-
Investors — seek compound optionality: Given the market’s steady growth profile, investment cases that combine equipment sales with recurring service or irradiation center revenues present more attractive risk‑adjusted returns than pure hardware bets. Early‑mover positions in service platforms (digital monitoring, remote diagnostics) can create durable differentiation.
-
OEMs — scale through modularity and partnerships: For manufacturers, pursuing modular designs and certified integration partners accelerates deployment into regulated end markets. Expanding channel service footprints or partnering with regional irradiation operators reduces adoption friction and supports premium pricing.
Operational playbook: five tactical moves for 2026
-
Lock in service capabilities now — secure service contracts, regional technicians, and spare‑parts logistics before demand accelerates; service continuity will be a primary competitive battleground.
-
Pilot monitoring and retrofit programs — deploy digital monitoring pilots (e.g., EPS monitoring systems) on strategic lines to validate uptime improvements and justify broader rollouts.
-
Mitigate supplier concentration risk — diversify sourcing for critical modules and consider dual‑supplier strategies for key components to reduce lead‑time exposure.
-
Negotiate outcome‑based contracts — where possible, structure deals around throughput, availability, or sterilization yield to align supplier incentives with operational outcomes.
-
Build a regulatory playbook — map certification requirements across target geographies and integrate clearance timelines into procurement and deployment schedules.
Scenario planning and financial sensitivity
PW Consulting’s forecast envelope presents baseline, upside, and downside scenarios for 2026–2032 that hinge on four variables: regulatory clarity, capex cycles in medical and food sectors, speed of technology adoption (digital monitoring and higher‑energy systems), and macro‑supply chain stability. Our baseline—reflecting current policy and investment momentum—assumes continued steady growth at approximately 4.15% CAGR over the forecast period. Clients receive downloadable financial models in the full report to test investment outcomes under alternative assumptions (e.g., faster sterilization adoption, constrained supply lines, or accelerated regulatory approvals).
M&A and partnership opportunities
Given the current market structure, attractive targets include regional integrators with established irradiation centers, specialist OEMs with proven niche technologies, and service platform providers enabling remote monitoring and predictive maintenance. Buyers should prioritize targets that can deliver immediate recurring revenue uplift, accelerate geographic entry, or provide complementary technology stacks that reduce time‑to‑market for larger industrial customers.
What we recommend next
-
For strategic buyers: run a focused due‑diligence sprint on service economics and installed‑base attrition risk, using the report’s buy vs. build frameworks to stress‑test acquisition scenarios.
-
For OEMs: accelerate development of monitoring and service packages; pilot with anchor customers to create reference cases that lower sales friction.
-
For investors: prioritize deals that combine hardware with recurring services or irradiation center models to capture higher life‑time value.
-
For procurement and operations leaders: integrate regulatory timelines and spare‑parts availability into 2026 capital plans; prioritize suppliers showing demonstrable service capacity and local support.
How PW Consulting’s report supports implementation
The full E‑Beam Accelerators Market report provides the empirical foundation and execution tools to convert strategic intent into operational plans. It includes: detailed historical data (2020–2025), baseline and scenario forecasts (2026–2032), vendor scorecards, a procurement negotiation playbook, and downloadable financial models. To preserve competitive value for subscribing clients, the report presents full segmentation tables and application‑level breakdowns behind secure access—ensuring that decision‑makers can drill into the specific regional, type, and application splits they need to act upon.
Closing — why act in 2026
2026 represents an inflection year in the E‑beam market where steady macro growth combines with accelerating service innovation and wider industrial acceptance. Companies able to couple disciplined procurement with service‑oriented commercial models will capture outsized value as the market matures. PW Consulting’s report translates data and field intelligence into the practical steps organizations need to take now to convert market momentum into sustainable competitive advantage.
For access to the full dataset, segmentation tables, and vendor scorecards to inform deal execution and procurement decisions, visit the PW Consulting research portal to download the complete E‑Beam Accelerators Market report and supporting tools.
For detailed analysis of this topic, please visit the official page: E Beam Accelerators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Turbine Inlet Air Cooling (TIAC) Market Poised for Robust Growth — 7.35% CAGR Projected for 2026–2032
By pmarketresearch, 2026-07-02
Turbine Inlet Air Cooling (TIAC) Market: Strategic Compass for 2026 Decisions
As air temperatures rise and grid dynamics become more volatile, the role of Turbine Inlet Air Cooling (TIAC) in safeguarding and augmenting gas-turbine output has moved from niche optimization to board-level strategic planning. PW Consulting’s latest market study — covering 2020–2025 history and a 2026–2032 forecast horizon — distills the actionable intelligence executives need to make high‑confidence capital, procurement, and partnership decisions in 2026. This release outlines the report’s high-level findings, competitive map, and practical tools while deliberately withholding the granular segment tables and model outputs that deliver the full investment case (available in the full report).
Turbine Inlet Air Cooling (TIAC) Market
Market Trajectory — What the headline numbers mean for strategy
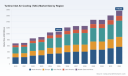
Our macro modelling shows the global TIAC market expanding materially over the next decade. After advancing through a cyclical recovery in 2020–2025, the market is forecast to grow at a compound annual growth rate (CAGR) of approximately 7.35% across 2026–2032. The overall market scale exceeds one billion USD by the 2025 base year and grows into the multi‑billion range over the forecast period. This trajectory reflects three intersecting forces: (1) ongoing demand for peak and mid‑merit power capacity optimization, (2) the operational economics of output augmentation in warm climates, and (3) technology-led cost declines and modularization enabling faster deployments.
Turbine Inlet Air Cooling (TIAC) Market
For executives, the headline takeaway is clear: TIAC is no longer a tactical add‑on; it is an investable capability that can materially influence plant-level dispatch economics and fleet availability. The CAGR implies that waiting for “perfect” market conditions risks being outpaced by competitors who deploy TIAC to secure more reliable, flexible generation capacity.
Turbine Inlet Air Cooling (TIAC) Market
Why 2026 is a pivotal decision window
- CapEx and replacement cycles: Many gas‑turbine operators are entering scheduled overhauls in 2026–2028. These windows minimize integration costs for TIAC systems compared with brownfield retrofits outside outage windows.
- Grid flexibility premium: Markets valuing fast-response capacity and ancillary services are increasing the revenue uplift associated with higher turbine output and ramp capability — creating improved payback profiles for TIAC investments.
- Supplier consolidation and M&A: Recent transactions demonstrate industry consolidation, altering supplier bargaining power and acquisition targets for industrial buyers seeking vertically integrated solutions.
Report anatomy — what PW Consulting provides (practical, modelled, implementable)
PW Consulting’s TIAC study is structured to move executives from strategic intent to executable plans in months, not years. Key deliverables include:
- Market sizing and forecast model (interactive): scenario‑driven top‑down forecasts with sensitivity levers for ambient temperature trends, gas turbine fleet retirement/retrofit rates, and regional demand growth. Note: the public synopsis highlights overall market scale and growth rate; the detailed model that disaggregates by region, type, and application is only available in the full report.
- Investment and payback toolkit: plant-level financial templates that calculate IRR, NPV, and simple payback under variable fuel, power price, and capacity-remuneration regimes.
- Technology decision matrix: a pragmatic framework that maps evaporative systems, fogging, mechanical chillers, and absorption chillers to site conditions (humidity, space, water availability), regulatory constraints, and O&M complexity.
- Procurement and contracting playbook: standardised RFP language, performance acceptance tests, and warranty structures tailored to TIAC modules and integrated systems.
- Deployment playbooks: modular installation pathways (containerized chillers, field-built evaporative systems, packaged fogging), integration checklists for control systems, and commissioning sequencing aligned with turbine maintenance windows.
- Risk and resilience matrix: supply‑chain stress tests, raw‑material exposure analysis, and contingency plans for prolonged warm‑season demand peaks.
Competitive landscape — who matters and why
The TIAC supplier ecosystem is diverse: specialist system integrators, large HVAC and chiller OEMs, and filtration and humidification technology providers converge on the value chain. The market concentration is moderate: the top three players account for a meaningful but not overwhelming share of market revenues, and the top five collectively hold a clear majority, reflecting an industry where regional specialists coexist with global suppliers.
Selected company profiles and recent moves highlighted in the report illustrate the strategic positioning you should monitor as you shape 2026 agendas:
- Stellar Energy (Jacksonville, Florida) — turnkey TIAC systems with thermal energy storage options; claims of up to 30% turbine output enhancement position them strongly for integrated power and data‑center cooling opportunities. Their acquisition by a major thermal systems player in early 2026 underscores the attractiveness of TIAC technologies to broader HVAC/energy companies and signals further consolidation.
- ARANER (Madrid, Spain) — specialist in indirect cooling with heat-exchanger approaches and condensate management; their engineering focus is well-suited to sites where water constraints or regulatory limits favour indirect solutions.
- Mee Industries (California) — leading high‑pressure fogging systems provider; recent industry recognition and product content publications indicate an effort to codify performance benefits and accelerate adoption.
- Johnson Controls (global) — mechanical chiller packaging and containerized systems; their global supply footprint and packaged product lines make them a logical partner for fastest time‑to‑market deployments.
- SPX Cooling Technologies, Munters, Camfil, Caldwell Energy — firms that span evaporative cooling, fogging, filtration, and system integration; their offerings illustrate the modular build vs. integrated system tradeoff faced by buyers.
These profiles reveal two strategic supplier archetypes: product‑centric OEMs (packaged chillers, foggers, filtration) and solution integrators that bundle hardware, controls, and performance guarantees. Buyers should decide whether to optimize for lowest CAPEX (product buys + internal integration) or lowest time/operational risk (turnkey systems with performance contracts).
Market dynamics and risk factors to factor into 2026 planning
- Regulatory and standards environment: Industry bodies continue to develop best practices and standards for TIAC implementation. Organizations that proactively align with these emerging standards will shorten approval cycles and reduce permitting risk.
- Supply‑chain and input cost pressure: Rising commodity prices for steel and aluminum have increased manufacturing input costs for cooling system components. Procurement strategies must incorporate input‑cost escalation clauses, multi‑vendor sourcing, and longer lead‑time planning for critical frames and heat‑exchanger cores.
- Water availability and environmental constraints: Site water use and condensate handling are growing determinants in technology selection, particularly in arid regions. Indirect and closed‑loop systems require more CAPEX but can avoid regulatory constraints associated with evaporative approaches.
- Technology convergence: Thermal energy storage, hybrid cooling architectures, and IoT-enabled controls are creating new value pools by enabling time‑shifted cooling and predictive performance guarantees.
Actionable recommendations for executives (fast moves and strategic bets)
- Supply‑chain readiness (fast move): Lock lead times and component prices for projects scheduled in 2026–2028. Consider call‑off orders or vendor financing where possible to protect against commodity inflation.
- Bundle vs. buy decision framework (fast move): Use a three‑criterion assessment (time to revenue, integration risk, total lifecycle cost) to decide between turnkey providers and best‑of‑breed OEM stacks on each project.
- Targeted pilots (strategic bet): Run two pilots in the 2026 window — one with a high‑augmentation solution (e.g., fogging + wet compression) and one with a conservative, low‑water indirect chiller — to produce empiric delta performance and refine financial models for fleet rollouts.
- M&A and partnership scanning (strategic bet): Monitor specialist integrators and thermal‑storage players as potential acquisition targets to accelerate capability ownership and capture margin uplift from bundled services.
- Contracting innovation (operational): Negotiate performance‑linked contracts where vendors accept partial performance risk in return for higher maintenance or upgrade fees — aligning incentives and de‑risking capital deployment.
What the full PW Consulting TIAC report delivers (and why you should download it)
The public brief identifies the market’s direction and primary decision levers. The full report provides the proprietary, drillable analytics that translate insight into executable project plans: region and application breakdowns, technology share modelling, plant‑level ROI calculators, vendor scorecards, and a suite of procurement templates. We intentionally withhold the granular segmentation figures from this overview to preserve the value of the proprietary datasets and modelling logic that enable confident capital allocation.
If you are evaluating capacity upgrades, negotiating supplier contracts, or sizing acquisition targets in 2026, the full TIAC market study supplies the comparative data, scenario stress‑testing, and commercial templates you need to shorten decision cycles and reduce execution risk.
Next steps
- Download the full report to access the detailed regional, technology, and application models along with the interactive financial toolkit.
- Schedule a briefing with PW Consulting to run a customized site‑level assessment using our plant‑level ROI model and vendor selection matrix.
- Use the procurement playbook immediately to preview standardised RFP language and acceptance testing criteria for your 2026 procurement cycle.
TIAC is more than a technical retrofit; it is a strategic lever for capacity monetization and resilience in a warming world. For leaders shaping 2026 investment plans, the question is not whether TIAC can add value, but how quickly you can operationalize that value into controllable, revenue‑generating capacity. PW Consulting’s TIAC study gives you the roadmap, tools, and vendor insights required to move from consideration to commissioning within the next procurement cycle.
For detailed analysis of this topic, please visit the official page: Turbine Inlet Air Cooling (TIAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Precision Agriculture GNSS Guidance System Market Poised to Expand at an 8.75% CAGR, Reveals New Insights
By pmarketresearch, 2026-07-01
Precision Agriculture GNSS Guidance System Market — Strategic Insights for 2026 Decision-Makers
Executive summary
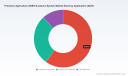
PW Consulting’s new market research brief on the Precision Agriculture GNSS Guidance System market synthesizes five years of observed adoption (2020–2025) and produces an actionable forecast across 2026–2032. The market has moved from a mid-single‑digit billion-dollar base in 2020 to an estimated USD 3,530 million in 2025, and our modelling now points to continued expansion at a compound annual growth rate (CAGR) of 8.75% through 2032, with the global market exceeding USD 6.35 billion by the end of the forecast period. Concentration metrics indicate a moderately consolidated vendor landscape (CR3 ~52.3%, CR5 ~68.7%), with clear implications for procurement, partnership strategy, and competitive response.
Precision Agriculture Gnss Guidance System Market
Why this matters for 2026 strategy
Decision-makers planning capital allocation, product roadmaps, and channel strategies in 2026 face a compressed window for differentiation. The combination of accelerating farmer uptake, government reimbursement mechanisms, maturation of PPP/RTK correction services, and rapid integration of autonomy technologies create both risk and opportunity. Our report is designed as a practical playbook for corporate leaders, farm-equipment OEMs, retrofit suppliers, and large-scale agricultural operators who must decide where to invest in the next 12–18 months to capture disproportionate value through 2032.
Precision Agriculture Gnss Guidance System Market
Market dynamics shaping the next phase
- Macro growth trajectory: Rapid revenue expansion from 2020 through 2025 validates underlying demand for accuracy, automation, and fleet interoperability. The forecasted 8.75% CAGR reflects continued commercialisation of higher-precision solutions, declining hardware costs, and stronger software/service monetisation.
- Consolidation and concentration: A top-heavy vendor landscape (CR3 and CR5 indicators) means partnerships, OEM access, and channel control are decisive competitive levers. Smaller specialists remain crucial for niche innovation but face distribution and scale challenges.
- Regulatory and policy tailwinds: Public augmentation services (e.g., regional SBAS implementations) and notable policy levers increase adoption economics. Notably, reimbursement mechanisms introduced in the latest agricultural policy cycles—designed to accelerate precision technology adoption—are material for the 2026 buying cycle.
- Technical resilience and platform interoperability: Ionospheric disturbances, GPS datum modernisation initiatives planned for 2026, and supply‑chain pressures for key hardware components have elevated system robustness and multi-constellation, multi-correction solutions from “nice-to-have” features to procurement must-haves.
- Automation frontier: Vision-augmented autonomy and active implement steering are moving from concept demos to commercial pilot phases, reshaping product roadmaps for both OEMs and retrofit players.
What the PW Consulting report contains — practical, decision-ready deliverables
This study is built as a decision-support package, balancing market intelligence with applied tools executives can use immediately. The report includes:
Precision Agriculture Gnss Guidance System Market
- Top-line historical and forecasted market sizing (2020–2032) with scenario-based sensitivity analysis to test alternate adoption and pricing paths.
- Vendor landscaping and a proprietary vendor scoring matrix covering technology stack (receiver, correction service, antenna), platform openness, retrofit capability, and go‑to‑market reach.
- Commercial models: unit economics, Total Cost of Ownership (TCO) templates, and multi-year ROI calculators tailored for OEMs, dealers, and farm operators.
- Procurement playbook for 2026: specification checklists, interoperability validation steps, and supplier negotiation levers to mitigate supply‑chain and tariff shocks.
- Use-case deep dives — tractors & harvesters, sprayers/spreaders, and emerging autonomy implementations — showing where precision guidance drives yield, input savings, and operational efficiency.
- Regulatory and policy impact assessment, including actionable guidance on leveraging reimbursement programs and preparing for datum modernisation and public augmentation services in your systems and documentation.
- Go-to-market options and partnership archetypes: OEM integration, retrofit channel scaling, and software-as-a-service monetisation strategies.
Competitive landscape — who matters and why
The competitive environment is a mix of vertically integrated OEMs and specialised GNSS vendors. Key players analysed in the report include established OEM platform leaders, global GNSS specialists, and fast-growing retrofit players. Highlights include:
- John Deere (Deere & Company): Strength lies in integrated factory-installed guidance, a large installed base, and ecosystem lock-in. Strategy considerations focus on balancing proprietary benefits with farmer demand for cross-vendor interoperability.
- PTx Trimble (Trimble/PTx): Market-leading corrections and resilience features (including recent releases targeted at ionospheric disturbance mitigation) position the company well for mixed-fleet compatibility and reliability-critical deployments.
- CHC Navigation (CHCNAV): Aggressive cost-performance positioning for retrofit markets and expanded PPP services enable market penetration in regions with limited RTK infrastructure.
- Hexagon (NovAtel / HxGN AgrOn): OEM-focused high-precision components and correction services help machine manufacturers deliver integrated machine control with predictable performance guarantees.
- Topcon: A broad portfolio of GNSS, corrections, and emerging partnerships with autonomy players signal the firm’s push into vision-fused, machine-centric solutions.
- AG Leader, CNH Industrial (Raven), Hemisphere/Outback: Each brings targeted strengths — user-centric consoles and data workflows, modular connectivity platforms for OEM fleets, and specialized machine-control systems for retrofit applications.
The report’s vendor scorecards combine technical capability, field-proven robustness, go-to-market footprint, and partnership flexibility. Recent corporate moves — such as the launch of ionospheric-resilient correction technologies, trade-show showcases of active implement steering, and strategic autonomy partnerships — are evaluated for their likely competitive impact over the 2026 planning cycle.
Key recent developments to factor into 2026 plans
- Product enhancements improving GNSS resilience during solar/ionospheric activity are now commercially available; procurement specifications should include resilience performance thresholds.
- Major trade-show demonstrations have shifted several retrofit autonomy concepts toward mid‑2026 commercial availability; integration timelines need to be revisited for product roadmaps.
- Strategic partnerships between GNSS vendors and vision/autonomy specialists create new go-to-market pathways — particularly relevant for OEMs looking to outsource perception stacks.
- Regulatory movements (public augmentation services and datum modernisation, plus targeted reimbursement programs) materially change adoption economics and mapping workflows; these are quantified and operationalised in the report.
Strategic imperatives for 2026 — where to play, how to win
- Prioritise interoperability: Require multi-correction support (RTK, PPP, SBAS) and open APIs in RFPs to protect fleet operators and enable future sensor fusion.
- Design for resilience: Specify ionospheric disturbance mitigation and fallback modes; include these metrics in acceptance testing.
- Time procurement to policy windows: Align major purchases with reimbursement program cycles to maximise subsidy capture and shorten payback periods.
- Modularise product roadmaps: Separate core guidance from perception/autonomy modules to accelerate partnerships and limit capital exposure.
- Mitigate supply risks: Build dual-sourcing strategies for critical hardware and model tariff scenarios in procurement budgets.
- Invest in dealer enablement: Field execution and uptime matter; training, remote diagnostics, and service delivery are now as important as unit precision.
How PW Consulting supports execution
Beyond analysis, PW Consulting offers tailored advisory and implementation services designed to translate the report’s insights into measurable outcomes: vendor due diligence and negotiation support, ROI modelling for specific fleets or geographies, integration blueprints for autonomy pilots, and dealer/channel enablement programs. Our proprietary templates and stress-tested scenario models reduce decision latency and increase the probability of successful deployment.
Next steps — access to the full intelligence
This release is a strategic preview of the full PW Consulting Precision Agriculture GNSS Guidance System Market report. For 2026 planning, we strongly recommend stakeholders obtain the complete study, which contains the region- and application-level breakouts, full vendor scorecards, downloadable financial models, and a 12-point procurement checklist. These granular elements are intentionally reserved for the full report to preserve commercial value and enable tailored consultancy engagement.
Contact PW Consulting to request the full report, schedule a briefing with our senior industry analysts, or commission a custom 90‑day implementation roadmap aligned to your 2026 strategic objectives.
For detailed analysis of this topic, please visit the official page: Precision Agriculture Gnss Guidance System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Body Repair Fillers Market Set to Rise from USD 3,600M in 2025 to USD 5,015.4M by 2032 at a 4.85% CAGR
By pmarketresearch, 2026-07-01
Automotive Body Repair Fillers Market: A Strategic Preview for 2026 Decision‑Makers
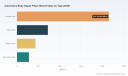
PW Consulting’s latest market intelligence on the Automotive Body Repair Fillers market equips executives, product leaders and M&A teams with the strategic orientation they need for 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study synthesizes macro demand trajectories, supplier economics, raw‑material stress tests and regulatory scenario planning. In short: the market reached approximately USD 3.6 billion in 2025 and is forecast to grow at a 4.85% CAGR through the 2026–2032 period, converging toward the mid‑single‑digit‑billion range by the end of the forecast. This briefing highlights the decision‑critical insights inside the full report while intentionally withholding core breakouts to prompt direct engagement with PW Consulting’s primary analysis.
Automotive Body Repair Fillers Market
Why this market matters to your 2026 playbook
-
Profit pools are shifting. Modest overall growth masks divergent economics between product classes, formulation pathways (solvent vs water‑based vs UV), and channel end‑uses (collision, surface prep, restoration). Executive capital allocation in 2026 must prioritize product lines and customers that can sustain margin under volatile input costs and tightening regulatory scrutiny.
Automotive Body Repair Fillers Market -
Input volatility is no longer episodic. Polyester resins and other feedstocks experienced extreme swings during 2020–2025 — our industry dataset shows peak‑to‑trough movements exceeding 40% for key unsaturated polyester inputs — and petroleum‑linked components remain exposed to global oil market shocks. Supply‑chain resilience and hedging strategies will materially affect competitiveness.
Automotive Body Repair Fillers Market -
Regulation is a strategic variable. Pending evaluations by regulatory authorities (notably ECHA assessments around styrene) introduce asymmetric downside risk for polyester‑based systems. Firms that preemptively diversify into lower‑styrene or non‑styrene chemistries, or that adopt UV and water‑based technologies, will have optionality if authorization regimes tighten.
What PW Consulting’s report delivers (practical content summary)
-
Forward‑looking market architecture: A granular forecasting engine that projects total market growth under multiple macroeconomic scenarios, with sensitivity knobs for raw‑material price shocks, vehicle parc evolution and repair rate trends.
-
Competitive positioning and concentration analysis: A supplier ecosystem map that identifies capability differentials—formulation depth, vacuum processing competence, UV curing platforms, and channel strength—paired with a concentration assessment showing a market that remains moderately fragmented at the top end.
-
Product and go‑to‑market playbooks: Actionable pathways for premiumization, lightweight and rapid‑repair formulations, and channel segmentation (professional collision repair chains vs independent installers vs restoration specialists), including SKU rationalization templates and margin simulations.
-
Raw‑material stress tests and mitigation strategies: Scenario models quantifying margin compression across different resin and filler price trajectories; recommended procurement levers including index‑linked contracts, multi‑sourcing, backward integration evaluation and strategic inventory buffers.
-
Regulatory scenario planning: A decision tree assessing potential outcomes from chemical reclassification actions and the operational, reformulation and certification costs associated with each outcome.
-
Commercial and M&A playbooks: Target profiles for tuck‑ins, capability buys (e.g., UV curing or water‑based chemistry), and distribution roll‑ups; integration checklists emphasizing technical service, training and brand equity transfer to protect aftermarket revenues.
-
Performance dashboards and KPIs: Practical metrics for manufacturing efficiency, scrap and rework, technical‑service penetration, and channel gross margin — packaged as templates for rapid roll‑out in 2026 planning cycles.
Competitive landscape — who sets the technical and commercial bar
The competitive field blends established global coatings and chemical groups with regional specialists and manufacturing houses focused on formulation performance for professional repair shops. Key players covered in the report include legacy innovators with broad channel reach, specialist filler manufacturers and emerging low‑cost producers focused on global distribution.
-
ITW Evercoat — Cleveland, Ohio. A premium player known for a full suite of body fillers engineered for professional collision repair, with emphasis on easy sanding, minimal pinholes and lightweight formulations. Recent product activity (including a 2025 product refresh and launches showcased at SEMA) signals continued investment in both performance and brand premiumization.
-
3M (including Bondo brands) — St. Paul, Minnesota. An incumbent with strong vacuum‑process capabilities and cross‑substrate chemistry for steel, aluminum and fiberglass. 3M’s portfolio strategy balances professional‑grade Platinum offerings with the high‑recognition Bondo consumer and pro products, creating channel coverage from DIY to high‑end shops.
-
U.S. Chemical & Plastics (USC) — Ohio. A specialty manufacturer focused on spreadability and workability for professional applications; proposition is grounded in consistent performance and shop productivity.
-
U‑POL — United Kingdom. Differentiates on high‑performance adhesives and finishing attributes in European and global markets; a brand to watch where finish quality and adhesion drive spec decisions.
-
AkzoNobel — Amsterdam. Brings refinish and UV‑capable products into the repair ecosystem, and leverages coatings expertise to offer faster cure paths and productivity gains in high‑throughput collision centers.
-
SYNEW — China. Represents the highly competitive cost‑and‑scale segment supplying distributors and professional shops; global ambition is anchored in price/availability advantages but requires consistent quality control to expand premium adoption.
Collectively, the top tier of suppliers account for a minority share of overall market revenue, leaving room for regional specialists and technology leaders to grow share through differentiated value propositions (service, speed, sustainability and cost). PW Consulting’s market concentration metrics quantify this dynamic and the implications for pricing power and consolidation potential.
Strategic implications for 2026 — prioritized actions
-
De‑risk feedstock exposure now: Build procurement playbooks that combine indexed contracts, geographically diversified suppliers and scenario‑based inventory thresholds. For product leaders, allocate R&D to lower‑styrene and water‑borne alternatives as an insurance strategy against regulatory action.
-
Invest selectively in fast‑cure and productivity technologies: UV‑curable primers and vacuum‑processed fillers materially shorten cycle times in collision centers. Capital allocation for R&D, pilot lines and technical service yields high ROI where labor or bay‑time reduction is a premium.
-
Segment your channel strategy: Differentiate SKU sets and service models for multi‑site collision chains versus independents and restoration specialists. Commercial terms, training investments and technical support should reflect the lifetime value and repair throughput of each customer type.
-
Plan for regulatory bifurcation: Create a two‑track product roadmap—iterate existing chemistries for short‑term competitiveness while accelerating a medium‑term switch to lower‑risk formulations.
-
Explore consolidation around capability gaps: Targets that add UV curing, water‑based chemistry, or technical‑service reach represent the most value‑accretive M&A plays in 2026, particularly for players seeking to climb the value chain into finished refinish systems.
How PW Consulting can accelerate your 2026 decisions
Our full Automotive Body Repair Fillers market report provides the empirical backbone behind the guidance above: a calibrated forecast engine, supplier scorecards, raw‑material stress tests, regulatory scenario matrices and executable commercial playbooks. The material is designed for immediate translation into annual operating plans, capital investment cases and M&A diligence materials.
We intentionally limit the disclosure in this press briefing to preserve the commercial value of core segmentation and pricing models. The full dataset contains detailed regional and application splits, type‑level economics, and a complete financial model that ties demand drivers to price and margin outcomes — elements we recommend decision‑makers review before finalizing 2026 budgets and strategy.
Next steps for leaders
-
Request the full report and the accompanying financial model to stress‑test your business under the PW Consulting scenarios.
-
Commission a tailored workshop to translate the market and regulatory scenarios into a prioritized 90‑day action plan for procurement, R&D and commercial teams.
-
Engage our M&A team for target screening using capability‑based filters that align with your 2026 strategic objectives.
Contact PW Consulting to access the complete Automotive Body Repair Fillers market report and schedule a strategy session tailored to your firm’s competitive context. The full intelligence package is necessary for high‑confidence decisions in 2026; this briefing is a strategic preview designed to orient your agenda and identify where to focus scarce executive attention.
For detailed analysis of this topic, please visit the official page: Automotive Body Repair Fillers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fish Nets Market Poised to Expand at a 6.45% CAGR Through 2032
By pmarketresearch, 2026-07-01
Fish Nets Market 2026: Strategic Imperatives from PW Consulting’s Industry Brief
As companies prepare their 2026 budgets and strategic roadmaps, the global fish nets market is no longer a commodity story. It is an intersection of material science, regulation-driven demand, and concentrated supplier dynamics that together re-shape procurement, product development, and M&A choices. PW Consulting’s latest Fish Nets Market research—anchored to a 2025 base year—translates multi-year market evolution into actionable decision levers for executives, investors, and supply‑chain leaders.
Fish Nets Market
Executive snapshot: macro trajectory and what it means
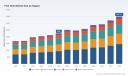
Between 2020 and 2025 the market expanded substantially, reaching approximately USD 2,260 million in 2025. Our forecast through 2032 projects continued expansion to roughly USD 3,501 million by 2032, underpinned by a compound annual growth rate (CAGR) of 6.45% over the 2026–2032 forecast window. This pace signals steady, investment‑grade growth—not the explosive spikes associated with early-stage categories, nor the stagnation of fully commoditized segments.
Fish Nets Market
What this implies for 2026 decision-making:
Fish Nets Market
- Procurement teams should move from transactional to strategic sourcing: long‑term supply agreements for advanced fibers (HDPE, UHMWPE and new biodegradable polymers) will materially reduce unit cost volatility and secure capacity for scaling aquaculture and commercial fishing demands.
- R&D and product teams must re-prioritize materials engineering and circularity: the market rewards nets that deliver durability, lower mass, and recyclability—differentiators that increasingly translate into premium positioning with OEMs and fish farm operators.
- Corporate development should treat the space as consolidation-ready: mid-sized specialists command meaningful share in a market where the top three players account for a significant share and the top five occupy a majority of market concentration—creating opportunities for bolt‑on acquisitions and strategic alliances.
What the report delivers: practical tools, not just forecasts
PW Consulting’s Fish Nets Market report is designed as a playbook for executives, combining strategic narrative with operational templates. Highlights include:
- Market sizing and demand scenarios—baseline, downside, and accelerated adoption trajectories—built from primary interviews, supply‑side capacity checks, and material substitution curves.
- Commercial playbooks for procurement and sales: negotiation levers, contract structures, and pricing sensitivity models for fiber inputs and finished nets.
- Technology and sustainability roadmaps assessing biodegradable polymers, regenerated nylon solutions, and high‑performance polyolefins; with ranked vendor lists and TRL (technology readiness level) assessments.
- Supply‑chain risk matrices and mitigation protocols: dual‑sourcing strategies, inventory buffers, and logistics contingencies calibrated to seasonal fishing cycles and factory lead times.
- M&A and partnership assessment templates: valuation checklists, synergy mapping, and integration risk heat maps tailored to net manufacturers and upstream fiber suppliers.
- Operator-focused ROI calculators for farm-scale and commercial fishing investments—enabling CAPEX/OPEX trade-off analysis for switching net types or adopting circular products.
Competitive landscape: who matters and why
The competitive picture is a hybrid of legacy net makers and innovation-focused specialists. Market concentration metrics indicate the sector is neither atomistic nor a closed oligopoly: the top three firms capture a meaningful portion of demand, while the top five control an outright majority of market share—an important backdrop for strategy.
- Nitto Seimo Co., Ltd. (Tokyo, Japan) : A comprehensive manufacturer active across knotted and knotless systems. Their renewed corporate messaging and digital presence (website refresh, Dec 2024) signal an intent to lead with customer solutions and technology marketing; watch for product‑led service models and expanded aftersales offerings.
- King Chou Marine Technology (Kaohsiung, Taiwan) : Longstanding producer of purse seine and specialized aquaculture cage nets; strong custom‑engineering capabilities make them a natural partner for large aquaculture projects in Asia and beyond.
- Garware Technical Fibres (Pune, India) : A leader on high‑performance synthetic fibers (HDPE/PP/UHMWPE); their positioning bridges raw material innovation with finished-net solutions—an attractive counterparty for firms seeking integrated supply security.
- Miller Net Company & Memphis Net & Twine (Memphis, TN, USA) : U.S. players that concentrate on custom nets and commercial supplies; they are important conduits to North American fisheries and recreational segments, often differentiating on service speed and customization.
- AKVA group (Egersund, Norway) : Known for specialized aquaculture nets and mooring systems; their strength is systems integration—combining netting with farm architecture and deployment services.
- Badinotti Group (Milan, Italy) and Momoi Fishing Net (Japan) : Regional champions with deep product knowledge in purse seining and synthetic monofilament processing respectively—targets for regional consolidation or technology partnerships.
Recent sector moves provide directional signals: pilots of biodegradable PBS‑based nets in East Africa and Southern Africa (Jan 2025) and the launch of circular aquaculture nets made from regenerated nylon (mid‑2024) illustrate two simultaneous currents—regulation-led sustainability and circular materials commercialization. These are not peripheral experiments; they represent new procurement criteria that buyers and regulators will increasingly demand.
Regulation, materials, and margin: the three accelerators
Three interlocking forces will shape winners and losers through 2026 and beyond:
- Regulatory tightening on marine plastics —authorities and NGOs are accelerating requirements around lost gear and end‑of‑life management. Suppliers with documented biodegradability or proven recycling pathways will increasingly access premium contracts and public tenders.
- Material innovation —roughly a third of new nets in recent years incorporated HDPE or UHMWPE fibers, improving durability and reducing weight; parallel work on marine‑biodegradable polymers has produced materials that biodegrade rapidly while maintaining tensile strength. Buyers must balance upfront costs against longer useful life and lower retrieval costs.
- Value chain circularity —recycling discarded nets into new nylon avoids significant CO2 emissions and reduces environmental externalities; lifecycle analyses show meaningful social and cost benefits that can be monetized in ESG reporting and public procurement scoring.
Strategic recommendations for 2026 planning
For executives prioritizing near-term moves, PW Consulting recommends the following actions:
- Integrate material roadmaps into procurement tenders. Specify performance thresholds (e.g., abrasion resistance, UV stability, biodegradability metrics) rather than prescriptive material types to preserve competitive tension while driving innovation.
- Pursue staged supplier commitments. Adopt a three-tier contracting approach: a strategic core supplier for primary volumes, a development partner for new-material pilots, and a rapid-response regional supplier for emergency fill‑ins.
- Run experimental pilots for circular products in low-regret geographies. Use partner networks and grant funding to offset pilot costs and secure first‑mover advantage in regulated tenders.
- Stress-test balance sheets for raw‑material inflation. Hedging strategies for polymer inputs and back‑to‑back purchase agreements can protect margin while maintaining flexibility for material switching.
- Assess M&A targets not only for capacity but for capability—look for firms with unique R&D, recycling access, or regional distribution that can leapfrog time‑to‑market for sustainable nets.
Why PW Consulting’s report is decision‑useful for 2026
Many market reports stop at descriptive statistics. Ours is designed to be prescriptive: every chapter links macro forecasts to a set of executable decisions—contract terms, procurement KPIs, pilot design checklists, and acquisition thesis templates. We quantify risk and reward across alternative adoption timelines so business leaders can select strategies that align to their risk appetite and capital plans for 2026.
Importantly, the most sensitive datasets—the granular splits by region, application, and product subtype—are intentionally reserved for the full report. This “trailer” approach gives executives the strategic orientation needed for planning while preserving the proprietary, transaction‑ready detail behind the report paywall.
Next steps and how to use the brief
For teams preparing 2026 initiatives, immediate next steps include:
- Commission a 90‑day supplier due diligence using our supplier assessment template to validate capacity and material compliance.
- Run a 6‑month pilot of biodegradable or circular nets in a controlled operational environment; use our ROI model to capture full lifecycle costs and retrieval savings.
- Map M&A targets against the concentration and capability insights in the full report to identify 12–18 month acquisition candidates.
To access the full dataset, granular segmentation, and downloadable implementation tools referenced throughout this brief, please consult the Fish Nets Market report on PW Consulting’s research portal. The complete document contains detailed tables, regional and application breakdowns, supplier scorecards, and our proprietary financial models required for transaction execution.
Closing perspective
The fish nets market in 2026 is a market of disciplined growth and strategic inflection. Companies that translate material science advances and regulatory shifts into integrated commercial and sourcing strategies will capture disproportionate value. PW Consulting’s Fish Nets Market report equips leaders with the foresight, tools, and vendor intelligence to make those strategic moves with confidence—while preserving the granular, transaction-ready data that underpins high‑stakes decisions.
For detailed analysis of this topic, please visit the official page: Fish Nets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.45% CAGR for Global Fender Flare Trim Market Through 2032
By pmarketresearch, 2026-07-01
Fender Flare Trim Market 2026 Strategic Outlook — PW Consulting Preview
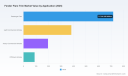
PW Consulting’s latest Fender Flare Trim Market report delivers a forward-looking, decision-ready framework tailored for executives, product leaders, procurement teams, and investors planning actions in 2026. Built on a 2020–2025 historical base with 2025 as the reference year and a 2026–2032 forecast horizon, the study contextualizes the market’s trajectory — growing from roughly USD 1,025 million in 2020 to about USD 1,386 million in 2025, and projected to reach approximately USD 2,010 million by 2032 at a compound annual growth rate (CAGR) of 5.45% over the forecast period. This brief synthesizes the strategic implications of those macro trends while preserving the granular segment intelligence for subscribers and advisory clients.
Fender Flare Trim Market
Why this report matters for 2026 planning
- Actionable timing: The market momentum captured in our forecast frames investment windows for capacity, product launches, and M&A. A sustained mid-single-digit CAGR signals steady expansion rather than a short-lived spike — favoring staged investments and capability-building over rapid, high-risk scale-ups.
- Channel differentiation: The interplay between OEM accessory programs and aftermarket customization is shifting supplier value propositions. Companies that can serve both channels with differentiated product and installation solutions will capture higher margins and reduce customer concentration risk.
- Material and regulatory exposure: Material selection (rubber compounds, engineered plastics, metal trims) and compliance requirements influence design cycles, supplier qualification, and cost volatility. Our report translates those technical constraints into procurement and product strategies for 2026.
Core market dynamics shaping 2026 decisions
Three structural forces will define competitive outcomes in the near term:
Fender Flare Trim Market
- Material evolution and supply-chain resilience: EPDM and other synthetic rubbers remain central to edge trims and sealing solutions. Global manufacturing footprint and robust supply chains for EPDM reduce some sourcing risk, but rising demand from automotive electrification and other end markets is tightening segments of the synthetic rubber value chain. Our modeling incorporates upstream market forecasts and stress-tests supplier scenarios to quantify exposure for manufacturers and integrators.
- Product diversification and premiumization: Demand for both low-profile OEM-style trims and high-margin premium stainless or molded solutions is increasing. This bifurcation creates product-tier opportunities: scalable standardized trims for high-volume platforms, and engineered premium trims for aftermarket and specialty vehicles. Strategic players will optimize product portfolios to capture both value and growth.
- Regulatory and performance requirements: Automotive component standards — including flammability and material performance specifications — materially affect design and supplier qualification. Compliance frameworks (e.g., relevant flammability requirements) must be embedded early in the design-to-sourcing process to avoid costly redesigns and market access delays.
Competitive landscape — what to watch
The Fender Flare Trim market exhibits a mix of niche specialists, OEM suppliers, and custom fabricators. Market concentration metrics indicate a competitive environment with room for consolidation: the top three players do not fully dominate the market, and the top five capture a little over half of industry revenues, leaving substantial share distributed across regional and specialty suppliers.
Fender Flare Trim Market
- Trim-Lok, Inc.: A prominent supplier of EPDM rubber and PVC peel-and-stick solutions, notable for catalog-driven product breadth and a recent series of catalog updates and product introductions. Their investments in design guides and metric/multilingual publications indicate a push to deepen global aftermarket and OEM support.
- Trimco: Focused on flexible plastic trims that prioritize conformability and adhesive technologies. Their product positioning emphasizes ozone resistance and curvature conformity — attributes valued across both retrofit and OE accessory channels.
- Johnson Bros. Roll Forming Co.: A custom manufacturer positioned to serve differentiated needs where bespoke profiles and roll-formed solutions are required, often serving niche OEM and specialty aftermarket programs.
- Bushwacker and Air Design: These brands bridge OE-style accessories and aftermarket offerings, with go-to-market advantages tied to vehicle fitment libraries and OEM accessory programs.
- Steel Rubber and Putco: Represent material- and finish-led differentiation — from ozone-resistant EPDM edge trims to premium stainless offerings — playing to durability and aesthetic premium segments.
Recent vendor moves illustrate competitive intent: Trim-Lok’s 2025 catalog refresh and product launches expand addressable use cases and signal a deeper push into both international and metric markets. Such updates matter for buyers evaluating partner roadmaps and for investors assessing execution capability beyond pure product engineering.
Report content — practical, deal-ready deliverables
PW Consulting’s full report is structured to support immediate decision-making across commercial, operational, and strategic functions. Key deliverables include:
- Market sizing and 2026–2032 forecasts by material type, application, and region — with scenario analysis for supply shocks and demand pivots.
- Competitive benchmarking: capability heatmaps, go-to-market profiles, and product-positioning matrices for the leading vendors and fast-growing challengers.
- Action templates: supplier scorecards, product roadmaps keyed to regulatory gates, cost-model templates, and an M&A screening matrix aligned to consolidation economics.
- Raw-material risk dashboard and mitigation playbook, incorporating upstream synthetic rubber market trends and supplier concentration metrics.
- Commercial playbooks for OEM account penetration, aftermarket channel expansion, and digital-direct strategies for end-consumer sales.
To preserve the report’s role as a strategic asset, we intentionally withhold detailed segment-level tables and proprietary company scores from this preview — clients can access the full set of granular models and tailored consulting options through PW Consulting’s subscription portal or advisory engagement.
Strategic imperatives for 2026
Based on our integrated market and competitive analysis, PW Consulting recommends the following prioritized actions for firms targeting outperformance in 2026:
- Lock in material supply and dual-source critical compounds: Secure EPDM and engineered-plastic contracts with flexible terms; qualify alternate suppliers and compounds to hedge against price and availability swings tied to broader synthetic rubber demand.
- Modularize product architecture: Design trim systems that allow common subcomponents across different trim families to lower NPI cost and shorten lead times for custom fitments.
- Prioritize channels based on margin and scale: Develop a two-track commercial strategy — a high-volume program for OEM accessories and a premium aftermarket lineup that leverages brand, finish, and installation ease to justify higher ASPs.
- Invest in adhesive and installation technology: Peel-and-stick and foam-tape solutions reduce installation labor and warranty risk; differentiation in adhesive systems and fitment accuracy translates directly into reduced return rates and higher channel acceptance.
- Target tactical M&A and partnerships: Use the market’s middle-ground concentration as an opportunity to acquire regional specialists or complementary capability (e.g., roll-forming, stainless finishing, fitment-engineering) to accelerate scale and margin improvement.
- Embed compliance and sustainability into product development: Anticipate regulatory requirements and evolving OEM sustainability targets by increasing recycled-content readiness and documenting lifecycle performance early in the development cycle.
How to use this preview and next steps
This article is designed as a strategic teaser — it demonstrates the PW Consulting team’s methodology and key takeaways while protecting the proprietary granular analytics that power transaction-level decisions. The full report contains the segment-level forecasts, regional and application splits, supplier scorecards, and downloadable financial models you’ll need to operationalize the recommendations above.
- For immediate advisory support: PW Consulting can run a tailored supplier risk assessment or M&A target screen using your priorities and balance-sheet constraints.
- For product teams: we offer an accelerated workshop to convert the report’s playbooks into a 90-day product launch and cost-reduction roadmap.
- To access the full market dataset and models: visit our research access page or contact our subscription services to obtain the report and supporting Excel models.
In a market that combines steady growth, material sensitivity, and heterogeneous competitive positions, clear, quantified strategy matters. PW Consulting’s Fender Flare Trim Market report equips leaders with the forecasting fidelity, competitive insight, and execution templates required to convert the market’s projected expansion into sustainable commercial advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Fender Flare Trim Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Elastic Sealing Gate Valve Market Poised to Expand at a 7.3% CAGR Through 2032
By pmarketresearch, 2026-07-01
Elastic Sealing Gate Valve Market — Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest market research on the Elastic Sealing (resilient seated) Gate Valve market synthesizes five years of historical performance with a seven‑year forward view to deliver the kind of actionable intelligence executives need in 2026. Built on a transparent methodology and validated through primary interviews with OEMs, EPC contractors, and procurement leads, the study shows a steady expansion in the global market — driven by infrastructure renewal, water management programmes, and performance upgrades in industrial systems. The market reached a meaningful scale by the 2025 base year and, under our central case, continues to grow at a compound annual growth rate (CAGR) of 7.3% through 2032.
Elastic Sealing Gate Valve Market
Executive snapshot: size, trajectory and concentration
From 2020 through the 2025 base year the market expanded substantially, reflecting accelerated replacement cycles and rising adoption of resilient seated designs in both municipal and industrial applications. In 2025 the market levelled at a notable industry milestone; our modelling then projects a steady climb to 2032 underpinned by upgrades to ageing water infrastructure, industrial cooling system investments, and stringent leakage-control specifications. The forecast path indicates sustained mid‑single‑digit to low‑high single‑digit growth, yielding a robust opportunity set for manufacturers, system integrators, and investors.
Elastic Sealing Gate Valve Market
Market structure matters: the competitive landscape displays a moderate level of concentration with the top three players accounting for a meaningful portion of sales and the top five commanding a clear majority of the organized market. That configuration produces both competitive pressure on global leaders and room for scale-driven consolidation among regional specialists.
Elastic Sealing Gate Valve Market
Why 2026 is an inflection window
-
Regulatory tightening and standards harmonization. Drinking-water and public works specifications across major markets continue to converge on strict leakage and material standards. Key technical frameworks — including AWWA standards for water supply service and relevant EN/BS standards in European markets — are increasingly enforced in procurement tenders, pushing buyers toward resilient seated designs that guarantee zero leakage and durability.
-
Materials and cost volatility. Elastomers used for resilient seating are a focal point of both performance and procurement risk. Our raw‑material monitoring shows regional price points that materially affect unit economics and supplier margin structures. Procurement teams who lock in elastomer supply or develop validated secondary sources reduce exposure to short‑term swings.
-
Infrastructure renewal and water management priorities. A combination of urbanization, climate stress on water resources, and renewed public investment is sustaining demand for valves that deliver reliability and low lifecycle leakage costs — creating long‑tail aftermarket and service revenue opportunities.
-
Supplier strategies: product evolution and sustainability. Advancements in elastomer technology, sealing geometries, and low‑emissions casting methods are differentiating new product introductions. The winners in 2026 will be those that pair technical proof points with scalable manufacturing footprints and verifiable sustainability credentials.
What the report delivers — practical, operational intelligence
This study is purpose‑built for executives who need to make high‑stakes decisions in 2026. Beyond high‑level forecasting, the full report contains the operational tools necessary to translate market trends into executable plans:
-
Demand model and sensitivity analysis — a transparent bottom‑up model that maps end‑market drivers to demand across forecast scenarios, with selectable sensitivity levers for raw‑material cost, CAPEX intensity in water infrastructure, and regulatory tightening.
-
Cost‑build and margin benchmarking — a production cost matrix that isolates the contribution of casting, machining, elastomer compounding, and testing/qualification to landed cost by production model.
-
Supply‑chain risk heat map — supplier concentration, critical input exposure (including elastomers), lead‑time dynamics, and mitigation pathways (local sourcing, buffer inventories, long‑term contracts).
-
Compliance and tender playbook — concise checklists and documentation templates aligned to AWWA C509/C515 and European potable‑water standards to accelerate qualification for municipal bids.
-
Go‑to‑market and channel strategies — differentiated plans for global OEMs, regional manufacturers, and distributors, including pricing strategies, aftermarket service offers, and digitalization roadmaps to extract recurring revenue.
-
M&A and partnership diagnostics — an acquisition screening matrix that highlights targets based on technology fit, regional access, and aftermarket penetration, with pro‑forma upside cases under conservative and aggressive integration assumptions.
-
Case studies and validation interviews — real project examples demonstrating how design choices and procurement terms influenced total lifecycle cost and operational risk.
Note: The report contains detailed segment and regional splits and granular unit economics that are essential to execution; these detailed tables and dashboards are reserved for the full report to protect sensitive market intelligence while allowing readers to validate and operationalize our findings.
Competitive landscape — profiles and strategic positions
The report’s competitive chapter synthesizes company profiles, technology differentiators, and strategic moves across the market. It examines established European specialists, scale manufacturers from Asia, and a variety of regional players that compete on cost, compliance, or engineering performance.
-
AVK Valves (Denmark) — Known for resilient seated gate valve series that meet key European standards, AVK’s strengths are design maturity, certification track record, and access to large municipal projects in developed markets. Their product compliance and specification depth make them a preferred supplier where standards adherence is non‑negotiable.
-
VAG GmbH (Germany) — A specialist in advanced sealing technologies for municipal water and industrial uses, VAG’s engineering‑led approach and reputation for quality position it to capture premium tenders and engineering‑specification wins.
-
EJ Industrial Group (China) — A high‑volume manufacturer offering ductile iron resilient seat designs and a dual offering of metal‑to‑metal and resilient seats. EJ’s scale advantages underpin competitive pricing and fast fulfillment for large infrastructure projects.
-
Union Valve (China) — Focused on cast and ductile iron models including non‑rising stem variants, Union plays strongly in distribution networks and export shipments for international water projects, and its recent project shipments underscore global execution capability.
-
Dervos Valve (China) — Differentiates on zero‑leakage performance in elastic‑seat designs; their focus on sealing reliability makes them a logical partner for operators prioritizing long lifecycle performance.
-
Weidouli Valves (China) — Offers a portfolio with EPDM and PTFE seating options suited to higher‑pressure systems; their material flexibility caters to industrial and high‑pressure municipal applications.
-
BELGICAST (Spain) — A regional specialist providing high‑performance resilient seated valves for infrastructure projects, with an emphasis on engineering and project support for complex tenders.
Recent industry developments — such as updated product analyses highlighting improved elastomer formulations and sustainability features, and documented shipments of non‑rising stem valves for international deployments — confirm that both product evolution and global execution are accelerating across segments.
Strategic imperatives for 2026
-
Prioritize standards‑first product roadmaps. Ensure product portfolios are pre‑qualified to the most demanding standards in target markets to avoid tender disqualification and capture margin premia.
-
Lock in elastomer supply and diversify sourcing. Given elastomer price and availability sensitivity, secure multi‑year contracts and validated secondary suppliers to protect margins.
-
Invest in certification and test capability. Speed to qualification often determines procurement outcomes in municipal tenders — local test labs and recognized certifications shorten sales cycles.
-
Pursue aftermarket and service revenue. Extended performance warranties, predictive maintenance programs, and digital monitoring create durable high‑margin revenue streams.
-
Consider targeted consolidation. With a moderate degree of market concentration, opportunistic M&A can rapidly expand footprint, consolidate aftermarket channels, and create scale in procurement.
-
Embed sustainability into supply chains. Low‑emission casting processes and demonstrable material recycling will increasingly factor into public procurement.
-
Operationalize scenario planning. Use the report’s sensitivity matrices to stress‑test business cases against raw‑material shocks, CAPEX funding cycles, and regulatory shifts.
Investor and board implications
For investors and corporate boards, the market presents a classic combination: predictable, infrastructure‑driven demand with product complexity that rewards engineering and brand trust. Companies that control critical supply inputs, boast robust compliance documentation, and can deliver lifecycle service will secure higher margins and more defensible positions. The market’s structure favors platform strategies that combine in‑region manufacturing with centralized R&D and standardized product platforms.
Closing and how to act
PW Consulting’s Elastic Sealing Gate Valve report is designed to convert market knowledge into boardroom decisions in 2026: from capex allocation and M&A screening to product roadmaps and procurement strategy. The full report includes the granular segment tables, regional demand dashboards, and company performance benchmarks necessary to operationalize the recommendations summarized here.
To access the complete dataset, interactive models, and executable playbooks referenced in this briefing, please consult the PW Consulting report page where the full study and supporting materials are available.
For detailed analysis of this topic, please visit the official page: Elastic Sealing Gate Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Millimeter-Wave Radar for Unmanned Driving to Surge at 19.7% CAGR — Market Climbs from USD 16.43B in 2025 to USD 48.73B by 2032, Led by 77 GHz and Adaptive Cruise Control
By pmarketresearch, 2026-07-01
Millimeter Wave Radar for Unmanned Driving: Strategic Imperatives for 2026 — PW Consulting Market Preview
Executive summary
The millimeter wave (mmWave) radar market for unmanned driving is transitioning from niche capability to core vehicle perception layer. Our latest PW Consulting market model — based on a 2025 base year and a historical window spanning 2020–2025 with forecasts through 2026–2032 — shows sustained, high‑double‑digit expansion. Total market value rose from approximately USD 4.21 billion (2020) to about USD 16.43 billion (2025), and is projected to exceed USD 18.7 billion in 2026. The modeled compound annual growth rate (CAGR) for the forecast period is 19.7%, reflecting accelerating adoption driven by regulatory mandates, OEM automation programs, and rapid improvements in perception performance.
Millimeter Wave Radar For Unmanned Driving Market
This preview outlines the strategic value of the full PW Consulting Millimeter Wave Radar For Unmanned Driving Market report for corporate decision‑makers in 2026. It highlights the competitive dynamics, supply‑chain and regulatory headwinds, and practical playbooks that will influence supplier selection, R&D allocation, manufacturing investments, and M&A activity over the next 18–36 months. We deliberately present high‑level conclusions here while reserving detailed subsegment and regional breakdowns for the full report to preserve the commercial edge our clients rely on.
Millimeter Wave Radar For Unmanned Driving Market
Why this matters to decision‑makers in 2026
- Tactical procurement and capacity planning: With market expansion forecast at nearly 20% CAGR, OEMs and Tier‑1 suppliers must convert strategic roadmaps into binding supply agreements and capacity commitments now to avoid multi‑quarter lead times when program ramping intensifies.
- Technology differentiation is consolidating: 4D imaging, digital radar‑on‑chip architectures, and embedded AI signal processing are no longer lab novelties — they are procurement criteria. Firms that can demonstrate higher resolution, robust false‑alarm rejection and software‑native upgrades will command premium positioning.
- Regulatory and spectrum uncertainty: Global safety mandates are increasing baseline feature adoption, while spectrum allocation delays and regional harmonization gaps create deployment timing risks that must be factored into program schedules and market entry sequencing.
- Supply‑chain fragility: Semiconductor supply disruptions and shortages in RF‑grade materials persist, amplifying the need for diversified sourcing, long‑lead procurement, and strategic partnerships with foundries and MMIC suppliers.
What the PW Consulting report delivers (practical content you can act on)
- Proprietary market sizing and 2026–2032 forecasts, anchored to our 2025 base year and historical 2020–2025 dataset, with scenario analyses to quantify upside and downside cases under different regulatory and supply assumptions.
- Competitive intelligence dossiers for leading incumbents, scale challengers and specialist chipset vendors, including technology roadmaps, recent contracts and production milestones.
- Go‑to‑market playbooks for OEMs, Tier‑1 suppliers and semiconductor vendors — covering pricing strategy, product tiering, and partner ecosystems for perception stacks in unmanned driving.
- Risk assessments and mitigation blueprints for semiconductor dependency, raw material constraints and labor skill gaps — plus practical sourcing checklists and contract templates.
- Regulatory scenario modeling for spectrum allocation and safety mandates, with decision trees that map regulation outcomes to product certification timelines and commercialization windows.
- Investment and M&A screening matrices that prioritize targets by technology moat, production readiness and commercial traction, plus unit‑economics sensitivity models tailored to client cost structures.
To preserve the strategic value of those deliverables, we withhold full subsegment and regional breakdowns in this public summary. The full dataset and interactive models are available via the report portal.
Millimeter Wave Radar For Unmanned Driving Market
Competitive landscape: leaders, challengers and disruptive entrants
The market displays a mix of entrenched automotive suppliers and specialized semiconductor and radar startups. Market concentration is meaningful but not prohibitive — the top three suppliers account for approximately 48.5% of market revenue, while the top five capture about 62.8%. This structure creates room for both scale players to defend margins and for focused innovators to win design slots through superior technology or cost advantages.
- Robert Bosch GmbH (Gerlingen, Germany): Bosch continues to invest in radar SoCs with integrated AI processing targeting SAE Level 2+ and unmanned applications. Recent introductions of advanced 22nm mmWave SoCs strengthen its ability to offer vertically integrated sensor modules and software, making Bosch a default partner for OEMs seeking one‑stop sensor solutions.
- Continental AG (Hanover, Germany): Continental’s achievement of substantial production milestones and new high‑value orders for its 6th‑generation mmWave sensors signals large‑scale industrialization. Their production capacity and program wins make them a high‑confidence supplier for long‑lead unmanned programs starting 2026–2027.
- Denso, Valeo, HELLA, Aptiv, ZF: These Tier‑1s bring complementary strengths — from long‑range detection expertise to systems integration across vehicle domains. Expect a mix of in‑house development, co‑development and supply relationships with semiconductor partners.
- Specialists and chip innovators (Arbe Robotics, Uhnder, Texas Instruments, Infineon): Startups and chip vendors are pushing the envelope on 4D imaging, digital radar‑on‑chip, and MMIC integration. Their offerings are attractive for OEMs that prioritize perception fidelity and software upgradability, but commercialization risk and production scale remain differentiators.
Recent developments underline two linked dynamics: consolidation of production scale among incumbents and accelerated productization of advanced radar chips. Continental’s multi‑hundred‑million unit production milestone and Bosch’s SoC launches exemplify how scale and silicon capability are becoming essential competitive levers. Simultaneously, demonstrations of automotive‑grade 4D imaging at key industry shows spotlight an emergent performance tier that could reshape value capture.
Industry headwinds and structural risks
- Regulatory drivers and friction: Governments are mandating safety features that increase baseline mmWave radar penetration, yet inconsistent spectrum allocation and regional harmonization delays can slow rollouts or drive fragmented product variants.
- Semiconductor and raw material constraints: The global RF semiconductor supply chain remains a bottleneck; program planners should assume volatile lead times and price pressure unless bilateral wafer commitments or foundry partnerships are secured.
- Workforce and operational costs: Skilled RF and metrology talent shortages elevate manufacturing OPEX and lengthen qualification cycles for new production lines — an underappreciated friction point for rapid scale‑up.
Strategic recommendations for 2026
- Lock strategic wafer and chip capacity now: Given the projected near‑term ramp, secure capacity with prioritized allocation clauses and contingency capacity to protect program timelines.
- Differentiate by perception stack integration: Combine mmWave radar capabilities with sensor fusion and over‑the‑air software update pathways to create stickier OEM relationships and recurring revenue.
- Adopt a tiered supplier strategy: Pair scale incumbents for volume supply with specialist vendors for premium feature sets. Use dual‑sourcing where possible to hedge delivery risk.
- Pursue co‑development and IP partnerships: Consider joint technology development with chipset innovators to accelerate integration and de‑risk qualification timelines while preserving margin expansion.
- Engage regulators on spectrum harmonization: Participate in industry consortia and public consultation to influence timelines and reduce fragmentation risk in primary target markets.
- Invest in workforce and automation: Scale automated test and calibration systems and invest in RF engineering talent pipelines to shorten time‑to‑volume and improve yields.
- Use M&A tactically: Target high‑value technology houses and proven system integrators to fill capability gaps quickly rather than building in‑house at higher cost and delay.
Scenario planning and KPIs to monitor
We recommend three principal scenarios for 2026 planning: base case (steady adoption at modeled CAGR), constrained supply case (short‑term semiconductor shocks and spectrum delays), and accelerated adoption case (faster regulatory mandates and emergency braking requirements). For each scenario, prioritize monitoring these KPIs:
- Order book and signed program wins (quarterly visibility)
- Lead times and wafer allocations from key foundries
- Production yields and calibration throughput per line
- Certification and spectrum clearance timelines per market
- Price trend of RF‑grade components and passives
Conclusion and next steps
The mmWave radar market for unmanned driving presents both a substantial growth opportunity and a complex operational environment. PW Consulting’s full market report translates the headline numbers and industry dynamics into executable choices: which suppliers to partner with, where to invest in silicon vs. systems, how to de‑risk supply chains and what M&A targets deliver the fastest time‑to‑value. For decision‑makers setting 2026 budgets and program commitments, the difference between a winning and a delayed program will be decided by the quality of supply agreements, the sharpness of technical differentiation and the ability to anticipate regulatory timing.
PW Consulting clients receive the complete forecast dataset, interactive scenario tools and vendor due‑diligence packages. To review the full analysis, detailed segmentation, regional strategies and downloadable models, visit the PW Consulting report page or contact our industry advisory team to schedule a briefing tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Millimeter Wave Radar For Unmanned Driving Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com