

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Millimeter-Wave Radar for Unmanned Driving to Surge at 19.7% CAGR — Market Climbs from USD 16.43B in 2025 to USD 48.73B by 2032, Led by 77 GHz and Adaptive Cruise Control

Millimeter Wave Radar for Unmanned Driving: Strategic Imperatives for 2026 — PW Consulting Market Preview
Executive summary
The millimeter wave (mmWave) radar market for unmanned driving is transitioning from niche capability to core vehicle perception layer. Our latest PW Consulting market model — based on a 2025 base year and a historical window spanning 2020–2025 with forecasts through 2026–2032 — shows sustained, high‑double‑digit expansion. Total market value rose from approximately USD 4.21 billion (2020) to about USD 16.43 billion (2025), and is projected to exceed USD 18.7 billion in 2026. The modeled compound annual growth rate (CAGR) for the forecast period is 19.7%, reflecting accelerating adoption driven by regulatory mandates, OEM automation programs, and rapid improvements in perception performance.
Millimeter Wave Radar For Unmanned Driving Market
This preview outlines the strategic value of the full PW Consulting Millimeter Wave Radar For Unmanned Driving Market report for corporate decision‑makers in 2026. It highlights the competitive dynamics, supply‑chain and regulatory headwinds, and practical playbooks that will influence supplier selection, R&D allocation, manufacturing investments, and M&A activity over the next 18–36 months. We deliberately present high‑level conclusions here while reserving detailed subsegment and regional breakdowns for the full report to preserve the commercial edge our clients rely on.
Millimeter Wave Radar For Unmanned Driving Market
Why this matters to decision‑makers in 2026
- Tactical procurement and capacity planning: With market expansion forecast at nearly 20% CAGR, OEMs and Tier‑1 suppliers must convert strategic roadmaps into binding supply agreements and capacity commitments now to avoid multi‑quarter lead times when program ramping intensifies.
- Technology differentiation is consolidating: 4D imaging, digital radar‑on‑chip architectures, and embedded AI signal processing are no longer lab novelties — they are procurement criteria. Firms that can demonstrate higher resolution, robust false‑alarm rejection and software‑native upgrades will command premium positioning.
- Regulatory and spectrum uncertainty: Global safety mandates are increasing baseline feature adoption, while spectrum allocation delays and regional harmonization gaps create deployment timing risks that must be factored into program schedules and market entry sequencing.
- Supply‑chain fragility: Semiconductor supply disruptions and shortages in RF‑grade materials persist, amplifying the need for diversified sourcing, long‑lead procurement, and strategic partnerships with foundries and MMIC suppliers.
What the PW Consulting report delivers (practical content you can act on)
- Proprietary market sizing and 2026–2032 forecasts, anchored to our 2025 base year and historical 2020–2025 dataset, with scenario analyses to quantify upside and downside cases under different regulatory and supply assumptions.
- Competitive intelligence dossiers for leading incumbents, scale challengers and specialist chipset vendors, including technology roadmaps, recent contracts and production milestones.
- Go‑to‑market playbooks for OEMs, Tier‑1 suppliers and semiconductor vendors — covering pricing strategy, product tiering, and partner ecosystems for perception stacks in unmanned driving.
- Risk assessments and mitigation blueprints for semiconductor dependency, raw material constraints and labor skill gaps — plus practical sourcing checklists and contract templates.
- Regulatory scenario modeling for spectrum allocation and safety mandates, with decision trees that map regulation outcomes to product certification timelines and commercialization windows.
- Investment and M&A screening matrices that prioritize targets by technology moat, production readiness and commercial traction, plus unit‑economics sensitivity models tailored to client cost structures.
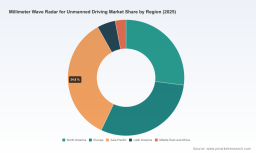
To preserve the strategic value of those deliverables, we withhold full subsegment and regional breakdowns in this public summary. The full dataset and interactive models are available via the report portal.
Millimeter Wave Radar For Unmanned Driving Market
Competitive landscape: leaders, challengers and disruptive entrants
The market displays a mix of entrenched automotive suppliers and specialized semiconductor and radar startups. Market concentration is meaningful but not prohibitive — the top three suppliers account for approximately 48.5% of market revenue, while the top five capture about 62.8%. This structure creates room for both scale players to defend margins and for focused innovators to win design slots through superior technology or cost advantages.
- Robert Bosch GmbH (Gerlingen, Germany): Bosch continues to invest in radar SoCs with integrated AI processing targeting SAE Level 2+ and unmanned applications. Recent introductions of advanced 22nm mmWave SoCs strengthen its ability to offer vertically integrated sensor modules and software, making Bosch a default partner for OEMs seeking one‑stop sensor solutions.
- Continental AG (Hanover, Germany): Continental’s achievement of substantial production milestones and new high‑value orders for its 6th‑generation mmWave sensors signals large‑scale industrialization. Their production capacity and program wins make them a high‑confidence supplier for long‑lead unmanned programs starting 2026–2027.
- Denso, Valeo, HELLA, Aptiv, ZF: These Tier‑1s bring complementary strengths — from long‑range detection expertise to systems integration across vehicle domains. Expect a mix of in‑house development, co‑development and supply relationships with semiconductor partners.
- Specialists and chip innovators (Arbe Robotics, Uhnder, Texas Instruments, Infineon): Startups and chip vendors are pushing the envelope on 4D imaging, digital radar‑on‑chip, and MMIC integration. Their offerings are attractive for OEMs that prioritize perception fidelity and software upgradability, but commercialization risk and production scale remain differentiators.
Recent developments underline two linked dynamics: consolidation of production scale among incumbents and accelerated productization of advanced radar chips. Continental’s multi‑hundred‑million unit production milestone and Bosch’s SoC launches exemplify how scale and silicon capability are becoming essential competitive levers. Simultaneously, demonstrations of automotive‑grade 4D imaging at key industry shows spotlight an emergent performance tier that could reshape value capture.
Industry headwinds and structural risks
- Regulatory drivers and friction: Governments are mandating safety features that increase baseline mmWave radar penetration, yet inconsistent spectrum allocation and regional harmonization delays can slow rollouts or drive fragmented product variants.
- Semiconductor and raw material constraints: The global RF semiconductor supply chain remains a bottleneck; program planners should assume volatile lead times and price pressure unless bilateral wafer commitments or foundry partnerships are secured.
- Workforce and operational costs: Skilled RF and metrology talent shortages elevate manufacturing OPEX and lengthen qualification cycles for new production lines — an underappreciated friction point for rapid scale‑up.
Strategic recommendations for 2026
- Lock strategic wafer and chip capacity now: Given the projected near‑term ramp, secure capacity with prioritized allocation clauses and contingency capacity to protect program timelines.
- Differentiate by perception stack integration: Combine mmWave radar capabilities with sensor fusion and over‑the‑air software update pathways to create stickier OEM relationships and recurring revenue.
- Adopt a tiered supplier strategy: Pair scale incumbents for volume supply with specialist vendors for premium feature sets. Use dual‑sourcing where possible to hedge delivery risk.
- Pursue co‑development and IP partnerships: Consider joint technology development with chipset innovators to accelerate integration and de‑risk qualification timelines while preserving margin expansion.
- Engage regulators on spectrum harmonization: Participate in industry consortia and public consultation to influence timelines and reduce fragmentation risk in primary target markets.
- Invest in workforce and automation: Scale automated test and calibration systems and invest in RF engineering talent pipelines to shorten time‑to‑volume and improve yields.
- Use M&A tactically: Target high‑value technology houses and proven system integrators to fill capability gaps quickly rather than building in‑house at higher cost and delay.
Scenario planning and KPIs to monitor
We recommend three principal scenarios for 2026 planning: base case (steady adoption at modeled CAGR), constrained supply case (short‑term semiconductor shocks and spectrum delays), and accelerated adoption case (faster regulatory mandates and emergency braking requirements). For each scenario, prioritize monitoring these KPIs:
- Order book and signed program wins (quarterly visibility)
- Lead times and wafer allocations from key foundries
- Production yields and calibration throughput per line
- Certification and spectrum clearance timelines per market
- Price trend of RF‑grade components and passives
Conclusion and next steps
The mmWave radar market for unmanned driving presents both a substantial growth opportunity and a complex operational environment. PW Consulting’s full market report translates the headline numbers and industry dynamics into executable choices: which suppliers to partner with, where to invest in silicon vs. systems, how to de‑risk supply chains and what M&A targets deliver the fastest time‑to‑value. For decision‑makers setting 2026 budgets and program commitments, the difference between a winning and a delayed program will be decided by the quality of supply agreements, the sharpness of technical differentiation and the ability to anticipate regulatory timing.
PW Consulting clients receive the complete forecast dataset, interactive scenario tools and vendor due‑diligence packages. To review the full analysis, detailed segmentation, regional strategies and downloadable models, visit the PW Consulting report page or contact our industry advisory team to schedule a briefing tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Millimeter Wave Radar For Unmanned Driving Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com