

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: E-Beam Accelerators Market to Grow at 4.15% CAGR, Reaching USD 270 Million by 2032

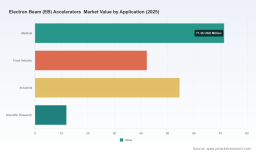
E‑Beam Accelerators Market: Strategic Insights to Guide Corporate Decisions in 2026
PW Consulting is pleased to publish a focused industry briefing drawn from our new E‑Beam Accelerators Market report (base year: 2025). Designed for C‑suite leaders, corporate development teams, and industrial technology investors, this briefing translates market dynamics, competitive positioning, and practical adoption roadmaps into decisive actions for 2026. The global market for electron beam (E‑beam) accelerators has demonstrated steady expansion—from the mid‑double digits in 2020 to USD 180 Million in 2025—and is forecast to continue growing through 2032 at a compound annual growth rate of 4.15%. By 2032 the market is projected to reach roughly USD 270 Million. These macro trajectories provide the context for the strategic choices that follow.
E Beam Accelerators Market
Why this report matters for 2026 decisions
-
Timing and scale: The market has moved from early‑adopter investments toward broader industrial adoption. The modest but consistent growth profile signals that 2026 is a pivotal year to shift from exploratory pilots to operational scaling for the right use cases.
E Beam Accelerators Market -
Risk‑reward clarity: Our analysis isolates the commercial and regulatory variables that most materially affect near‑term returns—enabling executive teams to prioritize capital deployment with clearer downside protection.
E Beam Accelerators Market -
Competitive intelligence: The report synthesizes vendor capabilities, recent commercial developments, and service models so buyers and potential partners can match supplier profiles to their own operating requirements.
What the PW Consulting report delivers (practical, executable content)
-
Concise market sizing and trend maps covering 2020–2025 historical data and 2026–2032 forecasts—presented with scenario paths and sensitivity analyses that isolate demand drivers and policy risk.
-
Decision frameworks for purchasers and investors—covering build vs. buy, financing and lifecycle cost models (CapEx vs. OpEx), and service contract negotiation checklists tailored to E‑beam equipment.
-
Go‑to‑market and commercialization playbooks for equipment OEMs and service providers—addressing channel design, irradiation center economics, and retrofit strategies for incumbent industrial installations.
-
Regulatory and standards mapping—identifying certification timelines, inspection regimes, and market access contingencies that materially influence procurement schedules.
-
Use‑case deep dives—with practical ROI models for high‑impact applications such as sterilization, polymer modification, and niche environmental treatments—presented without revealing proprietary segmentation detail, to protect competitive insights while enabling action.
-
M&A and partnership screening criteria—highlighting the profile of attractive targets and the likely post‑deal value capture levers (service integration, geographic reach, and technologies enabling higher throughput).
Market structure and competitive dynamics — what to watch in 2026
The E‑beam accelerator market sits in a middle‑concentration regime: a handful of established OEMs and specialized system integrators own a meaningful share of installed capacity and service revenue, yet there remains room for regional challengers and technology specialists to grow. PW Consulting measures concentration metrics that confirm a competitive landscape where the top three players account for a plurality, while the top five approach two‑thirds of market value—creating both stability and pockets of competitive opportunity.
Key player archetypes emerge from our company profiling:
-
Integrated systems OEMs with global service networks: Firms offering end‑to‑end solutions and integrated maintenance services tend to capture higher life‑time value from sterilization and industrial clients. Their strength is predictable uptime and bundled contracting.
-
Regional manufacturing leaders and irradiation center operators: These players combine localized manufacturing with irradiator operations, which helps lower logistics cost and accelerate time‑to‑market for applications such as polymer cross‑linking.
-
Specialist low‑voltage solution providers: Companies that lead in low‑voltage EB systems enjoy a competitive edge in thin‑film and flexible packaging sectors where compact footprints and low operating complexity matter.
-
Custom systems and integration houses: Smaller, highly technical firms focus on bespoke builds for wire, cable, and advanced materials—winning business where standard platforms cannot meet unique production lines.
Representative company developments in early 2025–2026 underscore the strategic thrusts shaping vendor competition. Examples include a Japan‑based systems supplier moving to commercialize a real‑time EPS monitoring solution through a production line contract with a tyre manufacturer, and a Chinese accelerator designer delivering its first EU unit—each signaling shifts in service offerings and geographic expansion. A European supplier’s multi‑accelerator deployment for industrial irradiation speaks to growing demand for higher‑throughput applications. These and other trade‑show activities reflect both product innovation and intensifying commercial engagement with key industries.
Strategic implications for buyers, investors, and OEMs
-
Buyers — prioritize operational resilience and service economics: For manufacturing and sterilization customers, procurement decisions should be driven as much by the service and monitoring propositions as by headline equipment specifications. Contracts that include predictive maintenance, spare‑parts pipelines, and uptime guarantees materially shorten payback windows.
-
Investors — seek compound optionality: Given the market’s steady growth profile, investment cases that combine equipment sales with recurring service or irradiation center revenues present more attractive risk‑adjusted returns than pure hardware bets. Early‑mover positions in service platforms (digital monitoring, remote diagnostics) can create durable differentiation.
-
OEMs — scale through modularity and partnerships: For manufacturers, pursuing modular designs and certified integration partners accelerates deployment into regulated end markets. Expanding channel service footprints or partnering with regional irradiation operators reduces adoption friction and supports premium pricing.
Operational playbook: five tactical moves for 2026
-
Lock in service capabilities now — secure service contracts, regional technicians, and spare‑parts logistics before demand accelerates; service continuity will be a primary competitive battleground.
-
Pilot monitoring and retrofit programs — deploy digital monitoring pilots (e.g., EPS monitoring systems) on strategic lines to validate uptime improvements and justify broader rollouts.
-
Mitigate supplier concentration risk — diversify sourcing for critical modules and consider dual‑supplier strategies for key components to reduce lead‑time exposure.
-
Negotiate outcome‑based contracts — where possible, structure deals around throughput, availability, or sterilization yield to align supplier incentives with operational outcomes.
-
Build a regulatory playbook — map certification requirements across target geographies and integrate clearance timelines into procurement and deployment schedules.
Scenario planning and financial sensitivity
PW Consulting’s forecast envelope presents baseline, upside, and downside scenarios for 2026–2032 that hinge on four variables: regulatory clarity, capex cycles in medical and food sectors, speed of technology adoption (digital monitoring and higher‑energy systems), and macro‑supply chain stability. Our baseline—reflecting current policy and investment momentum—assumes continued steady growth at approximately 4.15% CAGR over the forecast period. Clients receive downloadable financial models in the full report to test investment outcomes under alternative assumptions (e.g., faster sterilization adoption, constrained supply lines, or accelerated regulatory approvals).
M&A and partnership opportunities
Given the current market structure, attractive targets include regional integrators with established irradiation centers, specialist OEMs with proven niche technologies, and service platform providers enabling remote monitoring and predictive maintenance. Buyers should prioritize targets that can deliver immediate recurring revenue uplift, accelerate geographic entry, or provide complementary technology stacks that reduce time‑to‑market for larger industrial customers.
What we recommend next
-
For strategic buyers: run a focused due‑diligence sprint on service economics and installed‑base attrition risk, using the report’s buy vs. build frameworks to stress‑test acquisition scenarios.
-
For OEMs: accelerate development of monitoring and service packages; pilot with anchor customers to create reference cases that lower sales friction.
-
For investors: prioritize deals that combine hardware with recurring services or irradiation center models to capture higher life‑time value.
-
For procurement and operations leaders: integrate regulatory timelines and spare‑parts availability into 2026 capital plans; prioritize suppliers showing demonstrable service capacity and local support.
How PW Consulting’s report supports implementation
The full E‑Beam Accelerators Market report provides the empirical foundation and execution tools to convert strategic intent into operational plans. It includes: detailed historical data (2020–2025), baseline and scenario forecasts (2026–2032), vendor scorecards, a procurement negotiation playbook, and downloadable financial models. To preserve competitive value for subscribing clients, the report presents full segmentation tables and application‑level breakdowns behind secure access—ensuring that decision‑makers can drill into the specific regional, type, and application splits they need to act upon.
Closing — why act in 2026
2026 represents an inflection year in the E‑beam market where steady macro growth combines with accelerating service innovation and wider industrial acceptance. Companies able to couple disciplined procurement with service‑oriented commercial models will capture outsized value as the market matures. PW Consulting’s report translates data and field intelligence into the practical steps organizations need to take now to convert market momentum into sustainable competitive advantage.
For access to the full dataset, segmentation tables, and vendor scorecards to inform deal execution and procurement decisions, visit the PW Consulting research portal to download the complete E‑Beam Accelerators Market report and supporting tools.
For detailed analysis of this topic, please visit the official page: E Beam Accelerators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com