

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insight: Front-Loaded Industrial Parts Washer Market to Rise from USD 223.45 Million in 2025 to USD 292.4 Million by 2032 at a 3.85% CAGR

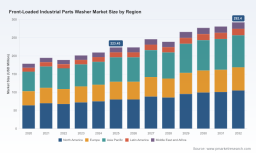
Front Loaded Industrial Parts Washer Market 2026: Strategic Imperatives for Operational Leaders
As manufacturers recalibrate capital plans and sustainability roadmaps for 2026, PW Consulting’s new Front Loaded Industrial Parts Washer Market report delivers the focused market intelligence executives need to prioritize investment, procurement, and product development decisions. Drawing on a rigorous base year of 2025 and a forecast through 2032, the study synthesizes trend signals across technology, regulation, costs, and competitive moves to reveal where front-loaded parts washing will create operational leverage — and where it will merely protect the status quo.
Front Loaded Industrial Parts Washer Market
Market snapshot: a stable base with steady, targeted growth
Our analysis shows the front loaded industrial parts washer market reached approximately USD 223.45 Million in 2025. From this base, the market is expected to expand at a compound annual growth rate (CAGR) of 3.85% over the 2026–2032 forecast window, reflecting measured growth driven by replacement cycles, incremental automation adoption, and regulatory pressures that favor aqueous systems. By 2032 our model projects a market trajectory consistent with these forces, underscoring the importance of timing for procurement and product rollouts.
Front Loaded Industrial Parts Washer Market
Why 2026 is a pivot year for corporate decision-makers
- Capital allocation clarity: With modest but persistent growth, 2026 is less about chasing volume peaks and more about allocating capital to solutions that reduce lifecycle costs (energy, maintenance, regulatory compliance). Firms that prioritize durability, serviceability, and energy efficiency will capture outsized ROI over a 5–10 year horizon.
- Regulatory-driven product selection: The shift to aqueous cleaners is not merely environmental virtue signaling — it’s a pragmatic response to evolving hazardous waste regulations. Purchasing teams must weigh the avoided costs and operational simplicity of aqueous front-load systems against the legacy strengths of solvent approaches.
- Consolidation and partnerships: Market concentration metrics reveal a landscape where the top three players account for roughly one third of market revenue, and the top five approach half. That structure creates opportunities for mid-sized suppliers to differentiate through service models, customization, and channel partnerships.
Operational levers that matter for 2026
- Lifecycle cost modeling: Stainless steel construction commands higher upfront spend but offers lower maintenance and longer service lives — a critical consideration for plants planning 10–20 year equipment horizons.
- Energy and thermal efficiency: Modern front-load aqueous washers incorporate insulated chambers and more efficient heating systems capable of operating up to 200°F. Energy optimization will be a decisive factor in total cost of ownership calculations, especially for high-cycle environments.
- Modularity and serviceability: Select systems provide configuration flexibility (turntables, conveyors, immersion, ultrasonic options) that reduce customization lead times and spare-parts inventories.
- Compliance and waste management: Eliminating solvent waste simplifies compliance and can lower disposal costs; procurement teams should explicitly quantify these savings in payback models.
Competitive landscape: profiles, positioning, and near-term moves
The competitive field blends legacy machine builders, specialist fabricators, and service-oriented providers. Below we synthesize the strategic positioning and recent activity of core firms featured in our report — a practical snapshot to inform vendor selection and partnership scouting.
Front Loaded Industrial Parts Washer Market
- Alliance Manufacturing, Inc. (Fond du Lac, WI) — https://www.alliancemfginc.com/
Alliance brings a broad portfolio of front/top-loading aqueous cabinets complemented by custom conveyor and rotary systems. Its presence at major trade events (scheduled exhibitions at WIMTS 2025 and IMTS 2026) signals an aggressive outreach strategy focused on OEM and heavy-industry channels. For buyers, Alliance is a candidate where configurability and demonstrated machine throughput matter.
- Better Engineering Manufacturing, Inc. (Joppa, MD) — https://www.betterengineering.com/
Better Engineering emphasizes custom solutions — turntables, conveyors, immersion and ultrasonic systems — targeting precision cleaning and high-volume manufacturing. Their strength lies in tailored engineering services and hybrid system designs that can integrate into existing lines with minimal disruption.
- Renegade Parts Washers / Service Line, Inc. (Reedsburg, WI) — https://renegadepartswashers.com/
Renegade’s I-Series and FL Series machines focus on high-load, heavy-duty cleaning. A recent website refresh in January 2026 highlights product documentation and support resources, an indicator of a company investing in buyer enablement and aftermarket service visibility.
- Cuda Cleaning Systems (Watertown, SD) — https://cudausa.com/
Cuda’s product family of front-load automatic aqueous washers targets solvent-free cleaning in the automotive and industrial maintenance sectors. Their model strategy emphasizes standardized offerings for broad OEM and aftermarket penetration, appealing to buyers who value quick procurement and repeatable performance.
- Safety-Kleen (Plano, TX) — https://www.safety-kleen.com/
Safety-Kleen leverages a service- and safety-first positioning, offering front-loading automatic spray washers with turntable systems and an emphasis on automation and compliance features. Their channel model tends to favor integrated service contracts and environmental risk mitigation.
- Graymills Corporation (Chicago, IL) — https://www.graymills.com/
Graymills builds premium front-load spray wash cabinets designed for high-pressure aqueous cleaning. The firm’s reputation centers on robust industrial specs and high-performance cleaning cycles suitable for demanding shop-floor environments.
- Alkota Cleaning Systems (Alcester, SD) — https://alkota.com/
Alkota offers front-load washers for small- to medium-sized parts, targeting maintenance shops and light manufacturing. Their value proposition is straightforward — cost-effective, compact solutions with reliable service networks.
- Niagara Systems LLC (Mentor, OH) — https://niagarasystemsllc.com/
Niagara emphasizes custom cabinets and front-load configurations, positioning itself as a flexible engineering partner for unique cleaning challenges where standard off-the-shelf units fall short.
Recent vendor activity: what it signals
- Trade show investments by established players indicate continued emphasis on OEM channels and on-floor demonstrations — a reminder that tactile evaluation remains important for higher-ticket equipment.
- Digital refreshes and expanded online support resources reflect a broader industry move to reduce buyer friction and accelerate post-sale service engagement.
Market dynamics and risk factors
Three structural dynamics should guide 2026 decision-making:
- Regulatory tailwinds: Facilities shifting from solvent to aqueous washers reduce hazardous waste liabilities. This trend is not uniform across jurisdictions, but its aggregate effect is to raise the floor on aqueous adoption over the medium term.
- Material and build economics: Choosing stainless steel versus mild steel construction is a classic tradeoff: roughly 35% higher upfront cost for stainless in many configurations, offset by lower maintenance and longer useful life. Strategic buyers should model maintenance cycles and parts inventories rather than focusing solely on capital outlay.
- Energy consumption and operating design: Thermal efficiency gains — insulated chambers and optimized heating — materially affect operating cost in high-throughput environments. Energy considerations should be treated as a first-order variable in TCO models.
What the PW Consulting report delivers — actionable elements
This report is structured for immediate application by procurement teams, plant managers, and product strategists. Key, actionable deliverables include:
- Executive decision frameworks for equipment selection, including TCO templates that incorporate energy, maintenance, and regulatory compliance variables.
- Vendor assessment matrices that map capabilities (customization, throughput, service coverage, safety features) against buyer priorities.
- Scenario-based procurement timelines aligned to the industry replacement cycle and CAPEX budgeting windows, enabling phased deployments that minimize operational disruption.
- Risk registers and mitigation strategies related to supply chain (materials for durable construction), energy pricing sensitivity, and regulatory shifts.
- Practical implementation checklists for commissioning, validation, and training to accelerate time-to-value post-installation.
How to use this analysis in boardroom and plant-floor conversations
- For CFOs and procurement leads: use the report’s TCO templates to normalize vendor proposals and to compare payback across stainless versus mild steel options, as well as different energy-efficiency tiers.
- For operations and maintenance leaders: prioritize modular designs and strong aftermarket commitments to reduce downtime risk and spare-part inventories.
- For product and R&D teams: focus on thermal efficiency, control-system integration, and serviceability features that lower lifecycle costs — these are the differentiators buyers will pay a premium for through 2032.
Concluding guidance
With a measured CAGR near 3.85% and a market base exceeding USD 220 million in 2025, the front loaded industrial parts washer market presents predictable growth anchored in compliance, efficiency, and replacement demand. However, the real performance differentiator for suppliers and buyers alike will be the ability to translate engineering features into quantifiable lifecycle savings and regulatory risk reduction. PW Consulting’s Front Loaded Industrial Parts Washer Market report provides the analytical scaffolding and practical tools to do exactly that — with deeper segmentation, scenario models, and procurement-ready templates housed in the full study.
Take the next step
This release is a strategic preview. To access the complete segmentation, full vendor scorecards, and downloadable TCO models that support procurement and capital planning in 2026, please visit the PW Consulting report portal. The full report contains the granular data and templates you will need to operationalize the insights summarized above.
For detailed analysis of this topic, please visit the official page: Front Loaded Industrial Parts Washer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com