

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Turbine Inlet Air Cooling (TIAC) Market Poised for Robust Growth — 7.35% CAGR Projected for 2026–2032

Turbine Inlet Air Cooling (TIAC) Market: Strategic Compass for 2026 Decisions
As air temperatures rise and grid dynamics become more volatile, the role of Turbine Inlet Air Cooling (TIAC) in safeguarding and augmenting gas-turbine output has moved from niche optimization to board-level strategic planning. PW Consulting’s latest market study — covering 2020–2025 history and a 2026–2032 forecast horizon — distills the actionable intelligence executives need to make high‑confidence capital, procurement, and partnership decisions in 2026. This release outlines the report’s high-level findings, competitive map, and practical tools while deliberately withholding the granular segment tables and model outputs that deliver the full investment case (available in the full report).
Turbine Inlet Air Cooling (TIAC) Market
Market Trajectory — What the headline numbers mean for strategy
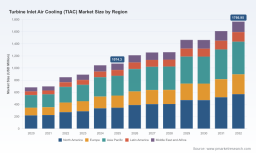
Our macro modelling shows the global TIAC market expanding materially over the next decade. After advancing through a cyclical recovery in 2020–2025, the market is forecast to grow at a compound annual growth rate (CAGR) of approximately 7.35% across 2026–2032. The overall market scale exceeds one billion USD by the 2025 base year and grows into the multi‑billion range over the forecast period. This trajectory reflects three intersecting forces: (1) ongoing demand for peak and mid‑merit power capacity optimization, (2) the operational economics of output augmentation in warm climates, and (3) technology-led cost declines and modularization enabling faster deployments.
Turbine Inlet Air Cooling (TIAC) Market
For executives, the headline takeaway is clear: TIAC is no longer a tactical add‑on; it is an investable capability that can materially influence plant-level dispatch economics and fleet availability. The CAGR implies that waiting for “perfect” market conditions risks being outpaced by competitors who deploy TIAC to secure more reliable, flexible generation capacity.
Turbine Inlet Air Cooling (TIAC) Market
Why 2026 is a pivotal decision window
- CapEx and replacement cycles: Many gas‑turbine operators are entering scheduled overhauls in 2026–2028. These windows minimize integration costs for TIAC systems compared with brownfield retrofits outside outage windows.
- Grid flexibility premium: Markets valuing fast-response capacity and ancillary services are increasing the revenue uplift associated with higher turbine output and ramp capability — creating improved payback profiles for TIAC investments.
- Supplier consolidation and M&A: Recent transactions demonstrate industry consolidation, altering supplier bargaining power and acquisition targets for industrial buyers seeking vertically integrated solutions.
Report anatomy — what PW Consulting provides (practical, modelled, implementable)
PW Consulting’s TIAC study is structured to move executives from strategic intent to executable plans in months, not years. Key deliverables include:
- Market sizing and forecast model (interactive): scenario‑driven top‑down forecasts with sensitivity levers for ambient temperature trends, gas turbine fleet retirement/retrofit rates, and regional demand growth. Note: the public synopsis highlights overall market scale and growth rate; the detailed model that disaggregates by region, type, and application is only available in the full report.
- Investment and payback toolkit: plant-level financial templates that calculate IRR, NPV, and simple payback under variable fuel, power price, and capacity-remuneration regimes.
- Technology decision matrix: a pragmatic framework that maps evaporative systems, fogging, mechanical chillers, and absorption chillers to site conditions (humidity, space, water availability), regulatory constraints, and O&M complexity.
- Procurement and contracting playbook: standardised RFP language, performance acceptance tests, and warranty structures tailored to TIAC modules and integrated systems.
- Deployment playbooks: modular installation pathways (containerized chillers, field-built evaporative systems, packaged fogging), integration checklists for control systems, and commissioning sequencing aligned with turbine maintenance windows.
- Risk and resilience matrix: supply‑chain stress tests, raw‑material exposure analysis, and contingency plans for prolonged warm‑season demand peaks.
Competitive landscape — who matters and why
The TIAC supplier ecosystem is diverse: specialist system integrators, large HVAC and chiller OEMs, and filtration and humidification technology providers converge on the value chain. The market concentration is moderate: the top three players account for a meaningful but not overwhelming share of market revenues, and the top five collectively hold a clear majority, reflecting an industry where regional specialists coexist with global suppliers.
Selected company profiles and recent moves highlighted in the report illustrate the strategic positioning you should monitor as you shape 2026 agendas:
- Stellar Energy (Jacksonville, Florida) — turnkey TIAC systems with thermal energy storage options; claims of up to 30% turbine output enhancement position them strongly for integrated power and data‑center cooling opportunities. Their acquisition by a major thermal systems player in early 2026 underscores the attractiveness of TIAC technologies to broader HVAC/energy companies and signals further consolidation.
- ARANER (Madrid, Spain) — specialist in indirect cooling with heat-exchanger approaches and condensate management; their engineering focus is well-suited to sites where water constraints or regulatory limits favour indirect solutions.
- Mee Industries (California) — leading high‑pressure fogging systems provider; recent industry recognition and product content publications indicate an effort to codify performance benefits and accelerate adoption.
- Johnson Controls (global) — mechanical chiller packaging and containerized systems; their global supply footprint and packaged product lines make them a logical partner for fastest time‑to‑market deployments.
- SPX Cooling Technologies, Munters, Camfil, Caldwell Energy — firms that span evaporative cooling, fogging, filtration, and system integration; their offerings illustrate the modular build vs. integrated system tradeoff faced by buyers.
These profiles reveal two strategic supplier archetypes: product‑centric OEMs (packaged chillers, foggers, filtration) and solution integrators that bundle hardware, controls, and performance guarantees. Buyers should decide whether to optimize for lowest CAPEX (product buys + internal integration) or lowest time/operational risk (turnkey systems with performance contracts).
Market dynamics and risk factors to factor into 2026 planning
- Regulatory and standards environment: Industry bodies continue to develop best practices and standards for TIAC implementation. Organizations that proactively align with these emerging standards will shorten approval cycles and reduce permitting risk.
- Supply‑chain and input cost pressure: Rising commodity prices for steel and aluminum have increased manufacturing input costs for cooling system components. Procurement strategies must incorporate input‑cost escalation clauses, multi‑vendor sourcing, and longer lead‑time planning for critical frames and heat‑exchanger cores.
- Water availability and environmental constraints: Site water use and condensate handling are growing determinants in technology selection, particularly in arid regions. Indirect and closed‑loop systems require more CAPEX but can avoid regulatory constraints associated with evaporative approaches.
- Technology convergence: Thermal energy storage, hybrid cooling architectures, and IoT-enabled controls are creating new value pools by enabling time‑shifted cooling and predictive performance guarantees.
Actionable recommendations for executives (fast moves and strategic bets)
- Supply‑chain readiness (fast move): Lock lead times and component prices for projects scheduled in 2026–2028. Consider call‑off orders or vendor financing where possible to protect against commodity inflation.
- Bundle vs. buy decision framework (fast move): Use a three‑criterion assessment (time to revenue, integration risk, total lifecycle cost) to decide between turnkey providers and best‑of‑breed OEM stacks on each project.
- Targeted pilots (strategic bet): Run two pilots in the 2026 window — one with a high‑augmentation solution (e.g., fogging + wet compression) and one with a conservative, low‑water indirect chiller — to produce empiric delta performance and refine financial models for fleet rollouts.
- M&A and partnership scanning (strategic bet): Monitor specialist integrators and thermal‑storage players as potential acquisition targets to accelerate capability ownership and capture margin uplift from bundled services.
- Contracting innovation (operational): Negotiate performance‑linked contracts where vendors accept partial performance risk in return for higher maintenance or upgrade fees — aligning incentives and de‑risking capital deployment.
What the full PW Consulting TIAC report delivers (and why you should download it)
The public brief identifies the market’s direction and primary decision levers. The full report provides the proprietary, drillable analytics that translate insight into executable project plans: region and application breakdowns, technology share modelling, plant‑level ROI calculators, vendor scorecards, and a suite of procurement templates. We intentionally withhold the granular segmentation figures from this overview to preserve the value of the proprietary datasets and modelling logic that enable confident capital allocation.
If you are evaluating capacity upgrades, negotiating supplier contracts, or sizing acquisition targets in 2026, the full TIAC market study supplies the comparative data, scenario stress‑testing, and commercial templates you need to shorten decision cycles and reduce execution risk.
Next steps
- Download the full report to access the detailed regional, technology, and application models along with the interactive financial toolkit.
- Schedule a briefing with PW Consulting to run a customized site‑level assessment using our plant‑level ROI model and vendor selection matrix.
- Use the procurement playbook immediately to preview standardised RFP language and acceptance testing criteria for your 2026 procurement cycle.
TIAC is more than a technical retrofit; it is a strategic lever for capacity monetization and resilience in a warming world. For leaders shaping 2026 investment plans, the question is not whether TIAC can add value, but how quickly you can operationalize that value into controllable, revenue‑generating capacity. PW Consulting’s TIAC study gives you the roadmap, tools, and vendor insights required to move from consideration to commissioning within the next procurement cycle.
For detailed analysis of this topic, please visit the official page: Turbine Inlet Air Cooling (TIAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com