

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Body Repair Fillers Market Set to Rise from USD 3,600M in 2025 to USD 5,015.4M by 2032 at a 4.85% CAGR

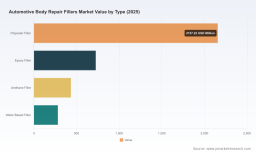
Automotive Body Repair Fillers Market: A Strategic Preview for 2026 Decision‑Makers
PW Consulting’s latest market intelligence on the Automotive Body Repair Fillers market equips executives, product leaders and M&A teams with the strategic orientation they need for 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study synthesizes macro demand trajectories, supplier economics, raw‑material stress tests and regulatory scenario planning. In short: the market reached approximately USD 3.6 billion in 2025 and is forecast to grow at a 4.85% CAGR through the 2026–2032 period, converging toward the mid‑single‑digit‑billion range by the end of the forecast. This briefing highlights the decision‑critical insights inside the full report while intentionally withholding core breakouts to prompt direct engagement with PW Consulting’s primary analysis.
Automotive Body Repair Fillers Market
Why this market matters to your 2026 playbook
-
Profit pools are shifting. Modest overall growth masks divergent economics between product classes, formulation pathways (solvent vs water‑based vs UV), and channel end‑uses (collision, surface prep, restoration). Executive capital allocation in 2026 must prioritize product lines and customers that can sustain margin under volatile input costs and tightening regulatory scrutiny.
Automotive Body Repair Fillers Market -
Input volatility is no longer episodic. Polyester resins and other feedstocks experienced extreme swings during 2020–2025 — our industry dataset shows peak‑to‑trough movements exceeding 40% for key unsaturated polyester inputs — and petroleum‑linked components remain exposed to global oil market shocks. Supply‑chain resilience and hedging strategies will materially affect competitiveness.
Automotive Body Repair Fillers Market -
Regulation is a strategic variable. Pending evaluations by regulatory authorities (notably ECHA assessments around styrene) introduce asymmetric downside risk for polyester‑based systems. Firms that preemptively diversify into lower‑styrene or non‑styrene chemistries, or that adopt UV and water‑based technologies, will have optionality if authorization regimes tighten.
What PW Consulting’s report delivers (practical content summary)
-
Forward‑looking market architecture: A granular forecasting engine that projects total market growth under multiple macroeconomic scenarios, with sensitivity knobs for raw‑material price shocks, vehicle parc evolution and repair rate trends.
-
Competitive positioning and concentration analysis: A supplier ecosystem map that identifies capability differentials—formulation depth, vacuum processing competence, UV curing platforms, and channel strength—paired with a concentration assessment showing a market that remains moderately fragmented at the top end.
-
Product and go‑to‑market playbooks: Actionable pathways for premiumization, lightweight and rapid‑repair formulations, and channel segmentation (professional collision repair chains vs independent installers vs restoration specialists), including SKU rationalization templates and margin simulations.
-
Raw‑material stress tests and mitigation strategies: Scenario models quantifying margin compression across different resin and filler price trajectories; recommended procurement levers including index‑linked contracts, multi‑sourcing, backward integration evaluation and strategic inventory buffers.
-
Regulatory scenario planning: A decision tree assessing potential outcomes from chemical reclassification actions and the operational, reformulation and certification costs associated with each outcome.
-
Commercial and M&A playbooks: Target profiles for tuck‑ins, capability buys (e.g., UV curing or water‑based chemistry), and distribution roll‑ups; integration checklists emphasizing technical service, training and brand equity transfer to protect aftermarket revenues.
-
Performance dashboards and KPIs: Practical metrics for manufacturing efficiency, scrap and rework, technical‑service penetration, and channel gross margin — packaged as templates for rapid roll‑out in 2026 planning cycles.
Competitive landscape — who sets the technical and commercial bar
The competitive field blends established global coatings and chemical groups with regional specialists and manufacturing houses focused on formulation performance for professional repair shops. Key players covered in the report include legacy innovators with broad channel reach, specialist filler manufacturers and emerging low‑cost producers focused on global distribution.
-
ITW Evercoat — Cleveland, Ohio. A premium player known for a full suite of body fillers engineered for professional collision repair, with emphasis on easy sanding, minimal pinholes and lightweight formulations. Recent product activity (including a 2025 product refresh and launches showcased at SEMA) signals continued investment in both performance and brand premiumization.
-
3M (including Bondo brands) — St. Paul, Minnesota. An incumbent with strong vacuum‑process capabilities and cross‑substrate chemistry for steel, aluminum and fiberglass. 3M’s portfolio strategy balances professional‑grade Platinum offerings with the high‑recognition Bondo consumer and pro products, creating channel coverage from DIY to high‑end shops.
-
U.S. Chemical & Plastics (USC) — Ohio. A specialty manufacturer focused on spreadability and workability for professional applications; proposition is grounded in consistent performance and shop productivity.
-
U‑POL — United Kingdom. Differentiates on high‑performance adhesives and finishing attributes in European and global markets; a brand to watch where finish quality and adhesion drive spec decisions.
-
AkzoNobel — Amsterdam. Brings refinish and UV‑capable products into the repair ecosystem, and leverages coatings expertise to offer faster cure paths and productivity gains in high‑throughput collision centers.
-
SYNEW — China. Represents the highly competitive cost‑and‑scale segment supplying distributors and professional shops; global ambition is anchored in price/availability advantages but requires consistent quality control to expand premium adoption.
Collectively, the top tier of suppliers account for a minority share of overall market revenue, leaving room for regional specialists and technology leaders to grow share through differentiated value propositions (service, speed, sustainability and cost). PW Consulting’s market concentration metrics quantify this dynamic and the implications for pricing power and consolidation potential.
Strategic implications for 2026 — prioritized actions
-
De‑risk feedstock exposure now: Build procurement playbooks that combine indexed contracts, geographically diversified suppliers and scenario‑based inventory thresholds. For product leaders, allocate R&D to lower‑styrene and water‑borne alternatives as an insurance strategy against regulatory action.
-
Invest selectively in fast‑cure and productivity technologies: UV‑curable primers and vacuum‑processed fillers materially shorten cycle times in collision centers. Capital allocation for R&D, pilot lines and technical service yields high ROI where labor or bay‑time reduction is a premium.
-
Segment your channel strategy: Differentiate SKU sets and service models for multi‑site collision chains versus independents and restoration specialists. Commercial terms, training investments and technical support should reflect the lifetime value and repair throughput of each customer type.
-
Plan for regulatory bifurcation: Create a two‑track product roadmap—iterate existing chemistries for short‑term competitiveness while accelerating a medium‑term switch to lower‑risk formulations.
-
Explore consolidation around capability gaps: Targets that add UV curing, water‑based chemistry, or technical‑service reach represent the most value‑accretive M&A plays in 2026, particularly for players seeking to climb the value chain into finished refinish systems.
How PW Consulting can accelerate your 2026 decisions
Our full Automotive Body Repair Fillers market report provides the empirical backbone behind the guidance above: a calibrated forecast engine, supplier scorecards, raw‑material stress tests, regulatory scenario matrices and executable commercial playbooks. The material is designed for immediate translation into annual operating plans, capital investment cases and M&A diligence materials.
We intentionally limit the disclosure in this press briefing to preserve the commercial value of core segmentation and pricing models. The full dataset contains detailed regional and application splits, type‑level economics, and a complete financial model that ties demand drivers to price and margin outcomes — elements we recommend decision‑makers review before finalizing 2026 budgets and strategy.
Next steps for leaders
-
Request the full report and the accompanying financial model to stress‑test your business under the PW Consulting scenarios.
-
Commission a tailored workshop to translate the market and regulatory scenarios into a prioritized 90‑day action plan for procurement, R&D and commercial teams.
-
Engage our M&A team for target screening using capability‑based filters that align with your 2026 strategic objectives.
Contact PW Consulting to access the complete Automotive Body Repair Fillers market report and schedule a strategy session tailored to your firm’s competitive context. The full intelligence package is necessary for high‑confidence decisions in 2026; this briefing is a strategic preview designed to orient your agenda and identify where to focus scarce executive attention.
For detailed analysis of this topic, please visit the official page: Automotive Body Repair Fillers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com