

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive DSP Amplifier Market Set for 8.75% CAGR (2026–2032) as Asia Pacific Commands USD 1,800.45 Million Share

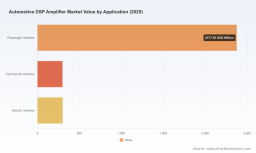
Automotive DSP Amplifier Market — Strategic Outlook for 2026: PW Consulting Market Brief
PW Consulting today releases a strategic preview of our forthcoming Automotive DSP Amplifier Market report (base year 2025, forecast period 2026–2032). The market has demonstrated resilient growth through the first half of the decade and is now entering an inflection phase where software-defined audio, high-efficiency power stages and OEM-level integration are reshaping value chains. Our modeling pegs the 2025 market at USD 2,980.6 million and projects a compound annual growth rate (CAGR) of 8.75% over the forecast horizon, taking the market to a multi-billion-dollar opportunity by 2032. This brief outlines the report’s strategic value for corporate executives planning for 2026 while intentionally withholding the granular segmentation tables and proprietary screenings that are available in the full report.
Automotive Dsp Amplifier Market
Why this matters for 2026 decision-making
-
Timing: Suppliers and OEMs must decide in 2026 whether to accelerate investments in DSP-enabled architectures or to optimize legacy analog pathways. The window to position for premium cabin experiences and EV-tailored audio is narrow; choices this year set product roadmaps and supply commitments for the next generation of vehicles.
Automotive Dsp Amplifier Market -
Technology convergence: Advances in Class‑D efficiency, high-resolution DSP cores and AI/ML-enabled audio processing are creating differentiation that is increasingly software-driven. Companies that can marry silicon advantages with system-level tuning will capture a disproportionate share of aftermarket and OEM wallet.
Automotive Dsp Amplifier Market -
Supply-side constraints: Semiconductor node availability, power-IC lead times and raw-material pressures (including rare-earth challenges) are altering procurement strategies—making near-term supplier qualification and multi-sourcing essential actions for 2026.
What PW Consulting’s full report delivers (practical, executable content)
-
Proprietary market sizing and forward-looking financial scenarios: A bottom-up model that captures unit and ASP dynamics across the entire value chain, providing executable inputs for strategic planning and budgeting.
-
Technology readiness and adoption maps: Comparative assessments of Class‑D topologies, integrated DSP amplifier platforms and multi-channel architectures, with guidance on speed-to-market and IP risks.
-
Competitive playbooks: Company-level capability matrices, product positioning analyses, and channel/partnership opportunity maps to inform go-to-market and OEM negotiation strategies.
-
Supply-chain stress tests and mitigation frameworks: Scenario-based analyses quantifying the impact of semiconductor volatility and rare-earth shortages, with recommended sourcing and inventory levers to preserve launch timelines.
-
Commercial models and pricing sensitivities: Tactics for balancing margin recovery with value-based pricing in OEM replacement cycles and aftermarket segments.
-
M&A and partnership screening tools: A tranche-based approach to assess acquisition targets and strategic partnerships across product, software and silicon layers.
-
Regulatory and qualification checklist: Actionable steps to align development programs with AEC‑Q100 and functional-safety expectations so product validations do not become launch blockers.
Market trajectory and strategic implications
The path from 2020 to 2025 reflects steady expansion in installed units and value-addition per vehicle as audio systems evolved from commodity amplifiers to integrated DSP-powered audio experiences. Our forecast sees that trajectory accelerating as vehicles—especially those positioned as premium or electric—embed higher levels of signal processing, personalized sound profiles and cloud-enabled tuning. The reported CAGR of 8.75% is not simply a volume story: it captures rising average selling prices driven by software-layer monetization, higher channel counts for immersive audio, and the premiumization of in-cabin experiences.
For executives this means three immediate strategic implications for 2026:
-
Product roadmaps must be defined as software-first. Hardware decisions should enable lifecycle monetization through OTA updates, app-based personalization, and analytics.
-
Partnerships with semiconductor vendors and audio-software specialists will be the primary lever to accelerate feature deployment while controlling BOM and certification timelines.
-
Commercial models should shift from transactional hardware margins to recurring revenue streams and value-based pricing tied to perceived user experience improvements.
Competitive landscape — who to watch and why
The market exhibits a mix of specialist audio brands and large semiconductor OEMs. Market concentration is meaningful but not insurmountable: the top three suppliers account for a substantive portion of revenues, and the top five increase that share further—creating a landscape where scale and systems expertise matter.
-
Audiotec Fischer (Germany): A leader in high-end aftermarket and premium OEM audio, the company’s HELIX and BRAX lines—bolstered by recent awards—signal continued traction in differentiated DSP tuning and consumer-facing premium positioning.
-
Audison (Italy): With strong D‑Class power expertise and OEM-focused integrations, Audison is positioned to capitalize on both replacement market demand and niche OEM programs that value tuned audio signatures.
-
Alpine Electronics (Japan): Alpine’s Status and Hi-Res offerings underscore an approach that blends performance hardware with system-level integration—an attractive blueprint for suppliers seeking OEM certification pathways.
-
AudioControl and ARC Audio (USA): These vendors are notable for their signal-processing depth and pro-level tuning tools, which remain highly attractive in aftermarket and specialty OEM fitments.
-
Mosconi (Italy): Compact integrated DSP platforms that target high-fidelity automotive installations; their product strategy highlights the continuing demand for space-efficient solutions in modern cabins.
-
STMicroelectronics, Texas Instruments, Analog Devices, NXP (Semiconductor vendors): These companies are the backbone of the transformation—supplying automotive-grade Class‑D amplifiers, high-performance DSP cores and peripheral silicon. Recent product launches and announcements indicate a clear push to enable smart-cockpit audio features and AI-enabled sound processing at scale.
Recent industry moves—awards for high-end DSP systems, new Class‑D launches, and major processor announcements—are accelerating competitive differentiation along software capability, thermal and electrical efficiency, and ease of OEM integration. For 2026, monitoring which vendors can pair silicon roadmaps with robust automotive qualification and supply commitments will be decisive.
Risks, regulation and supply-chain dynamics to factor into 2026 plans
-
Regulatory/qualification burden: Automotive audio components must meet stringent AEC‑Q100 and functional-safety expectations. These qualification cycles add months to launch timelines and must be embedded in program plans early.
-
Semiconductor and raw-material risk: Mature-node MCU and power-IC volatility—plus rare-earth availability—remain material constraints. Procurement strategies should include long‑lead contracts, dual-sourcing, and design-for-availability to avoid launch slippages.
-
Market consolidation and margin pressure: As silicon suppliers exert pricing pressure and tier-1s demand system-level solutions, supply-side players will face margin compression unless they capture software and services revenue or secure scale advantages.
How PW Consulting’s report accelerates practical decisions in 2026
Our report is structured to convert analysis into executable decisions. It provides scenario-tested financial models you can adapt to internal inputs, supplier risk heatmaps that feed procurement scorecards, and a decision tree for platform vs. bespoke product investment. Importantly, while this preview highlights market direction and competitive forces, the full report contains the granular segmentation, supplier scoring and unit-level assumptions that buyers and strategists require to finalize budgets and supplier selections. We have intentionally omitted those tables here to preserve the integrity of proprietary client frameworks—access to those sections is available on the report page and via direct PW Consulting briefings.
Recommended immediate actions for executives in 2026
-
Reassess product roadmaps against a software-first timeline: prioritize architectures that enable OTA tuning and analytics capture.
-
Secure semiconductor capacity: initiate multi-year supply agreements for key power ICs and DSP cores, and include clauses for supply continuity under elevated raw-material risk.
-
Accelerate supplier qualification: begin AEC‑Q100 and functional-safety validation now to avoid certification-driven delays.
-
Pursue modularization: adopt modular amplifier/DSP assemblies to shorten variant development and reduce inventory risk.
-
Explore partnerships for software monetization: negotiate revenue-sharing or licensing arrangements with audio-software specialists to capture post-sale value.
-
Use the PW Consulting heatmaps for M&A prioritization: target acquisitions that fill gaps in system tuning, cloud connectivity, or silicon partnerships.
PW Consulting’s Automotive DSP Amplifier Market report is designed to be the strategic playbook for 2026: it translates market growth, supplier dynamics and technology shifts into an operational roadmap that executives can act on this year. For full access to the segmentation, company scorecards, unit economics, and proprietary scenario models, please visit our report page or contact PW Consulting for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Automotive Dsp Amplifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com