

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: Press Machine Market to Surpass USD 20.3 Billion by 2032, Expanding at a 5.8% CAGR
By pmarketresearch, 2026-06-30
Press Machine Market 2026: Strategic Imperatives from PW Consulting’s New Market Report
PW Consulting is pleased to release an executive briefing drawn from our comprehensive Press Machine Market report (base year 2025; historical coverage 2020–2025; forecast period 2026–2032). As manufacturing leaders finalize 2026 capital allocation and supply-chain strategies, this briefing highlights the report’s strategic value: rigorous market sizing, trend-forward scenario planning, and actionable playbooks that translate industry insight into board-level decisions. We present high-level findings and strategic recommendations here — detailed segmentation tables, vendor scorecards, and modelled scenarios are intentionally reserved for the full report to preserve competitive utility and to drive direct engagement.
Press Machine Market
Why this report matters for 2026 decision-makers
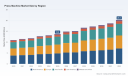
The press machine market has emerged from a period of steady recovery into a structurally evolving sector. Our analysis shows the market expanding from a post-pandemic baseline in 2020 to a materially larger industry by 2025, and continuing to grow through our forecast window. Specifically, total industry value rose consistently during 2020–2025 and, under PW Consulting’s baseline forecast, is projected to expand at a compound annual growth rate (CAGR) of 5.8% through 2032. This trajectory reflects an intersection of cyclical capital expenditures and durable, secular drivers — electrification and lightweighting in transport, reshoring of precision manufacturing, and accelerating adoption of digital process controls — which together create a multi-year investment runway.
Press Machine Market
Core dynamics shaping 2026 strategy
-
Technology substitution and product differentiation: Servo-driven systems and advanced control platforms are reshaping competitive advantage. Buyers now evaluate press procurements through a total-cost lens that places a premium on energy efficiency, repeatability, and integration with factory automation platforms.
Press Machine Market -
Aftermarket and service monetization: With presses being capital-intensive, vendors are competing on lifecycle economics. Service agreements, retrofits, remote diagnostics and spare-parts availability are becoming decisive procurement criteria, and they also represent high-margin revenue streams for machine builders.
-
Concentration and supplier dynamics: The market exhibits mid-level concentration, where the largest global suppliers capture a substantial share of installed capacity while a diverse long tail serves niche and regional needs. This dynamic creates predictable strategic choices for buyers: standardization around a few OEMs to secure scale efficiencies, or diversification to mitigate supplier risk.
-
Trade-show and product-cycle indicators: Recent industry calendar activity — including strategic rebranding and product demonstrations by major OEMs and a persistent presence at major trade events — signals that vendors are prioritizing platform upgrades and partnerships to differentiate in automation and digital services.
What the full PW Consulting report contains (practical, decision-grade content)
-
Market sizing and validated growth scenarios: An audited top-down and bottom-up market model covering 2020–2025 historicals and 2026–2032 forecasts, with sensitivity cases for high/low capex and demand shocks.
-
Buy-side playbooks: Procurement templates that translate market intelligence into RFP language, evaluation scorecards (technical, TCO, service), and tender timetables aligned to supplier lead times and long-lead components.
-
Sell-side strategies: Commercial playbooks for OEMs and integrators addressing portfolio prioritization (new machines vs retrofit), aftermarket monetization, and channel structuring to optimize lifetime value.
-
Technology and CapEx roadmaps: Comparative assessments of mechanical, hydraulic and servo-based platforms — focusing on control architectures, energy profiles, die-handling integration, and retrofit pathways that minimize production disruption.
-
Vendor dossiers and competitive gaps: In-depth company profiles, capabilities maps, M&A radar, and partner-fit assessments to support alliance and sourcing decisions. (Note: granular segmentation tables and per-vendor market shares are available in the full report only.)
-
Scenario planning and stress tests: Playbooks for supply-chain disruption, policy shocks (tariffs, content rules), and demand pivot scenarios with recommended tactical responses and contingency budgets.
Competitive landscape — strategic read for 2026
Our vendor analysis concentrates on leading global OEMs and innovative regional specialists. Rather than publish proprietary market shares in this briefing, we provide qualitative differentiation and strategic implications for corporate decision makers.
-
Schuler Group / ANDRITZ Schuler (Germany) — Following the March 2025 rebranding to ANDRITZ Schuler, the company has signalled a stronger emphasis on integrated forming and handling solutions for automotive and heavy industry. For buyers, this means a compelling proposition when seeking end-to-end systems with strong integration competence — especially for high-volume production lines where co-optimization of press and downstream automation reduces TCO.
-
AIDA (Japan) — AIDA continues to leverage breadth in mechanical and servo stamping solutions and has been active at major trade events. Their value proposition rests on a long track record of reliability and a clear channel for global support — a key consideration for multi-site manufacturers standardizing across geographies.
-
Komatsu (Japan) — Strong in progressive and transfer applications, Komatsu’s engineering depth in sheet-metal cutting and stamping technologies offers advantages in high-mix environments where die complexity and throughput balance are important.
-
Macrodyne Technologies (United States) — Macrodyne’s specialization in custom servo and hydraulic presses with turnkey automation positions it as a preferred partner for large OEMs and tier suppliers demanding bespoke line solutions and on-site engineering support.
-
Wickert Maschinenbau (Germany) — Known for high-precision hydraulic systems for deep drawing and aerospace applications, Wickert is an example of a technology-driven niche player where tolerance and process control command a price premium.
-
MULTIPRESS, Inc. (United States) — With recent product updates and ongoing trade-show engagement, MULTIPRESS remains relevant for buyers seeking proven custom hydraulic solutions and strong retrofitting capability.
-
Beckwood Industries & MetalPress Machinery (United States) — Both firms illustrate the strong North American supplier ecosystem for hydraulic and servo systems, with Beckwood notable for complete press systems and MetalPress for automation integration within regional production networks.
Recent tactical indicators (what we watched in 2025–2026)
-
March 2025: Schuler’s rebranding to ANDRITZ Schuler — signals consolidation of systems-level offerings and a strategic focus on automotive forming lines.
-
Throughout 2025: Active trade-show participation by multiple OEMs, including demonstrations at major regional shows — indicating a product refresh cycle and intensifying competition around digital capabilities and energy efficiency.
-
March 2026: MULTIPRESS updates public technical documentation — reflects an ongoing upgrade cadence among mid-sized suppliers catering to retrofit and custom projects.
Implications for procurement, operations, and corporate strategy in 2026
-
CapEx sequencing: Defer or accelerate? Our modelling suggests that organizations with existing assets that can be retrofitted for control upgrades and energy optimization should prioritize targeted retrofits in 2026 to capture rapid ROI, while greenfield capacity expansion should be staged to align with demand scenarios and component lead times.
-
Vendor selection: Prioritize lifecycle economics over headline price. Formalize TCO metrics in supplier evaluations and require transparent SLAs and spare-part roadmaps as part of contract awards.
-
Digital and service strategies: OEMs and integrators must commit to recurring-revenue models through enhanced service offerings; buyers should negotiate remote-monitoring clauses and joint continuous-improvement programs linked to performance KPIs.
-
Risk management: Diversify supplier exposure across OEM types (global integrators vs regional specialists) to balance lead-time resilience, local serviceability, and technological fit.
Actionable takeaways — what executives must do now
-
Commission a 90-day CapEx triage: classify presses by retrofit potential, remaining useful life, and strategic criticality to prioritize 2026 spend.
-
Update procurement scorecards to include digital compatibility, remote service capability, and spare-parts continuity — require these as contractual deliverables for all major equipment purchases.
-
Engage with two or three shortlisted OEMs on pilot projects to validate retrofit savings and digital integration before committing to fleet-wide rollouts.
-
Embed scenario-based stress tests into the 2026 budget cycle to quantify the impact of supply interruptions and demand variance on both CapEx and maintenance budgets.
How to obtain the full report and analytical assets
This briefing is an executive preview. PW Consulting’s full Press Machine Market report includes the detailed segmentation tables, vendor market shares, downloadable Excel models, and procurement templates that corporate and investor clients will need to operationalize these insights. Given the commercial sensitivity of granular segment-level data, those annexes are reserved for report purchasers and subscriber clients. Visit PW Consulting’s research portal to access the full package, obtain licensing for internal use, or schedule a private briefing with our industry practice team.
PW Consulting’s Press Machine Market report is designed to be a practical, decision-grade resource for 2026: it combines audited historicals, defensible forecast scenarios, and hands-on playbooks to help manufacturers, OEMs and investors convert market signals into measurable outcomes. For organizations that must balance CAPEX discipline with competitiveness, the report provides the frameworks and vendor intelligence needed to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Press Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Engineering Tech Center Market to Grow from USD 145 Million in 2025 to USD 203 Million by 2032 at a 5.25% CAGR
By pmarketresearch, 2026-06-30
PW Consulting Releases Strategic Market Brief: Engineering Tech Center Market — Critical Guidance for 2026 Decision-Making
Executive summary
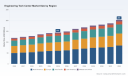
PW Consulting today published a focused market brief, the Engineering Tech Center Market Report (base year 2025, historical window 2020–2025, forecast 2026–2032). Built for senior leaders making capital allocation, site strategy, and product development decisions in 2026, the brief synthesizes quantitative market modeling with on‑the‑ground facility assessments and vendor benchmarking. Our core forecast shows the market expanding from approximately USD 145 million in 2025 to an estimated USD 203 million by 2032 — a compounded annual growth rate of roughly 5.25% — underscoring steady, investment‑grade growth driven by product innovation cycles, localized prototyping needs, and increased demand for controlled testing environments.
Engineering Tech Center Market
Why this report matters for 2026 strategic planning
-
Timing of investment: 2026 is a hinge year for companies that must decide between centralized lab consolidation and distributed “edge” Engineering Tech Centers designed for rapid prototyping and customer co‑development. Our analysis quantifies the valuation implications of each approach and maps the operational tradeoffs that matter most to executive boards.
Engineering Tech Center Market -
Funding and portfolio choices: With predictable mid‑single digit CAGR and identifiable pockets of premium margin activity, boards and PE sponsors can prioritize investments that accelerate time‑to‑customer and reduce NPI cycle time without materially increasing fixed overhead.
Engineering Tech Center Market -
Talent and regulatory planning: The brief links facility requirements to talent sourcing strategies and regulatory exposures that tend to surface as Tech Centers scale from pilot to production support roles.
What you’ll find in the report — practical, decision‑ready content
This is deliberately an operationally focused study designed to move leaders from analysis to action. Highlights include:
-
Investment playbook: step‑by‑step decision matrices for greenfield versus retrofit Tech Centers, including CapEx/Opex modelling templates and sensitivity scenarios tailored to different product types (optical, electro‑optical, digital visualization).
-
Site selection framework: a scoring model that blends accessibility to talent, supply‑chain proximity, real estate costs, utility and permitting risk, and time‑to‑operational readiness.
-
Facility design and layout templates: sample lab footprints (cleanroom gradings, test bays, collaborative demo spaces), equipment lists, and throughput simulations that translate strategic intent into square‑foot and staffing plans.
-
Operational playbook: SOPs for rapid prototyping workflows, test protocol checklists, quality gates, and supplier integration guidelines to compress NPI timelines while safeguarding IP.
-
Commercialization and customer engagement models: go‑to‑market templates for using Tech Centers as sales accelerators, co‑development hubs, and training centers.
-
Risk and compliance toolkits: a regulatory matrix, hazardous materials handling checklist, and market entry considerations for defense‑adjacent optical and imaging technologies.
-
M&A and partnership playbook: diligence checklists and integration roadmaps for bolt‑on acquisitions of lab assets, technology license arrangements, and strategic alliances.
Methodology and confidence
The report blends quantitative market-sizing with qualitative validation. Key inputs include: proprietary revenue modeling (reporting in USD millions), primary interviews with facility operators and technology buyers, on‑site assessments of exemplar Tech Centers, equipment vendor benchmarks, and scenario analysis across alternative adoption curves. We deliberately use a base year of 2025 and a forecast horizon through 2032 to align with typical capital planning cycles and to support multi‑year budgeting decisions.
Competitive landscape — who to watch and why
The Engineering Tech Center market exhibits moderate concentration; top three firms account for a material but not dominant share, while the top five capture roughly half of industry revenue—an environment that rewards both specialized niche players and scale‑enabled platforms. Our qualitative analysis identifies two distinct strategic archetypes that are particularly instructive for 2026 planning:
-
High‑specialization, mission‑driven facilities: companies that invest in deep lab capabilities aligned to a narrow product class (for example, precision electro‑optics for defense and high‑accuracy imaging). These operators compete on technical differentiation, integrated testing capabilities, and IP protection strategies.
-
Customer‑facing collaboration centers: vendors and OEMs that design Tech Centers primarily to accelerate adoption, training, and demonstration for commercial customers. These centers emphasize immersive demo spaces, training curricula, and rapid customization pipelines.
Recent facility investments — practical implications
Two recent facility openings illustrate the strategic calculus that executives should consider when evaluating their own Tech Center plans.
-
EOTECH (Plymouth, Michigan) inaugurated a new Engineering Tech Center in Orofino, Idaho in early 2025. The facility features a purpose‑built optics lab with cleanroom capabilities and precision test gear intended to shorten R&D cycles for weapon sights and camera systems. For competitors and partners, the move signals a commitment to in‑house prototyping and vertically integrated testing — a model that raises the bar for suppliers that rely on legacy external labs.
-
Vision Engineering Ltd (Send, UK) launched a West Coast Tech and Training Center in Irvine, California, also in 2025, focused on immersive visualization and digital microscopy demonstrations. The center emphasizes customer co‑development and hands‑on training with the latest product portfolio. This underscores a contrasting strategy: using Tech Centers to drive adoption and product stickiness rather than to centralize complex manufacturing testing.
Both examples highlight a central strategic choice: prioritize deep technical testing vs. prioritize customer engagement. Many mid‑market players will pursue hybrid models, but the path chosen has immediate capex, talent, and partnership implications that we map in the report.
Market dynamics and strategic implications
-
Structural growth with pockets of premium: Moderate market expansion at roughly 5.25% CAGR suggests that well‑timed investments can be accretive if they capture adjacent service revenue or improve product commercialization velocity.
-
Fragmentation creates opportunities: With a meaningful share held by specialized players, there are acquisition and partnership opportunities for companies seeking rapid capability build‑out without incurring full greenfield costs.
-
Operational complexity is underestimated: Our fieldwork shows that the hidden costs in facility qualification, staffing, and certification frequently extend payback timelines unless managed with explicit gating and milestone economics.
Actionable recommendations for 2026
-
Run a defend vs. expand decision: Use our CapEx/Opex template to model a defend‑or‑expand scenario for each product line in 60–90 day decision cycles. Prioritize experiments that demonstrate measurable reductions in NPI lead times.
-
Adopt a two‑tier hub strategy: Consider a compact central lab for high‑complexity testing paired with regional demo/validation hubs to accelerate sales and shorten feedback loops. The report provides a decision matrix to quantify this tradeoff.
-
Lock in supplier roadmaps early: Negotiate equipment and service contracts with performance SLAs tied to throughput and qualification timelines to protect against backlogs that can derail go‑to‑market launch plans.
-
Embed scalability criteria: Design facilities with modularity in mind so they can pivot between R&D, pilot production, and customer demonstration without major rework.
How to use this brief and where to access detailed datasets
This market brief is intentionally positioned as a high‑value preview: it outlines core forecasts, strategic frameworks, and operational checklists that senior teams can act on immediately while withholding select granular segment tables and regional/application breakdowns that form the basis for executable site and investment decisions. The full report includes comprehensive, downloadable models, regional and application splits, facility benchmarking data, and appendices with interview summaries and sample contractual terms.
To download the complete report, view Excel modeling workbooks, and access the proprietary benchmarking dataset, please visit our report page. The full dataset is available to subscribers and corporate clients who require the granular inputs for budgeting, M&A, and site selection exercises.
Closing perspective
Engineering Tech Centers are becoming a strategic lever: not merely a line item on an operations budget but an active part of product strategy and customer engagement. With predictable mid‑single digit growth and evolving competitive dynamics — including targeted investments from both equipment specialists and customer‑facing OEMs — 2026 is the year to convert strategy into tangible assets or strategic partnerships. PW Consulting’s Engineering Tech Center Market Report equips leaders with the frameworks and templates to do exactly that, while preserving the granular datasets that will inform definitive capital and partnership decisions.
For detailed analysis of this topic, please visit the official page: Engineering Tech Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hook-and-Loop Fasteners Market Poised for 5.3% CAGR, Says PW Consulting
By pmarketresearch, 2026-06-30
Hook-and-Loop Fasteners Market: 2026 Strategic Brief — Why PW Consulting’s New Report Will Shape Your Decisions This Year
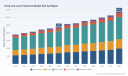
As companies recalibrate procurement, manufacturing footprints, and product roadmaps for 2026, the hook-and-loop fasteners market is moving from steady supply to strategic determinant. PW Consulting’s latest market report — with a 2025 base year, a five‑year historical window (2020–2025) and a 2026–2032 forecast horizon — quantifies that transition. The market expanded from roughly USD 1.9 billion in 2020 to about USD 2.375 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.3% through the forecast period, reaching north of USD 3.3 billion by 2032. That trajectory underpins why procurement, R&D, M&A and regulatory teams should treat hook‑and‑loop strategy as an active, cross‑functional priority in 2026.
Hook-and-Loop Fasteners Market
What the report delivers — practical intelligence, not platitudes
-
Proven, auditable market sizing and a transparent forecasting engine calibrated to a 2025 base year and historical data through 2020–2025, enabling stress‑tested scenarios for 2026 decisions.
Hook-and-Loop Fasteners Market -
Demand-driver decomposition and a supply‑side heat map that links end‑market dynamics (e.g., footwear, transportation, medical, industrial) to volume and pricing pressures without oversimplified assumptions.
Hook-and-Loop Fasteners Market -
Competitive and concentration diagnostics (the market shows clear consolidation dynamics), including a CR3/CR5 concentration view that explains where pricing power and margin pools lie.
-
Company dossiers with strategic positioning and capability matrices for the leading global suppliers, plus an M&A and partnership tracker that captures recent transactions and legal developments.
-
Supply‑chain risk assessments and sourcing playbooks, covering raw‑material volatility, manufacturing footprint tradeoffs, contract design and contingency options for 2026 procurement cycles.
-
Regulatory and standards compendium (medical certifications, trade policy headwinds, IP and tax rulings) and a checklist to convert compliance into commercial advantage.
-
Actionable tools: downloadable Excel models, scenario dashboards, supplier scorecards and negotiation scripts that your commercial and operations teams can deploy immediately.
Why this report is strategically valuable for 2026
Three practical realities make a focused hook‑and‑loop strategy urgent in 2026. First, incremental revenue growth is modest but durable — the market’s mid‑single‑digit CAGR translates to material margin opportunity when players optimize sourcing and product mix. Second, the competitive landscape is concentrated: a small constellation of global suppliers exert meaningful influence on price-setting, innovation cadence and certification availability, creating both risk and arbitrage for challengers and incumbents. Third, trade and regulatory developments in early 2026 have changed the calculus for onshore vs. offshore production and the design of contracts for cross‑border royalty and tax exposure.
For executives weighing capital allocation in 2026, this report converts general trends into decision‑grade inputs. Procurement teams receive supplier risk scores and cost‑to‑requalify estimates; corporate development teams get valuation sensitivities tied to concentration and product differentiation; regulatory and tax teams find timelines and likely outcomes for disputes and rulings that can affect royalty flows and transfer pricing.
Competitive dynamics — who matters and why
-
VELCRO Companies: the globally recognized brand and innovation engine. Its recent majority‑stake transaction in 2026 signals renewed private‑equity appetite for platform assets with durable aftermarket and industrial demand. Buyers and partners should re‑price partnership and licensing negotiations in light of the new ownership and capital strategy.
-
3M: leverages adhesive and assembly know‑how to compete on integrated solutions. Its strengths are materials science and channel reach; strategy teams should assess where bonding systems and reclosable technology create bundling opportunities or margin pressure.
-
APLIX and YKK: specialized product portfolios and manufacturing diversity make them natural collaborators for customers seeking tailored fasteners and extruded hook alternatives. Their R&D pipelines merit monitoring for niche performance breakthroughs (e.g., high‑cycle, non‑lint, biodegradable substrates).
-
Halco and Kuraray: high‑certification and specialty product capabilities matter to medical and defense customers. Halco’s ISO 13485 and ISO 10993‑5 compliance is a strategic enabler for medical OEMs seeking validated fasteners; companies evaluating entry into medical segments must budget for certification timelines and cost.
-
Regional manufacturers and specialists: a broad base of suppliers remains competitive on cost, customization and lead time. For commercial teams, the arbitrage between branded incumbents and nimble suppliers presents negotiation leverage, but also supplier risk if demand shifts rapidly.
Recent developments that should alter 2026 plans
-
Strategic ownership change at a leading brand (May 2026) — a private‑equity acquisition shifted capital priorities and M&A appetite at a market leader, creating window opportunities for bolt‑on consolidation or supplier agreements.
-
Legal rulings in early 2026 affecting royalty tax treatment — these create short‑term earnings and cash‑flow implications for companies with cross‑border licensing structures; tax and treasury teams should review treaty positions and withholding exposure.
-
Trade‑policy changes in February 2026 (an executive order ending certain additional duties) — while not a wholesale policy reset, it alters landed cost math for imports and should be modeled into 2026 sourcing optimization.
-
Market presence signals (trade‑show participation and product showcases) — suppliers continue to invest in differentiated fastener formats and adhesive systems; product teams should fast‑track compatibility testing for next‑generation assemblies.
Regulatory, quality and supply‑chain implications
Regulation, standards and certification are operational constraints — and potential commercial assets. Medical and defense segments reward vendors that meet ISO and biocompatibility standards; suppliers that are already certified hold pricing power in those channels. Meanwhile, trade policy permutations in early 2026 have reduced some tariff overhangs but left other emergency duties intact, creating a dynamic costing environment. Companies should therefore treat supply‑chain decisions as scenario‑based: evaluate the marginal benefit of onshore capacity versus the fixed cost of certification and long‑lead capital — and embed trade and tax scenario outputs into supplier selection criteria.
Five targeted, high‑impact recommendations for 2026
-
Re‑run supplier TCO with 2026 policy scenarios: incorporate revised duty assumptions, potential withholding tax exposures and the cost/time to requalify alternate suppliers.
-
Prioritize product differentiation where certification matters: accelerate investments in non‑lint, high‑cycle and biocompatible variants for medical and high‑performance industrial clients, and budget certification timelines into product launch plans.
-
Use market concentration to negotiate value: where a few suppliers dominate, structure multi‑year volume commitments with performance incentives rather than single‑factor price concessions to preserve innovation incentives.
-
Pursue opportunistic M&A and JV strategies: M&A activity among brand leaders and private investors opens windows for scale buys or technology access — conduct rapid but rigorous diligence on IP, royalty structures and compliance risk.
-
Operationalize sustainability and circularity as commercial differentiators: recycled‑content offerings and documented ESG performance increasingly move beyond compliance to procurement requirements in automotive, medical and institutional buyers.
How PW Consulting de‑risks your 2026 choices
Our report is built to be executable. Beyond narrative insight, subscribers receive a calibrated forecasting model, sensitivity analyses tied to tariff, currency, and raw‑material shocks, plus supplier scorecards and negotiation playbooks that translate market dynamics into contract clauses and KPI thresholds. For legal and tax teams, we map litigation and ruling timelines so that treasury and transfer‑pricing strategies can be stress‑tested against plausible outcomes. For commercial teams, we provide channel‑level demand elasticity proxies and price‑pack architecture recommendations to protect margin during price renegotiations or product upgrades.
Closing — the decision test for 2026
In 2026, the hook‑and‑loop fasteners market will reward organizations that shift from a transactional viewpoint — price and lead time — to a strategic lens that marries product capability, certification, supply resilience and regulatory foresight. PW Consulting’s report supplies the quantitative backbone and the tactical playbooks that allow leadership teams to convert market growth and concentration into durable margin and reduced operational risk.
To preserve the value of this preview (and to align with our “trailer” principle), core segment‑level tables, price curves and supplier‑specific revenue splits are omitted here and available in the full report and data pack. For the complete dataset, downloadable models, and to book a briefing with PW Consulting’s head analysts, visit our report page or contact our industry leads. Equip your 2026 plans with decision‑grade intelligence — the margin and timing differences are material.
For detailed analysis of this topic, please visit the official page: Hook-and-Loop Fasteners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Shrimp market to reach USD 109.0 Billion by 2032, growing at a 5.5% CAGR (2026–2032) as Asia‑Pacific commands ~38.5% share
By pmarketresearch, 2026-06-30
Shrimp Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Report
Executive summary
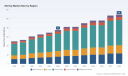
As global seafood markets recalibrate around new trade rules, higher cost structures and evolving consumer preferences, shrimp remains a bellwether commodity for supply-chain transformation and margin recovery. PW Consulting’s Shrimp Market report (base year 2025; historical review 2020–2025; forecast 2026–2032) quantifies that transformation: the industry expanded from roughly USD 50 billion in 2020 to USD 75 billion in 2025 and is projected to exceed USD 80 billion in 2026 under a baseline compound annual growth rate (CAGR) of 5.5%. Under the baseline scenario our modelling takes through 2032, market size approaches the low triple‑digit billions mark.
Shrimp Market
This release is written as a strategic briefing for executives making capital, procurement, channel and regulatory-compliance decisions in 2026. It highlights where value is materializing, where risks are concentrating, and what immediate actions leaders should prioritize. The full report, including granular regional, application and product splits, supply-cost curves and downloadable modelling workbooks, is available on our client portal.
Shrimp Market
Why the 2026 inflection matters
-
Regulatory tightening in key import markets has re-specified acceptable supply chains and verification standards, materially changing trade routes and sourcing costs.
Shrimp Market -
Commodity cost inflation and logistics volatility continue to pressure conventional margin structures; firms with advanced cost-to-serve analytics and adaptive sourcing strategies are already outperforming peers.
-
Consumption patterns are segmenting—retail and foodservice channels are each evolving under different value propositions (convenience, provenance, ready-to-eat formats)—creating differentiated pricing and product innovation opportunities.
Core findings with strategic relevance (what we reveal vs. what the report holds back)
-
Market momentum: After robust recovery through 2025, the shrimp market enters 2026 from a position of measured expansion. Our baseline forecast embeds a 5.5% CAGR across 2026–2032 and stress-tested scenarios for weaker global demand and for accelerated premiumization.
-
Structure and concentration: The market remains moderately fragmented. In aggregate, the top-tier suppliers do not dominate single-handedly; commercial advantage is created through integrated processing, branded value-added products and differentiated channel access.
-
Volatility drivers: Cost pressures (feed, labour, energy), trade policy, and inspection regimes are the primary near-term drivers of supply dislocation. Our scenario matrix shows that supply shocks aligned with regulatory actions create outsized short-term price moves and re-route volumes for up to 12–18 months.
-
Where we hold back: This briefing intentionally omits the detailed regional, type and application percentage splits, transactional price ladders and company-level segment revenues contained in the full report—those datasets are the strategic assets that will inform supplier negotiations, M&A screens and procurement hedging strategies.
Operational playbook for 2026 decisions
-
Immediate (0–6 months): Implement a supplier-risk triage that integrates regulatory-compliance scoring, certificate-of-origin validation and logistics‑time-to‑market exposure. For companies exposed to North American retail channels, prioritize suppliers with verified inspection pathways under the new comparability regimes.
-
Near term (6–18 months): Reprice channel economics using a cost-to-serve model that differentiates frozen vs. fresh throughput, ready-to-eat conversions and value-added processing. Push pilots for new frozen-format packaging and SKU rationalization in high-turn retail accounts.
-
Strategic (18+ months): Decide on vertical moves—selective investment in processing capacity, traceability systems, or a targeted M&A to secure farm-to-processor integration. Use our M&A heatmap (in the full report) to benchmark premium multiples by geography and capacity vintage.
Regulatory landscape and trade dynamics
-
Inspection and comparability rulings: Recent determinations by major importing authorities have tightened acceptable origins for shrimp imports. Importers and distributors who lack rapid compliance documentation face shipment holds and potential market access reductions.
-
Legislative shifts: Bills introduced in import markets that harmonize domestic inspection standards with import controls increase the cost of entry for suppliers that cannot certify to higher standards. Procurement teams must build regulatory contingency into sourcing contracts.
-
Product definitions: Updates to official seafood lists expand the set of regulated species and labelling requirements, with direct implications for product coding, tariff classification and shelf claims.
Competitive landscape: what leading firms are doing
We evaluated public and private players across the value chain—producers, processors, importers and branded distributors—and identified three repeatable strategic postures that correlate with resilience and margin improvement:
-
Integration and processing focus (example: Aqua Star, High Liner Foods). These firms are leveraging processing scale, frozen‑specialty competence and route-to-retail relationships to capture higher-margin, value-added SKUs.
-
Source-differentiation and traceability (example: Clearwater Seafoods, Wild Ocean Direct). Vertically-integrated wild-capture suppliers are positioning around provenance and sustainability claims to defend premium channels.
-
Distribution and market penetration (example: Mazzetta Company, Nordic Seafood, Surapon Foods). Importers and global distributors are optimizing inventory turns and leveraging long-standing trade networks; their near-term value depends on flexible logistics and rapid response to regulatory denials.
In practice, many market leaders combine these postures—backward integration, branded value-add and nimble distribution—to create differentiated offerings. The full report contains case studies and benchmarking tables detailing asset footprints, product portfolios and likely strategic moves for each named firm.
Recent market signals to monitor
-
Industry forums and trade shows continue to focus on China and larger Asian demand pools; these venues are where early shifts in consumer product mix and packaging innovations surface.
-
Market updates from trade analysts show persistent volatility in trade flows across major origins; buyers should maintain dynamic sourcing agreements and optionality on contracted volumes.
-
Product launches and commercial strategies from large exporters indicate a movement toward convenience and ready-to-eat formats—an axis that will shape shelf pricing and margin pools.
Risk and mitigation framework
Our report operationalizes risk into five quantifiable vectors—regulatory, supply, price, channel, and reputational—and maps mitigants aligned with investor and commercial timelines. Examples include:
-
Regulatory: Maintain dual-source approvals and invest in real-time certificate-of-origin verification tools.
-
Supply: Execute staged supplier diversification tied to performance KPIs rather than volume-only contracts.
-
Price: Embed flexible pricing corridors and index-linked clauses for feed and energy-related cost swings.
-
Channel: Pilot aggregated frozen-ready SKUs in retail to test demand elasticity without full SKU rollouts.
-
Reputational: Fund independent third-party audits and transparency dashboards for high-value retail accounts.
What the PW Consulting Shrimp Market report contains (operational table of contents)
-
Comprehensive market sizing and forecast (2020–2032) with baseline and stress scenarios.
-
Supplier and processing cost curves with unit-economics modelling.
-
Regulatory impact assessments and compliance playbooks for major importing jurisdictions.
-
Channel strategies for retail, foodservice and industrial demand—incl. go-to-market playbooks and SKU optimization templates.
-
Competitive intelligence dossiers on leading firms and an M&A heatmap showing target classes and valuation benchmarks.
-
Interactive Excel models and dashboards to test sourcing scenarios, price shocks and margin sensitivities.
Strategic recommendations for 2026
-
Prioritize compliance-driven sourcing: Tie new contracting to suppliers’ verifiable compliance status; delay capacity commitments where verification is uncertain.
-
Invest selectively in traceability: Low-cost traceability pilots deliver outsized ROI where access to regulated markets is conditional on provenance.
-
Adopt dynamic procurement: Move from static annual contracts to rolling contracts with volume-flex and price-index mechanisms to manage volatility.
-
Allocate R&D to convenience formats: Short-cycle investments in frozen and ready-to-eat formats can capture retail share shifts at modest incremental capex.
-
Use the PW M&A heatmap: For companies pursuing consolidation, prioritize targets that add processing capacity or verified supply chains rather than pure distribution reach alone.
Final note — the strategic value of the full dataset
For senior teams making allocation decisions in 2026, the value is not information per se, but actionable, model-led insight. PW Consulting’s full Shrimp Market report provides the raw datasets, regional and product splits, supply‑cost ladders and scenario workbooks you need to convert market intelligence into executable decisions. This briefing intentionally surfaces the strategic priorities and practical playbook while reserving the granular tables and deal-grade models for the full product—designed to be used directly in procurement negotiations, board-level planning and M&A diligence.
To access the full report, Excel models and bespoke advisory options, visit the PW Consulting Shrimp Market page or contact your client director. PW Consulting stands ready to support scenario testing, supplier rationalization and regulatory readiness planning for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Shrimp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mass Transfer (Distillation) Market to Expand at 6.98% CAGR (2026–2032), Rising from USD 1,549.0 Million in 2025 to USD 2,481.0 Million — North America, Column Internals and Petroleum Industrial Lead (CR3 58%, CR5 68%)
By pmarketresearch, 2026-06-30
Mass Transfer (Distillation) Market: Strategic Signals for 2026 Decision-Making
Executive snapshot
As PW Consulting releases its Mass Transfer (Distillation) Market study, we present a focused briefing on the strategic implications senior executives must weigh in 2026. The market has expanded steadily from an estimated USD 1,150 million in 2020 to about USD 1,549 million in 2025, and PwC-style forecasting (2026–2032) points to continued expansion at a compound annual growth rate (CAGR) of approximately 6.98%. By the end of the forecast window, the market is expected to approach the mid‑billion-dollar range. Market concentration is meaningful but not monopolistic: the top three players account for roughly 58% of industry revenue while the top five reach about 68%, leaving room for specialist entrants and regional champions.
Mass Transfer (Distillation) Market
Why this report matters for 2026 planning
-
Macro clarity for capex allocation: Our sizing and trend analysis provide finance and strategy teams a defensible basis to prioritize capital investments in distillation assets, internals and energy‑efficiency retrofits during 2026 budget cycles.
Mass Transfer (Distillation) Market -
Procurement and vendor selection: The vendor landscape analysis, combined with scenario modeling for energy price swings and regulatory tightening, equips procurement with a shortlisting framework that balances performance, total cost of ownership (TCO) and supply resilience.
Mass Transfer (Distillation) Market -
Technology-roadmap alignment: Engineers and R&D leaders can benchmark investment timing for electrified and hybrid distillation solutions against adoption curves and commercial deployments captured in the report.
-
M&A and partnership targeting: Corporate development teams can use our concentration and capability overlays to identify bolt‑on targets and strategic alliances that accelerate entry into adjacent separation technologies.
Market dynamics: drivers, constraints, and inflection points
The distillation value chain is being reshaped by three intersecting forces: regulatory pressure, energy and sustainability imperatives, and technology innovation. Regulation remains a consistent driver—programs focused on solvent recovery and emissions control are increasingly enforced, prompting operators to upgrade or replace legacy distillation systems. For example, enhanced solvent recovery requirements under key air quality programs are driving demand for higher‑efficiency column internals and integrated recovery units.
On the energy and sustainability front, feedstock and fuel specifications continue to evolve (e.g., tighter sulfur limits and cleaner fuel mandates), creating technical demand for refined separation solutions and process optimization. Simultaneously, electrified distillation and other process electrification concepts—already in commercial pilots and early plant rollouts—offer a pathway to reduce indirect emissions and, in some cases, lower operating expense through improved thermal integration. These emergent technologies (including proprietary implementations from incumbent suppliers) are altering retrofit economics and lifecycle assessments.
Technological progress is visible across internals, packings and tray designs, with emphasis on improving mass transfer per unit pressure drop, increasing turndown capability, and easing maintenance. Incremental hardware advances are being complemented by digital optimization—advanced control strategies, model predictive control, and condition-based maintenance are materially extending asset life and performance.
Report coverage and practitioner tools
PW Consulting’s Mass Transfer (Distillation) Market report is designed as an operationally actionable toolkit for executives, plant managers and corporate strategists. Key inclusions:
-
Comprehensive market sizing and historical trend analysis (2020–2025 base) with forward projections to 2032, employing bottom‑up and top‑down triangulation methods.
-
Segmentation across product types, applications, and regions, coupled with scenario analyses that stress‑test demand under different regulatory and energy price pathways. (Note: our public summary hides detailed segment-level figures to protect the competitive integrity of the primary data set—subscribers can access full granular tables and dashboards on the report portal.)
-
Vendor profiles and capability matrices covering design, manufacturing footprint, aftermarket services and innovation pipelines.
-
Practical decision frameworks—capex prioritization templates, retrofit business‑case models, procurement scorecards and a tender playbook optimized for complex separation projects.
-
Supply‑chain risk heatmaps and contingency planning guidelines addressing critical raw material availability, manufacturing lead times and geopolitical exposures.
Competitive landscape: what incumbents are doing
The industry is shaped by well-established engineering suppliers and a cohort of specialized fabricators and service providers. Several players are noteworthy for their strategic positioning:
-
Sulzer Ltd (Winterthur, Switzerland) — Strengths: deep product portfolio in column internals, active R&D in energy‑saving technologies, and growing commercial traction for electrified distillation concepts. Recent company disclosures indicate robust 2025 results and a continued emphasis on distillation and absorption technologies, underlining Sulzer’s role as a technology leader and a bellwether for advanced separation adoption.
-
Koch‑Glitsch (Wichita, USA) — Strengths: global engineering reach, integrated tower internals and phase‑separation solutions, and a history of project delivery for large refining and petrochemical clients. Their toolset is frequently chosen where scale and complete‑scope responsibility are required.
-
RVT Process Equipment GmbH (Marktrodach, Germany) — Strengths: European fabrication excellence and custom internals and tray manufacturing, serving clients needing engineered, high‑precision internals with tight quality and delivery specifications.
-
De Dietrich Process Systems (Niederbronn, France) — Strengths: engineered columns, turnkey systems and strong presence in chemical processing applications. Their exhibition plans at chemicals trade events highlight ongoing efforts to showcase integrated process equipment and to deepen market visibility.
-
Chane Terminal Botlek B.V. (Rotterdam, Netherlands) — Strengths: terminal operator with project capabilities for petrochemical processing and toll distillation services. Recent expansion projects focused on sustainable aviation fuel capacity signal an operational pivot to renewable fuel processing and hub services.
-
Sepco Process Inc. (Conroe, Texas, USA) — Strengths: vendor of random packings and separation media with a focus on competitive pricing, aftermarket supply continuity and specialty packing solutions for retrofit and newbuild columns.
These incumbents illustrate a mix of technology leadership, regional manufacturing density and service depth. The CR3/CR5 concentration metrics cited earlier reflect a market where a few firms capture scale advantages while a long tail of specialists compete on niche performance, cost or local presence.
Strategic implications and recommended actions for 2026
-
Prioritize retrofits that deliver near‑term OPEX reductions: Use the report’s retrofit TCO models to rank candidate columns by payback under varying energy price and carbon cost scenarios. Focus on internals and packing upgrades with short payback horizons to de‑risk CAPEX.
-
Evaluate electrified distillation pilots selectively: For sites with constrained thermal integration or access to low‑carbon electricity, run structured pilots with clear performance KPIs. Use supplier partnerships to offload technical uncertainty and integrate learnings into a cross‑site deployment roadmap.
-
Embed regulatory forward‑scanning in project gating: Given tightening solvent recovery and emissions standards, ensure that new projects and major revamps include compliance thresholds that exceed current minimums to avoid stranded assets.
-
Leverage procurement playbooks to shorten supplier selection cycles: Apply the report’s scorecard to balance technical fit, delivery risk and aftermarket service terms—this is especially important given lead‑time volatility and the strategic nature of internals supply.
-
Scan M&A selectively: Identify small, high‑performance suppliers or service providers whose technology or market access would accelerate the buyer’s entry into high‑growth niches, while being mindful of integration complexity and dilution of focus.
Next steps and how to use this briefing
This briefing highlights the strategic vantage points PW Consulting’s full Mass Transfer (Distillation) Market report provides. Leaders preparing 2026 budgets should treat the report as both a diagnostic and an implementation playbook: it combines market sizing and competitive benchmarking with contract templates, retrofit calculators and scenario analyses calibrated to realistic regulatory and energy trajectories.
To preserve the competitive integrity of our primary research and to respect client confidentiality, this release intentionally omits detailed segment tables and region‑level allocations. Subscribers to the full report receive interactive dashboards, downloadable datasets and supplier scorecards that unlock those insights for transaction support, capital planning and engineering decision‑making.
Conclusion: signal or noise?
The mass transfer sector is transitioning from incremental hardware improvements to a phase where system‑level integration, electrification and regulatory alignment will determine winners and losers. Market scale is growing at a mid‑single‑digit CAGR, incumbents are reinforcing position through technology and project wins, and new‑generation solutions are beginning to shift the economic calculus for retrofits and newbuilds. For 2026, the most valuable decisions will be those that convert market visibility into prioritized, measurable pilot and retrofit programs—supported by disciplined procurement and an eye toward regulatory resilience.
For full access to the granular segment tables, company profiles, and the implementation toolkit referenced above, visit the PW Consulting report page to download the full Mass Transfer (Distillation) Market report and associated datasets.
For detailed analysis of this topic, please visit the official page: Mass Transfer (Distillation) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aluminum Nitride Ceramic Heaters Market to Reach USD 401.9 Million by 2032, Expanding at a 7.2% CAGR (2026–2032)
By pmarketresearch, 2026-06-30
Aluminum Nitride (AlN) Ceramic Heaters Market — PW Consulting Strategic Preview for 2026 Decision-Makers
PW Consulting today releases a strategic preview of our forthcoming in-depth market research on the Aluminum Nitride (AlN) Ceramic Heaters market. Built on a rigorous assessment of the historical window (2020–2025) and forward-looking forecasts for 2026–2032, this analysis is designed as a practical decision-support tool for executives, procurement leaders, R&D heads and corporate strategists preparing plans for 2026. The market is sized and modeled in USD Million; our base year is 2025.
Aluminum Nitride Ceramic Heaters Market
Executive snapshot
- Market trajectory: Our bottom-up model shows the global AlN ceramic heaters market growing at a compound annual growth rate (CAGR) of approximately 7.2% over the forecast window. In USD Million terms the market expands from a 2025 base of roughly 247.2 to an estimated 401.9 by 2032, reflecting continuing demand from high‑precision thermal-management applications.
- Competitive posture: The supplier landscape remains fragmented relative to many semiconductor-related supply chains — the leading firms do not yet dominate in a way that precludes strategic entry, investment or consolidation plays.
- Strategic imperative: For organizations with exposure to semiconductor equipment, advanced packaging, medical devices, and high-temperature power electronics, the coming 18–24 months will be decisive for supplier qualification, capacity alignment and product-roadmap choices.
Why this report matters to 2026 strategic planning
- Actionable forecasting: The report translates growth trajectories into purchase‑level scenarios and capacity stress tests that help procurement and operations teams size buffer stocks, rework lead‑time assumptions, and prioritize second-source qualifications.
- Investment clarity: Corporate development and finance teams receive an invest-or-wait framework calibrated to AlN-specific R&D costs, expected margin dynamics, and market concentration trends — enabling disciplined capex and M&A screening for 2026 budgets.
- Risk-to-opportunity mapping: We map the upstream supply risks (feedstock availability, sintering capacity, multi-zone module complexity) into tangible mitigation options and commercial approaches — for example, how to partition sourcing between high‑conductivity suppliers and flexible custom-component shops.
- Technology roadmap alignment: Product and process teams gain a view of which heater architectures (multi‑zone, embedded sensors, thick‑film patterns) are passing from niche to mainstream, and how that evolution should affect validation programs and product launch timing.
Headline findings (selective, non‑exhaustive)
- Sustained mid-single-digit growth: Demand is driven by capital spending cycles in semiconductor fab equipment and by increasing thermal management needs in next‑gen power electronics and medical devices. The model’s 7.2% CAGR embeds scenarios for cyclical semiconductor demand as well as secular growth from adjacent spaces.
- Near-term capacity shifts matter: Capacity expansions announced and completed by established ceramic manufacturers materially change lead-time and price elasticity in the short term; buyers who act early can lock favorable terms or secure priority allocations.
- Modular, sensor‑integrated heaters are ascending: Designs that integrate multi‑zone control and embedded temperature sensing reduce process cycle variability and are being adopted faster in advanced node and ALD/PECVD toolsets.
- Fragmentation creates both risk and optionality: A market without a handful of overwhelming incumbents means opportunities for supply diversification and M&A, but it also increases the need for rigorous supplier qualification and quality assurance processes.
Report contents — the practical toolkit inside
To equip decision-makers for 2026, the full report is organized as an operational playbook rather than a high-level summary. Highlights include:
Aluminum Nitride Ceramic Heaters Market
- Methodology and market-sizing mechanics: detailed assumptions, primary interview framework and sensitivity analyses so you can replicate or update the model for bespoke scenarios.
- Demand segmentation framework: demand drivers by end-market and heater architecture, with scenario variants tied to semiconductor capex cycles, medical device adoption rates and power-electronics conversion timelines.
- Supply-chain map and capacity tracker: verified supplier capabilities, manufacturing methods, typical lead times, and a framework to evaluate single‑sourced vs diversified supply strategies.
- Competitive benchmarking: comprehensive profiles of active suppliers, innovation focus, manufacturing strengths, and recent capacity or product announcements—scored for fit against different buyer personas.
- Pricing and margin model: indexed price curves by heater complexity with a stress-testing feature for raw-material and energy-cost shocks.
- Commercial playbooks: supplier selection scorecards, qualification roadmaps, procurement contract templates and negotiation levers customized to AlN heaters.
- M&A and partnership screeners: high‑probability target profiles, valuation multiples observed in analogous ceramic and thermal‑management transactions, and a short-listing methodology for bolt-ons or strategic JV partners.
- Implementation appendices: sample test protocols, cleanroom integration checklists, and regulatory considerations specific to semiconductor and medical environments.
Competitive landscape — interpreting supplier moves
The report dissects the supplier ecosystem and profiles the market’s most consequential participants — from legacy ceramic specialists to niche technology suppliers. While the space remains fragmented (enabling buyers to assemble multi‑source networks), several firms stand out for distinct capabilities that shape strategy:
Aluminum Nitride Ceramic Heaters Market
- Leading ceramic specialists with deep high‑purity AlN expertise — strong in multi‑zone, custom heater modules for CVD/ALD applications and high-volume fab qualification programs.
- Global manufacturers investing in capacity expansion for larger wafer formats and higher throughput, which affects availability and qualification timelines for 300 mm and advanced packaging lines.
- Component-focused firms delivering differentiated approaches — hot‑pressed vs direct‑sintered production, thick‑film patterning, and embedded sensor integration — each technology path introduces different cost, lead time and performance trade-offs.
- Regional and emerging suppliers who provide nimble customization and favorable lead times for small‑batch needs, but require tighter incoming quality controls when integrated into critical process tools.
Our company-by-company analysis highlights where each supplier plays to win — for example, who is prioritizing high‑thermal‑conductivity substrates, who has scale for large‑format plates, and which firms are building embedded‑sensor heater lines. These profiles include operational footprints, recent capacity moves, and technology roadmaps to support supplier selection and partnership decisions.
Strategic implications — a focused 90‑day playbook for 2026
- Immediate (0–30 days): run a supplier risk assessment using our template; identify single-source exposures and flag critical long‑lead items for expedited qualification.
- Near term (30–90 days): initiate parallel qualification programs with a high‑conductivity incumbent and a nimble regional manufacturer; negotiate optionality in pricing and capacity commitments tied to milestone triggers.
- Medium term (90–180 days): evaluate M&A or strategic partnerships for upstream control of specialty AlN processing or for access to proprietary multi‑zone module designs that shorten customer qualification cycles.
- Cross‑functional: align procurement, R&D and operations on a single set of heater-performance KPIs, incorporating thermal uniformity, drift, and embedded-sensor fidelity into acceptance criteria to reduce iteration during tool integration.
Who should read this report
- CEOs and business-unit leaders planning market-entry, capacity or M&A moves in thermal management or semiconductor suppliers.
- Procurement and supply‑chain executives needing a clear, actionable qualification and sourcing plan for high‑reliability heater components.
- R&D and product teams seeking insight into which heater architectures will become standard in next‑gen tools and how to align validation timelines.
- Private equity and corporate development teams screening targets in advanced ceramics, thermal‑management components, or specialty manufacturing assets.
Why PW Consulting
PW Consulting’s research combines primary interviews with suppliers, OEMs and fab tool integrators, a rigorous bottom‑up sizing methodology, and scenario stress‑testing for capital and operational risks. Our objective is not only to quantify market momentum (the aggregated market model summarized earlier) but to convert that intelligence into executable commercial and technical plans that buyers and investors can apply immediately.
Next steps and how to access the full intelligence
This release is a strategic preview intended to demonstrate the report’s depth and relevance while preserving the proprietary segmentation tables, supplier scorecards, and primary‑data appendices that underpin 2026 decision-making. The full report contains the granular regional, application and product‑type breakdowns, company financial overlays, price‑by‑architecture models and primary interview transcripts required to operationalize the insights above.
To obtain the full Aluminum Nitride Ceramic Heaters Market report, including downloadable models and supplier benchmarking tools, please visit our report page or contact PW Consulting’s commercial team for a briefing and sample extracts tailored to your use case.
For detailed analysis of this topic, please visit the official page: Aluminum Nitride Ceramic Heaters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Safety Shut-off Valves for Gas Meters Market Poised to Rise from USD 215.0 Million in 2025 to USD 344.8 Million by 2032 at a 9.1% CAGR
By pmarketresearch, 2026-06-30
Safety Shut-off Valves for Gas Meters Market: Strategic Imperatives for 2026 — PW Consulting Snapshot
PW Consulting’s latest market study on Safety Shut-off Valves for Gas Meters (base year 2025, historical window 2020–2025, forecast period 2026–2032) provides an executive-level playbook for corporate decision-makers who must balance safety compliance, infrastructure modernization, and profitable growth. The market has expanded from roughly USD 163 million in 2020 to USD 215 million in 2025 and, under the report’s baseline scenario, is projected to reach approximately USD 345 million by 2032—reflecting a compounded annual growth rate (CAGR) of 9.1% across the 2026–2032 forecasting horizon.
Safety Shut-off Valves for Gas Meters Market
Why this report matters for 2026 corporate strategy
-
Regulatory acceleration: Building codes and state-level mandates (including recent earthquake-actuated and fire shut-off valve certification programs) are making integrated and certified shut-off solutions not only preferred but in many jurisdictions compulsory for new and replacement meter installs.
Safety Shut-off Valves for Gas Meters Market -
Smart-grid convergence: Utilities and meter OEMs are embedding shut-off functionality into smart metering platforms as a value-added safety capability that also serves operational and commercial purposes—leak mitigation, remote isolation, and automated incident response.
Safety Shut-off Valves for Gas Meters Market -
Risk transfer and insurance dynamics: Insurers and risk managers increasingly reward demonstrable automatic isolation and remote shut-off capabilities through reduced premiums and improved underwriting terms.
-
Commercial models evolving: The supply chain is shifting from pure hardware sales to integrated hardware-plus-services propositions (installation, calibration, data services, warranty extensions), opening new revenue streams but also complicating procurement.
Report scope — practical, decision-ready content (high level)
-
Validated market sizing and 7-year forecasting (2026–2032) with scenario analysis that isolates the impact of regulatory shocks, accelerated retrofit programs, and technology adoption curves.
-
Demand-driver decomposition and barrier mapping aligned to utility operator KPIs, building code timelines, and capex cycles.
-
Supplier landscape and capability heatmaps: product architectures, integration maturity, certification status, and go-to-market models (OEM, channel, systems integrator).
-
Commercial and technical due diligence checklists tailored for procurement, pilot programs, and M&A screening.
-
Deployment playbooks for residential, multi-family, commercial, and industrial rollouts—covering installation sequencing, telemetry integration, maintenance regimes, and retrofit constraints.
-
Financial toolkits including ROI calculators, lifecycle TCO models, and sensitivity analysis for component price volatility, installation labor rates, and regulatory phase-in schedules.
-
Risk matrices and mitigation plans covering performance failure modes, regulatory non-conformance, cybersecurity for remotely operated valves, and supply chain disruption scenarios.
Key strategic takeaways for executive decision-making
-
Prioritize integrated solutions where certification and remote-control capability materially reduce operational risk. In many municipal and utility contexts, the up-front premium for integrated shut-off valves is offset within a 3–5 year window through avoided incidents and insurance savings.
-
Design retrofit-first strategies that focus on high-risk building typologies and critical distribution nodes—these deliver the fastest risk reduction per dollar invested and create demonstrable ROI cases for broader programs.
-
Use procurement as a strategic lever: require interoperability and open telemetry standards in RFPs to avoid vendor lock-in and enable future analytics monetization.
-
Invest in field-service capability or partner with specialized integrators. The market is moving toward OPEX-friendly subscription models; capturing aftermarket services is essential to sustaining margins.
-
Embed regulatory monitoring into product roadmaps. Roadmap decisions—sensor fusion, actuator redundancy, self-diagnostic functionality—should be prioritized according to emerging certification requirements and local code changes.
-
Adopt a two-track M&A posture: (1) bolt-on components and valve-tech vendors that close functional gaps, and (2) systems integrators that accelerate route-to-market for retrofit programs.
Competitive landscape: what to watch
The competitive dynamic is defined by a mix of large metering OEMs embedding shut-off functionality and specialist valve suppliers focused on certification and compliance. Notable market participants include Itron and Honeywell’s American Meter (including the Elster product line), which have moved from offering valves as discrete components to delivering integrated meters with embedded shut-off logic and remote closure capability. Specialist vendors such as NSF Control play a critical role in compliance-focused designs and certification pathways.
-
Itron has demonstrated strong commercial traction and installed base momentum with its Intelis platform; recent disclosures indicate multi-million unit deployments and continued feature enhancements around automatic closure on high-flow, overpressure, or temperature excursions as well as remote shut-off. For strategy teams, Itron’s installed base represents both a benchmark for integration maturity and a competitive pressure point for incumbents and new entrants.
-
Honeywell (American Meter/Elster) continues to validate integrated shut-off approaches through pilots and government-supported demonstrations, positioning its AC-series meters as part of broader building safety projects. These demonstrations signal utility and regulatory interest in combining smart metering with automatic safety intervention.
-
Specialist suppliers such as NSF Control should not be underestimated: their compliance-focused offerings and relationships with certifying bodies make them sought-after partners for OEMs and utilities that must accelerate approvals across jurisdictions.
Regulatory and standards context — implications for 2026
Regulatory momentum is a primary demand lever. Examples include state-led certification programs for earthquake-actuated valves and local laws mandating thermal shut-off valves for new or replaced meters. These developments create predictable, near-term retrofit windows in many jurisdictions and drive procurement cycles among utilities, property owners, and municipal authorities. Strategy teams should map product certifications against license-to-operate requirements across target markets and model timing of mandated rollouts as scenario inputs to procurement and manufacturing planning.
Operational considerations and technology risks
-
Interoperability and telemetry: Closed, proprietary valve-control protocols increase total lifecycle cost and hinder integration with utility ADMS/MDMS platforms. RFPs should enforce open communication standards and documented APIs.
-
Cybersecurity: Remote-actuated valves introduce attack surfaces. Security-by-design (firmware signing, authenticated remote commands, intrusion detection) must be a procurement prerequisite.
-
Field reliability and maintainability: Valve actuators must meet specified duty cycles and environmental tolerances; maintenance models should be validated through pilot-to-scale service level agreements (SLAs).
-
Supply chain resilience: Critical component single-source risks (actuators, solenoids, control electronics) require dual-sourcing plans and contractual continuity clauses.
Decision framework for 2026 leaders
-
Step 1 — Rapid diagnostic: Map your installed meter population to regulatory exposure and risk-weighted incident history. This triage determines near-term retrofit priority.
-
Step 2 — Pilot and validation: Run 3–6 month pilots that stress-test integration with utility control systems, evaluate remote-shutoff response times, and validate fault-detection algorithms.
-
Step 3 — Procurement architecture: Shift from lowest-price bids to outcome-based contracts that tie vendor compensation to reliability KPIs and successful certifications.
-
Step 4 — Scale and service: Combine capital deployment with a managed services layer for firmware updates, incident analytics, and preventative maintenance.
-
Step 5 — Strategic M&A/partnerships: Use acquisitions to accelerate capability gaps (e.g., sensing, secure comms, field services) and partnerships to access local certification pathways.
How PW Consulting supports enterprise action
PW Consulting brings a rapid-deployment advisory package for senior executives that combines the full report’s data-driven market model with hands-on implementation support: regulatory mapping, supplier negotiations, pilot design, and a tailored ROI/TCO workbook. Our deep-dive vendor scorecards distill commercial, technical, and certification criteria into an executive-friendly dashboard to accelerate procurement and M&A decisions.
This release is a strategic “trailer” designed to demonstrate the depth of analysis and practical utility of PW Consulting’s full Safety Shut-off Valves for Gas Meters Market report. For licensing the full model, receiving the complete supplier scorecards, segmentation-level data, and the interactive scenario tools that power investment-grade decision-making, please visit our report page and request the full study.
For detailed analysis of this topic, please visit the official page: Safety Shut-off Valves for Gas Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water Hammer Arrestors Market Poised for Steady Expansion at 4.28% CAGR Through 2026–2032
By pmarketresearch, 2026-06-30
Water Hammer Arrestors Market 2026: Strategic Preview for Decision-Makers
Executive snapshot
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise strategic preview of our latest Water Hammer Arrestors Market report—designed to equip business leaders with the insight needed to make decisive moves in 2026. The global market, measured across a robust historical window (2020–2025) and modeled through an 2026–2032 forecast horizon, demonstrates steady expansion with a compound annual growth rate (CAGR) of 4.28%. From a base-year perspective (2025), the market has trended upward from earlier years and our projections show continued upside toward 2032.
Water Hammer Arrestors Market
Why this matters for 2026 decision-making
- Timing for product and channel investments: The mid-decade inflection evident in our historical-to-forecast series means firms that act in 2026 can capture incremental share as installers adopt smaller, easier-to-fit arrestors and as commercial retrofits accelerate.
- Regulatory alignment as a competitive moat: With certification and code requirements from bodies such as the Plumbing & Drainage Institute (PDI), ANSI/ASSE and the International Code Council increasingly shaping procurement and specification, compliance-aware offerings reduce friction for specifiers and lower go-to-market costs.
- M&A and consolidation readiness: A moderately concentrated marketplace—where the top three and top five firms hold a meaningful portion of market value—creates opportunities for bolt-on acquisitions, carve-outs and strategic alliances that can rapidly improve scale and channel access.
- Operational resilience: Supply chain disruption and commodity movement (stainless steel, copper) require firms to re-evaluate sourcing strategies, inventory posture and pricing architecture now to stabilize margins in 2026.
Market trajectory in plain terms
Our base-year calibration (2025) and the historical series (2020–2025) reveal consistent expansion following brief mid-period softening. The dataset indicates recovery and renewed momentum into 2026 and beyond, culminating in a material increase by 2032 under our central case. The 4.28% CAGR we model for the forecast window reflects a balance of steady demand from residential retrofit programs, increased specification in commercial builds, and growth in multi-story plumbing systems where surge-mitigation is mission-critical.
Water Hammer Arrestors Market
Drivers, constraints and inflection points
- Drivers
- Regulatory and code enforcement: certification standards and clearer installation mandates are driving specification-first purchasing and creating a premium for compliant, third-party certified arrestors.
- Product ergonomics and install-time optimization: innovations such as compact mini-arrestors, push-fit connections and integrated smart plumbing solutions reduce labor and retrofit costs—accelerating adoption in constrained spaces.
- Urbanization and multi-dwelling construction: taller, denser buildings increase the technical need for engineered surge control in central risers and distribution mains.
- Constraints
- Material and manufacturing volatility: stainless steel and copper cost swings, coupled with capacity bottlenecks, can compress margins and slow time-to-market for new SKUs.
- Installer preference and legacy systems: long-standing plumbing practices and installed-base inertia slow the pace of replacement demand unless clear labor and cost advantages are demonstrated.
- Inflection points to watch in 2026
- Broader code updates or national adoptions of PDI/ANSI standards that tighten installation and performance expectations.
- Major OEM product introductions or channel partnerships (e.g., smart-home integrators) that re-shape specification behavior.
Competitive landscape — who matters and why
The market remains characterized by a handful of established engineering-led suppliers that control distribution and specification channels. Our analysis highlights several incumbent strengths that buyers and investors should consider when benchmarking partners or targets:
Water Hammer Arrestors Market
- Watts (North Andover, MA, USA) — A long-standing player with a broad residential and commercial portfolio. Recent compact offerings demonstrate a focus on installation ease and compliance with lead-free mandates.
- Sioux Chief Manufacturing Company (Sioux Falls, SD, USA) — Known for made-in-USA positioning and product families that emphasize residential compatibility and straightforward retrofits.
- Zurn (Erie, PA, USA) — Positioned on engineered solutions for commercial and municipal projects, with advanced piston technologies for precise performance in demanding applications.
- Oatey (Cincinnati, OH, USA) — Focused on quieting solutions and, more recently, collaborations toward integrated smart plumbing systems to serve connected-building segments.
- Jay R. Smith Manufacturing Co. (Montgomery, AL, USA) — Broad SKU depth across piston and Hydrotrol types, with stainless and copper casing expertise for varied environments.
- Precision Plumbing Products (Oregon, USA) — Noted for PDI-compliant, system-rated products tailored to installer preferences in both new-build and retrofit contexts.
- BERMAD (Israel) — Supplier focus on pressure-surge mitigation for multi-story and high-rise structures, often engaged on engineering-led projects.
These profiles matter because they reveal where capability and channel control exist: Watts and Zurn for broad specification work in commercial builds; Sioux Chief and Precision for OEM-to-installer relationships; BERMAD for engineered system integrators.
Recent product moves worth noting
- Watts (Mar 2025) — Introduced a compact mini-series to fit constrained residential spaces and reduce install time; a direct play for retrofit demand.
- Oatey (Feb 2025) — Launched integrated arrestor solutions via partnership with a major automation partner, signaling convergence between plumbing hardware and smart-building systems.
- Zurn Elkay (Jan 2025) — Rolled out push-fit mini arrestors aimed at simplifying installation in both new-build and retrofit projects.
These launches underscore the industry’s push toward installers-first design, reduced labor time, and smart-system compatibility—key battlegrounds for share gain in 2026.
What the full PW Consulting report delivers (practical takeaways)
Our full report goes well beyond headline trends to provide operationally usable intelligence, including:
- Proprietary market-sizing and validated forecasts (2020–2032) with scenario analysis for commodity shocks and accelerated code adoption.
- Competitive benchmarking across product performance, channel strength, manufacturing footprint and R&D trajectories.
- Go-to-market playbooks tailored by buyer persona (distributors, specifiers, contractors) and installation archetype.
- Price-sensitivity and margin modelling under alternative raw-material and labor-cost assumptions.
- M&A and partnership target shortlists, supported by integration risk matrices and expected synergy realization timelines.
- Supply-chain stress-testing and alternative sourcing strategies to protect lead times and margin.
- Regulatory impact assessment tied to PDI and ANSI/ASSE compliance scenarios and code adoption timelines.
To uphold the “trailer” purpose of this release, we intentionally omit the granular regional, type and application-level revenue tables from this preview. Those detailed segment metrics—critical for tactical decisions such as SKU rationalization, regional sales targets and capex planning—are included in the full report and supporting datasets.
Strategic imperatives for executives and investors in 2026
- Prioritize installer ergonomics: Invest in product features that demonstrably reduce install time and rework. Our field economics show reduced labor time correlates directly to specification uptake in retrofit markets.
- Accelerate compliance-first productization: Ensure PDI and ANSI/ASSE certifications are baked into product development timelines. Certification accelerates inclusion in spec packages and municipal procurement.
- Hedge material exposure: Implement dual-sourcing strategies and evaluate hedging options for key commodities. Thin margins in commodity-sensitive SKUs demand proactive procurement strategies.
- Explore smart plumbing adjacency: Assess partnerships or pilot integrations with building-automation platforms—early movers can capture higher-value system-level contracts.
- Deploy M&A selectively: Target acquisitions that add channel depth (distributors, trade-focused OEMs) or specialized engineered capabilities for commercial and multi-story applications rather than broad product line extensions alone.
Key indicators we will be watching in 2026
- Adoption rate of certified products in municipal and large commercial specifications.
- Frequency and scale of product launches that materially lower installation time (e.g., push-fit, compact designs).
- Raw-material price trajectories for stainless steel and copper, combined with lead-time variance in manufacturing hubs.
- Partnership activity between hardware suppliers and smart-building integrators.
- M&A activity among the top players and regional consolidators—changes here will alter concentration and distribution economics.
Conclusion and next steps
The Water Hammer Arrestors market is entering a phase where product ergonomics, compliance and strategic sourcing will determine winners. Our analysis, grounded in historical performance and forward-looking scenario modeling, shows clear paths to value creation for manufacturers, distributors and investors—but execution must begin in 2026 to compound benefits over the forecast horizon.
For the complete dataset, granular segment tables, and the full set of strategic playbooks and M&A shortlists, access the full PW Consulting Water Hammer Arrestors Market report and supporting spreadsheets. The detailed intelligence contained there is designed to move leaders from insight to implementation—swiftly and with measured risk.
For detailed analysis of this topic, please visit the official page: Water Hammer Arrestors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Helicopter Simulator Market to Climb from USD 215.0 Million in 2025 to USD 344.8 Million by 2032 at 6.98% CAGR
By pmarketresearch, 2026-06-30
Helicopter Simulator Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
Executive snapshot
PW Consulting’s latest Helicopter Simulator Market report (base year 2025) synthesizes five years of historic performance (2020–2025) with a detailed outlook through 2032. The market has expanded materially since 2020 and is projected to continue growing at a compounded annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast window. From a strategic planning perspective, this trajectory transforms simulator programs from niche cost centers into scalable training and sustainment platforms that materially affect fleet readiness, instructor staffing models, and supplier selection across civil and defense operators.
Helicopter Simulator Market
Why this report matters for 2026 decision-makers
-
Timing: 2026 is an inflection year. Regulatory shifts, rapid adoption of mixed-reality technologies, and supplier consolidation are converging to create first-mover advantages for operators and vendors who align procurement, certification, and commercial models now.
Helicopter Simulator Market -
Risk-to-opportunity translation: The market’s steady growth trajectory—built on a resilient base established during the previous five years—means decisions made in 2026 about simulator type, certification pathways, and support contracts will influence total cost of ownership and training throughput for the next decade.
Helicopter Simulator Market -
Strategic clarity: For C-suite and operational leaders, the report converts macro growth and competitive dynamics into actionable priorities—procurement timing, technology partnerships, and aftermarket strategies—that preserve optionality while capturing upside from digitalization.
What the report contains (practical, actionable deliverables)
-
Market sizing and forecast: A validated topline series covering 2020–2032, with scenario-based forecasts to stress-test growth assumptions under differing regulatory and technology adoption paths.
-
Demand modelling toolkit: Customizable templates for operators to estimate training demand, simulator seat-hours, instructor staffing and break-even timelines under multiple fleet and utilization scenarios.
-
Certification and regulatory playbooks: Step-by-step guidance on contemporary FAA/EASA pathways, risk mitigations for cancelled or evolving advisory circulars, and a checklist for mixed-reality pre-qualification.
-
Supplier evaluation matrix: Rigorous comparative assessment criteria—technical fidelity, maintainability, upgradeability, IP and software openness, delivery lead times, and aftermarket economics—that buyers can deploy immediately.
-
M&A and partnership maps: Target profiles and diligence checklists for strategic acquisitions, minority investments, and OEM-operator JV structures to accelerate capability acquisition.
-
Commercial templates: Negotiable contract language, service-level benchmarks, and TCO calculators designed for procurement teams to secure predictable lifecycle costs and performance guarantees.
Market dynamics and what’s driving growth
The overall simulator market has shown robust expansion from its 2020 base, with an accelerated pace through 2024–2025 and sustained momentum into the forecast period. The drivers are multifold:
-
Technology substitution: Mixed-reality and high-fidelity visual systems are reducing the marginal cost of scenario complexity and enabling faster certification pathways for certain training objectives.
-
Operator economics: Rising real-flight costs and crew availability pressures are increasing the share of training conducted in simulators, while operators seek scalable, on-site training solutions.
-
Defense and security demand: Modern doctrines emphasizing realistic mission rehearsal have increased investments in mission-specific simulation capabilities.
-
Aftermarket service growth: With higher installed bases and longer lifecycle expectations, service revenues—updates, motion platform maintenance, and scenario libraries—are an expanding value pool for suppliers.
Regulatory & standards landscape — implications for 2026
-
Regulatory flux brings both risk and opportunity. The cancellation of FAA AC 120-63 in April 2026 alters the certification environment for some helicopter simulators, introducing uncertainty for certain device qualification routes but also opening space for manufacturers to propose alternate compliance regimes. Our report provides a navigation map for operators and vendors to re-scope certification programs, reduce rework risk, and accelerate deployment.
-
EASA’s Special Conditions framework and national pre-qualifications are emerging as practical accelerators for mixed-reality solutions; recent pre-qualifications and device pre-approvals demonstrate viable templates to follow.
Competitive landscape — players to watch and strategic moves
The market displays a concentrated supplier structure: the top three companies control a meaningful share of industry revenues, and the top five capture an even larger portion. This concentration creates differentiated routes to scale—either by partnering with established integrators or by targeting underserved niches with modular, lower-cost offerings.
-
CAE Inc. (Montreal): A dominant provider of full-flight devices and Level D-capable platforms, CAE’s portfolio and global service network make it a primary partner for large airlines, OEMs and defense customers. Strategic implication: CAE remains the go-to for turnkey, high-fidelity programs but can be expensive for mid-market operators seeking rapid deployment.
-
Frasca International (Urbana, IL): With a broad line of FTDs, AATDs and CPTS, Frasca is positioned to capture training center and flight school demand that prioritizes cost-effectiveness and reliability. Strategic implication: Frasca is a logical partner for scale-focused operators and regional training networks.
-
ELITE Simulation Solutions (Zurich): Known for FAA- and EASA-certified TH-125 and AS355 models, ELITE’s recent delivery and commissioning of an FAA-certified TH-125 for a law-enforcement unit underscores its operational focus and credibility in public safety markets.
-
Reiser Simulation and Training GmbH (Germany): A leader in mixed-reality integration, Reiser’s pre-qualification of the H145 D3 demonstrates the viability of high-fidelity XR solutions under EASA frameworks.
-
Ryan Aerospace (Gold Coast): By launching an affordable Robinson mixed-reality simulator, Ryan targets the professional training segment with a disruptive price-performance proposition.
-
TRU Simulation + Training (South Carolina) and Helisim GmbH (Germany): TRU’s close alignment with specific OEM platforms, and Helisim’s pre-qualification work for large twin-engine models, make both key partners for OEM-endorsed training ecosystems.
Recent market moves—product launches, certification milestones and localized deliveries—signal that suppliers are diversifying go-to-market approaches: OEM-aligned high-end devices, lower-cost XR-based solutions, and dedicated public-safety and regional operator offerings. The report decodes these tactics into playbooks for both buyers and investors.
Strategic imperatives for 2026
-
Prioritize certification-aligned procurement: Map procurement timelines to certification windows rather than catalog lead times. The cancellation of certain advisory guidance means certification strategy must be an early input to RFPs.
-
Adopt hybrid deployment models: Combine fixed-base simulators for core type-rating activities with mixed-reality units for recurrent and mission-specific training to optimize capital intensity and utilization.
-
Lock in service agreements with clear upgrade paths: Given the value of scenario libraries and software updates, negotiate multiyear, outcome-based SLAs that include upgrade credits and predictable refresh cycles.
-
Invest in instructor competence and digital curriculum: Simulation ROI compounds when paired with optimized curriculum and instructor training—investing in both reduces seat-hour inflation and shortens qualification timelines.
-
Explore consortium approaches for distributed training: Regional operators can pool demand to justify higher-fidelity devices while keeping per-operator costs manageable.
-
Embed simulation strategy into fleet acquisition and sustainment planning: Decisions about aircraft variants, avionics suites, and mission modules should consider simulator compatibility and lifecycle support.
How PW Consulting’s report accelerates execution
Beyond market maps and competitive profiles, our report equips executives with operational tools: customizable demand models, procurement templates, certification roadmaps, and a prioritized list of vendor diligence questions. For private equity and corporate development teams, we provide an M&A playbook that identifies thinly served niches and value-creation levers—service expansion, software monetization, and geographic channel development—that have the highest projected IRR given market growth and concentration dynamics.
Conclusion — decision-ready intelligence for 2026
As the helicopter simulator market transitions from tactical displacement to strategic capability, 2026 will be a decisive year for those who align procurement, certification and commercial models with emergent technology and regulatory realities. With an industry CAGR of 6.98% underpinning continued expansion through 2032 and a market structure where the top vendors hold meaningful share, the winners will be those who convert macro growth into repeatable, service-driven revenue streams while de-risking certification and delivery timelines.
To access the full dataset, regional and application-level segmentation, proprietary vendor scoring, and the suite of decision-support tools described here, visit our official report page. The report intentionally preserves certain granular segment outputs for subscribers—ensuring you receive the depth required to execute with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Helicopter Simulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Eddy Current NDT Equipment Market to Reach USD 846.7 Million by 2032, Growing at a 7.12% CAGR
By pmarketresearch, 2026-06-30
Eddy Current NDT Equipment Market: Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market research briefing on the Eddy Current Non-Destructive Testing (NDT) Equipment market synthesizes proprietary data, field interviews, and advanced scenario modeling to provide a decision-grade vantage point as corporate leaders set budgets, partnerships, and technology roadmaps for 2026. This preview highlights the report’s strategic value without disclosing the granular segment allocations—crafted intentionally to demonstrate analytical depth while directing executives and investment teams to the full report for transaction-ready detail.
Eddy Current NDT Equipment Market
Market Snapshot — Growth Trajectory and What It Means
The eddy current NDT equipment market has demonstrated steady expansion through the early 2020s and PW Consulting’s base-year assessment (2025) places the global market at USD 521.4 Million. Our forecast horizon (2026–2032) anticipates continued acceleration, with the market projected to reach approximately USD 846.7 Million by 2032, reflecting a compound annual growth rate (CAGR) of 7.12% over the forecast period. The 2026 projection sits notably ahead of 2025, signaling an inflection point for procurement cycles, capex allocation, and product development prioritization.
Eddy Current NDT Equipment Market
For corporate strategists, this macro trajectory matters for three reasons: (1) predictable scale allows larger OEMs and service firms to underwrite multi-year R&D and platform investments, (2) the rate of growth supports new business models—rental-as-a-service, condition-based inspection contracts, and integrated digital services—and (3) market momentum reduces exit risk for strategic M&A but raises the bar for transformational acquisitions.
Eddy Current NDT Equipment Market
Report Contents — Practical, Transaction-Ready Intelligence
- Robust Market Sizing & Methodology: Transparent bottom-up and top-down reconciliations with our base year anchored in 2025. Readers will find reproducible assumptions and sensitivity levers for adapting the model to bespoke use cases.
- Scenario & Stress Testing: Three forward-looking market scenarios (base, accelerated adoption, and constrained investment) that quantify revenue, margin, and CAPEX implications across short and long horizons.
- Technology Roadmaps: Comparative analysis of probe architectures, array and pulsed techniques, and software-enabled analytics—aligned to time-to-market and R&D investment profiles.
- Commercial Playbooks: Go-to-market segmentation, pricing elasticity matrices, channel strategies for rental vs. capital sales, and service contract templates for extended warranty and data services.
- Supplier & Buyer Intelligence: Verified supplier profiles, buyer persona mapping across aerospace, energy, and heavy industry, and procurement checklists to accelerate RFQ responses and vendor selection.
- M&A & Partnership Dossiers: Investment filters, synergy estimators, and target shortlists informed by our competitive and capability gap analyses.
- Regulatory & Standards Tracker: Compliance impact checklists—particularly for aerospace and nuclear applications—updated to reflect the latest validations and enforcement trends through 2025.
Each module is designed to be operational: slide-ready charts, downloadable data tables, and a compact executive decision memo template that executives can adapt directly for board and investment committee use.
Competitive Landscape — Leaders, Challengers and Where Value Hides
The vendor environment is characterized by a mix of established OEMs, focused specialty players, and service-oriented providers. Market concentration metrics indicate a moderately consolidated sector: the top three players command roughly 45% of market revenue and the top five capture close to 59%. This structure creates both defensive moats for incumbents and identifiable windows for niche entrants.
- Olympus Corporation (Tokyo, Japan): Strong in portable high-frequency systems for aerospace; incumbency in handheld units and a broad service footprint make Olympus a reference customer for airlines and MROs. Their continued product evolution keeps them central in aerospace inspection cycles.
- Zetec, Inc. (Snoqualmie, WA, USA): Deeply positioned in nuclear and power generation markets with integrated robotics and array systems—Zetec’s strength is in high-value service contracts and deployment of automated inspection solutions.
- Eddyfi Technologies (Quebec City, Canada): Known for advanced array and electromagnetic testing platforms, Eddyfi leads in high-resolution analytics and is often first-to-market for niche industrial use-cases requiring sophisticated defect characterization.
- Mid-sized specialists (Magnetic Analysis Corporation, ETher NDE, Rohmann, Institut Dr. Foerster, UniWest, Criterion, ibg NDT, Ashtead Technology, IMG ULTRASUONI): These firms collectively provide depth—probe design, inline solutions, rental and service models, and regionally dominant channel relationships. Their agility often makes them attractive targets for bolt-on acquisition by larger OEMs or private-equity platforms seeking volume or technology augmentation.
Recent strategic moves underscore the dynamic competitive environment: product launches across portable and array platforms in 2025, an acquisition expanding global footprints, and strong event activity leading into ECNDT 2026. These developments validate that incumbents continue to invest in product refreshes while also pursuing inorganic routes to shore up capabilities.
Technology & Adoption Dynamics — Signals to Monitor in 2026
- Digital Array Probe Adoption: Installations surged in 2025, reflecting a broader shift toward data-rich inspections and automated analysis. This adoption accelerates demand for integrated software and storage services, creating recurring revenue opportunities.
- Wireless & Connected Inspections: Wireless eddy current solutions recorded markedly higher adoption in 2025. Connectivity opens pathway to remote diagnostics, federated data models, and condition-based maintenance (CBM) offerings.
- Product Refreshes & Modular Platforms: Multiple vendors launched next-gen instruments in 2025—emphasizing portability, frequency range, and AI-assisted defect detection. Buyers should expect a compressing product lifecycle and a growing aftermarket for software updates and probe upgrades.
For R&D planning, these signals mean prioritizing software-enabled differentiation, cloud/edge data integration, and modular product architectures that support upgrades rather than full replacements—improving customer retention and lifetime value.
Regulatory & Standards Environment — Operational Risk and Opportunity
Standards bodies and industry validations continue to shape adoption. Notable developments include certification validations of eddy current techniques for aged nuclear assets (2025) and ongoing enforcement by bodies such as ASNT for aerospace and nuclear inspections. ECNDT 2026 remains a focal point for protocol updates and cross-industry harmonization. For compliance-driven buyers and suppliers, staying ahead of standards is not a cost-center but a market-access enabler.
Strategic Imperatives for 2026 Decision-Making
- For OEMs: Accelerate investment in digital analytics and probe modularity. Prioritize SaaS-enabled service tiers and subscription models for higher-margin recurring revenue.
- For Service Providers & Rentals: Expand asset-light rental fleets with remote monitoring capabilities; bundle inspections with analytics and trend reporting to capture downstream service economics.
- For Buyers (Aerospace, Energy, Manufacturing): Redesign procurement frameworks to favor total cost of ownership (TCO) evaluations that include software, upgrades, and data services—not just initial CAPEX.
- For Investors & Dealmakers: Target bolt-on acquisition candidates that fill capability gaps in array technologies, software analytics, or regional service coverage; use concentration dynamics to assess consolidation upside.
- For R&D Leaders: De-risk roadmaps by investing in adaptable platforms that address both pulsed and array use-cases and by building partnerships for AI-driven defect characterization.
Why PW Consulting’s Report Matters for 2026
Decision-makers told us they need three deliverables going into 2026: credible market sizing, scenario-planning with clear financial implications, and a tactical playbook for execution. Our report delivers each. It integrates the 2025 base-year reality with a forward model (2026–2032) that incorporates a 7.12% CAGR and multiple adoption pathways—allowing executives to stress-test budgets, prioritize capital allocation, and quantify strategic options such as entering new verticals, launching subscription services, or executing roll-up strategies.
The report packages actionable outputs—supplier heat maps, prioritized R&D roadmaps, M&A scorecards, and a regulatory impact matrix—so that teams can move from insight to investment in weeks, not months.
Next Steps
This preview outlines the strategic contours but intentionally omits the segment-level splits and targetable figures that trading, procurement, and M&A teams require to act. For access to the full data tables, scenario models, and vendor-level financial analytics that are essential for transaction execution and 2026 planning, consult the complete PW Consulting Eddy Current NDT Equipment Market report.
Contact PW Consulting to license the full report, request a briefing with our lead analyst, or commission a bespoke deep-dive tailored to your organization’s strategic questions.
For detailed analysis of this topic, please visit the official page: Eddy Current NDT Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com