

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hook-and-Loop Fasteners Market Poised for 5.3% CAGR, Says PW Consulting

Hook-and-Loop Fasteners Market: 2026 Strategic Brief — Why PW Consulting’s New Report Will Shape Your Decisions This Year
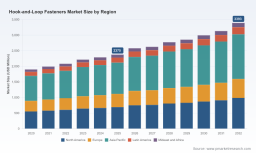
As companies recalibrate procurement, manufacturing footprints, and product roadmaps for 2026, the hook-and-loop fasteners market is moving from steady supply to strategic determinant. PW Consulting’s latest market report — with a 2025 base year, a five‑year historical window (2020–2025) and a 2026–2032 forecast horizon — quantifies that transition. The market expanded from roughly USD 1.9 billion in 2020 to about USD 2.375 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.3% through the forecast period, reaching north of USD 3.3 billion by 2032. That trajectory underpins why procurement, R&D, M&A and regulatory teams should treat hook‑and‑loop strategy as an active, cross‑functional priority in 2026.
Hook-and-Loop Fasteners Market
What the report delivers — practical intelligence, not platitudes
-
Proven, auditable market sizing and a transparent forecasting engine calibrated to a 2025 base year and historical data through 2020–2025, enabling stress‑tested scenarios for 2026 decisions.
Hook-and-Loop Fasteners Market -
Demand-driver decomposition and a supply‑side heat map that links end‑market dynamics (e.g., footwear, transportation, medical, industrial) to volume and pricing pressures without oversimplified assumptions.
Hook-and-Loop Fasteners Market -
Competitive and concentration diagnostics (the market shows clear consolidation dynamics), including a CR3/CR5 concentration view that explains where pricing power and margin pools lie.
-
Company dossiers with strategic positioning and capability matrices for the leading global suppliers, plus an M&A and partnership tracker that captures recent transactions and legal developments.
-
Supply‑chain risk assessments and sourcing playbooks, covering raw‑material volatility, manufacturing footprint tradeoffs, contract design and contingency options for 2026 procurement cycles.
-
Regulatory and standards compendium (medical certifications, trade policy headwinds, IP and tax rulings) and a checklist to convert compliance into commercial advantage.
-
Actionable tools: downloadable Excel models, scenario dashboards, supplier scorecards and negotiation scripts that your commercial and operations teams can deploy immediately.
Why this report is strategically valuable for 2026
Three practical realities make a focused hook‑and‑loop strategy urgent in 2026. First, incremental revenue growth is modest but durable — the market’s mid‑single‑digit CAGR translates to material margin opportunity when players optimize sourcing and product mix. Second, the competitive landscape is concentrated: a small constellation of global suppliers exert meaningful influence on price-setting, innovation cadence and certification availability, creating both risk and arbitrage for challengers and incumbents. Third, trade and regulatory developments in early 2026 have changed the calculus for onshore vs. offshore production and the design of contracts for cross‑border royalty and tax exposure.
For executives weighing capital allocation in 2026, this report converts general trends into decision‑grade inputs. Procurement teams receive supplier risk scores and cost‑to‑requalify estimates; corporate development teams get valuation sensitivities tied to concentration and product differentiation; regulatory and tax teams find timelines and likely outcomes for disputes and rulings that can affect royalty flows and transfer pricing.
Competitive dynamics — who matters and why
-
VELCRO Companies: the globally recognized brand and innovation engine. Its recent majority‑stake transaction in 2026 signals renewed private‑equity appetite for platform assets with durable aftermarket and industrial demand. Buyers and partners should re‑price partnership and licensing negotiations in light of the new ownership and capital strategy.
-
3M: leverages adhesive and assembly know‑how to compete on integrated solutions. Its strengths are materials science and channel reach; strategy teams should assess where bonding systems and reclosable technology create bundling opportunities or margin pressure.
-
APLIX and YKK: specialized product portfolios and manufacturing diversity make them natural collaborators for customers seeking tailored fasteners and extruded hook alternatives. Their R&D pipelines merit monitoring for niche performance breakthroughs (e.g., high‑cycle, non‑lint, biodegradable substrates).
-
Halco and Kuraray: high‑certification and specialty product capabilities matter to medical and defense customers. Halco’s ISO 13485 and ISO 10993‑5 compliance is a strategic enabler for medical OEMs seeking validated fasteners; companies evaluating entry into medical segments must budget for certification timelines and cost.
-
Regional manufacturers and specialists: a broad base of suppliers remains competitive on cost, customization and lead time. For commercial teams, the arbitrage between branded incumbents and nimble suppliers presents negotiation leverage, but also supplier risk if demand shifts rapidly.
Recent developments that should alter 2026 plans
-
Strategic ownership change at a leading brand (May 2026) — a private‑equity acquisition shifted capital priorities and M&A appetite at a market leader, creating window opportunities for bolt‑on consolidation or supplier agreements.
-
Legal rulings in early 2026 affecting royalty tax treatment — these create short‑term earnings and cash‑flow implications for companies with cross‑border licensing structures; tax and treasury teams should review treaty positions and withholding exposure.
-
Trade‑policy changes in February 2026 (an executive order ending certain additional duties) — while not a wholesale policy reset, it alters landed cost math for imports and should be modeled into 2026 sourcing optimization.
-
Market presence signals (trade‑show participation and product showcases) — suppliers continue to invest in differentiated fastener formats and adhesive systems; product teams should fast‑track compatibility testing for next‑generation assemblies.
Regulatory, quality and supply‑chain implications
Regulation, standards and certification are operational constraints — and potential commercial assets. Medical and defense segments reward vendors that meet ISO and biocompatibility standards; suppliers that are already certified hold pricing power in those channels. Meanwhile, trade policy permutations in early 2026 have reduced some tariff overhangs but left other emergency duties intact, creating a dynamic costing environment. Companies should therefore treat supply‑chain decisions as scenario‑based: evaluate the marginal benefit of onshore capacity versus the fixed cost of certification and long‑lead capital — and embed trade and tax scenario outputs into supplier selection criteria.
Five targeted, high‑impact recommendations for 2026
-
Re‑run supplier TCO with 2026 policy scenarios: incorporate revised duty assumptions, potential withholding tax exposures and the cost/time to requalify alternate suppliers.
-
Prioritize product differentiation where certification matters: accelerate investments in non‑lint, high‑cycle and biocompatible variants for medical and high‑performance industrial clients, and budget certification timelines into product launch plans.
-
Use market concentration to negotiate value: where a few suppliers dominate, structure multi‑year volume commitments with performance incentives rather than single‑factor price concessions to preserve innovation incentives.
-
Pursue opportunistic M&A and JV strategies: M&A activity among brand leaders and private investors opens windows for scale buys or technology access — conduct rapid but rigorous diligence on IP, royalty structures and compliance risk.
-
Operationalize sustainability and circularity as commercial differentiators: recycled‑content offerings and documented ESG performance increasingly move beyond compliance to procurement requirements in automotive, medical and institutional buyers.
How PW Consulting de‑risks your 2026 choices
Our report is built to be executable. Beyond narrative insight, subscribers receive a calibrated forecasting model, sensitivity analyses tied to tariff, currency, and raw‑material shocks, plus supplier scorecards and negotiation playbooks that translate market dynamics into contract clauses and KPI thresholds. For legal and tax teams, we map litigation and ruling timelines so that treasury and transfer‑pricing strategies can be stress‑tested against plausible outcomes. For commercial teams, we provide channel‑level demand elasticity proxies and price‑pack architecture recommendations to protect margin during price renegotiations or product upgrades.
Closing — the decision test for 2026
In 2026, the hook‑and‑loop fasteners market will reward organizations that shift from a transactional viewpoint — price and lead time — to a strategic lens that marries product capability, certification, supply resilience and regulatory foresight. PW Consulting’s report supplies the quantitative backbone and the tactical playbooks that allow leadership teams to convert market growth and concentration into durable margin and reduced operational risk.
To preserve the value of this preview (and to align with our “trailer” principle), core segment‑level tables, price curves and supplier‑specific revenue splits are omitted here and available in the full report and data pack. For the complete dataset, downloadable models, and to book a briefing with PW Consulting’s head analysts, visit our report page or contact our industry leads. Equip your 2026 plans with decision‑grade intelligence — the margin and timing differences are material.
For detailed analysis of this topic, please visit the official page: Hook-and-Loop Fasteners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com