

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Shrimp market to reach USD 109.0 Billion by 2032, growing at a 5.5% CAGR (2026–2032) as Asia‑Pacific commands ~38.5% share

Shrimp Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Report
Executive summary
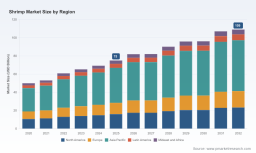
As global seafood markets recalibrate around new trade rules, higher cost structures and evolving consumer preferences, shrimp remains a bellwether commodity for supply-chain transformation and margin recovery. PW Consulting’s Shrimp Market report (base year 2025; historical review 2020–2025; forecast 2026–2032) quantifies that transformation: the industry expanded from roughly USD 50 billion in 2020 to USD 75 billion in 2025 and is projected to exceed USD 80 billion in 2026 under a baseline compound annual growth rate (CAGR) of 5.5%. Under the baseline scenario our modelling takes through 2032, market size approaches the low triple‑digit billions mark.
Shrimp Market
This release is written as a strategic briefing for executives making capital, procurement, channel and regulatory-compliance decisions in 2026. It highlights where value is materializing, where risks are concentrating, and what immediate actions leaders should prioritize. The full report, including granular regional, application and product splits, supply-cost curves and downloadable modelling workbooks, is available on our client portal.
Shrimp Market
Why the 2026 inflection matters
-
Regulatory tightening in key import markets has re-specified acceptable supply chains and verification standards, materially changing trade routes and sourcing costs.
Shrimp Market -
Commodity cost inflation and logistics volatility continue to pressure conventional margin structures; firms with advanced cost-to-serve analytics and adaptive sourcing strategies are already outperforming peers.
-
Consumption patterns are segmenting—retail and foodservice channels are each evolving under different value propositions (convenience, provenance, ready-to-eat formats)—creating differentiated pricing and product innovation opportunities.
Core findings with strategic relevance (what we reveal vs. what the report holds back)
-
Market momentum: After robust recovery through 2025, the shrimp market enters 2026 from a position of measured expansion. Our baseline forecast embeds a 5.5% CAGR across 2026–2032 and stress-tested scenarios for weaker global demand and for accelerated premiumization.
-
Structure and concentration: The market remains moderately fragmented. In aggregate, the top-tier suppliers do not dominate single-handedly; commercial advantage is created through integrated processing, branded value-added products and differentiated channel access.
-
Volatility drivers: Cost pressures (feed, labour, energy), trade policy, and inspection regimes are the primary near-term drivers of supply dislocation. Our scenario matrix shows that supply shocks aligned with regulatory actions create outsized short-term price moves and re-route volumes for up to 12–18 months.
-
Where we hold back: This briefing intentionally omits the detailed regional, type and application percentage splits, transactional price ladders and company-level segment revenues contained in the full report—those datasets are the strategic assets that will inform supplier negotiations, M&A screens and procurement hedging strategies.
Operational playbook for 2026 decisions
-
Immediate (0–6 months): Implement a supplier-risk triage that integrates regulatory-compliance scoring, certificate-of-origin validation and logistics‑time-to‑market exposure. For companies exposed to North American retail channels, prioritize suppliers with verified inspection pathways under the new comparability regimes.
-
Near term (6–18 months): Reprice channel economics using a cost-to-serve model that differentiates frozen vs. fresh throughput, ready-to-eat conversions and value-added processing. Push pilots for new frozen-format packaging and SKU rationalization in high-turn retail accounts.
-
Strategic (18+ months): Decide on vertical moves—selective investment in processing capacity, traceability systems, or a targeted M&A to secure farm-to-processor integration. Use our M&A heatmap (in the full report) to benchmark premium multiples by geography and capacity vintage.
Regulatory landscape and trade dynamics
-
Inspection and comparability rulings: Recent determinations by major importing authorities have tightened acceptable origins for shrimp imports. Importers and distributors who lack rapid compliance documentation face shipment holds and potential market access reductions.
-
Legislative shifts: Bills introduced in import markets that harmonize domestic inspection standards with import controls increase the cost of entry for suppliers that cannot certify to higher standards. Procurement teams must build regulatory contingency into sourcing contracts.
-
Product definitions: Updates to official seafood lists expand the set of regulated species and labelling requirements, with direct implications for product coding, tariff classification and shelf claims.
Competitive landscape: what leading firms are doing
We evaluated public and private players across the value chain—producers, processors, importers and branded distributors—and identified three repeatable strategic postures that correlate with resilience and margin improvement:
-
Integration and processing focus (example: Aqua Star, High Liner Foods). These firms are leveraging processing scale, frozen‑specialty competence and route-to-retail relationships to capture higher-margin, value-added SKUs.
-
Source-differentiation and traceability (example: Clearwater Seafoods, Wild Ocean Direct). Vertically-integrated wild-capture suppliers are positioning around provenance and sustainability claims to defend premium channels.
-
Distribution and market penetration (example: Mazzetta Company, Nordic Seafood, Surapon Foods). Importers and global distributors are optimizing inventory turns and leveraging long-standing trade networks; their near-term value depends on flexible logistics and rapid response to regulatory denials.
In practice, many market leaders combine these postures—backward integration, branded value-add and nimble distribution—to create differentiated offerings. The full report contains case studies and benchmarking tables detailing asset footprints, product portfolios and likely strategic moves for each named firm.
Recent market signals to monitor
-
Industry forums and trade shows continue to focus on China and larger Asian demand pools; these venues are where early shifts in consumer product mix and packaging innovations surface.
-
Market updates from trade analysts show persistent volatility in trade flows across major origins; buyers should maintain dynamic sourcing agreements and optionality on contracted volumes.
-
Product launches and commercial strategies from large exporters indicate a movement toward convenience and ready-to-eat formats—an axis that will shape shelf pricing and margin pools.
Risk and mitigation framework
Our report operationalizes risk into five quantifiable vectors—regulatory, supply, price, channel, and reputational—and maps mitigants aligned with investor and commercial timelines. Examples include:
-
Regulatory: Maintain dual-source approvals and invest in real-time certificate-of-origin verification tools.
-
Supply: Execute staged supplier diversification tied to performance KPIs rather than volume-only contracts.
-
Price: Embed flexible pricing corridors and index-linked clauses for feed and energy-related cost swings.
-
Channel: Pilot aggregated frozen-ready SKUs in retail to test demand elasticity without full SKU rollouts.
-
Reputational: Fund independent third-party audits and transparency dashboards for high-value retail accounts.
What the PW Consulting Shrimp Market report contains (operational table of contents)
-
Comprehensive market sizing and forecast (2020–2032) with baseline and stress scenarios.
-
Supplier and processing cost curves with unit-economics modelling.
-
Regulatory impact assessments and compliance playbooks for major importing jurisdictions.
-
Channel strategies for retail, foodservice and industrial demand—incl. go-to-market playbooks and SKU optimization templates.
-
Competitive intelligence dossiers on leading firms and an M&A heatmap showing target classes and valuation benchmarks.
-
Interactive Excel models and dashboards to test sourcing scenarios, price shocks and margin sensitivities.
Strategic recommendations for 2026
-
Prioritize compliance-driven sourcing: Tie new contracting to suppliers’ verifiable compliance status; delay capacity commitments where verification is uncertain.
-
Invest selectively in traceability: Low-cost traceability pilots deliver outsized ROI where access to regulated markets is conditional on provenance.
-
Adopt dynamic procurement: Move from static annual contracts to rolling contracts with volume-flex and price-index mechanisms to manage volatility.
-
Allocate R&D to convenience formats: Short-cycle investments in frozen and ready-to-eat formats can capture retail share shifts at modest incremental capex.
-
Use the PW M&A heatmap: For companies pursuing consolidation, prioritize targets that add processing capacity or verified supply chains rather than pure distribution reach alone.
Final note — the strategic value of the full dataset
For senior teams making allocation decisions in 2026, the value is not information per se, but actionable, model-led insight. PW Consulting’s full Shrimp Market report provides the raw datasets, regional and product splits, supply‑cost ladders and scenario workbooks you need to convert market intelligence into executable decisions. This briefing intentionally surfaces the strategic priorities and practical playbook while reserving the granular tables and deal-grade models for the full product—designed to be used directly in procurement negotiations, board-level planning and M&A diligence.
To access the full report, Excel models and bespoke advisory options, visit the PW Consulting Shrimp Market page or contact your client director. PW Consulting stands ready to support scenario testing, supplier rationalization and regulatory readiness planning for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Shrimp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com