

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mass Transfer (Distillation) Market to Expand at 6.98% CAGR (2026–2032), Rising from USD 1,549.0 Million in 2025 to USD 2,481.0 Million — North America, Column Internals and Petroleum Industrial Lead (CR3 58%, CR5 68%)

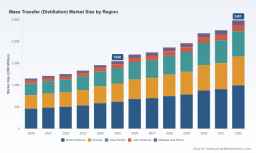
Mass Transfer (Distillation) Market: Strategic Signals for 2026 Decision-Making
Executive snapshot
As PW Consulting releases its Mass Transfer (Distillation) Market study, we present a focused briefing on the strategic implications senior executives must weigh in 2026. The market has expanded steadily from an estimated USD 1,150 million in 2020 to about USD 1,549 million in 2025, and PwC-style forecasting (2026–2032) points to continued expansion at a compound annual growth rate (CAGR) of approximately 6.98%. By the end of the forecast window, the market is expected to approach the mid‑billion-dollar range. Market concentration is meaningful but not monopolistic: the top three players account for roughly 58% of industry revenue while the top five reach about 68%, leaving room for specialist entrants and regional champions.
Mass Transfer (Distillation) Market
Why this report matters for 2026 planning
-
Macro clarity for capex allocation: Our sizing and trend analysis provide finance and strategy teams a defensible basis to prioritize capital investments in distillation assets, internals and energy‑efficiency retrofits during 2026 budget cycles.
Mass Transfer (Distillation) Market -
Procurement and vendor selection: The vendor landscape analysis, combined with scenario modeling for energy price swings and regulatory tightening, equips procurement with a shortlisting framework that balances performance, total cost of ownership (TCO) and supply resilience.
Mass Transfer (Distillation) Market -
Technology-roadmap alignment: Engineers and R&D leaders can benchmark investment timing for electrified and hybrid distillation solutions against adoption curves and commercial deployments captured in the report.
-
M&A and partnership targeting: Corporate development teams can use our concentration and capability overlays to identify bolt‑on targets and strategic alliances that accelerate entry into adjacent separation technologies.
Market dynamics: drivers, constraints, and inflection points
The distillation value chain is being reshaped by three intersecting forces: regulatory pressure, energy and sustainability imperatives, and technology innovation. Regulation remains a consistent driver—programs focused on solvent recovery and emissions control are increasingly enforced, prompting operators to upgrade or replace legacy distillation systems. For example, enhanced solvent recovery requirements under key air quality programs are driving demand for higher‑efficiency column internals and integrated recovery units.
On the energy and sustainability front, feedstock and fuel specifications continue to evolve (e.g., tighter sulfur limits and cleaner fuel mandates), creating technical demand for refined separation solutions and process optimization. Simultaneously, electrified distillation and other process electrification concepts—already in commercial pilots and early plant rollouts—offer a pathway to reduce indirect emissions and, in some cases, lower operating expense through improved thermal integration. These emergent technologies (including proprietary implementations from incumbent suppliers) are altering retrofit economics and lifecycle assessments.
Technological progress is visible across internals, packings and tray designs, with emphasis on improving mass transfer per unit pressure drop, increasing turndown capability, and easing maintenance. Incremental hardware advances are being complemented by digital optimization—advanced control strategies, model predictive control, and condition-based maintenance are materially extending asset life and performance.
Report coverage and practitioner tools
PW Consulting’s Mass Transfer (Distillation) Market report is designed as an operationally actionable toolkit for executives, plant managers and corporate strategists. Key inclusions:
-
Comprehensive market sizing and historical trend analysis (2020–2025 base) with forward projections to 2032, employing bottom‑up and top‑down triangulation methods.
-
Segmentation across product types, applications, and regions, coupled with scenario analyses that stress‑test demand under different regulatory and energy price pathways. (Note: our public summary hides detailed segment-level figures to protect the competitive integrity of the primary data set—subscribers can access full granular tables and dashboards on the report portal.)
-
Vendor profiles and capability matrices covering design, manufacturing footprint, aftermarket services and innovation pipelines.
-
Practical decision frameworks—capex prioritization templates, retrofit business‑case models, procurement scorecards and a tender playbook optimized for complex separation projects.
-
Supply‑chain risk heatmaps and contingency planning guidelines addressing critical raw material availability, manufacturing lead times and geopolitical exposures.
Competitive landscape: what incumbents are doing
The industry is shaped by well-established engineering suppliers and a cohort of specialized fabricators and service providers. Several players are noteworthy for their strategic positioning:
-
Sulzer Ltd (Winterthur, Switzerland) — Strengths: deep product portfolio in column internals, active R&D in energy‑saving technologies, and growing commercial traction for electrified distillation concepts. Recent company disclosures indicate robust 2025 results and a continued emphasis on distillation and absorption technologies, underlining Sulzer’s role as a technology leader and a bellwether for advanced separation adoption.
-
Koch‑Glitsch (Wichita, USA) — Strengths: global engineering reach, integrated tower internals and phase‑separation solutions, and a history of project delivery for large refining and petrochemical clients. Their toolset is frequently chosen where scale and complete‑scope responsibility are required.
-
RVT Process Equipment GmbH (Marktrodach, Germany) — Strengths: European fabrication excellence and custom internals and tray manufacturing, serving clients needing engineered, high‑precision internals with tight quality and delivery specifications.
-
De Dietrich Process Systems (Niederbronn, France) — Strengths: engineered columns, turnkey systems and strong presence in chemical processing applications. Their exhibition plans at chemicals trade events highlight ongoing efforts to showcase integrated process equipment and to deepen market visibility.
-
Chane Terminal Botlek B.V. (Rotterdam, Netherlands) — Strengths: terminal operator with project capabilities for petrochemical processing and toll distillation services. Recent expansion projects focused on sustainable aviation fuel capacity signal an operational pivot to renewable fuel processing and hub services.
-
Sepco Process Inc. (Conroe, Texas, USA) — Strengths: vendor of random packings and separation media with a focus on competitive pricing, aftermarket supply continuity and specialty packing solutions for retrofit and newbuild columns.
These incumbents illustrate a mix of technology leadership, regional manufacturing density and service depth. The CR3/CR5 concentration metrics cited earlier reflect a market where a few firms capture scale advantages while a long tail of specialists compete on niche performance, cost or local presence.
Strategic implications and recommended actions for 2026
-
Prioritize retrofits that deliver near‑term OPEX reductions: Use the report’s retrofit TCO models to rank candidate columns by payback under varying energy price and carbon cost scenarios. Focus on internals and packing upgrades with short payback horizons to de‑risk CAPEX.
-
Evaluate electrified distillation pilots selectively: For sites with constrained thermal integration or access to low‑carbon electricity, run structured pilots with clear performance KPIs. Use supplier partnerships to offload technical uncertainty and integrate learnings into a cross‑site deployment roadmap.
-
Embed regulatory forward‑scanning in project gating: Given tightening solvent recovery and emissions standards, ensure that new projects and major revamps include compliance thresholds that exceed current minimums to avoid stranded assets.
-
Leverage procurement playbooks to shorten supplier selection cycles: Apply the report’s scorecard to balance technical fit, delivery risk and aftermarket service terms—this is especially important given lead‑time volatility and the strategic nature of internals supply.
-
Scan M&A selectively: Identify small, high‑performance suppliers or service providers whose technology or market access would accelerate the buyer’s entry into high‑growth niches, while being mindful of integration complexity and dilution of focus.
Next steps and how to use this briefing
This briefing highlights the strategic vantage points PW Consulting’s full Mass Transfer (Distillation) Market report provides. Leaders preparing 2026 budgets should treat the report as both a diagnostic and an implementation playbook: it combines market sizing and competitive benchmarking with contract templates, retrofit calculators and scenario analyses calibrated to realistic regulatory and energy trajectories.
To preserve the competitive integrity of our primary research and to respect client confidentiality, this release intentionally omits detailed segment tables and region‑level allocations. Subscribers to the full report receive interactive dashboards, downloadable datasets and supplier scorecards that unlock those insights for transaction support, capital planning and engineering decision‑making.
Conclusion: signal or noise?
The mass transfer sector is transitioning from incremental hardware improvements to a phase where system‑level integration, electrification and regulatory alignment will determine winners and losers. Market scale is growing at a mid‑single‑digit CAGR, incumbents are reinforcing position through technology and project wins, and new‑generation solutions are beginning to shift the economic calculus for retrofits and newbuilds. For 2026, the most valuable decisions will be those that convert market visibility into prioritized, measurable pilot and retrofit programs—supported by disciplined procurement and an eye toward regulatory resilience.
For full access to the granular segment tables, company profiles, and the implementation toolkit referenced above, visit the PW Consulting report page to download the full Mass Transfer (Distillation) Market report and associated datasets.
For detailed analysis of this topic, please visit the official page: Mass Transfer (Distillation) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com