

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Safety Shut-off Valves for Gas Meters Market Poised to Rise from USD 215.0 Million in 2025 to USD 344.8 Million by 2032 at a 9.1% CAGR

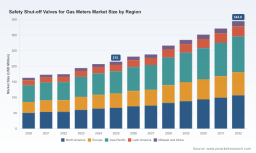
Safety Shut-off Valves for Gas Meters Market: Strategic Imperatives for 2026 — PW Consulting Snapshot
PW Consulting’s latest market study on Safety Shut-off Valves for Gas Meters (base year 2025, historical window 2020–2025, forecast period 2026–2032) provides an executive-level playbook for corporate decision-makers who must balance safety compliance, infrastructure modernization, and profitable growth. The market has expanded from roughly USD 163 million in 2020 to USD 215 million in 2025 and, under the report’s baseline scenario, is projected to reach approximately USD 345 million by 2032—reflecting a compounded annual growth rate (CAGR) of 9.1% across the 2026–2032 forecasting horizon.
Safety Shut-off Valves for Gas Meters Market
Why this report matters for 2026 corporate strategy
-
Regulatory acceleration: Building codes and state-level mandates (including recent earthquake-actuated and fire shut-off valve certification programs) are making integrated and certified shut-off solutions not only preferred but in many jurisdictions compulsory for new and replacement meter installs.
Safety Shut-off Valves for Gas Meters Market -
Smart-grid convergence: Utilities and meter OEMs are embedding shut-off functionality into smart metering platforms as a value-added safety capability that also serves operational and commercial purposes—leak mitigation, remote isolation, and automated incident response.
Safety Shut-off Valves for Gas Meters Market -
Risk transfer and insurance dynamics: Insurers and risk managers increasingly reward demonstrable automatic isolation and remote shut-off capabilities through reduced premiums and improved underwriting terms.
-
Commercial models evolving: The supply chain is shifting from pure hardware sales to integrated hardware-plus-services propositions (installation, calibration, data services, warranty extensions), opening new revenue streams but also complicating procurement.
Report scope — practical, decision-ready content (high level)
-
Validated market sizing and 7-year forecasting (2026–2032) with scenario analysis that isolates the impact of regulatory shocks, accelerated retrofit programs, and technology adoption curves.
-
Demand-driver decomposition and barrier mapping aligned to utility operator KPIs, building code timelines, and capex cycles.
-
Supplier landscape and capability heatmaps: product architectures, integration maturity, certification status, and go-to-market models (OEM, channel, systems integrator).
-
Commercial and technical due diligence checklists tailored for procurement, pilot programs, and M&A screening.
-
Deployment playbooks for residential, multi-family, commercial, and industrial rollouts—covering installation sequencing, telemetry integration, maintenance regimes, and retrofit constraints.
-
Financial toolkits including ROI calculators, lifecycle TCO models, and sensitivity analysis for component price volatility, installation labor rates, and regulatory phase-in schedules.
-
Risk matrices and mitigation plans covering performance failure modes, regulatory non-conformance, cybersecurity for remotely operated valves, and supply chain disruption scenarios.
Key strategic takeaways for executive decision-making
-
Prioritize integrated solutions where certification and remote-control capability materially reduce operational risk. In many municipal and utility contexts, the up-front premium for integrated shut-off valves is offset within a 3–5 year window through avoided incidents and insurance savings.
-
Design retrofit-first strategies that focus on high-risk building typologies and critical distribution nodes—these deliver the fastest risk reduction per dollar invested and create demonstrable ROI cases for broader programs.
-
Use procurement as a strategic lever: require interoperability and open telemetry standards in RFPs to avoid vendor lock-in and enable future analytics monetization.
-
Invest in field-service capability or partner with specialized integrators. The market is moving toward OPEX-friendly subscription models; capturing aftermarket services is essential to sustaining margins.
-
Embed regulatory monitoring into product roadmaps. Roadmap decisions—sensor fusion, actuator redundancy, self-diagnostic functionality—should be prioritized according to emerging certification requirements and local code changes.
-
Adopt a two-track M&A posture: (1) bolt-on components and valve-tech vendors that close functional gaps, and (2) systems integrators that accelerate route-to-market for retrofit programs.
Competitive landscape: what to watch
The competitive dynamic is defined by a mix of large metering OEMs embedding shut-off functionality and specialist valve suppliers focused on certification and compliance. Notable market participants include Itron and Honeywell’s American Meter (including the Elster product line), which have moved from offering valves as discrete components to delivering integrated meters with embedded shut-off logic and remote closure capability. Specialist vendors such as NSF Control play a critical role in compliance-focused designs and certification pathways.
-
Itron has demonstrated strong commercial traction and installed base momentum with its Intelis platform; recent disclosures indicate multi-million unit deployments and continued feature enhancements around automatic closure on high-flow, overpressure, or temperature excursions as well as remote shut-off. For strategy teams, Itron’s installed base represents both a benchmark for integration maturity and a competitive pressure point for incumbents and new entrants.
-
Honeywell (American Meter/Elster) continues to validate integrated shut-off approaches through pilots and government-supported demonstrations, positioning its AC-series meters as part of broader building safety projects. These demonstrations signal utility and regulatory interest in combining smart metering with automatic safety intervention.
-
Specialist suppliers such as NSF Control should not be underestimated: their compliance-focused offerings and relationships with certifying bodies make them sought-after partners for OEMs and utilities that must accelerate approvals across jurisdictions.
Regulatory and standards context — implications for 2026
Regulatory momentum is a primary demand lever. Examples include state-led certification programs for earthquake-actuated valves and local laws mandating thermal shut-off valves for new or replaced meters. These developments create predictable, near-term retrofit windows in many jurisdictions and drive procurement cycles among utilities, property owners, and municipal authorities. Strategy teams should map product certifications against license-to-operate requirements across target markets and model timing of mandated rollouts as scenario inputs to procurement and manufacturing planning.
Operational considerations and technology risks
-
Interoperability and telemetry: Closed, proprietary valve-control protocols increase total lifecycle cost and hinder integration with utility ADMS/MDMS platforms. RFPs should enforce open communication standards and documented APIs.
-
Cybersecurity: Remote-actuated valves introduce attack surfaces. Security-by-design (firmware signing, authenticated remote commands, intrusion detection) must be a procurement prerequisite.
-
Field reliability and maintainability: Valve actuators must meet specified duty cycles and environmental tolerances; maintenance models should be validated through pilot-to-scale service level agreements (SLAs).
-
Supply chain resilience: Critical component single-source risks (actuators, solenoids, control electronics) require dual-sourcing plans and contractual continuity clauses.
Decision framework for 2026 leaders
-
Step 1 — Rapid diagnostic: Map your installed meter population to regulatory exposure and risk-weighted incident history. This triage determines near-term retrofit priority.
-
Step 2 — Pilot and validation: Run 3–6 month pilots that stress-test integration with utility control systems, evaluate remote-shutoff response times, and validate fault-detection algorithms.
-
Step 3 — Procurement architecture: Shift from lowest-price bids to outcome-based contracts that tie vendor compensation to reliability KPIs and successful certifications.
-
Step 4 — Scale and service: Combine capital deployment with a managed services layer for firmware updates, incident analytics, and preventative maintenance.
-
Step 5 — Strategic M&A/partnerships: Use acquisitions to accelerate capability gaps (e.g., sensing, secure comms, field services) and partnerships to access local certification pathways.
How PW Consulting supports enterprise action
PW Consulting brings a rapid-deployment advisory package for senior executives that combines the full report’s data-driven market model with hands-on implementation support: regulatory mapping, supplier negotiations, pilot design, and a tailored ROI/TCO workbook. Our deep-dive vendor scorecards distill commercial, technical, and certification criteria into an executive-friendly dashboard to accelerate procurement and M&A decisions.
This release is a strategic “trailer” designed to demonstrate the depth of analysis and practical utility of PW Consulting’s full Safety Shut-off Valves for Gas Meters Market report. For licensing the full model, receiving the complete supplier scorecards, segmentation-level data, and the interactive scenario tools that power investment-grade decision-making, please visit our report page and request the full study.
For detailed analysis of this topic, please visit the official page: Safety Shut-off Valves for Gas Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com